
 Global Colorectal Cancer Diagnostics and Therapeutics Market | 2026-2036
Global Colorectal Cancer Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colorectal Cancer Diagnostics and Therapeutics Market Foresight
Project finance for precision diagnostic platforms is fragmenting competitive barriers in colorectal cancer care, allowing specialized firms to scale without capital-intensive manufacturing footprints. Exact Sciences leverages its commercial laboratory network to sustain direct-to-physician channel control. Guardant Health anchors its position through circulating tumor DNA specialization. Bristol-Myers Squibb differentiates via immuno-oncology combination protocols that require companion diagnostic alignment.
Colorectal cancer diagnostics and therapeutics encompass molecular screening assays, targeted biologics, endoscopic imaging systems, and surgical adjuncts designed to detect adenomatous polyps and malignant lesions while guiding therapeutic intervention. The field operates through fecal immunochemical testing sensitivity thresholds of 50 ng hemoglobin per milliliter and programmed death-ligand 1 expression cutoffs that determine checkpoint inhibitor eligibility. Diagnostic kits and biomarkers command concentrated margin pools as laboratories convert to automated high-throughput platforms. Therapeutic drugs face biosimilar pressure in mature markets while novel antibody-drug conjugates capture premium positioning. Imaging devices and surgical instruments represent replacement-cycle revenue with lower growth velocity.
FDA premarket approval pathways and EMA companion diagnostic guidance create dual-track compliance costs for multinational developers. WHO cancer screening frameworks and national reimbursement lists determine market access velocity across jurisdictions. Stakeholders must monitor regulatory convergence on liquid biopsy standards and prepare for diagnostic-therapeutic bundling in value-based contracts.
Market Dynamics
Liquid biopsy platforms are compressing diagnostic timelines from weeks to days while fragmenting laboratory economics. This shift forces incumbents to abandon capital-intensive tissue-based workflows without sacrificing clinical credibility.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for companion diagnostics accelerate product-to-revenue cycles. Developers leverage this mechanism to secure pre-market positioning ahead of therapeutic launches.
- Fecal Immunochemical Testing Sensitivity Thresholds:Detection limits at 50 ng hemoglobin per milliliter enable earlier polyp identification. Population screening programs in Germany and Japan incorporate these thresholds into reimbursement protocols.
- Programmed Death-Ligand 1 Expression Cutoffs:Standardized biomarker thresholds determine checkpoint inhibitor eligibility. Pathology laboratories automate PD-L1 scoring to capture companion diagnostic revenue streams.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction master mixes depend on concentrated enzyme suppliers. Single-source dependencies in the United States create vulnerability to batch variability.
- EMA Companion Diagnostic Guidance Complexity:Dual-track compliance with FDA and European requirements extends development timelines. Smaller developers lack regulatory affairs bandwidth to navigate parallel submissions.
- Endoscopic Imaging Replacement Cycles:Capital equipment refresh intervals of seven to ten years limit revenue velocity. Hospital procurement committees prioritize therapeutic devices over diagnostic upgrades.
Strategic Opportunities
- India Screening Program Expansion:National cancer grid initiatives create demand for affordable molecular assays. Local manufacturing partnerships circumvent import duty structures.
- Artificial Intelligence-Enabled Pathology:Machine learning algorithms converge with whole-slide imaging to automate adenoma detection. Academic medical centers in South Korea pilot regulatory sandbox approvals.
- Direct-to-Consumer Channel Development:At-home stool collection kits bypass physician gatekeeping. DTC platforms in the United States capture screening-hesitant demographics.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant interpretation pipelines require computational biologists with oncology domain expertise. Academic compensation benchmarks exceed commercial laboratory budgets.
- Liquid Biopsy Standardization Delays:Pre-analytical variables in circulating tumor DNA isolation remain unresolved. Cross-laboratory reproducibility studies lag behind clinical adoption curves.
- Legacy Laboratory Information System Integration:Automated platforms interface poorly with hospital electronic health records. Interface development consumes implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colorectal Cancer Diagnostics and Therapeutics Market |
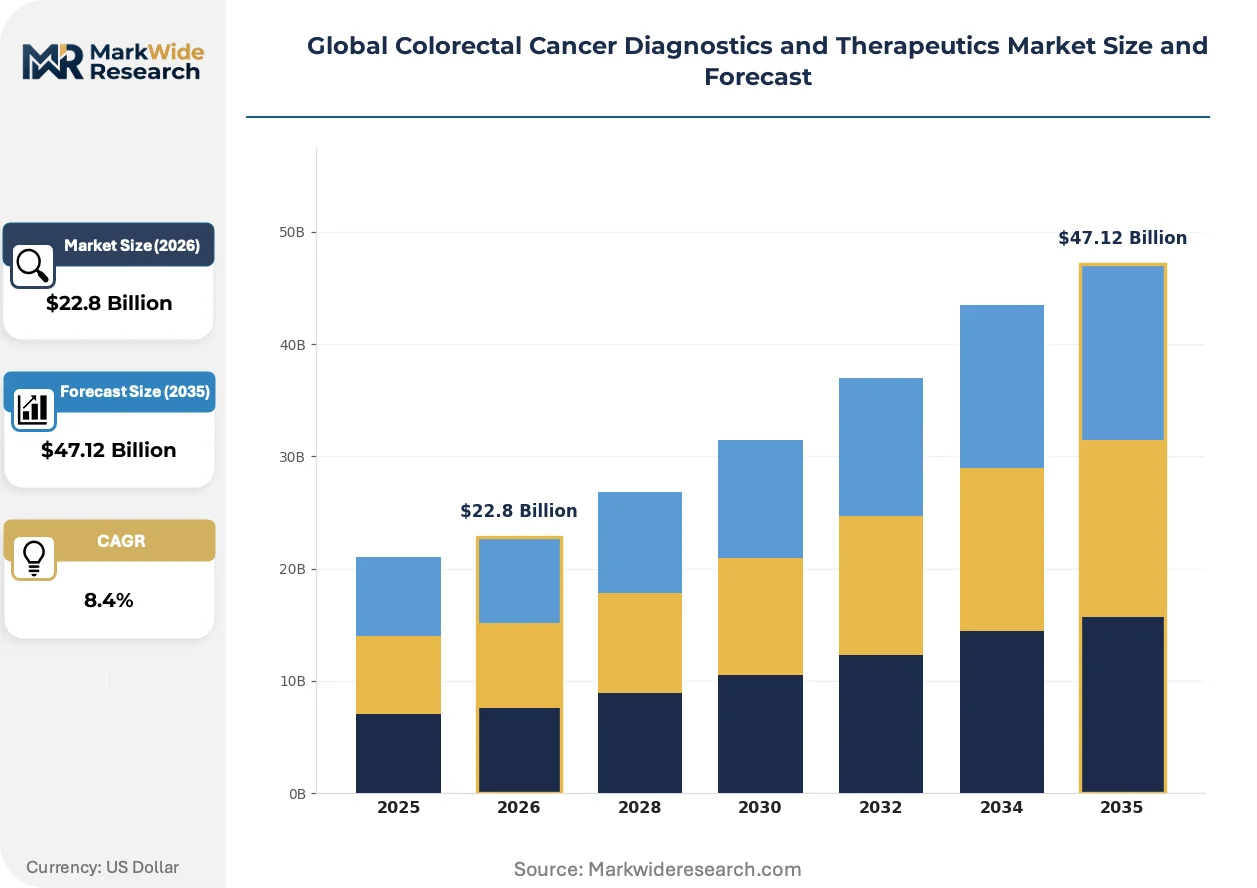
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Therapeutic Drugs, Imaging Devices, Surgical Instruments, Biomarkers Application: Early Detection, Treatment Monitoring, Post-operative Care, Risk Assessment, Disease Staging End User: Hospitals, Diagnostic Laboratories, Oncology Clinics, Research Institutions, Ambulatory Surgical Centers Delivery Mode: Invasive Procedures, Non-invasive Testing, Telemedicine Services, Laboratory Testing, Point-of-Care Devices |
| Companies Covered | Exact Sciences, Guardant Health, Bristol-Myers Squibb, Roche, Amgen, Abbott Laboratories, Epigenomics AG, Novigenix SA, Quest Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colorectal Cancer Diagnostics and Therapeutics Market Shifts & Advancements
Multi-cancer early detection assays are compressing the addressable market for single-organ tests while raising the competitive bar for analytical specificity. Developers must demonstrate negative predictive value superiority to displace established screening modalities.
Next-generation sequencing-based minimal residual disease monitoring is migrating from clinical trial endpoints to routine surveillance protocols. Oncology practices in the United States adopt longitudinal ctDNA tracking to detect recurrence before radiographic evidence. This migration from research-grade to standard-of-care applications compresses reimbursement negotiation timelines and forces platform consolidation.
The European Union's In Vitro Diagnostic Medical Devices Regulation imposes stricter clinical evidence requirements on companion diagnostics. Manufacturers must generate prospective performance data rather than relying on bridging studies. High-risk device classifications in Germany and France trigger notified body bottlenecks that delay market entry by eighteen to twenty-four months.
Hospital procurement committees now unbundle diagnostic service contracts from therapeutic purchasing agreements. Standalone laboratory service agreements replace bundled vendor relationships in the United States and Japan. This unbundling concentrates purchasing power within supply chain functions and compresses margin structures for integrated diagnostic-therapeutic developers.
Global Colorectal Cancer Diagnostics and Therapeutics Market Segmentation
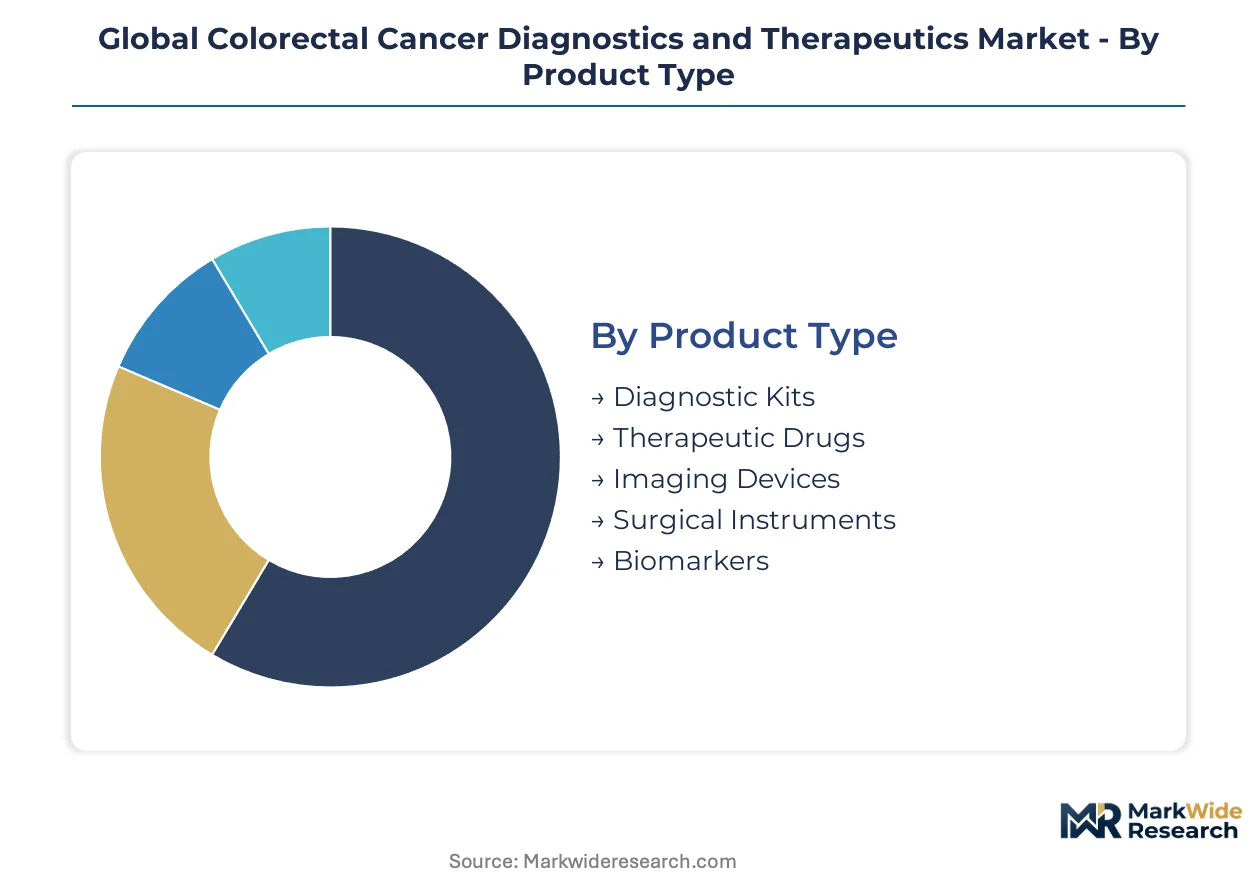
Colorectal cancer market segmentation reveals divergent capital intensity and margin profiles across the care continuum. Diagnostic kits and biomarkers compress revenue cycles to months while imaging devices and surgical instruments lock capital for seven to ten year replacement windows. Understanding these temporal dynamics shapes portfolio allocation and partnership strategies for market participants.
Product Type:
Cycle times range from rapid consumable replenishment to decade-long capital equipment refresh, creating distinct cash flow profiles and customer relationship models.
- Diagnostic Kits:Fecal immunochemical tests and liquid biopsy collection systems operate on 30- to 90-day reorder cycles. Demand concentrates in high-throughput clinical laboratories in Germany and Japan where automated platforms process thousands of samples daily. Reagent rental agreements and throughput-based pricing sustain recurring revenue streams.
- Therapeutic Drugs:Checkpoint inhibitors and antibody-drug conjugates require cold chain distribution and specialty pharmacy networks. Oncology clinics in the United States capture companion diagnostic alignment bonuses when prescribing FDA-approved combination protocols. Biosimilar pressure in European markets compresses margin duration for mature biologics.
- Imaging Devices:Endoscopic visualization systems with 4K and AI-enhanced polyp detection represent seven-figure capital commitments.
- Surgical Instruments:Robotic-assisted resection platforms and advanced energy devices follow hospital procurement committee approval timelines.
- Biomarkers:Circulating tumor DNA assays and tissue-based companion diagnostics command premium pricing through proprietary algorithm protection.
Diagnostic kits dominate installed base. Therapeutic drugs represent where expansion concentrates most steeply.
Application:
Clinical utility intensifies downstream from screening toward surveillance, with reimbursement density tracking intervention invasiveness.
- Early Detection:Population screening programs and high-risk surveillance protocols drive fecal test and colonoscopy volumes. Germany's national cancer screening framework reimburses biennial FIT for insured populations aged 50-54. Sensitivity thresholds at 50 ng hemoglobin per milliliter determine program eligibility and manufacturer competitive positioning.
- Treatment Monitoring:Serial ctDNA measurements track therapeutic response and detect resistance mutations before radiographic progression. Academic medical centers in the United States adopt minimal residual disease protocols as standard surveillance, compressing the research-to-reimbursement timeline.
- Post-operative Care:Recurrence surveillance combines imaging intervals with biomarker testing schedules.
- Risk Assessment:Polygenic risk scores and family history algorithms stratify screening intensity.
- Disease Staging:PET-CT and molecular profiling determine neoadjuvant therapy eligibility.
Early detection captures the highest absolute volumes. Treatment monitoring is climbing the fastest as longitudinal testing protocols mature.
End User:
Site-of-care economics fragment purchasing authority between centralized supply chain functions and distributed clinical decision-makers.
- Hospitals:Integrated delivery networks consolidate diagnostic and therapeutic procurement through value-based contracts. Procurement committees in the United States unbundle laboratory services from pharmaceutical purchasing, concentrating negotiating leverage within supply chain functions.
- Diagnostic Laboratories:Commercial reference labs and hospital-affiliated laboratories automate high-throughput platforms to capture companion diagnostic revenue. Exact Sciences leverages its commercial laboratory network to sustain direct-to-physician channel control without capital-intensive manufacturing footprints.
- Oncology Clinics:Community oncology practices adopt point-of-care molecular testing to reduce send-out delays.
- Research Institutions:Clinical trial endpoints and biomarker discovery programs drive early-stage assay development.
- Ambulatory Surgical Centers:Outpatient colonoscopy and polypectomy procedures concentrate in suburban and rural markets.
Hospitals anchor current spending. Diagnostic laboratories represent the steepest expansion trajectory as liquid biopsy platforms displace tissue-based workflows.
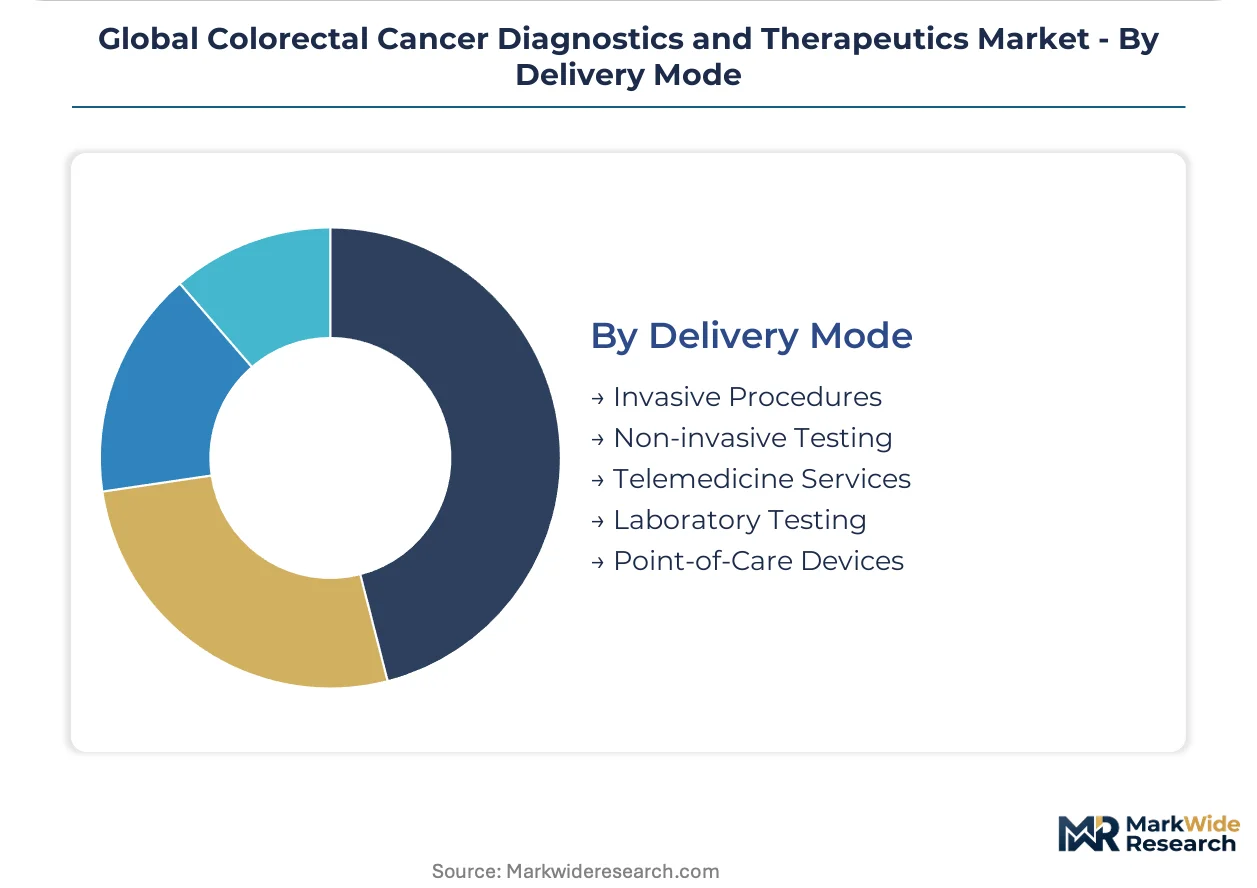
Delivery Mode:
Patient preference and pandemic-accelerated behavioral shifts redistribute volumes between physical sites and remote collection models.
- Invasive Procedures:Colonoscopy with polypectomy remains the gold standard for adenoma detection and removal. Japanese screening programs achieve participation rates above 60% through workplace-based scheduling and transportation subsidies.
- Non-invasive Testing:At-home stool collection kits bypass physician gatekeeping and capture screening-hesitant demographics. Direct-to-consumer platforms in the United States leverage telemedicine prescribing to circumvent traditional laboratory ordering workflows.
- Telemedicine Services:Virtual consultation and remote result delivery expand access in rural and underserved regions.
- Laboratory Testing:Centralized molecular profiling maintains analytical specificity advantages for complex biomarker panels.
- Point-of-Care Devices:Rapid FIT and portable endoscopy systems enable decentralized screening in resource-limited settings.
Invasive procedures retain the largest procedure volume. Non-invasive testing is gaining share fastest as consumer-directed healthcare models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for molecular reagents concentrates supply risk in three manufacturing clusters, while diagnostic service exports from Germany and Japan balance regional trade flows in precision oncology.
United States
FDA breakthrough device designations accelerate commercialization timelines for liquid biopsy developers. The national cancer screening framework under the Affordable Care Act mandates colorectal coverage without cost-sharing. Boston and San Diego anchor companion diagnostic development, with Exact Sciences operating commercial laboratory networks that bypass traditional hospital procurement channels.
Germany
Biennial fecal immunochemical testing for insured populations aged 50-54 drives standardized assay demand. The EMA companion diagnostic guidance and national reimbursement lists create dual-track compliance requirements. The Rhine-Ruhr and Munich metropolitan regions concentrate pathology automation, where laboratory networks convert to high-throughput platforms processing thousands of samples daily.
Japan
Workplace-based screening programs achieve participation rates above sixty percent through transportation subsidies and scheduled colonoscopy access. PMDA regulatory pathways align with FDA premarket approval standards for multinational device submissions. Tokyo and Osaka host academic medical centers piloting AI-enabled pathology sandbox approvals for adenoma detection algorithms.
India
National cancer grid initiatives generate demand for affordable molecular assays in tier-two cities. CDSCO regulatory harmonization with WHO screening frameworks accelerates import substitution programs. Maharashtra and Karnataka foster local manufacturing partnerships that circumvent duty structures on polymerase chain reaction reagents and collection systems.
South Korea
MFDS regulatory sandboxes enable accelerated approvals for machine learning-enabled whole-slide imaging systems. Government-funded precision medicine initiatives expand biomarker testing access through national health insurance. Seoul metropolitan hospitals lead minimal residual disease protocol adoption, compressing research-to-reimbursement timelines for circulating tumor DNA surveillance.
Global Colorectal Cancer Diagnostics and Therapeutics Market Competitive Landscape
On the supply side, the industry is bifurcated between capital-intensive therapeutic manufacturers and asset-light diagnostic service platforms. Laboratory networks and pharmaceutical developers occupy distinct competitive spheres with limited overlap. Three archetypes dominate: integrated diagnostic-therapeutic bundlers, specialized liquid biopsy laboratories, and precision oncology biologics developers. Capacity expansion in automated pathology platforms and strategic partnerships for companion diagnostic alignment represent the dominant competitive moves.
Among United States-based precision diagnostic specialists, Exact Sciences and Guardant Health exemplify the asset-light laboratory network model, while Bristol-Myers Squibb occupies a position within the immuno-oncology biologics tier. Exact Sciences leverages direct-to-physician channel control without manufacturing footprints. Guardant Health anchors the circulating tumor DNA specialization vector. Bristol-Myers Squibb represents the therapeutic developer archetype requiring companion diagnostic alignment for combination protocol eligibility.
| Leading Market Players |
|---|
| Exact Sciences |
| Guardant Health |
| Bristol-Myers Squibb |
| Roche |
| Amgen |
| Abbott Laboratories |
| Epigenomics AG |
| Novigenix SA |
| Quest Diagnostics |
| Others |
Supply & Pricing Matrix
Trans-Pacific air freight corridors connecting bioreagent manufacturing hubs in Germany and Japan to clinical laboratory networks in the United States impose cold-chain cost premiums that amplify margin stratification between premium liquid biopsy platforms and commoditized fecal immunochemical tests. These logistics economics concentrate pricing power among automated platform operators while forcing manual assay providers toward volume-based contract structures.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium companion diagnostics, standard high-throughput screening assays, and economy-grade rapid tests. Price differentiation hinges on FDA breakthrough device designation status and automated platform integration depth. Cost compression in the economy tier intensifies as Indian manufacturers scale polymerase chain reaction reagent production. Community oncology clinics exhibit highest price sensitivity, while integrated delivery networks leverage volume aggregation for standard-tier discounts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for nucleic acid extraction kits and sequencing consumables. Manufacturing concentrates in Germany, Japan, and the United States for precision optics and automated liquid handling systems. Raw material dependencies include fluorophore-labeled probes, thermostable polymerases, and silicon-based microfluidic chips. Single-source vulnerability persists for CRISPR guide RNA synthesis. Distribution runs through specialty laboratory distributors and direct-to-hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid biopsy platform adoption sits at early-cycle expansion, with longitudinal minimal residual disease monitoring protocols migrating from academic medical centers to community oncology practices. This penetration tailwind compresses reimbursement negotiation timelines and accelerates standard-of-care designation for circulating tumor DNA assays.
For Market Incumbents: Insulate companion diagnostic revenue streams through exclusive alignment with checkpoint inhibitor developers facing biosimilar pressure in European markets. Deepen backward integration into nucleic acid extraction chemistry to offset reagent supply concentration. Secure FDA breakthrough device designation for multi-cancer early detection panels before competitive entrants capture pre-market positioning.
For New Entrants and Emerging Players: India's tier-two cities present underpenetrated demand for affordable molecular assays as national cancer grid initiatives expand beyond metropolitan hospital networks. Target local manufacturing partnerships in Maharashtra and Karnataka to circumvent import duty structures on collection systems. Deploy telemedicine-integrated direct-to-consumer channels to bypass physician gatekeeping in screening-hesitant demographics.
For Investors and Strategic Acquirers: Asset-light laboratory networks with proprietary algorithm protection command premium multiples as hospital procurement committees unbundle diagnostic services from therapeutic purchasing. Long-term viability frames around automated pathology platform consolidation and AI-enabled whole-slide imaging regulatory sandbox approvals. Watch for FDA-EMA regulatory convergence on liquid biopsy analytical validity standards as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Alignment | Secures reimbursement pathway alongside Bristol-Myers Squibb checkpoint inhibitor protocols. |
| Automated Platform Integration | Enables Exact Sciences to sustain direct-to-physician channel control without manufacturing footprints. |
| Regulatory Sandbox Participation | MFDS approvals in South Korea accelerate machine learning-enabled pathology commercialization timelines. |
| Local Manufacturing Partnership | CDSCO harmonization allows Indian producers to substitute imported polymerase chain reaction reagents. |
| Direct-to-Consumer Channel Development | At-home stool collection kits capture screening-hesitant demographics outside traditional laboratory workflows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket approval filings, EMA companion diagnostic guidance documents, and national reimbursement list updates. Interviews with regulatory affairs leads at multinational diagnostic developers, pathology laboratory directors in Germany and Japan, and hospital procurement managers in integrated delivery networks informed demand-side assumptions. Secondary validation drew from ClinicalTrials.gov minimal residual disease protocol registrations, CMS Medicare coverage determination databases, and WHO cancer screening framework publications. Bottom-up assay volume modeling triangulated against top-down therapeutic prescription data.
Forecast inputs span product type segmentation across diagnostic kits, therapeutic drugs, imaging devices, and biomarkers; application dimensions from early detection through treatment monitoring; and end-user categories including hospitals, diagnostic laboratories, and oncology clinics. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory approval velocity and reimbursement density variations. Industry-specific inputs incorporated liquid biopsy platform conversion rates and automated pathology installation cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light laboratory networks or AI-enabled pathology entrants would shift outcomes. Macroeconomic contraction affecting hospital capital expenditure budgets, EMA MDR implementation delays extending notified body review timelines, or FDA breakthrough device designation pathway modifications would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market