
 Cancer API Market | 2026-2036
Cancer API Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer API Market Intelligence
The end-user landscape is pivoting from traditional pharmaceutical companies towards a greater reliance on specialized biotechnology firms and Contract Manufacturing Organizations for complex API development. Large pharmaceutical entities like Pfizer Inc. leverage extensive in-house R&D capabilities for blockbuster drugs. In contrast, generic manufacturers such as Teva Pharmaceutical Industries Ltd. and Dr. Reddy’s Laboratories specialize in cost-efficient production of off-patent APIs. Roche Holding AG differentiates through its strong portfolio in monoclonal antibodies.
Cancer Active Pharmaceutical Ingredients (APIs) are the biologically active components in oncological drugs responsible for their therapeutic effects. These substances, which include highly potent small molecules and complex biologics, are synthesized through multi-step chemical or biotechnological processes requiring stringent purity and containment protocols. While small molecule APIs remain a foundational product type, monoclonal antibodies and other recombinant proteins are driving significant value growth. Therapy area focus is expanding beyond breast and lung cancer to include targeted treatments for melanoma and colorectal cancer.
Market access and manufacturing standards are governed by stringent regulations from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These agencies enforce Good Manufacturing Practice (GMP) guidelines and require extensive data on API purity, stability, and impurity profiling for drug approval. Future competitiveness depends on a manufacturer's ability to navigate evolving regulatory expectations for continuous manufacturing and advanced process controls.
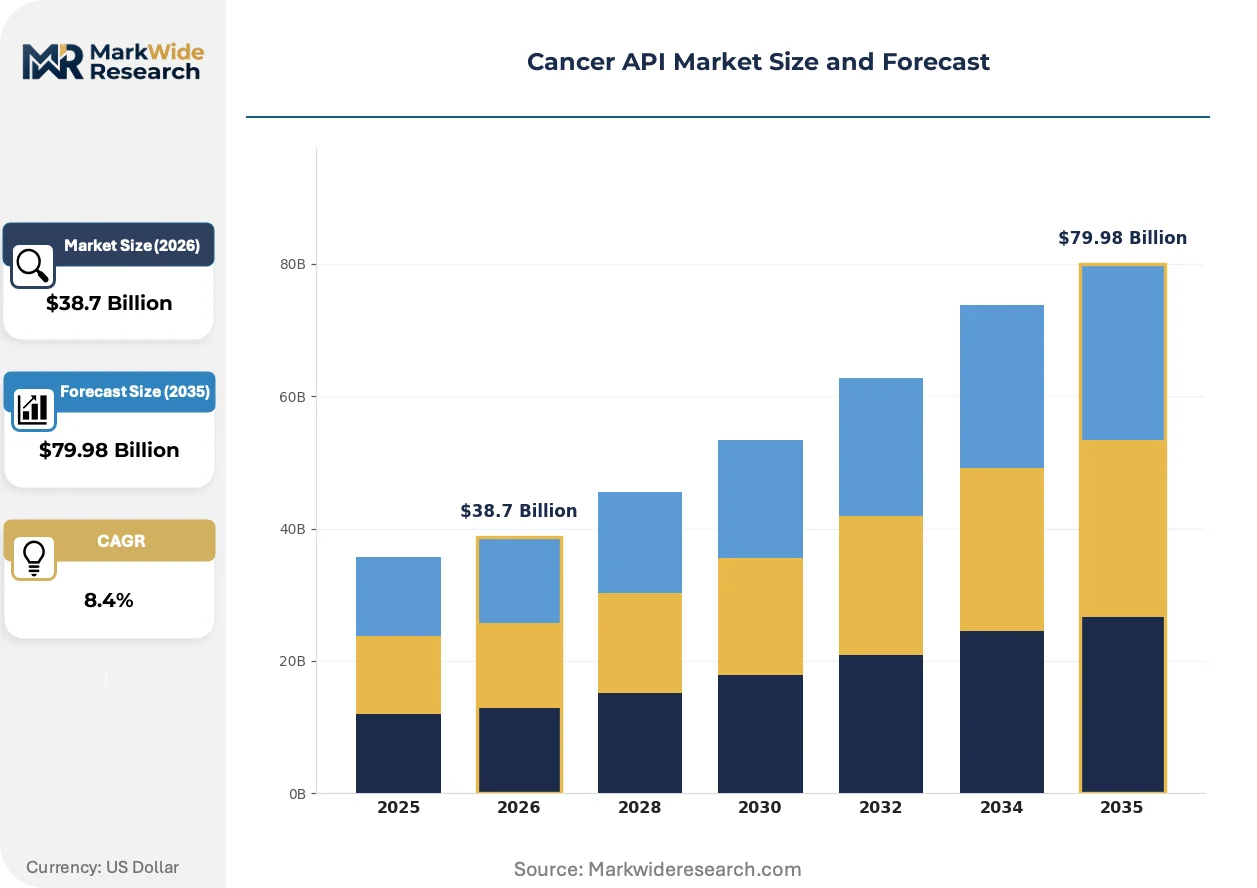
Market Dynamics
The increasing dominance of high-potency active pharmaceutical ingredients (HPAPIs) and complex biologics, like monoclonal antibodies, is the central force shaping the market. This shift necessitates advanced containment technologies and specialized manufacturing capabilities, concentrating production with expert contract organizations.
Growth Catalysts
- Bioconjugation Advancements:Progress in antibody-drug conjugate (ADC) technology creates demand for specialized API synthesis and conjugation services for targeted therapies.
- Chinese Regulatory Reforms:China's NMPA is accelerating drug approval timelines, stimulating domestic API production to support a growing pipeline of oncology drugs.
- Strategic Outsourcing by Pharma:Large pharmaceutical firms outsource complex HPAPI development to Contract Manufacturing Organizations to reduce capital expenditure and access specialized containment.
Market Restraints
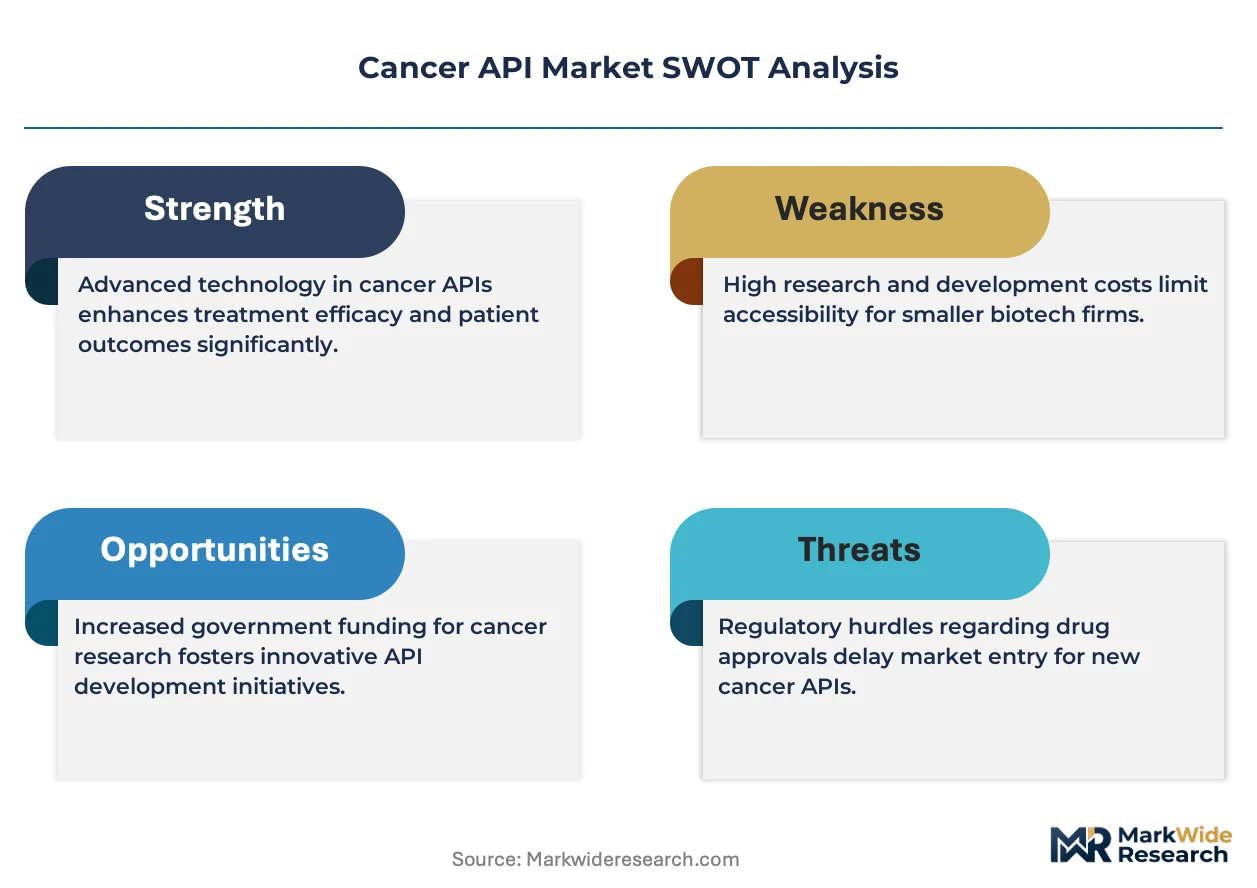
- High Capital Expenditure:Building facilities compliant with containment standards for high-potency APIs requires significant investment, creating a high barrier to entry.
- Stringent Regulatory Scrutiny:Complex impurity profiling and stability data requirements from the FDA and EMA add significant time and cost to API development.
- Synthesis Complexity:The multi-step processes for novel oncology APIs often result in low yields and high production costs, challenging commercial viability.
Strategic Opportunities
- Biosimilar API Production:Approaching patent expirations for blockbuster monoclonal antibodies creates a major opportunity for manufacturers specializing in cost-effective biosimilar API development.
- Continuous Manufacturing Adoption:Implementing continuous manufacturing offers a path to improve API purity and lower production costs, aligning with FDA and EMA quality initiatives.
- Indian Manufacturing Incentives:India's Production Linked Incentive (PLI) scheme creates favorable conditions for establishing API manufacturing hubs to serve global oncology markets.
Industry Challenges
- Talent Scarcity:A shortage of chemists and engineers with specialized experience in high-potency containment, bioconjugation, and advanced process control hinders capacity expansion and technology adoption.
- Intellectual Property Complexity:Navigating the dense patent landscape surrounding novel biologics, linker technologies for ADCs, and crystalline forms of small molecules creates significant legal risks for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer API Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peptide-Based, Small Molecule, Recombinant Proteins, Monoclonal Antibodies, Enzyme-Based Therapy Area: Lung Cancer, Breast Cancer, Colorectal Cancer, Prostate Cancer, Melanoma End User: Pharmaceutical Companies, Biotechnology Firms, Diagnostic Laboratories, Research Institutes, Contract Manufacturing Organizations Delivery Technology: Injectable, Oral, Intravenous, Transdermal, Subcutaneous |
| Companies Covered | Pfizer Inc., Novartis AG, Roche Holding AG, Merck & Co., Inc., Bristol-Myers Squibb, AstraZeneca PLC, Dr. Reddy’s Laboratories, Teva Pharmaceutical Industries Ltd., Cipla Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer API Market Strategic Shifts & Innovations
The convergence of advanced biotechnology and synthetic chemistry is defining the next generation of cancer APIs. This shift toward more complex and targeted molecules, such as antibody-drug conjugates, is demanding greater precision and control in manufacturing processes.
Continuous manufacturing systems represent a significant technological evolution in API production. Forward-thinking CMOs and large pharmaceutical companies are adopting these systems for high-volume oncology drugs. This technology is integrating process analytical technology (PAT) with real-time feedback controls, which enhances API quality consistency and reduces manufacturing cycle times.
International Council for Harmonisation (ICH) Q12 guidelines are streamlining post-approval lifecycle management for APIs. This regulatory framework provides manufacturers with greater flexibility to implement process improvements without requiring extensive regulatory resubmissions. Established API producers with large product portfolios are most affected, as they can now more efficiently optimize manufacturing for approved drugs.
A demand-side shift towards smaller batch sizes for targeted therapies and orphan drugs is altering production planning. This trend disrupts the traditional contract manufacturing model, which historically prioritized large-scale, campaign-based production for blockbuster drugs. This pattern is most visible in North America and Europe, where clinical development pipelines are rich with personalized medicine candidates.
Cancer API Market Segmentation
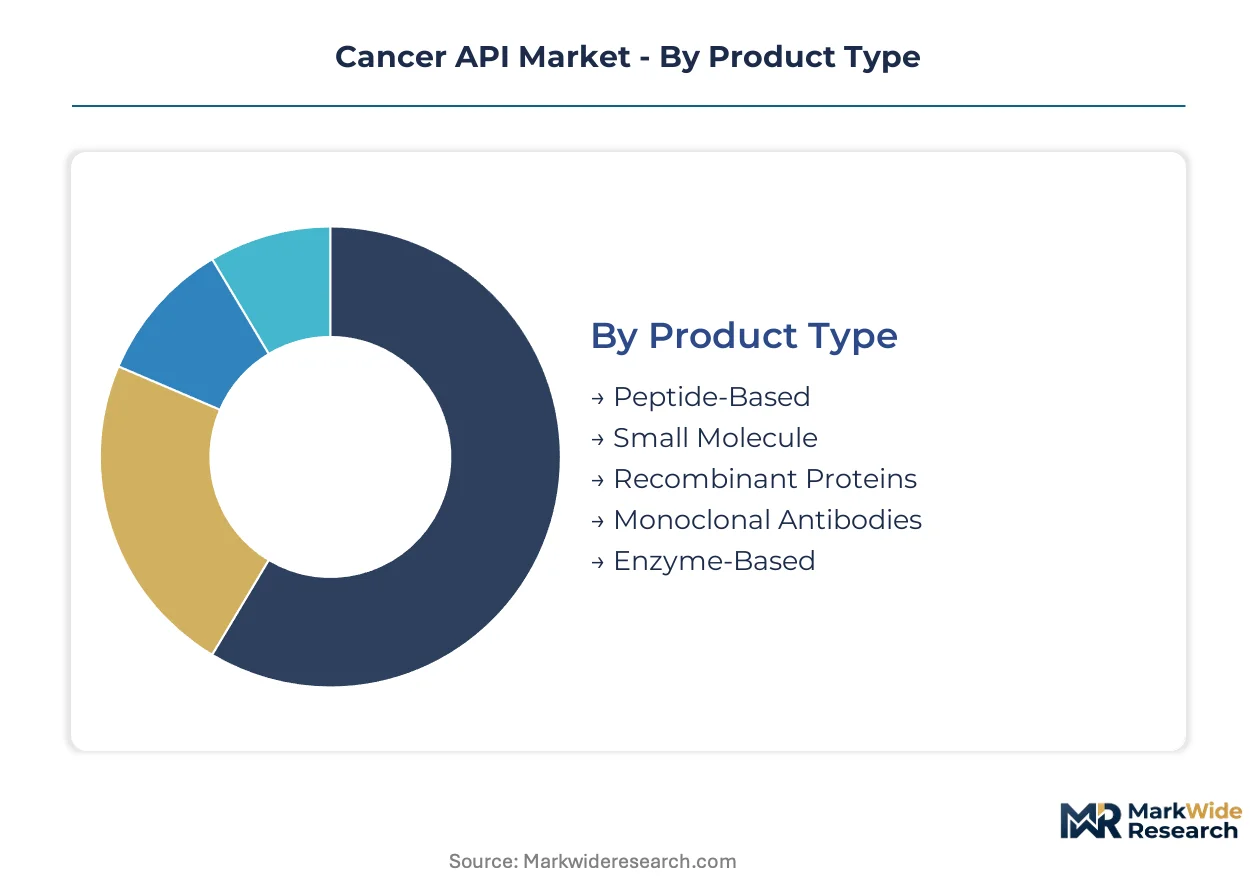
Segmentation analysis provides a granular view of the Cancer API Market, highlighting the diverse product forms, therapeutic applications, and end-user requirements. Understanding these distinct segments is crucial for manufacturers to align their production capabilities with specific market demands and regulatory pathways.
Product Type:
Product types for cancer APIs delineate between high-volume foundational compounds and premium, complex biologics. This distinction impacts manufacturing complexity and required capital investment.
- Small Molecule:Small molecule APIs are foundational, synthesized through multi-step chemical processes requiring stringent purity. Demand concentrates in generic drug manufacturing, driven by cost-efficient production for off-patent APIs.
- Monoclonal Antibodies:Monoclonal antibodies are complex biologics, representing significant value growth in targeted cancer therapies. Their production necessitates specialized biotechnological processes and advanced containment technologies.
- Peptide-Based:Peptide-based APIs offer high specificity, used in targeted therapies for various cancer types.
- Recombinant Proteins:Recombinant proteins, produced through genetic engineering, serve as active components in some oncology drugs.
- Enzyme-Based:Enzyme-based APIs are a niche segment, utilizing enzymatic activity for therapeutic effects in specific cancer treatments.
Mature deployment sits with Small Molecule APIs. Newer deployment is concentrated in Monoclonal Antibodies.
Therapy Area:
Therapy areas define the specific disease targets for cancer APIs, influencing research and development priorities across pharmaceutical pipelines.
- Breast Cancer:Breast cancer APIs target various subtypes, often involving hormonal or HER2-positive pathways. Demand for these APIs is substantial, reflecting the high prevalence of the disease globally.
- Melanoma:Melanoma APIs focus on targeted treatments for advanced skin cancer, including immune checkpoint inhibitors. Research institutes and biotechnology firms drive demand for novel API development in this area.
- Lung Cancer:Lung cancer APIs address a prevalent oncology segment, including small cell and non-small cell types.
- Colorectal Cancer:Colorectal cancer APIs target gastrointestinal malignancies, with a focus on personalized medicine approaches.
- Prostate Cancer:Prostate cancer APIs are essential for managing hormone-sensitive and castration-resistant forms of the disease.
Targeted treatments for Melanoma are gaining share fastest, while Breast Cancer remains a foundational segment.
End User:
The end-user landscape for cancer APIs reflects distinct operational models and sourcing strategies across the biopharmaceutical ecosystem.
- Pharmaceutical Companies:Pharmaceutical companies leverage extensive in-house R&D for blockbuster drugs, often outsourcing complex API development to specialized partners. This segment includes large established drug manufacturers.
- Contract Manufacturing Organizations:Contract Manufacturing Organizations (CMOs) provide specialized HPAPI development and bioconjugation services, reducing capital expenditure for pharma clients. Their expertise is critical for complex biologics.
- Biotechnology Firms:Biotechnology firms specialize in novel biologics and targeted therapies, relying on advanced API synthesis.
- Diagnostic Laboratories:Diagnostic laboratories utilize specific APIs for biomarker detection and disease monitoring in oncology.
- Research Institutes:Research institutes focus on early-stage API discovery and preclinical development for next-generation cancer treatments.
Specialized Contract Manufacturing Organizations exhibit significant supply concentration, while traditional Pharmaceutical Companies prioritize in-house capabilities for specific drugs.
Delivery Technology:
Delivery technologies dictate the mode of administration for oncological drugs, impacting patient adherence and API formulation requirements.
- Oral:Oral delivery offers patient convenience and non-invasive administration, suitable for small molecule APIs. This technology requires APIs with good bioavailability and stability in the gastrointestinal tract.
- Injectable:Injectable delivery, encompassing intravenous and subcutaneous routes, is common for biologics and high-potency small molecules. This method ensures direct systemic absorption and precise dosing for cancer treatments.
- Intravenous:Intravenous delivery provides rapid and complete systemic exposure, crucial for many chemotherapy agents.
- Transdermal:Transdermal delivery offers sustained release and avoids first-pass metabolism for select cancer APIs.
- Subcutaneous:Subcutaneous delivery allows for self-administration, improving patient convenience for certain biological therapies.
Oral delivery technologies offer ease of use for patients, contrasting with the precise administration required for injectable methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive (PLI) scheme actively drives domestic API manufacturing, creating favorable conditions for establishing oncology API hubs. This government initiative aims to reduce import reliance and strengthen pharmaceutical supply chains. Such strategic programs stimulate investment and capacity expansion across the country.
United States
United States demand arises from extensive R&D in novel oncology drugs and a robust biotechnology sector. The US FDA enforces rigorous impurity profiling and stability data requirements for drug approvals. The Boston-Cambridge biopharma cluster actively drives advanced API discovery and development, concentrating significant expertise and capital.
Germany
Germany's established pharmaceutical industry drives demand for complex biologics and high-potency APIs. The European Medicines Agency (EMA) sets stringent Good Manufacturing Practice (GMP) guidelines for API production. The Frankfurt-Rhine-Main region actively supports specialized API manufacturing and research, fostering innovation within its industrial ecosystem.
China
China's expanding domestic biopharmaceutical sector fuels demand for oncology APIs, supported by accelerated drug approval processes. The NMPA is actively streamlining regulatory pathways, stimulating significant domestic API production. The Yangtze River Delta region serves as a major hub for biopharmaceutical manufacturing and R&D, attracting substantial investment.
India
Indian manufacturers focus on cost-effective production for off-patent APIs and emerging biosimilar opportunities. India's Production Linked Incentive (PLI) scheme actively encourages domestic manufacturing and reduces import dependence. Hyderabad and Ahmedabad are key centers for API manufacturing and pharmaceutical exports, creating a strong supply base.
Japan
Japanese companies prioritize advanced therapeutic development and high-quality manufacturing standards for oncology APIs. The Pharmaceuticals and Medical Devices Agency (PMDA) strictly regulates API purity and stability for drug approvals. The Osaka region concentrates significant pharmaceutical R&D and specialized API production, fostering technological advancements.
Cancer API Market Key Industry Players
Top-tier vendors anchor the integrated pharmaceutical sector, while specialized Contract Manufacturing Organizations (CMOs) and biotechnology firms form a distinct lower tier. The market structure exhibits a blend of consolidation among established players and fragmentation within niche service providers. Strategic archetypes include large-scale innovators, cost-efficient generic producers, and specialized high-potency API manufacturers. Companies pursue capacity expansion and strategic partnerships to strengthen their market position and access advanced technologies.
On the premium-tier vector, companies like Pfizer Inc. exemplify extensive in-house R&D capabilities for blockbuster drugs. Roche Holding AG represents a strong portfolio in complex biologics, especially monoclonal antibodies, requiring specialized manufacturing expertise. Dr. Reddy’s Laboratories, a generic manufacturer, demonstrates expertise in cost-efficient production of off-patent APIs. These entities collectively underscore the diverse operational models within the cancer API market, ranging from high-value innovation to volume-driven production.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Roche Holding AG |
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| AstraZeneca PLC |
| Dr. Reddy’s Laboratories |
| Teva Pharmaceutical Industries Ltd. |
| Cipla Ltd. |
| Others |
Cost & Logistics Intelligence
Advancements in bioconjugation and high-potency API synthesis are reshaping cost economics and concentrating specialized manufacturing capabilities. These technical shifts demand significant capital investment, influencing pricing power across the value chain.
Pricing Analysis
Short lead times for novel oncology APIs command a premium, while established off-patent compounds face discounting for spot inventory. The dominant pricing model for complex biologics is project-based, transitioning to contract-based long-term offtake for commercial volumes. Price differentiation stems from specialized manufacturing containment requirements and stringent purity certification levels from bodies like the FDA. Pricing softness reflects competition from cost-efficient producers in India for generic APIs, making generic manufacturers highly price-sensitive compared to biotechnology firms developing targeted therapies.
Supply Chain Analysis
Logistics and freight costs for temperature-sensitive biologics significantly impact the final delivered price of cancer APIs. Geographic supply concentrates in China and India for small molecules, while specialized biologics often originate from the United States and Germany. The supply chain draws from specialized reagents and cell culture media, creating dependencies on a few key suppliers. Single-source vulnerability for highly potent intermediates represents a structural risk. Distribution runs through direct channels to pharmaceutical companies and specialized Contract Manufacturing Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cancer API Market is becoming a vertical-integration race, as leading players pursue upstream control over specialized HPAPI synthesis and bioconjugation capabilities. This strategic imperative aims to secure critical supply and enhance quality control for complex oncology drugs.
For Market Incumbents: Extend capabilities in continuous manufacturing to reduce production costs and improve API purity for high-volume oncology drugs. Consolidate market position by acquiring specialized Contract Manufacturing Organizations with advanced containment technologies, mitigating talent scarcity and high capital expenditure threats. Invest in R&D for advanced process controls to navigate evolving regulatory expectations from the FDA and EMA. Capacity addition in established regions like the United States and Germany can reinforce supply chain resilience.
For New Entrants and Emerging Players: Underserved biotechnology firms developing orphan drugs represent a penetrable segment for specialized HPAPI and bioconjugation services. Focus on biosimilar API production for monoclonal antibodies approaching patent expiration, leveraging cost-effective manufacturing in India. Offer highly specialized services for niche peptide-based APIs, where larger players may not prioritize smaller batch sizes. A go-to-market strategy emphasizing rapid development timelines and flexible capacity can attract innovative clients.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized Contract Manufacturing Organizations given the increasing outsourcing trends from large pharmaceutical companies. The oncology API market offers long-term viability over the next 5-10 years due to the persistent global cancer burden and continuous innovation in treatments. Target acquisition archetypes include firms with established HPAPI containment capabilities or novel bioconjugation technologies. Successful regulatory approvals for new antibody-drug conjugates or widespread adoption of continuous manufacturing by key players are critical inflection indicators to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand for high-potency compounds and reduces supply chain risks. |
| Strategic Partnerships | Accesses novel drug pipelines and specialized bioconjugation expertise for targeted therapies. |
| Technology Licensing | Improves API purity, lowers production costs, and aligns with evolving regulatory standards. |
| Regulatory Approval Pathway | Accelerates market entry and commercialization for oncology APIs in key growth regions. |
| Pipeline Diversification | Captures emerging opportunities in targeted therapies for melanoma and colorectal cancer. |
Research Approach
Multi-period observation of oncology drug pipelines and manufacturing capacity anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with drug development executives, regulatory affairs leads, CMO operations managers, and pharmaceutical procurement specialists. This was validated against secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov, and NMPA announcements. A rigorous bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
Segment-weighting across product type, therapy area, end-user, delivery technology, and regional regulatory frameworks structured the forecast model. The analytical framework projected market evolution across the analysis window, deriving compound annual growth rates from historical growth patterns, oncology drug pipeline analysis, and expert consensus. Key forecast inputs included global R&D spending on cancer therapies and upcoming patent expiration schedules for blockbuster drugs. This ensured a comprehensive view of future market dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory changes or rapid technological breakthroughs. These forecasts reflect a set of assumptions regarding market evolution and geopolitical stability impacting supply chains. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Immuno-Oncology Clinical Trials Market
Oncology
Global Interventional Oncology Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Hadron Therapy Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Liposarcoma Treatment Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Europe Tumor Ablation Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Particle Therapy Systems Market
Oncology
Radiotherapy Market
Oncology
Global Veterinary Oncology Market
Oncology
Interventional Oncology Ablation Market
Oncology
Pancreatic Cancer Market