
 Colostomy Bags Market | 2026-2036
Colostomy Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Colostomy Bags Market Intelligence
The end-use mix for colostomy bags is shifting from hospital-based management towards a model dominated by home care settings. Coloplast leverages its extensive direct-to-consumer channels and patient support programs to capture this transition. ConvaTec competes on the basis of its advanced skin barrier technologies and a broad portfolio catering to diverse patient needs. Hollister sustains a strong position through its educational resources and established relationships with ostomy nurses.
Colostomy bags are medical devices designed to securely collect fecal matter from a surgically created stoma. They typically consist of a multi-layer, odor-proof pouch and a skin barrier, or flange, made from hydrocolloid adhesives. Product selection between one-piece systems for simplicity and two-piece systems for flexibility is a key patient and clinician decision point. Demand arising from colorectal cancer treatment remains the primary application, followed by management of inflammatory bowel disease.
Market access is governed by stringent medical device regulations, such as those from the US FDA, which classify these products as Class I devices. In parallel, compliance with Europe's Medical Device Regulation (MDR) and Japan's PMDA requirements is essential for commercialization. Manufacturers must continually balance reimbursement pressures from healthcare systems with patient demands for greater discretion, comfort, and skin-friendliness in new product designs.
Market Dynamics
The central dynamic shaping the market is the definitive shift of ostomy management from clinical environments to patient homes. This transition elevates patient-centric demands for discretion, comfort, and ease of use, compelling manufacturers to innovate beyond basic functional requirements.
Growth Catalysts
- Demographic Pressures:Aging populations in countries like Germany and Japan are leading to a higher incidence of colorectal cancer and other related conditions, directly expanding the primary patient base for colostomy products.
- Material Science Advances:Innovations in hydrocolloid adhesives and flexible, odor-proof pouch films are enhancing user comfort, reducing skin irritation, and improving discretion, which encourages consistent use and better quality of life.
- Home Healthcare Expansion:A systemic move towards post-operative care in home settings, supported by reimbursement policies, empowers patients and caregivers, driving demand for products designed for self-management and simplicity.
Market Restraints
- Reimbursement Constraints:Pressure from national healthcare systems and private insurers to contain costs often limits patient access to premium, technologically advanced ostomy products, favoring standard, lower-cost options.
- Regulatory Fragmentation:Navigating disparate and stringent regulatory frameworks, such as the US FDA's requirements versus Europe's Medical Device Regulation (MDR), creates significant compliance costs and can delay new product introductions.
- Social Stigma:Persistent social stigma and lack of public awareness surrounding stomas can create psychological barriers for patients, affecting their willingness to engage with support services and adopt newer, more visible technologies.
Strategic Opportunities
- Emerging Market Penetration:Expanding into developing regions with improving healthcare infrastructure, such as parts of Southeast Asia and Latin America, presents a significant opportunity to reach a large, underserved patient population.
- Smart Pouch Technology:The integration of sensors into ostomy bags to monitor output, detect leaks, or signal pouch capacity can create a new premium segment linked to digital health platforms and telehealth services. *Subscription-Based Models: Developing direct-to-consumer e-commerce channels with automated subscription services can enhance patient convenience, improve supply chain predictability, and build direct brand loyalty.
Industry Challenges
- Continuous Regulatory Compliance:Manufacturers face a substantial operational challenge in maintaining and updating technical files and clinical evidence to remain compliant with evolving standards like the EU's MDR.
- Supply Chain Vulnerability:The reliance on a concentrated group of suppliers for specialized raw materials, including specific hydrocolloids and multi-layer films, exposes the supply chain to potential disruptions and price volatility.
- Patient Education at Scale:Ensuring adequate education for a growing and dispersed patient population in home care settings is a major logistical challenge, critical for preventing skin complications and ensuring correct product application.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colostomy Bags Market |
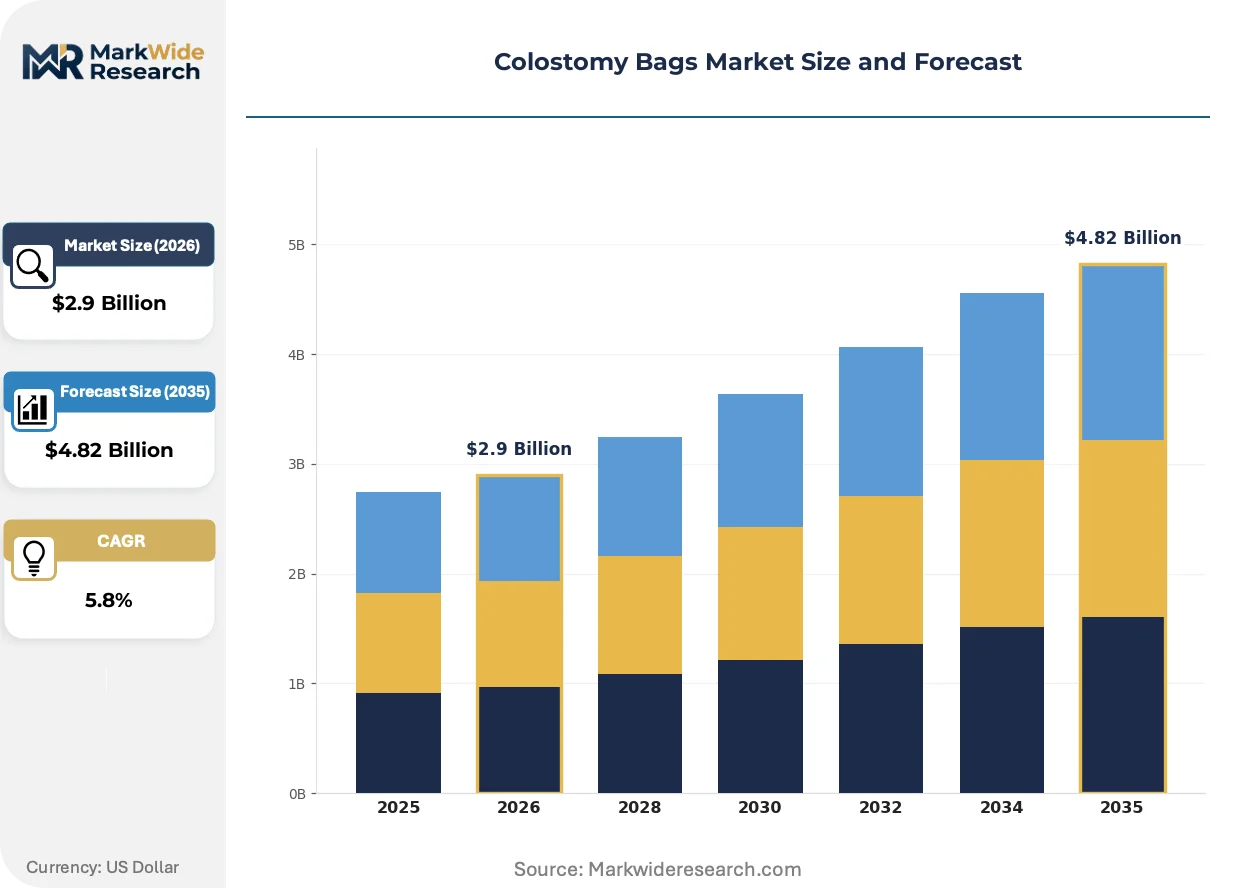
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.82 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Closed-End, Drainable, Two-Piece, One-Piece Application: Colorectal Cancer, Diverticulitis, Inflammatory Bowel Disease, Trauma, Congenital Defects, Fistulas End User: Hospitals, Home Care, Ambulatory Surgical Centers, Rehabilitation Facilities, Specialized Clinics Closure Type: Tape, Velcro, Adhesive, Elastic, Heat Seal, Snap |
| Companies Covered | Coloplast, ConvaTec, Hollister, B. Braun, Marlen Manufacturing, Alcare, Welland Medical, Salts Healthcare, Flexicare Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colostomy Bags Market Strategic Shifts & Innovations
Product evolution is increasingly driven by a focus on the peristomal skin environment and patient lifestyle integration. This focus is steering innovation in material science and product form factors, while digital tools begin to augment traditional ostomy care pathways.
Advanced hydrocolloid formulations infused with skin-soothing agents like ceramide are gaining traction. These materials are designed to actively maintain the health of the skin surrounding the stoma, not just adhere to it. Patients managing their ostomies in home care environments are the primary adopters. This development is unifying the previously distinct objectives of secure adhesion and therapeutic skin care into a single, high-value product feature.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This regulation forces manufacturers to conduct more rigorous testing and data collection to prove the safety and performance of colostomy bags. The impact is most acute for companies selling across the European Union, which must now allocate substantial resources to update documentation for their entire portfolio to maintain market access.
A notable behavioral shift is occurring as patients move from passive recipients to active consumers, often bypassing traditional pharmacy channels. Direct-to-consumer (DTC) models, complete with online consultations and subscription deliveries, are disrupting the established distribution network. This trend is most visible in the United States and parts of Europe, where patient empowerment and digital commerce are well-established.
Colostomy Bags Market Segmentation
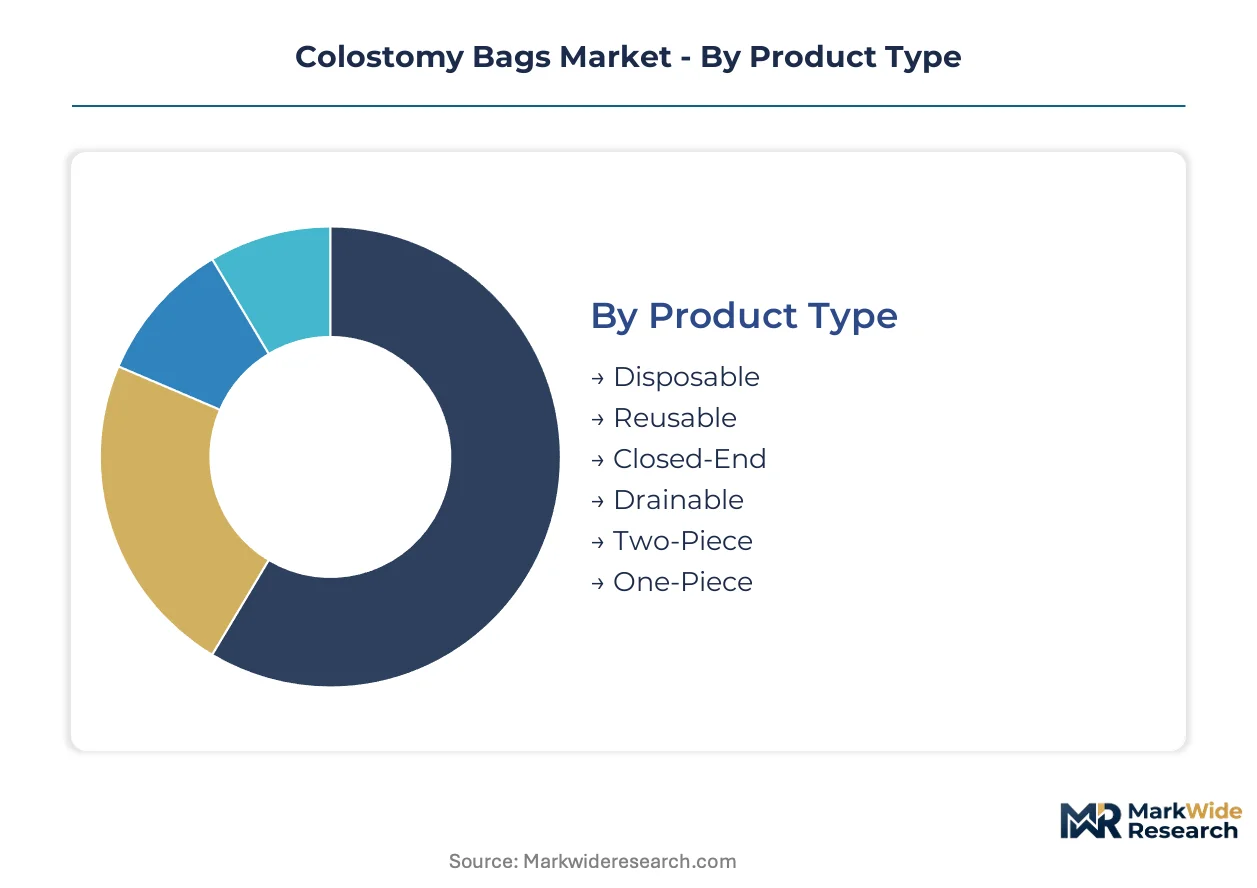
The colostomy bags market exhibits diverse segmentation, reflecting varied patient needs and clinical requirements across different care settings. Understanding these distinct product types, applications, end-user preferences, and closure mechanisms is crucial for manufacturers to tailor innovations and for healthcare providers to optimize patient outcomes.
Product Type:
Product type segmentation highlights the integration depth of ostomy systems, distinguishing between standalone, single-use options and more adaptable, multi-component solutions.
- Two-Piece:These systems feature a separate skin barrier and pouch, allowing the pouch to be changed independently without removing the barrier. This design offers enhanced flexibility and reduces skin irritation, making them popular for long-term management in home care settings.
- One-Piece:These integrated systems combine the skin barrier and pouch into a single unit, providing simplicity and a low profile. Their ease of application makes them suitable for patients seeking discretion and straightforward management, particularly for new ostomates.
- Disposable:Designed for single use, these pouches are discarded after use, offering convenience and hygiene for patients in various care environments.
- Reusable:Less common, these systems are designed to be emptied, cleaned, and reused, often favored for specific clinical or economic considerations.
- Closed-End:These pouches are sealed at the bottom and are typically used for solid stool, requiring removal and disposal when full.
- Drainable:Equipped with an opening at the bottom, these pouches allow for emptying without removal, suitable for liquid or semi-liquid output and offering extended wear time.
Drainable leads volumes today; Two-Piece is gaining share fastest.
Application:
The application segmentation categorizes colostomy bag usage based on the underlying medical condition necessitating ostomy surgery, reflecting varied patient demographics and disease prevalence.
- Colorectal Cancer:This segment represents the primary application for colostomy bags, driven by the high incidence of the disease globally and surgical interventions requiring fecal diversion. Demand concentrates in countries with aging populations like Japan and Germany, where cancer rates are elevated.
- Inflammatory Bowel Disease:Including conditions like Crohn's disease and ulcerative colitis, IBD often necessitates ostomy surgery for disease management or complication resolution. Patients with IBD frequently require long-term ostomy solutions, driving consistent product demand.
- Diverticulitis:Severe cases of diverticulitis with complications such as perforation or abscess may require temporary or permanent colostomy. These applications often involve acute care settings initially.
- Trauma:Abdominal injuries from accidents or violence can necessitate emergency colostomy to manage intestinal damage. Such cases require immediate access to suitable devices.
- Congenital Defects:Birth defects affecting the bowel, such as imperforate anus, often require colostomy in pediatric patients. Specialized smaller-sized products are needed for this population.
- Fistulas:Complex fistulas that do not respond to other treatments may require diversion colostomies to facilitate healing. This application often involves meticulous skin care.
Colorectal Cancer currently dominates usage; Inflammatory Bowel Disease shows significant expansion.
End User:
End-user segmentation reflects the primary care setting where colostomy bags are utilized, indicating distinct procurement patterns and support needs.
- Home Care:This segment represents a rapidly expanding market, as patients increasingly manage ostomy care independently post-discharge. Home care patients prioritize discretion, comfort, and ease of use, supported by direct-to-consumer channels.
- Hospitals:Hospitals serve as the initial point of care for ostomy patients, providing post-operative management and product education. Procurement in hospitals emphasizes clinical efficacy and cost-effectiveness for acute care.
- Ambulatory Surgical Centers:These facilities handle less complex surgical procedures, and some ostomy creations or revisions occur here. Product selection focuses on efficiency and quick patient turnover.
- Rehabilitation Facilities:Patients recovering from extensive surgeries or those requiring long-term rehabilitation often receive ostomy care in these settings. Staff require training on diverse product types.
- Specialized Clinics:Ostomy clinics provide expert consultation, product fitting, and ongoing support for patients. These clinics influence product preferences and education.
Home Care is experiencing the most significant shift; Hospitals maintain a foundational role.
Closure Type:
Closure type segmentation distinguishes colostomy bags based on the mechanism used to seal the pouch, influencing security, ease of use, and patient comfort.
- Adhesive:Adhesive closures provide a secure and often discreet seal, integrated directly into the pouch design. These are commonly found in disposable systems for reliable containment.
- Velcro:Velcro closures offer convenience and ease of manipulation, allowing for quick opening and closing of drainable pouches. This mechanism is favored for its simplicity, particularly by patients with dexterity challenges.
- Tape:Tape closures provide a basic sealing method, often used in conjunction with other mechanisms or for securing certain types of pouches. They are generally cost-effective.
- Elastic:Elastic closures may be incorporated into pouch design for a snug fit or to provide additional security around the stoma. This type offers flexibility.
- Heat Seal:Heat-sealed closures are typically permanent, ensuring an odor-proof and leak-proof seal for closed-end pouches. This method is critical for product integrity.
- Snap:Snap closures offer a tactile and secure fastening method, often used in two-piece systems to connect the pouch to the skin barrier. They provide audible confirmation of closure.
Adhesive is foundational for security; Velcro offers expanding convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The colostomy bags market experiences regional disparities due to varying regulatory stringency, influencing production and market access strategies. Manufacturers often balance the high compliance costs of established markets with the growth potential of regions having less developed regulatory frameworks. This dynamic shapes investment patterns and product availability across diverse healthcare systems.
Germany
Germany's demand for colostomy bags stems from its aging population and high incidence of colorectal cancer. The country adheres to the strict requirements of Europe's Medical Device Regulation (MDR), ensuring product safety and performance. Berlin and Munich host significant medical device clusters, driving innovation in advanced hydrocolloid formulations and discreet designs.
Japan
Japan exhibits substantial demand for colostomy products, primarily due to its rapidly aging demographic and associated rise in chronic diseases. The PMDA regulates medical devices, mandating rigorous clinical evidence for market entry. Osaka and Tokyo's medical technology hubs focus on developing smaller, more comfortable devices tailored to patient lifestyle needs.
United States
The United States represents a large market for colostomy bags, driven by a significant patient population and advanced healthcare infrastructure. US FDA classification as Class I devices requires specific pre-market notification and quality system compliance. The "MedTech Corridor" in Minneapolis and medical device innovators in California lead in smart pouch technology and direct-to-consumer models.
United Kingdom
The United Kingdom's market for colostomy bags is propelled by an increasing number of ostomy surgeries and a strong home care support system. Compliance with UKCA marking, post-Brexit, and Europe's MDR standards remains critical for market access. Manchester and London's healthcare technology ecosystems foster patient education initiatives and subscription-based product delivery.
India
India presents an opportunity for colostomy bag market expansion, fueled by improving healthcare access and a large, underserved patient base. The Central Drugs Standard Control Organization (CDSCO) governs medical device approvals, with a focus on affordability and local manufacturing. Bengaluru and Mumbai are emerging as medical device manufacturing centers, addressing the need for cost-effective ostomy solutions.
Colostomy Bags Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The colostomy bags market exhibits consolidation among a few global players while a fragmented ecosystem of regional and niche providers also exists. Archetypes include established medical device giants, specialized ostomy care providers, and emerging technology innovators. Dominant competitive moves involve strategic partnerships for market access and continuous portfolio diversification to meet varied patient needs.
On the premium-tier vector, Coloplast and ConvaTec exemplify companies with extensive global reach and a focus on advanced skin barrier technologies and patient support programs. Hollister, another significant player, occupies a position emphasizing educational resources and established relationships with ostomy nurses. These companies anchor the market by setting benchmarks for product innovation in areas like hydrocolloid formulations and user comfort, while also navigating complex regulatory landscapes.
| Leading Market Players |
|---|
| Coloplast |
| ConvaTec |
| Hollister |
| B. Braun |
| Marlen Manufacturing |
| Alcare |
| Welland Medical |
| Salts Healthcare |
| Flexicare Medical |
| Others |
Cost & Logistics Intelligence
Specialized polymer input costs for hydrocolloid adhesives cascade through the colostomy bags market, directly influencing product pricing across premium and standard tiers. This cost structure shapes manufacturers' profit margins and consumer accessibility.
Pricing Analysis
Distributor margins significantly influence the final pricing of colostomy bags to healthcare providers and direct consumers. Premium-mid-economy pricing differentiation exists, driven by advanced hydrocolloid formulations and comprehensive patient support programs. Pricing softness stems from reimbursement constraints by national healthcare systems, particularly for standard products. Hospital procurement committees exhibit high price sensitivity, while home care patients often prioritize comfort and discretion.
Supply Chain Analysis
US FDA Class I device classification and Europe's MDR impose stringent qualification gating for colostomy bag components and finished products. The supply chain draws from specialized material producers in Germany, Japan, and the United States. Raw material dependencies include advanced hydrocolloid polymers and multi-layer odor-proof films. Single-source vulnerability for specialized hydrocolloids presents a structural risk within this market, impacting availability. Multi-channel distribution runs through hospitals and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colostomy bags market presents a geographic-arbitrage opportunity, with lower manufacturing costs in India contrasting sharply with the stringent regulatory compliance demands of Europe’s Medical Device Regulation.
For Market Incumbents: Extend existing patient support programs to integrate telehealth services, enhancing engagement and brand loyalty in home care settings. Invest in advanced hydrocolloid research to develop next-generation skin barriers that actively promote peristomal skin health, countering reimbursement pressures from national healthcare systems. Leverage channel control through direct-to-consumer models to bypass traditional procurement inefficiencies.
For New Entrants and Emerging Players: Capture white-space opportunities in emerging markets with improving healthcare infrastructure, such as parts of Southeast Asia, focusing on affordable and user-friendly products. Target the nascent smart pouch technology segment by integrating sensors for output monitoring, offering a premium value proposition. Implement subscription-based direct-to-consumer e-commerce models to build brand loyalty and streamline delivery.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized ostomy care providers integrating digital health solutions, offering long-term viability driven by aging populations and chronic disease prevalence. Prioritize acquisition targets with strong intellectual property in smart pouch technology or advanced skin barrier formulations. Watch for increasing adoption rates of smart pouch technology as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (Smart Pouch) | Introduces data-driven patient management, enhancing user quality of life and clinical oversight. |
| Distribution Channel Expansion (DTC) | Bypasses traditional pharmacy channels, building direct brand loyalty and improving patient access. |
| Regulatory Approval Pathway (MDR Compliance) | Ensures continued market access across the stringent European Union, upholding product standards. |
| Material Science Innovation (Ceramide Hydrocolloids) | Improves peristomal skin health and user comfort, actively reducing common skin complications. |
| Strategic Partnership (Telehealth Provider) | Integrates remote patient monitoring, enhancing support for a dispersed home care patient base. |
Research Approach
Bottom-up home care modeling reconciled against top-down manufacturer tracking forms the analytical core of this study. Primary interviews with ostomy nurses, colorectal surgeons, hospital procurement managers, and patient advocacy groups provided qualitative insights. Secondary validation drew from US FDA filings, Europe MDR guidance documents, national health statistics, and company annual reports.
An input-output matrix framework was utilized to project market dynamics across the analysis window. Segmentation dimensions modeled include product type, application, end-user, closure type, and regional regulatory frameworks. Compound annual growth rates were extrapolated using historical trends and projected market dynamics. Incidence rates of colorectal cancer and aging population demographics served as key forecast inputs.
Underlying measurement precision varies by segment; hospital procurement and colorectal cancer applications carry tighter precision than others. Forecasts reflect assumptions regarding unforeseen regulatory changes, rapid material science breakthroughs, or shifts in healthcare reimbursement policies. A model refresh is warranted upon material change in healthcare policy shifts or major technological advancements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Disposable Medical Gowns Market