
 Endoscope Protective Barrier Covers Market | 2026-2036
Endoscope Protective Barrier Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Protective Barrier Covers Market Foresight
FDA's updated reprocessing guidance is restructuring the cost-of-entry calculus for barrier cover manufacturers by elevating validation requirements for sterile claims. Olympus Corporation leverages its installed base of endoscopy systems to bundle protective accessories through hospital supply contracts. STERIS plc anchors its position through terminal sterilization compatibility testing that extends cover shelf life claims. Medline Industries, Inc. competes on distribution density, sustaining same-day fulfillment to outpatient clinics across North America.
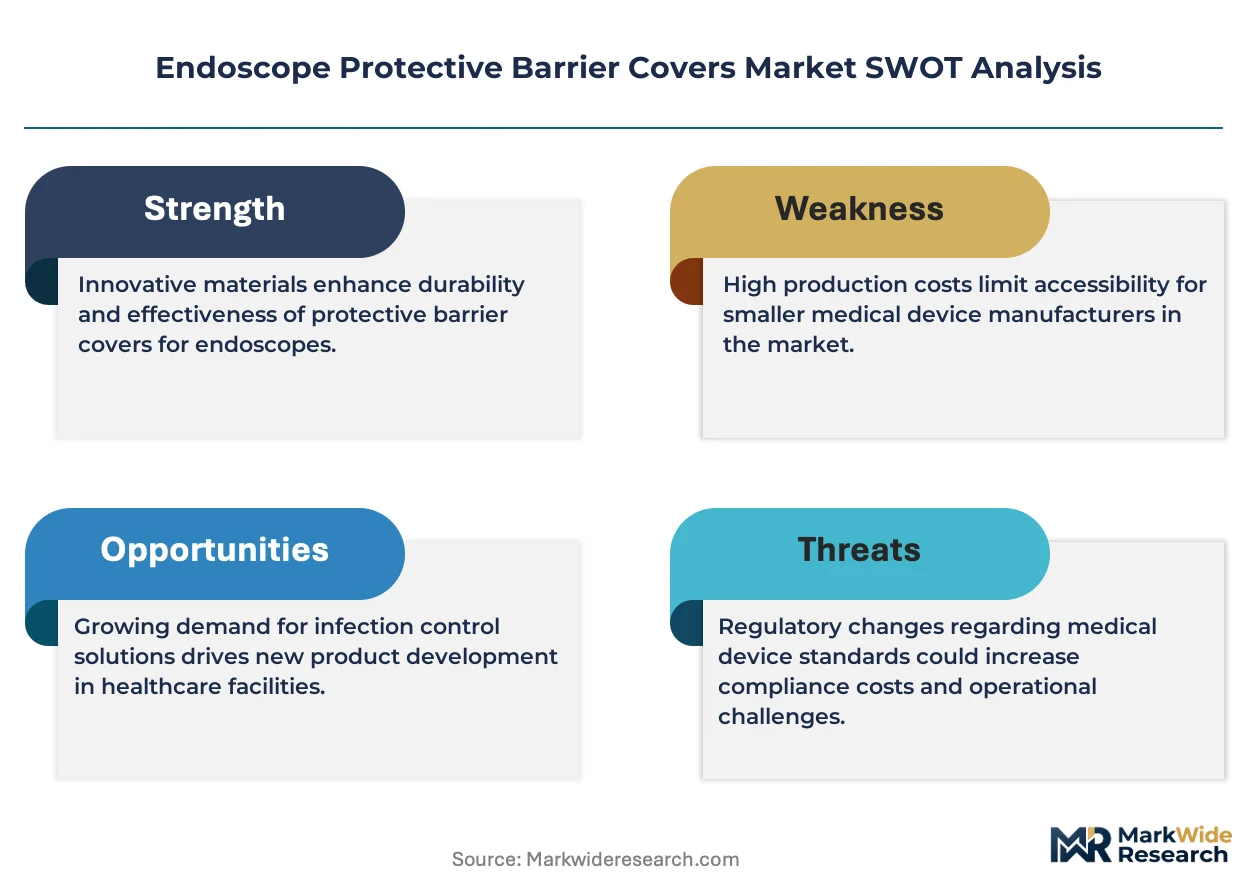
Endoscope protective barrier covers are thin polymeric sheaths, typically 0.02–0.08 mm in gauge, that envelope flexible or rigid endoscopes to block bioburden transfer between patients. These covers are manufactured via blown film extrusion or dip molding and serve primarily to reduce cross-contamination risk during procedures where full sterilization cycles between cases are impractical. Single-use polyethylene covers dominate volume due to their compatibility with high-throughput ambulatory settings, while sterile covers command margin premiums in operating rooms where aseptic protocol is non-negotiable. Reusable silicone-based alternatives occupy a narrowing niche as reprocessing labor costs erode their total-cost-of-ownership advantage.
FDA 510(k) clearance pathways, EMA MDR classification for Class I medical devices, and ISO 13485 quality management standards collectively dictate design documentation, biocompatibility testing, and post-market surveillance obligations for barrier cover suppliers. These frameworks elevate compliance spending for entrants while rewarding incumbents with established regulatory dossiers and notified body relationships. Stakeholders must monitor evolving EPA guidance on single-use plastics in healthcare and assess whether material substitution mandates will force polyethylene-to-polypropylene transitions ahead of competitor pipeline adjustments.
Market Dynamics
FDA's updated reprocessing guidance is elevating validation requirements for sterile claims, forcing manufacturers to restructure their cost-of-entry calculus and favoring incumbents with established regulatory dossiers. This regulatory compression is simultaneously accelerating polyethylene film extrusion advances and concentrating procurement power among ambulatory surgical centers with stricter infection control mandates.
Growth Catalysts
- EMA MDR classification:Class I medical device designation for barrier covers streamlines market access across European Union member states while mandating ISO 13485 quality management compliance that reinforces buyer confidence.
- Blown film extrusion advances:Improvements in polyethylene gauge control and tensile strength are expanding single-use cover applications into higher-complexity endoscopic procedures previously reserved for sterilized equipment.
- Ambulatory surgical centers:High-throughput outpatient facilities in the United States are expanding procurement of single-use barrier covers as procedure volumes compress turnaround times between cases.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene resin prices fluctuate with crude oil benchmarks, compressing margin stability for cover manufacturers without backward integration into polymer production.
- Reusable silicone alternatives:Narrowing total-cost-of-ownership gaps in low-volume settings create substitution pressure, particularly where reprocessing labor costs remain below automated sterilization thresholds.
- FDA 510(k) pathway complexity:Biocompatibility testing and post-market surveillance obligations extend time-to-revenue for new entrants, consolidating advantage with established notified body relationships.
Strategic Opportunities
- Japan's aging demographic:Expanding endoscopy screening programs for gastric cancer detection are elevating procedure volumes and protective accessory consumption in metropolitan hospital clusters.
- EPA single-use plastics guidance:Anticipated material substitution mandates create first-mover advantage for manufacturers pivoting to polypropylene or bio-based polymer formulations ahead of competitor pipeline adjustments.
- Terminal sterilization compatibility:Extended shelf life claims through STERIS plc validation protocols open long-term contracting opportunities with integrated delivery networks seeking supply security.
Industry Challenges
- ISO 13485 certification timelines:Notified body backlogs and documentation requirements delay quality management system approvals, constraining production scale-up for emerging manufacturers.
- Legacy endoscope integration:Dimensional variability across Olympus Corporation and competing installed bases complicates universal cover design, fragmenting SKU portfolios and inventory management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Protective Barrier Covers Market |
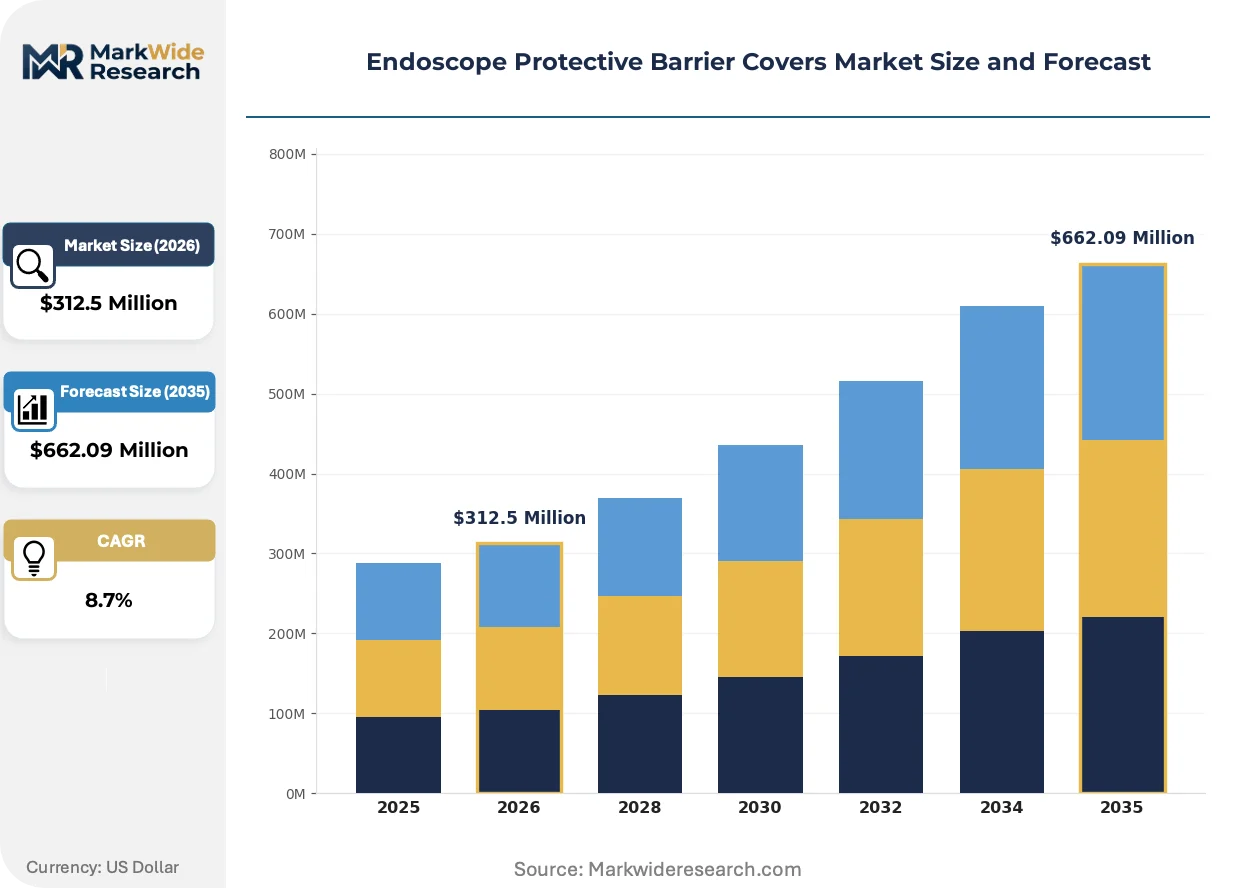
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Covers, Reusable Covers, Sterile Covers, Non-Sterile Covers Application: Endoscopy, Surgical Procedures, Diagnostic Procedures, Therapeutic Procedures Material: Polyethylene, Polypropylene, Vinyl, Latex End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories |
| Companies Covered | Cogentix Medical, Cover Srl, Olympus Corporation, Key Surgical, STERIS plc, Medtrica Solutions Ltd, Aspen Surgical, Meditech Endoscopy Ltd, Medline Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Protective Barrier Covers Market Shifts & Advancements
Material science advances and regulatory compression are actively restructuring competitive positioning in barrier cover manufacturing. Three distinct vectors are reshaping how suppliers design, validate, and distribute protective accessories across endoscopy workflows.
Co-extruded multilayer polyethylene films with oxygen barrier properties are extending cover shelf life without gamma sterilization. Ambulatory surgical centers in Germany are adopting these materials for same-day procedure scheduling flexibility. This shelf-life extension is decentralizing inventory management from centralized hospital stores to point-of-care cabinets, compressing logistics overhead for outpatient networks.
REACH regulation amendments targeting healthcare single-use plastics are accelerating material substitution roadmaps across European manufacturing. Industrial consequence includes accelerated R&D spending on polypropylene and cyclic olefin copolymer alternatives ahead of 2027 restriction timelines. Sterile cover segments serving operating rooms are most affected, with notified body consultations expanding to encompass new polymer biocompatibility dossiers.
Hospital supply contract bundling is consolidating procurement decisions for protective accessories with endoscope system purchases. Integrated delivery networks in the United States are displacing standalone cover purchasing through multi-year equipment lease arrangements that specify captive accessory supply. This channel compression is most visible in metropolitan health systems where Olympus Corporation leverages installed base relationships to anchor protective product volume commitments.
Endoscope Protective Barrier Covers Market Segmentation
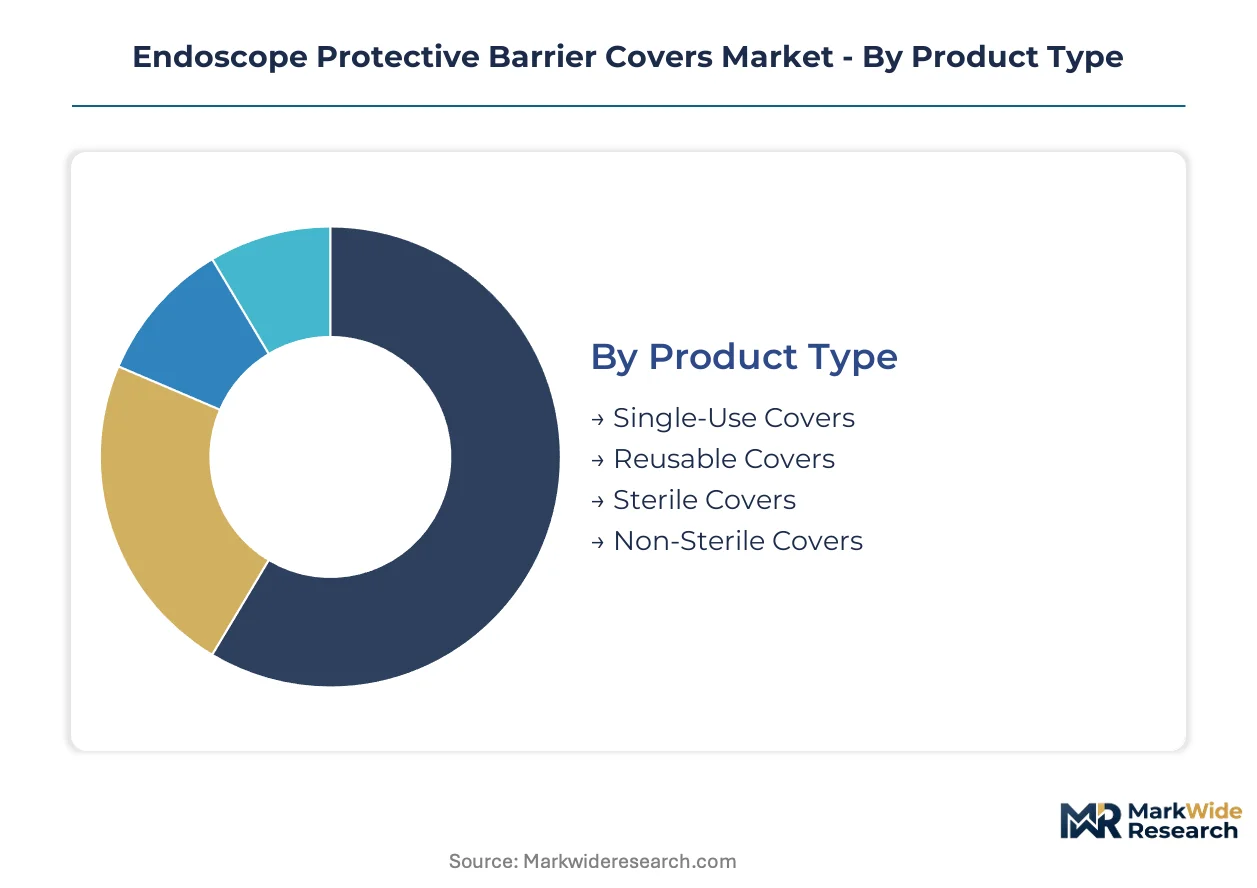
Endoscope protective barrier cover procurement varies sharply across clinical settings and sterilization protocols. Material selection and regulatory classification determine margin structures, while end-user scale dictates volume concentration and distribution economics.
Product Type:
Cost tier separates high-throughput outpatient facilities from capital-intensive hospital systems.
- Single-Use Covers:Polyethylene sheaths manufactured via blown film extrusion dominate ambulatory surgical center procurement. United States outpatient networks favor these for compressed turnaround times between cases where sterilization infrastructure is absent.
- Sterile Covers:Gamma-irradiated or ethylene oxide-sterilized variants command premium positioning in operating rooms. EMA MDR Class I designation and FDA 510(k) clearance requirements elevate validation costs, consolidating supply among incumbents with established notified body relationships.
- Reusable Covers:Silicone-based alternatives face narrowing adoption as automated reprocessing labor costs erode total-cost-of-ownership advantages in low-volume settings.
- Non-Sterile Covers:Basic polyethylene barriers serve diagnostic workflows where aseptic protocol is less stringent, competing primarily on unit economics and same-day fulfillment.
Single-use covers lead volumes today; sterile covers are gaining share fastest.
Application:
Procedure complexity drives specification requirements and reimbursement eligibility.
- Endoscopy:Gastrointestinal and pulmonary diagnostic workflows generate baseline demand for standard-gauge polyethylene barriers. Japan's aging demographic and expanding gastric cancer screening programs elevate procedure volumes in metropolitan hospital clusters.
- Surgical Procedures:Operating room integration demands sterile covers with validated bioburden blocking and terminal sterilization compatibility. STERIS plc validation protocols extend shelf life claims, enabling long-term contracting with integrated delivery networks.
- Diagnostic Procedures:Colonoscopy and cystoscopy screening volumes concentrate procurement power among high-throughput ambulatory chains seeking compressed per-procedure costs.
- Therapeutic Procedures:ERCP and EUS interventions require specialized cover dimensions accommodating instrument channels, fragmenting SKU portfolios across legacy endoscope installed bases.
Endoscopy anchors current volumes; surgical procedures show the steepest expansion trajectory.
Material:
Regulatory pressure on single-use plastics is forcing substitution roadmaps across European manufacturing.
- Polyethylene:Low-density and linear low-density variants dominate via cost-optimized blown film extrusion. REACH regulation amendments targeting healthcare plastics are accelerating R&D spending on alternatives ahead of restriction timelines.
- Polypropylene:Cyclic olefin copolymer formulations offer improved clarity and sterilization tolerance. Germany's ambulatory networks are piloting these materials for oxygen barrier properties that extend shelf life without gamma irradiation.
- Vinyl:PVC-based covers occupy declining share amid environmental scrutiny and plasticizer biocompatibility concerns.
- Latex:Natural rubber alternatives persist in niche reusable segments despite allergy protocol complications and reprocessing labor intensity.
Polyethylene retains volume leadership; polypropylene is climbing the fastest.
End User:
Customer scale determines distribution density requirements and contract bundling leverage.
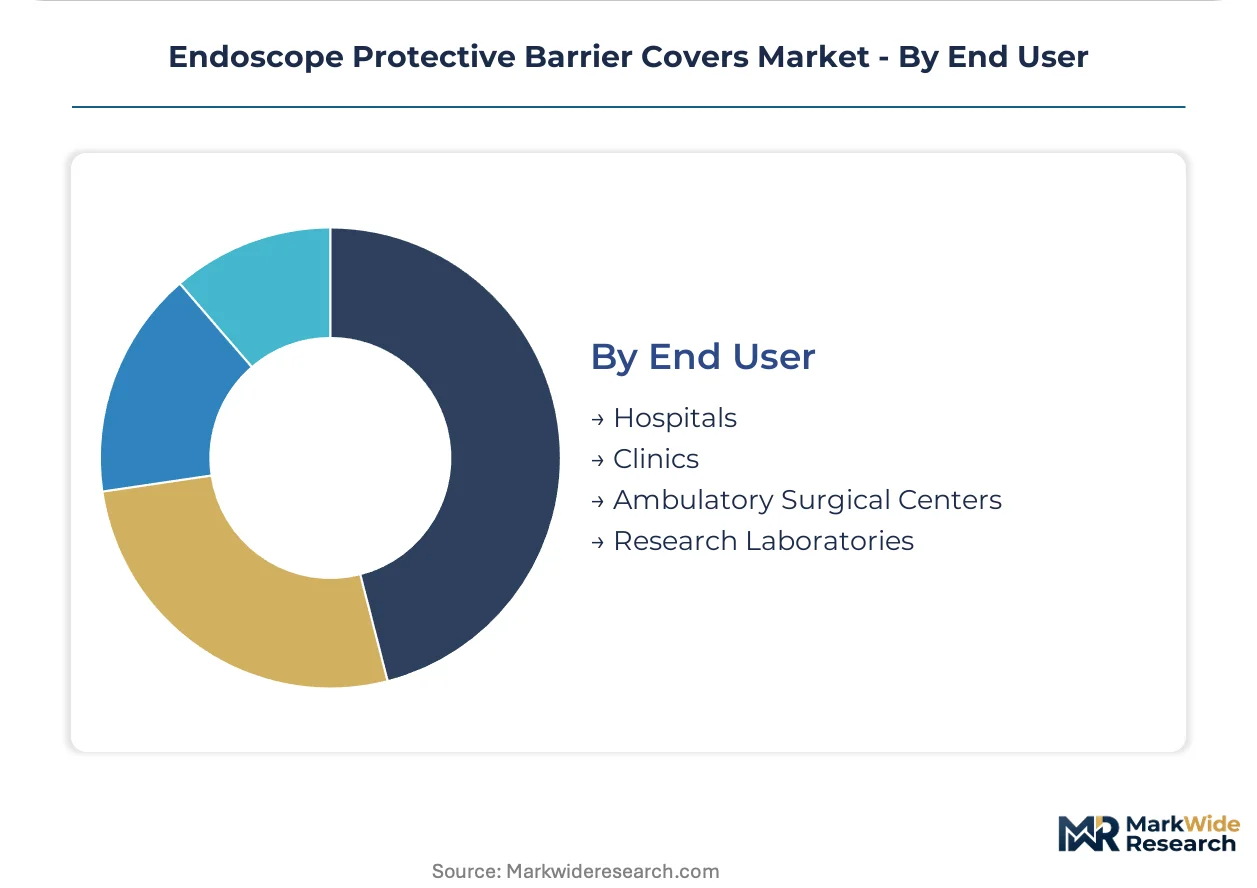
- Ambulatory Surgical Centers:High-throughput United States outpatient facilities drive single-use cover volume through compressed case scheduling. Same-day fulfillment requirements favor distributors with dense last-mile networks.
- Hospitals:Integrated delivery networks consolidate procurement through multi-year equipment lease arrangements. Olympus Corporation leverages installed base relationships to anchor protective accessory commitments.
- Clinics:Independent gastroenterology practices prioritize unit economics over sterile certification, sourcing non-sterile covers through group purchasing organizations.
- Research Laboratories:Preclinical and veterinary applications generate fragmented demand with specialized dimensional requirements and limited volume concentration.
Ambulatory surgical centers dominate current procurement; hospitals are expanding share fastest through contract bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer engineers and sterile manufacturing technicians concentrate in medical device hubs across the United States, Germany, and Japan, anchoring production capacity for precision extrusion and terminal sterilization validation.
United States
Ambulatory surgical centers in Texas and Florida drive single-use polyethylene cover consumption through compressed case scheduling. FDA 510(k) clearance pathways elevate validation costs for sterile claims, consolidating supply among incumbents with established notified body relationships. Minneapolis-based distributors sustain same-day fulfillment networks to outpatient clinics across the Midwest and Southeast.
Germany
REACH regulation amendments targeting healthcare single-use plastics are accelerating material substitution roadmaps in Baden-Württemberg manufacturing clusters. EMA MDR Class I designation streamlines market access while mandating ISO 13485 compliance. Stuttgart-area extrusion facilities are piloting cyclic olefin copolymer formulations for oxygen barrier properties that extend shelf life without gamma irradiation.
Japan
Expanding gastric cancer screening programs in the Kanto region are elevating endoscopy procedure volumes and protective accessory consumption. PMDA quality management standards enforce rigorous biocompatibility testing protocols. Tokyo metropolitan hospital clusters represent the densest concentration of therapeutic endoscopy workflows requiring specialized cover dimensions.
United Kingdom
Integrated delivery networks in London and the Southeast are consolidating procurement through multi-year equipment lease arrangements. NHS infection control mandates are elevating sterile cover specifications in operating room settings. Cambridge-area research partnerships are exploring bio-based polymer alternatives ahead of anticipated environmental restriction timelines.
China
Domestic endoscope manufacturers in the Yangtze River Delta are expanding captive production of protective accessories to reduce import dependency. NMPA medical device registration requirements are elevating documentation burdens for foreign suppliers. Suzhou industrial parks are attracting blown film extrusion specialists to serve regional diagnostic equipment demand.
Endoscope Protective Barrier Covers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure favors incumbents with backward integration into polymer supply and established regulatory dossiers. Three archetypes dominate: integrated endoscopy system manufacturers bundling protective accessories, standalone cover specialists competing on distribution density, and sterilization service providers extending into validated cover supply. Dominant competitive moves include hospital supply contract bundling and terminal sterilization compatibility certification to extend shelf life claims.
Among diversified medical technology conglomerates, Olympus Corporation and STERIS plc exemplify distinct strategic positioning. Olympus leverages installed base relationships to anchor protective accessory commitments through multi-year equipment lease arrangements. STERIS anchors its market position through terminal sterilization compatibility testing that extends cover shelf life claims for integrated delivery networks. Medline Industries, Inc. occupies a position within the distribution-focused tier, competing on fulfillment density to outpatient clinics rather than manufacturing scale or system integration.
| Leading Market Players |
|---|
| Cogentix Medical |
| Cover Srl |
| Olympus Corporation |
| Key Surgical |
| STERIS plc |
| Medtrica Solutions Ltd |
| Aspen Surgical |
| Meditech Endoscopy Ltd |
| Medline Industries, Inc. |
| Others |
Supply & Pricing Matrix
ASC procurement mandates for sterile certification are compressing supplier margins and forcing polyethylene resin sourcing toward integrated compounders with FDA master file documentation. This demand-side specification tightening elevates validation costs for new entrants while rewarding incumbents with established notified body relationships and backward polymer integration.
Pricing Analysis
Bundled equipment-accessory contracts versus standalone cover purchasing splits pricing power between integrated endoscopy manufacturers and distribution-focused specialists. Three-tier pricing structure across sterile premium, single-use standard, and non-sterile economy levels reflects certification grade and terminal sterilization compatibility. Cost compression in the standard tier is intensifying because ambulatory chains negotiate volume commitments against same-day fulfillment guarantees. Independent gastroenterology clinics exhibit highest price sensitivity; integrated delivery networks anchored by multi-year system leases show lowest.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Stuttgart, and Tokyo anchor hub-and-spoke fulfillment patterns for same-day clinic service. Manufacturing concentrates in the United States, Germany, and Japan where sterile extrusion and terminal sterilization validation capabilities cluster. Feedstock draws from Saudi Arabian and U.S. Gulf Coast polyethylene resin suppliers, with gamma irradiation services resting on Nordion and Sterigenics network nodes. Single-source vulnerability in medical-grade resin qualification creates supply continuity exposure. Distribution runs through distributor-owned warehousing with direct-to-ASC last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on material substitution roadmaps that capture polypropylene premiums ahead of REACH restriction timelines, alongside automated extrusion scale-down that compresses per-unit conversion costs.
For Market Incumbents: Deploy terminal sterilization compatibility certification as a defensive moat against emerging entrants lacking STERIS plc validation relationships. Deepen backward integration into medical-grade polyethylene compounding to insulate margin from petrochemical feedstock volatility. Channel control through GPO contract anchoring defends position against ambulatory chain procurement consolidation. For New Entrants and Emerging Players: Begin with bio-based polymer formulation R&D targeting Cambridge-area research partnerships and NHS sustainability procurement preferences. White-space sits with cyclic olefin copolymer pilot programs in German ambulatory networks where oxygen barrier shelf-life extension commands premium positioning. Go-to-market through specialized endoscope repair depots bypasses incumbent equipment bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with sterile cover specialists possessing EMA MDR Class I dossiers and ISO 13485 notified body relationships ahead of regulatory compression. Five-to-ten year viability favors acquisition targets with material science pipelines beyond polyethylene. Signal to watch: EPA guidance finalization on healthcare single-use plastics triggering substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | 510(k) clearance for sterile claims anchors hospital procurement contracts against unvalidated competitors. |
| Hospital System Partnership | Multi-year equipment lease bundling with Olympus Corporation locks protective accessory volume commitments. |
| Backward Integration | In-house polyethylene compounding insulates margin from resin price volatility and qualification delays. |
| CE Marking Pathway | EMA MDR Class I designation streamlines EU market access while mandating ISO 13485 quality systems. |
| Reimbursement Strategy | CPT code alignment for protective accessories elevates ambulatory surgical center procurement eligibility. |
Research Methodology
Coverage spans the United States, Germany, Japan, and the United Kingdom, with primary inputs from each market's stakeholder ecosystem. Primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and ASC operations directors combined with secondary validation from FDA 510(k) filings, EMA MDR registration databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Rate-of-change decomposition separated volume growth from price-mix effects across product type, application, material, and end-user segmentation dimensions. CAGRs derived from logistic curve fitting to procedure volume trajectories and polymer cost pass-through elasticity estimates. Forecast inputs incorporated REACH amendment timelines, EPA single-use plastics guidance development, and ambulatory surgical center expansion pipelines without year-specific milestone assumptions.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration, raw material supply disruptions, and endoscope system technology obsolescence. Forecasts reflect documented assumptions about sterilization protocol adoption and reimbursement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Luer Plug Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Autoclaving Trays Market