
 Swabs Collection Kit Market | 2026-2036
Swabs Collection Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Swabs Collection Kit Market Analytics
The swabs collection kit landscape is restructuring around a sharp split between premium sterile kits with full traceability and commodity bulk swabs competing on unit cost. BD leverages vertical integration across medical devices and diagnostics to sustain margin capture from nasopharyngeal kit production. Puritan Medical Products anchors its position through manufacturing scale in synthetic-fiber swab technology, while Copan Diagnostics differentiates via specialized transport media integration that extends kit functionality beyond basic specimen collection.
Swabs collection kits comprise single-use devices engineered for targeted biological specimen retrieval, typically featuring flocked nylon or molded plastic shafts paired with absorbent tips designed to release samples into transport media or extraction buffers. Nasopharyngeal swabs dominate hospital procurement due to respiratory pathogen detection protocols, while diagnostic labs drive fastest expansion in oropharyngeal and vaginal kit categories as molecular testing menus broaden. Sterile individual packs command premium positioning in clinical settings, whereas bulk non-sterile formats occupy cost-sensitive reference laboratory workflows where in-house sterilization occurs downstream.
FDA 21 CFR Part 820 quality system regulations and ISO 13485 medical device standards govern sterility assurance and traceability, with the former mandating design controls that elevate R&D costs for new kit entrants. The EPA regulates ethylene oxide sterilization emissions from manufacturing facilities, constraining capacity expansion at existing sterilization hubs. Stakeholders must monitor evolving EPA emission limits and FDA guidance on reprocessed versus single-use devices, as these will determine capital allocation between sterilization infrastructure and alternative material platforms.
Market Dynamics
Automated specimen processing workflows in diagnostic laboratories are compressing turnaround time requirements and forcing swab kit suppliers to engineer compatibility with liquid-handling robotics rather than manual collection protocols.
Growth Catalysts
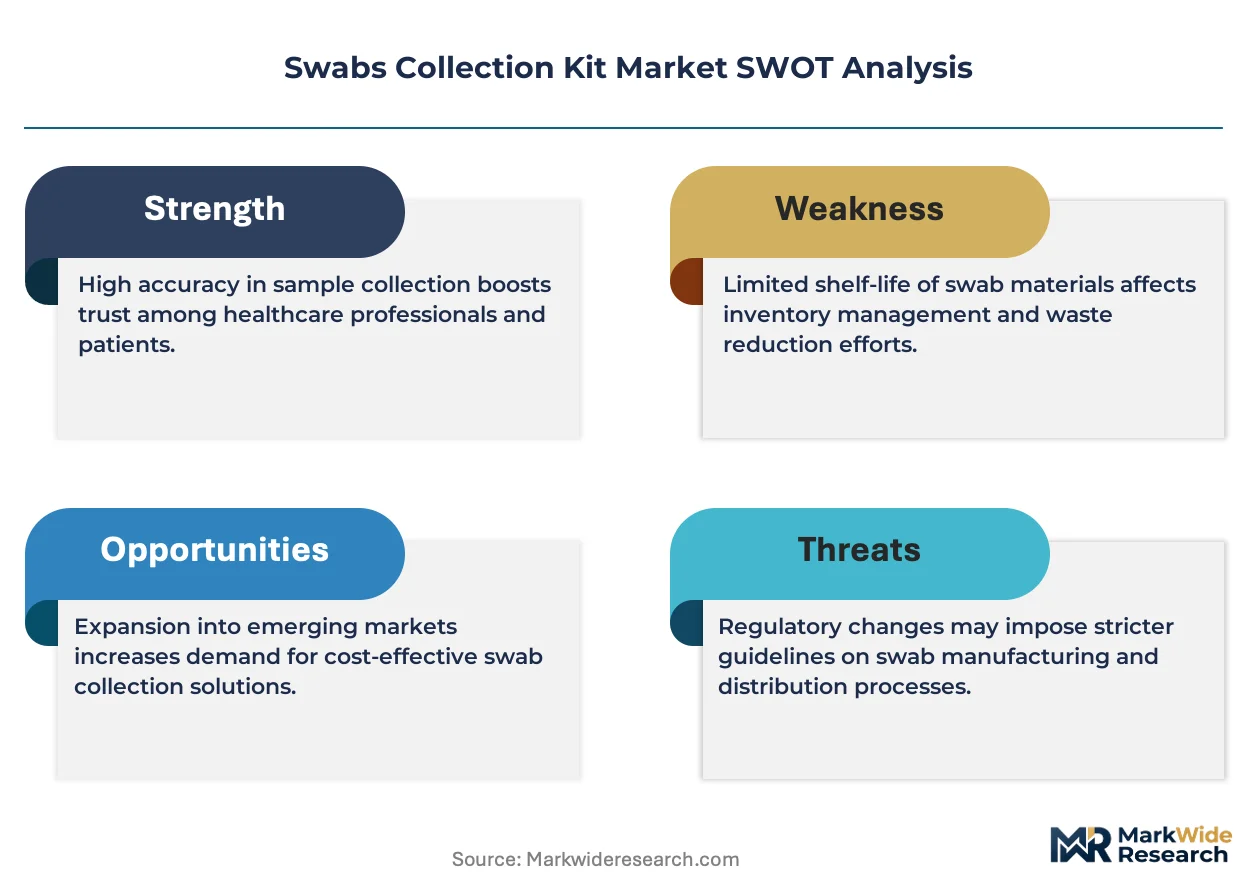
- EPA Ethylene Oxide Emission Controls:Stricter EPA caps on EtO sterilization emissions are accelerating capital investment in alternative sterilization technologies, expanding manufacturing capacity for sterile kit suppliers who adapt first.
- Molecular Testing Menu Expansion:Diagnostic laboratories are broadening respiratory, STI, and gastrointestinal pathogen detection panels, pulling demand for specialized oropharyngeal and vaginal collection formats.
- Hospital Procurement Consolidation:Integrated delivery networks in the United States are consolidating vendor lists, favoring kit suppliers with full traceability systems and multi-site distribution capabilities.
Market Restraints
- Synthetic Flocked Nylon Supply Concentration:Three manufacturers control the majority of medical-grade flocked fiber production, creating input bottlenecks during demand surges.
- FDA 21 CFR Part 820 Compliance Burden:Design control documentation and sterility validation requirements extend new product development timelines by 18-24 months for kit entrants.
- Downstream In-House Sterilization:Large reference laboratories maintain captive EtO and gamma sterilization capacity, limiting pricing power for pre-sterilized kit suppliers in bulk segments.
Strategic Opportunities
- At-Home Collection Authorization:FDA emergency use pathway expansions for patient-collected specimens are opening direct-to-consumer channels previously restricted to clinical settings.
- Transport Media Integration:Convergence of nucleic acid stabilization chemistry with swab design extends shelf life and reduces cold-chain dependency for point-of-care deployments.
- India Diagnostic Infrastructure Buildout:CDSCO streamlined medical device registration and government health scheme expansion are creating entry points for CE-marked kit suppliers.
Industry Challenges
- ISO 13485 Auditor Shortage:Limited availability of qualified certification bodies is extending quality management system audit queues, delaying market entry for new manufacturers.
- Legacy LIMS Integration:Hospital laboratory information management systems require custom barcode and data field mapping for automated kit tracking, complicating vendor switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swabs Collection Kit Market |
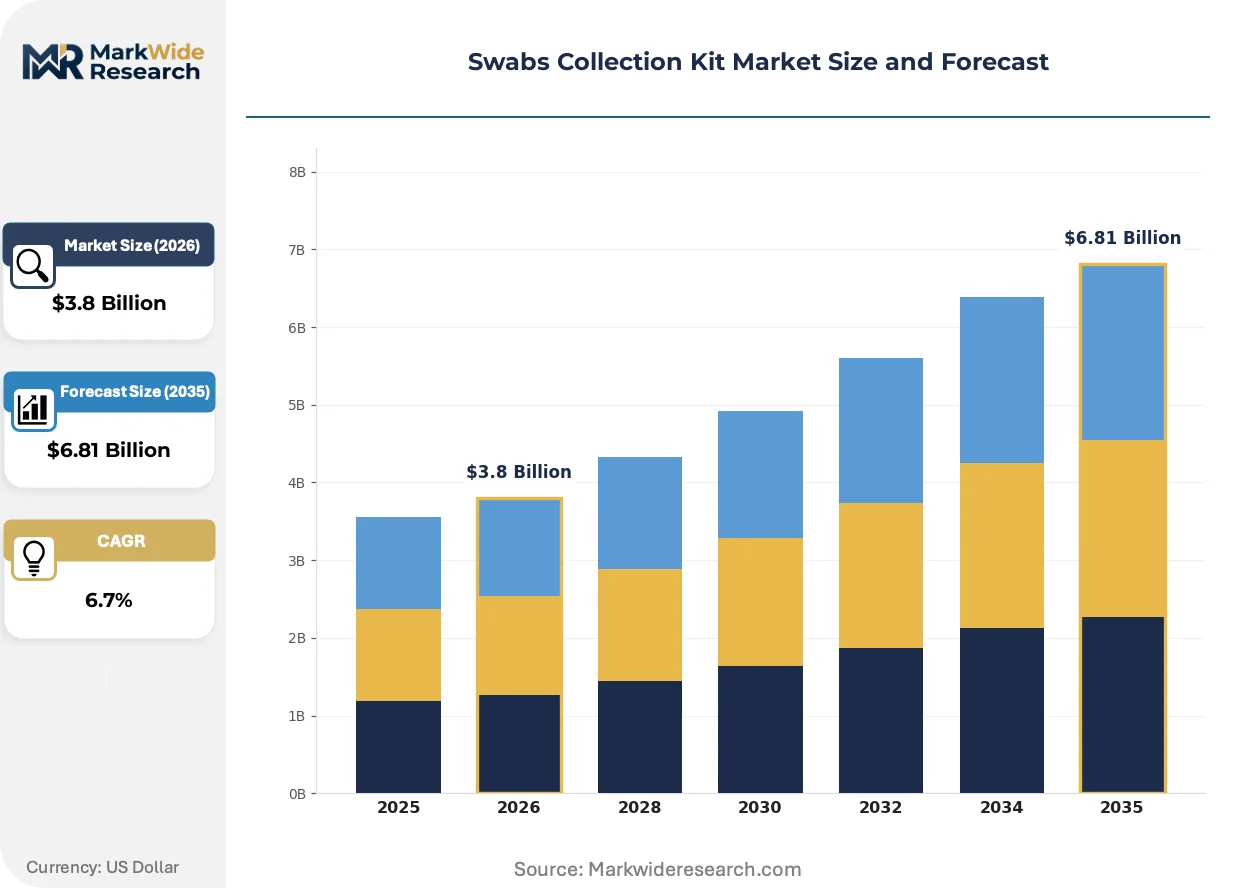
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasopharyngeal Swabs, Oropharyngeal Swabs, Vaginal Swabs, Urinary Swabs End User: Hospitals, Clinics, Diagnostic Labs, Home Care Packaging Type: Sterile Kits, Non-Sterile Kits, Bulk Packaging, Individual Packs Material: Plastic, Cotton, Nylon, Bamboo |
| Companies Covered | BD, Puritan Medical Products, Copan Diagnostics Inc., Thermo Fisher Scientific Inc., HiMedia Laboratories, QIAGEN, F. Hoffmann-La Roche, Medline Industries, LP., Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swabs Collection Kit Market Evolving Landscape
Swab collection technology is bifurcating between high-complexity integrated systems for automated labs and simplified formats for decentralized testing, with material science and regulatory compliance as the primary axes of differentiation.
Flocked nylon swab tips are absorbing liquid specimen volumes more efficiently than traditional spun-fiber designs, enabling higher nucleic acid yields from minimal biological material. Diagnostic laboratories with high-throughput molecular platforms are adopting these formats fastest, replacing legacy Dacron and rayon alternatives. The shift is compressing demand for basic molded-plastic shaft swabs in premium clinical segments while commodity bulk orders persist in cost-constrained settings.
EU MDR 2017/745 device classification rules are reclassifying swabs with integrated transport media as Class IIa or IIb devices, triggering notified body involvement and clinical evidence requirements that did not apply under the prior Medical Device Directive. Manufacturers with existing CE certificates face renewal audits under stricter biocompatibility and sterility assurance standards. Small and mid-sized kit suppliers without dedicated regulatory affairs functions are outsourcing compliance to specialized consultancies or exiting the European market entirely.
Hospital supply chain directors are consolidating vendor contracts around integrated kit suppliers who bundle collection devices, transport media, and extraction consumables under single-source agreements. This behavior is displacing fragmented purchasing of swabs, tubes, and reagents from separate vendors. The pattern is most visible in United States health systems with centralized procurement offices, where total-cost-of-contract metrics override unit-price comparisons in supplier selection.
Swabs Collection Kit Market Segmentation
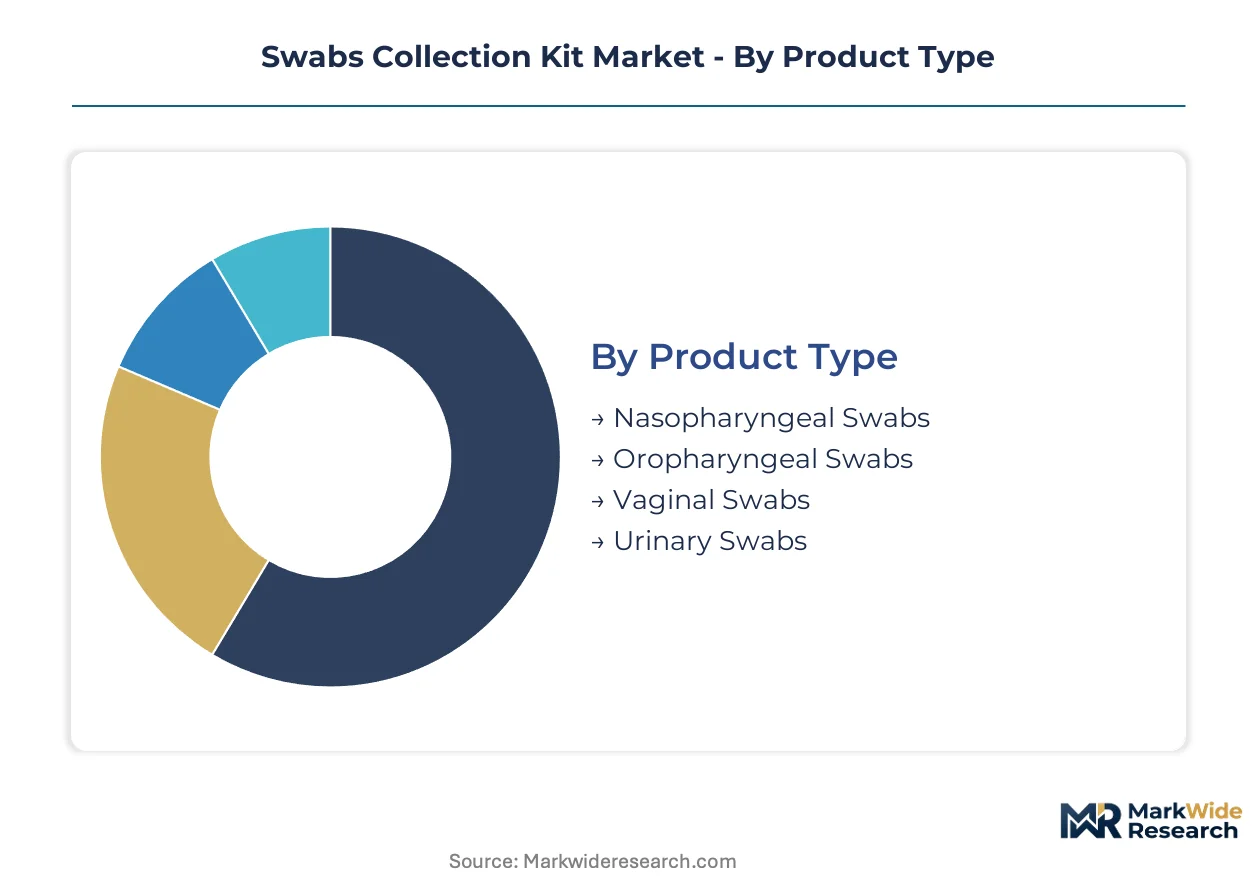
Swabs collection kit suppliers configure production lines around sterility grade, material specifications, and end-user workflow requirements. Segmentation discipline determines capital allocation between automated sterile packaging and bulk non-sterile formats.
Product Type:
Nasopharyngeal swabs demand the heaviest upfront tooling investment for flocked fiber precision molding and shaft flexibility calibration.
- Nasopharyngeal Swabs:Flocked nylon tips engineered for deep nasal cavity access and optimal viral RNA recovery dominate hospital procurement contracts. United States respiratory surveillance programs and seasonal influenza monitoring sustain volume concentration in integrated health systems with centralized pathology departments.
- Oropharyngeal Swabs:Shorter shafts with absorbent fiber tips target posterior pharyngeal wall sampling for streptococcal and respiratory pathogen panels. Diagnostic laboratories in Germany and France are expanding oropharyngeal kit orders as molecular multiplex testing menus broaden beyond COVID-19 surveillance.
- Vaginal Swabs:Tapered tips with reduced diameter address cytology and STI molecular testing requirements in women's health clinics.
- Urinary Swabs:Specialized collection devices for catheter-associated specimen retrieval occupy urology and microbiology lab workflows.
Nasopharyngeal swabs absorb the bulk of installed capacity; oropharyngeal swabs are expanding most quickly.
End User:
Customer type determines pricing power, with diagnostic laboratories commanding volume discounts that compress per-unit margins below hospital procurement tiers.
- Hospitals:Inpatient and emergency departments require sterile individual packs with full lot traceability for Joint Commission compliance. United States health systems with consolidated supply chains negotiate multi-year kit agreements bundling nasopharyngeal and oropharyngeal formats.
- Diagnostic Labs:High-throughput molecular platforms drive fastest kit consumption growth as automated liquid-handling systems standardize on specific shaft dimensions and tip geometries. Reference laboratories in India and Brazil are scaling PCR testing infrastructure.
- Clinics:Outpatient settings balance sterility requirements against inventory turnover constraints in limited storage environments.
- Home Care:Patient-collected specimen authorization under FDA emergency use pathways is opening direct-to-consumer channels with simplified collection instructions and stabilized transport media.
Diagnostic labs absorb the bulk of installed capacity; home care is climbing the fastest.
Packaging Type:
Packaging configuration directly governs sterilization capital requirements and regulatory filing complexity.
- Sterile Kits:Individual peel-pouch packaging with ethylene oxide or gamma sterilization validation commands premium positioning in surgical and neonatal intensive care settings. FDA 21 CFR Part 820 design controls and ISO 13485 quality system documentation elevate entry barriers for new sterile kit suppliers.
- Non-Sterile Kits:Bulk packaging without terminal sterilization serves reference laboratories with captive EtO capacity and in-house quality validation. Cost-sensitive procurement in academic medical center core laboratories favors this format for non-invasive screening applications.
- Bulk Packaging:Large-volume cartons with minimal unit labeling reduce per-swab cost for high-consumption reference laboratories.
- Individual Packs:Single-unit pouches with barcode serialization support point-of-care inventory tracking and automated dispensing cabinet integration.
Sterile kits absorb the bulk of installed capacity; individual packs are gaining share fastest.
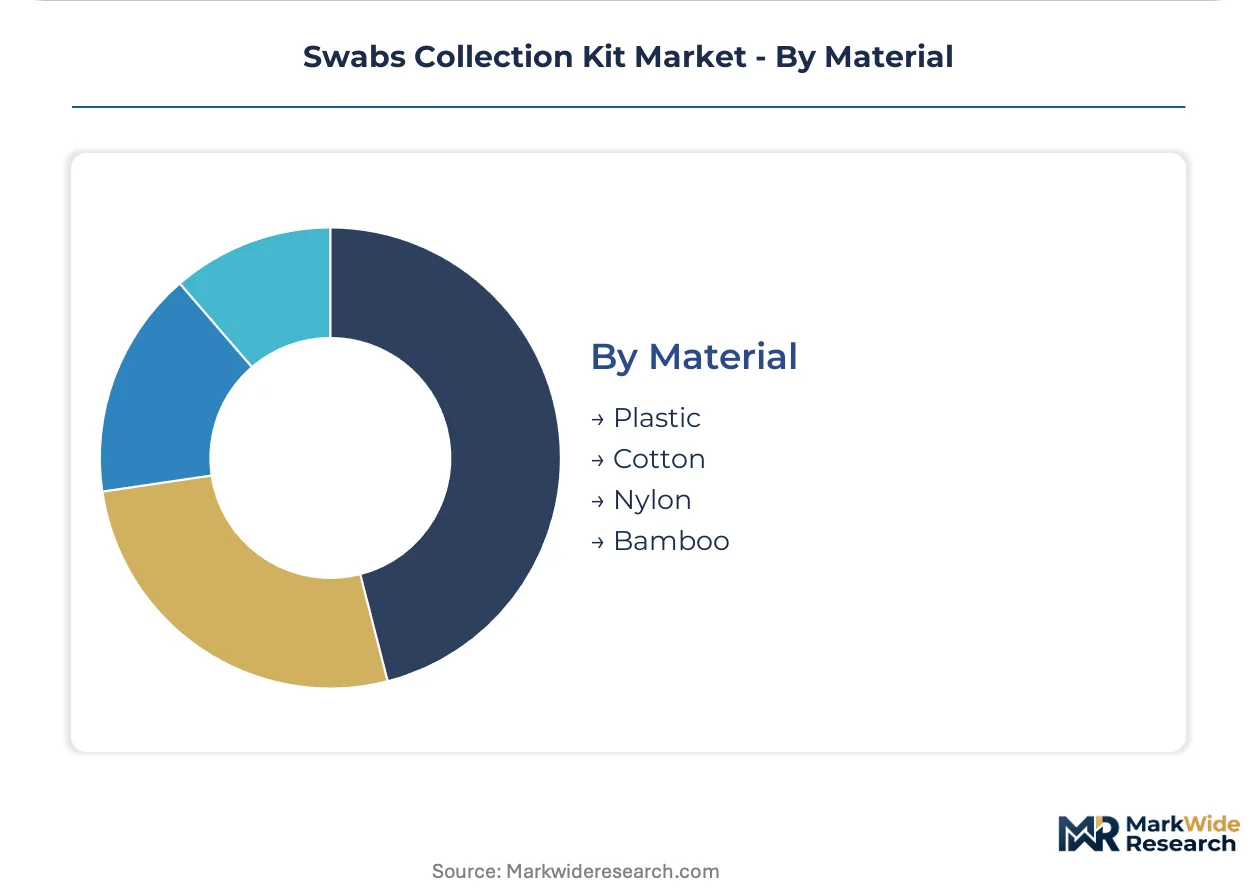
Material:
Raw material selection locks suppliers into specific fiber supply agreements and sterilization compatibility profiles.
- Nylon:Flocked medical-grade nylon fibers with defined denier and electrostatic charge properties enable superior nucleic acid release compared to spun natural fibers. Synthetic fiber supply concentrates among three manufacturers, creating input bottlenecks during demand surges for respiratory testing.
- Plastic:Molded polystyrene or polypropylene shafts with break-point engineering dominate cost-optimized kit production for high-volume reference laboratory contracts.
- Cotton:Natural fiber tips with high absorbency persist in legacy cytology and wound culture applications where nucleic acid yield is secondary to cell preservation.
- Bamboo:Biodegradable shaft materials are emerging in sustainability-focused procurement tenders from European hospital systems targeting plastic waste reduction.
Nylon absorbs the bulk of installed capacity; bamboo is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guilford, Maine anchors North American manufacturing capacity for synthetic-fiber swab production, with Puritan Medical Products operating multiple facilities along the rural industrial corridor. This concentration shapes procurement patterns across downstream diagnostic supply chains.
United States
Hospital procurement consolidation through integrated delivery networks favors kit suppliers with multi-site distribution and full traceability systems. FDA 21 CFR Part 820 quality system regulations mandate design controls that extend product development timelines for new market entrants. The Research Triangle Park corridor in North Carolina hosts diagnostic laboratory clusters scaling automated specimen processing workflows.
Germany
Diagnostic laboratories in Bavaria and Baden-Württemberg are expanding molecular testing menus beyond respiratory panels into gastrointestinal and STI pathogen detection. EU MDR 2017/745 reclassifies swabs with integrated transport media as Class IIa or IIb devices, triggering notified body involvement and clinical evidence requirements. The Munich-Stuttgart industrial corridor concentrates reference laboratory automation infrastructure.
India
Government health scheme expansion and CDSCO streamlined medical device registration are accelerating diagnostic infrastructure buildout in Maharashtra and Karnataka. The central government's PLI scheme for medical devices incentivizes domestic manufacturing capacity for sterile collection kits. Hyderabad's pharmaceutical cluster is absorbing expanded PCR testing infrastructure investment.
China
NMPA medical device registration requirements and GB standards for sterility assurance govern domestic production and import substitution programs. The Yangtze River Delta around Shanghai hosts contract manufacturers serving export markets with cost-optimized bulk packaging formats. Shenzhen's medical device ecosystem is developing automated packaging lines for individual sterile pouches.
Japan
PMDA quality management system requirements and JIS standards for medical device sterility sustain premium positioning for domestic kit suppliers. METI industrial policy supports domestic production of high-complexity diagnostic consumables. The Kansai region around Osaka maintains specialized manufacturing for flocked fiber precision molding.
Swabs Collection Kit Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sterility validation and traceability certification tiers. The vendor base clusters around three strategic archetypes: vertically integrated medical device conglomerates with diagnostic divisions, specialized synthetic-fiber manufacturers with captive swab production, and transport media specialists extending into collection device integration. Dominant competitive moves include capacity expansion in alternative sterilization technologies and strategic partnerships bundling collection devices with nucleic acid extraction consumables.
Among North American manufacturers, BD and Puritan Medical Products exemplify divergent archetypes within the premium tier. BD represents the vertically integrated medical device conglomerate model with backward integration into diagnostics. Puritan Medical Products anchors the specialized synthetic-fiber manufacturer archetype with concentrated production in rural Maine. Copan Diagnostics occupies a position exemplifying the transport media integration specialist model, extending kit functionality beyond basic specimen collection through stabilized chemistry platforms.
| Leading Market Players |
|---|
| BD |
| Puritan Medical Products |
| Copan Diagnostics Inc. |
| Thermo Fisher Scientific Inc. |
| HiMedia Laboratories |
| QIAGEN |
| F. Hoffmann-La Roche |
| Medline Industries, LP. |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation across United States integrated delivery networks is mandating full traceability systems and multi-site distribution capabilities, forcing suppliers to absorb certification costs that compress margins on non-sterile bulk formats while elevating premiums for validated sterile kits.
Pricing Analysis
Value-based pricing anchored to nucleic acid yield recovery and automated liquid-handling compatibility separates premium flocked nylon kits from commodity spun-fiber alternatives. Three-tier pricing structure across premium sterile, standard clinical-grade, and economy bulk levels reflects ISO 13485 certification investment and FDA 21 CFR Part 820 design control documentation. Cost compression in economy tiers is intensifying because large reference laboratories maintain captive EtO sterilization capacity. Diagnostic laboratories command highest price sensitivity through volume aggregation, while neonatal intensive care units accept premium positioning for individual sterile pouches with full lot traceability.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital procurement committees mandate qualified backup suppliers for medical-grade flocked nylon fibers, forcing manufacturers to maintain relationships with multiple synthetic fiber producers despite production concentration in Guilford, Maine and Kansai region facilities. Raw material dependencies center on electrostatically charged nylon denier specifications, molded polystyrene shaft resins, and stabilized transport media chemistries. Single-source vulnerability concentrates in medical-grade flocked fiber production where three manufacturers control global capacity. Distribution runs through integrated delivery network central procurement offices and diagnostic laboratory consumables distributors with automated inventory management integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR 2017/745 reclassification of transport-media-integrated swabs as Class IIa or IIb devices is accelerating exit of undercapitalized suppliers, creating acquisition opportunities for firms with dedicated regulatory affairs infrastructure.
For Market Incumbents: Hedge against EPA ethylene oxide emission cap tightening by accelerating capital deployment into gamma sterilization and vaporized hydrogen peroxide alternatives at existing production hubs. Deepen backward integration into synthetic fiber production to secure input supply during respiratory testing demand surges, while maintaining multi-site distribution agreements with consolidated United States health systems to defend contract renewals.
For New Entrants and Emerging Players: Capture white-space opportunity in India's CDSCO-registered sterile kit segment as government health scheme expansion accelerates diagnostic infrastructure buildout in Maharashtra and Karnataka. Target direct-to-consumer channels opened by FDA emergency use pathway expansions for patient-collected specimens, leveraging simplified collection instructions and room-temperature stabilized transport media as differentiation against clinical-focused incumbents.
For Investors and Strategic Acquirers: The window for entry favors specialized synthetic-fiber manufacturers with captive swab production and existing ISO 13485 certification. Long-term viability rests on regulatory compliance infrastructure rather than unit cost optimization. Monitor EPA enforcement actions on ethylene oxide sterilization emissions as inflection indicator for capacity reallocation toward alternative sterilization platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Sterilization Capacity Expansion | Gamma and vaporized hydrogen peroxide investments bypass EPA ethylene oxide emission constraints. |
| Transport Media Integration | Stabilized nucleic acid chemistry extends shelf life and reduces cold-chain dependency for point-of-care deployment. |
| CDSCO Registration Pathway | Streamlined medical device registration in India opens government health scheme procurement channels. |
| Automated Packaging Line Deployment | Individual sterile pouch serialization supports hospital automated dispensing cabinet integration requirements. |
| Synthetic Fiber Backward Integration | Captive flocked nylon production insulates against supply concentration among three global manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement managers, diagnostic laboratory directors, biomedical engineers, and GPO contracts specialists. FDA 21 CFR Part 820 quality system documentation, EPA ethylene oxide emission reports, ISO 13485 certification databases, and hospital supply chain expenditure records provided validation layers. Bottom-up kit consumption modeling triangulated against top-down diagnostic testing volume projections.
Granularity-level modeling operated at product type, end user, packaging configuration, and material specification dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by sterile versus non-sterile mix shifts and automated liquid-handling adoption curves. Forecast inputs incorporated EPA sterilization emission regulatory timelines and EU MDR notified body audit queue durations.
The model holds under stable regulatory enforcement intensity; deviation in EPA ethylene oxide emission cap implementation timing or EU MDR renewal audit backlogs would shift capacity expansion priorities and market entry timelines materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Safety Lancet Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Medical Liners Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market