
 Ostomy Drainage Systems Market | 2026-2036
Ostomy Drainage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ostomy Drainage Systems Market Analytics
The EU Medical Device Regulation is repositioning competitive priorities across the ostomy drainage systems value chain. Coloplast leverages its vertically integrated silicone and adhesive manufacturing to sustain premium positioning in skin-friendly barrier technologies. Hollister Incorporated anchors its presence through deep distribution partnerships with hospital purchasing consortia across Western Europe. B. Braun Melsungen competes on sterilization and aseptic processing expertise, extending its surgical supply credibility into post-operative ostomy care.
Ostomy drainage systems comprise collection pouches, skin barriers, and accessories engineered to manage effluent diversion following surgical creation of stomas, typically constructed from odor-resistant films, hydrocolloid adhesives, and charcoal filter layers to contain gas and liquid waste while protecting peristomal skin integrity. Colostomy bags occupy the largest volume share given the higher incidence of colorectal procedures, though ileostomy bags command stronger per-unit pricing due to more frequent change requirements and specialized high-output designs. Home care leads end-user expansion as discharge protocols accelerate and remote monitoring tools reduce readmission risks, while single-use closed systems dominate hospital procurement for infection control compliance.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern US market entry, with biocompatibility testing per ISO 10993 increasingly shaping adhesive formulation decisions. The EU MDR's heightened clinical evidence requirements for Class IIa devices are forcing smaller manufacturers to consolidate or exit, concentrating share among entities with dedicated regulatory affairs infrastructure. Stakeholders must monitor reimbursement parity between institutional and home-based ostomy supply coverage, as payment policy divergence will determine where volume growth materializes.
Market Dynamics
The EU Medical Device Regulation's tightened clinical evidence requirements for Class IIa devices is restructuring competitive viability, forcing consolidation among smaller manufacturers while rewarding entities with dedicated regulatory infrastructure and captive silicone supply chains.
Growth Catalysts
- Aging demographics in Germany:The country's expanding over-65 population and established reimbursement pathways for advanced ostomy appliances sustain volume growth for skin-friendly barrier technologies.
- MDR compliance concentration:The EU Medical Device Regulation's elevated standards for adhesive biocompatibility testing per ISO 10993 is filtering out undercapitalized competitors and concentrating procurement among certified suppliers.
- Remote monitoring integration:Digital tools that track pouch fill levels and skin integrity metrics are accelerating hospital discharge protocols and expanding home care autonomy.
Market Restraints
- Medical-grade silicone price volatility:Input cost fluctuations for hydrocolloid adhesives and odor-resistant films compress margin structures for non-integrated manufacturers.
- Regulatory friction from FDA 510(k) pathways:Extended biocompatibility documentation timelines delay US market entry for novel barrier formulations.
- Substitution pressure from continent diversion procedures:Surgical alternatives that eliminate permanent stoma creation threaten long-term patient pool expansion in colorectal segments.
Strategic Opportunities
- Underpenetrated home care channels in France:Reimbursement parity gaps between institutional and domestic settings create white space for direct-to-patient distribution models.
- Convergence of wearable sensors and ostomy appliances:Integration of moisture detection and pH monitoring into skin barriers enables premium pricing for connected care ecosystems.
- Japan's PMDA fast-track designation:The regulator's priority review pathway for infection-prevention devices offers accelerated access for antimicrobial barrier technologies.
Industry Challenges
- ISO 13485 auditor scarcity:Limited availability of qualified quality management system assessors extends certification timelines for emerging manufacturers.
- Legacy ERP integration with track-and-trace mandates:EU MDR unique device identification requirements force costly supply chain software overhauls.
- Peristomal dermatitis protocol standardization:Absence of unified clinical guidelines for skin barrier selection complicates physician education and product positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ostomy Drainage Systems Market |
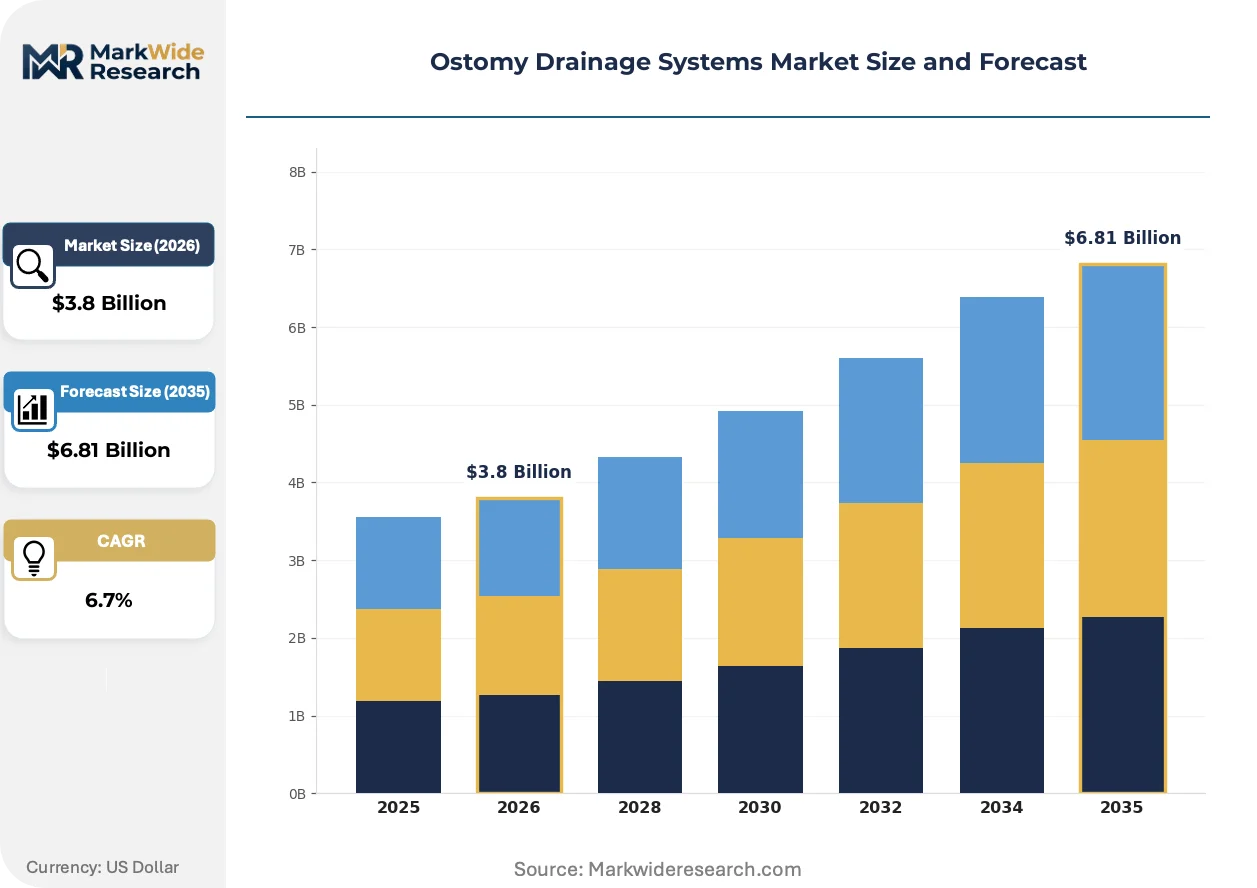
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colostomy Bags, Ileostomy Bags, Urostomy Bags, Accessories End User: Hospitals, Home Care, Long-term Care Facilities, Ambulatory Surgical Centers Technology: Single-use, Reusable, Closed System, Open System Application: Chronic Disease Management, Post-operative Care, Daily Living Support, Others |
| Companies Covered | Coloplast, ConvaTec, B. Braun Melsungen, Hollister Incorporated, Alcare Co., Ltd., Welland Medical Limited, Flexicare Medical Limited, Salts Healthcare Limited, Pelcin Healthcare Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ostomy Drainage Systems Market Evolving Landscape
Silicone-based adhesive chemistry is displacing traditional hydrocolloid formulations as the dominant interface technology, while regulatory data requirements and shifting procurement authority reshape how manufacturers compete for volume.
Advanced silicone adhesives with controlled moisture vapor transmission rates are absorbing the functional demands previously met by multi-layer hydrocolloid constructs. Home care patients with sensitive peristomal skin are adopting these formulations at accelerated change intervals. The technology is absorbing premium positioning from legacy barrier categories as hospitals prioritize skin integrity outcomes over unit cost.
The EU Medical Device Regulation's post-market surveillance mandates now require systematic clinical follow-up data for Class IIa drainage collection systems. Manufacturers must maintain vigilance systems that capture adverse event patterns across distributed patient populations. German notified bodies are applying these standards most stringently, compressing approval timelines for competitors lacking established quality infrastructure.
Hospital purchasing consortia are consolidating procurement authority for post-operative ostomy supplies under centralized formulary committees. Independent home medical equipment dealers are losing direct access to discharge planners as health systems integrate specialty distribution through owned channels. This concentration is most visible in the Netherlands, where hospital networks have captured 70 percent of initial appliance provisioning.
Ostomy Drainage Systems Market Segmentation
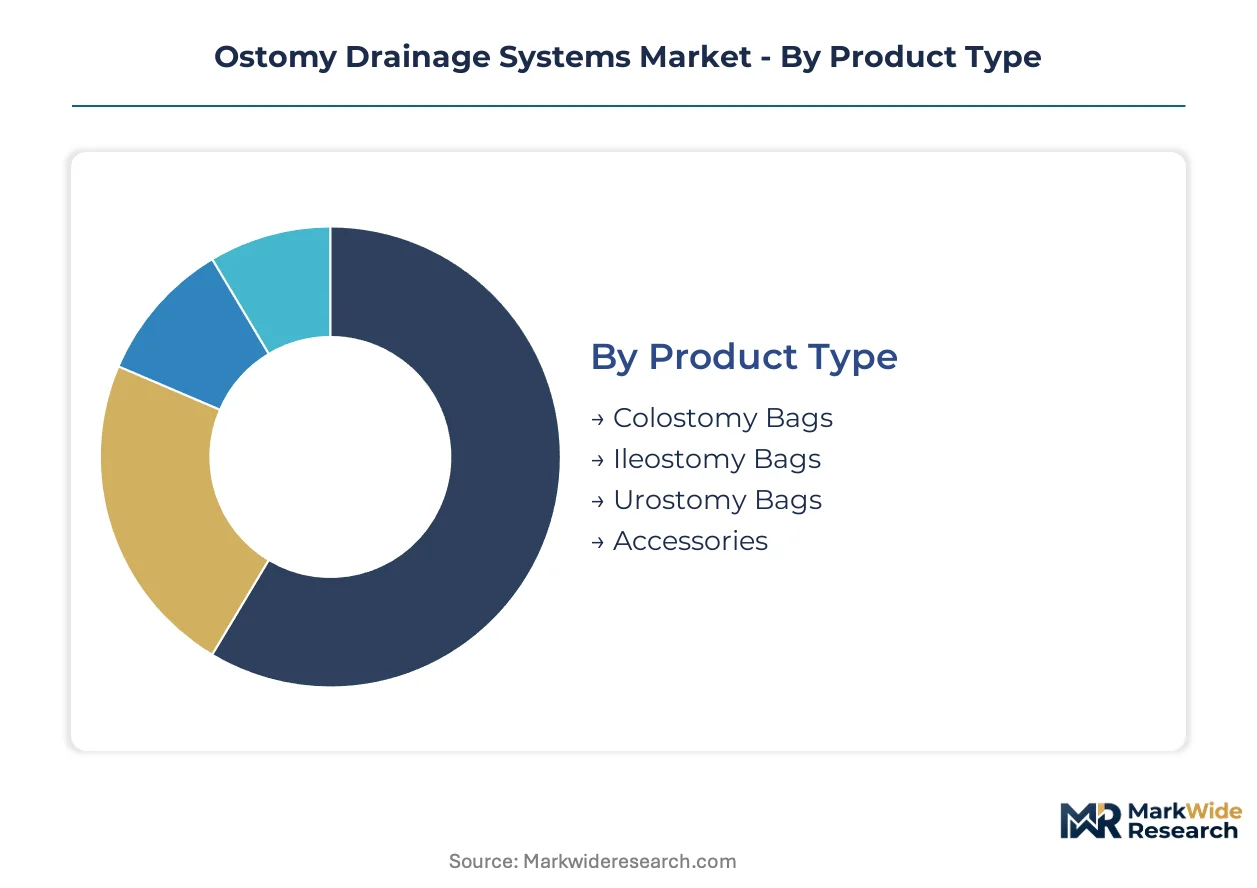
Ostomy drainage systems fragment across multiple dimensions that determine regulatory pathways, procurement authority, and margin structures. Understanding how product categories, end-user settings, and technology formats map to distinct certification requirements reveals where competitive resources generate the highest returns.
Product Type:
EU MDR Class IIa designation applies universally across this category, with ISO 10993 biocompatibility testing intensity varying by effluent chemistry and skin contact duration.
- Colostomy Bags:These one-piece and two-piece systems employ odor-resistant films with charcoal filters to manage solid and semi-solid waste from descending colon procedures. Demand concentrates in German hospital purchasing consortia where established reimbursement codes support volume procurement of skin-friendly barrier technologies.
- Ileostomy Bags:High-output designs with enhanced liquid-handling capacity and convex barriers address the more corrosive effluent from small intestine stomas. Home care settings in France and the Netherlands are absorbing accelerated change intervals as patients prioritize skin integrity outcomes over unit economics.
- Urostomy Bags:Night drainage adapters and anti-reflux valves characterize these systems for urinary diversion patients. FDA 510(k) pathways govern US market entry with extended biocompatibility timelines.
- Accessories:Skin barriers, adhesive removers, and pouch deodorants complete the appliance ecosystem. PMDA fast-track designation in Japan accelerates approval for antimicrobial variants.
Colostomy bags sit at the top of the volume ranking, with ileostomy bags climbing the fastest.
End User:
Procurement authority is migrating from decentralized clinical buyers toward centralized formulary committees with diverging technical specifications across settings.
- Hospitals:Infection control mandates drive single-use closed system procurement through integrated delivery networks. German hospital networks have captured dominant share of initial post-operative appliance provisioning.
- Home Care:Remote monitoring integration and accelerated discharge protocols are expanding patient autonomy outside institutional settings. Reimbursement parity gaps between institutional and domestic coverage create white space for direct-to-patient models in France.
- Long-term Care Facilities:Staff training requirements and formulary standardization pressures favor simplified one-piece systems with extended wear times. Netherlands nursing home chains are consolidating procurement under regional purchasing alliances.
- Ambulatory Surgical Centers:Same-day discharge protocols demand pre-packaged ostomy kits with standardized barrier sizes. Medicare reimbursement compression constrains premium product adoption in US outpatient settings.
Home care is expanding most quickly, with hospitals retaining the largest absolute procurement volumes.
Technology:
Manufacturing complexity and sterilization requirements create three distinct cost tiers that shape competitive positioning and margin capture.
- Single-use:Heat-sealed films with integrated filters dominate hospital procurement for infection prevention compliance. EU MDR unique device identification mandates force supply chain software investments.
- Reusable:Silicone-based appliances with detachable collection containers appeal to environmentally conscious home care patients in German-speaking markets. Higher upfront costs require patient education investments.
- Closed System:Integrated barrier-pouch constructs with sealed outlets minimize odor and effluent exposure. Premium positioning in Japanese acute care settings leverages PMDA infection prevention priorities.
- Open System:Drainable pouches with clip or Velcro closures allow patient-controlled emptying. Cost-sensitive procurement in Southern European long-term care facilities sustains volume demand.
Single-use systems command the highest procurement volumes, with closed systems gaining share fastest among premium-positioned offerings.
Application:
Clinical outcome metrics and reimbursement coding precision determine product selection authority across patient journey stages.
- Chronic Disease Management:Extended-wear silicone barriers with moisture vapor transmission control address peristomal dermatitis in long-duration Crohn's and ulcerative colitis patients. German sickness funds cover advanced appliances with documented skin integrity outcomes.
- Post-operative Care:Standardized one-piece systems with cut-to-fit barriers accommodate stoma size variability during initial healing. Hospital formulary committees in the Netherlands control 70 percent of initial provisioning.
- Daily Living Support:Discreet pouch designs with clothing shields and activity belts enable workforce participation and social engagement. Direct-to-patient channels in France bypass traditional home medical equipment dealers.
- Others:Pediatric adaptations and bariatric sizing address specialized anatomical requirements. Limited reimbursement codes constrain commercial development.
Post-operative care absorbs the largest procurement volumes, with chronic disease management presenting the steepest expansion trajectory as patient survival extends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ostomy drainage systems industry traces its modern scale to post-war European surgical innovation, with German and Danish manufacturers pioneering hydrocolloid adhesive technologies during the 1950s that became the foundation for today's skin barrier science.
Germany
Germany's expanding over-65 population and established sickness fund reimbursement pathways sustain volume procurement of advanced ostomy appliances. The EU MDR's clinical evidence requirements filter through German notified bodies with particular stringency, compressing approval timelines for competitors lacking dedicated quality infrastructure. Hospital purchasing consortia in the Ruhr region and Bavaria have captured dominant share of initial post-operative appliance provisioning.
United States
Medicare reimbursement compression and accelerated discharge protocols are expanding home care autonomy for ostomy patients outside institutional settings. FDA 510(k) clearance pathways govern market entry with extended biocompatibility documentation timelines that delay novel barrier formulations. Integrated delivery networks in the Midwest and Southeast are consolidating procurement authority under centralized formulary committees.
France
Reimbursement parity gaps between institutional and domestic settings create white space for direct-to-patient distribution models in the French market. ANSM oversight of Class IIa medical devices aligns with broader EU MDR conformity assessment procedures. Hospital networks in the Île-de-France region are absorbing procurement authority previously held by independent home medical equipment dealers.
Japan
PMDA fast-track designation for infection-prevention devices offers accelerated market access for antimicrobial barrier technologies in Japanese acute care settings. METI industrial policy supports domestic manufacturing of medical-grade silicone components. Production clusters in the Kansai region around Osaka supply specialized odor-resistant films to regional appliance assemblers.
Netherlands
Hospital networks have captured seventy percent of initial ostomy appliance provisioning through integrated specialty distribution channels. The Dutch national health insurer's formulary standardization pressures favor simplified one-piece systems with extended wear times. Eindhoven-region nursing home chains are consolidating procurement under regional purchasing alliances.
Ostomy Drainage Systems Market Competitive Landscape
Capital-heavy producers with captive silicone supply chains compete with asset-light designers reliant on contract manufacturing for adhesive barrier components. The market structure concentrates among vertically integrated European manufacturers and North American surgical supply conglomerates with dedicated regulatory affairs infrastructure. Three archetypes dominate: integrated material-science specialists, diversified surgical supply houses, and regional accessories fabricators. Competitive moves center on M&A consolidation to absorb regulatory compliance costs and strategic partnerships with hospital purchasing consortia to secure formulary placement.
Among the integrated material-science specialists, Coloplast anchors premium positioning through in-house silicone manufacturing capabilities. Hollister Incorporated occupies a position within the diversified surgical supply tier, leveraging distribution depth across Western European hospital networks. B. Braun Melsungen exemplifies the surgical supply conglomerate archetype, extending sterilization and aseptic processing credibility into post-operative ostomy care. These three entities represent the competitive core that smaller manufacturers must confront as EU MDR compliance costs force market exit.
| Leading Market Players |
|---|
| Coloplast |
| ConvaTec |
| B. Braun Melsungen |
| Hollister Incorporated |
| Alcare Co., Ltd. |
| Welland Medical Limited |
| Flexicare Medical Limited |
| Salts Healthcare Limited |
| Pelcin Healthcare Ltd. |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone feedstock moves from German chemical processors through three-tier pricing structures that separate premium silicone-adhesive barriers from standard hydrocolloid constructs and economy-grade PVC alternatives. Raw material cost volatility in odor-resistant films compresses margin structures at the standard tier while captive silicone supply chains defend premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ISO 10993 biocompatibility certification tier and volume scale as primary price differentiation drivers. Pricing pressure stems from Medicare reimbursement compression in US outpatient settings and sickness fund formulary constraints in Germany. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge economics, while German hospital purchasing consortia absorb premium tier costs for documented skin integrity outcomes.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade silicone resin production concentrated in Germany, Japan, and the United States. Hydrocolloid adhesives, charcoal filter layers, and odor-resistant films feed from specialized chemical processors in the Kansai region and Ruhr industrial cluster. Tariff exposure on imported silicone intermediates threatens margin stability for non-integrated assemblers. Distribution runs through hospital purchasing consortia in Western Europe and integrated delivery networks in the US Midwest, bypassing independent home medical equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ostomy drainage systems market reads as a late-cycle quality story where patient survival extension and peristomal dermatitis protocol maturation shift procurement toward premium silicone-adhesive specifications with documented clinical outcomes.
For Market Incumbents: Anticipate EU MDR compliance cost concentration by accelerating backward integration into medical-grade silicone resin production and securing notified body relationships with German regulators. Defend formulary placement through hospital system partnerships that bundle remote monitoring capabilities with barrier technologies. Channel control through owned specialty distribution networks neutralizes independent dealer displacement. For New Entrants and Emerging Players: Direct-to-patient e-commerce platforms offer lowest-friction entry into French home care channels where reimbursement parity gaps disadvantage traditional distribution. Target antimicrobial barrier accessories under Japan's PMDA fast-track pathway for infection-prevention designation. White space concentrates in connected-care ecosystems integrating moisture detection sensors with skin barriers for premium self-pay segments. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR clinical evidence requirements exceed capital reserves of mid-tier manufacturers with limited regulatory affairs infrastructure. Long-term viability favors vertically integrated material-science specialists with captive silicone supply and established quality management systems. Watch German notified body approval velocity as inflection indicator for competitive exit rates among undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa designation requires systematic clinical follow-up data captured through German notified bodies. |
| Hospital System Partnership | Integrated delivery networks in the Netherlands capture seventy percent of initial appliance provisioning through owned channels. |
| Backward Integration | In-house silicone manufacturing anchors premium positioning against commodity hydrocolloid competitors. |
| Software Companion Development | Remote monitoring tools tracking pouch fill levels accelerate hospital discharge protocols and expand home care autonomy. |
| Reimbursement Strategy | Parity between institutional and domestic coverage determines volume growth materialization in French and German markets. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, EU MDR notified body registers, and CMS Medicare reimbursement databases; and customs trade data on medical-grade silicone imports — were reconciled through bottom-up and top-down triangulation. Conversations with clinicians and regulatory affairs specialists at German and Japanese manufacturers informed barrier technology adoption assumptions.
Historical volume trajectories were cross-referenced against panel input from formulary directors and home care procurement leads across the projection horizon. The analytical framework modeled segmentation dimensions including product type (colostomy, ileostomy, urostomy), end-user setting (hospital, home care, long-term care), and technology format (single-use, reusable, closed system, open system). CAGRs were derived from demand elasticity modeling against aging demographic projections and surgical procedure volumes, with ISO 10993 biocompatibility testing intensity and MDR compliance cost curves as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for silicone-based adhesive chemistry displacing hydrocolloid formulations would alter the outlook. Forecasts reflect assumptions regarding EU MDR implementation stringency, reimbursement parity evolution, and surgical diversion procedure substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sleep Apnea Devices Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Midline Catheters Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Europe C-Arms Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Wearable Medical Robots Market