
 Compression Socks Market | 2026-2036
Compression Socks Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Socks Market Analytics
Asset-light leasing models for medical device distribution are narrowing the capital barrier for regional entrants in compression therapy. SIGVARIS GROUP leverages direct-to-clinic subscription programs to sustain recurring revenue streams. Medi GmbH and Co. KG anchors its position through captive manufacturing of medical-grade elastane blends. 3M competes by extending its industrial materials science into antimicrobial fiber coatings for hospital-grade socks.
Compression socks are elastic garments engineered with graduated pressure gradients, typically measured in millimeters of mercury (mmHg), designed to enhance venous return and reduce peripheral edema through controlled mechanical compression of the lower extremities. Graduated compression dominates clinical applications due to established reimbursement pathways, while anti-embolism variants serve immobile post-surgical populations with standardized 18 mmHg profiles. Athletes drive expansion in nylon-spandex blends engineered for moisture wicking and muscle oscillation control, whereas cotton-polyester compositions occupy the retail travel segment where comfort priorities override medical precision.
The US FDA classifies medical compression garments as Class I devices, mandating labeling accuracy for mmHg claims and biocompatibility testing for extended skin contact. Germany's CE marking under the EU MDR requires clinical evidence for therapeutic claims above 20 mmHg, elevating documentation burdens for premium manufacturers. Japan's PMDA enforces JIS standards for textile elasticity retention after repeated laundering cycles. Stakeholders must monitor evolving reimbursement thresholds for chronic venous insufficiency indications across national health systems.
Market Dynamics
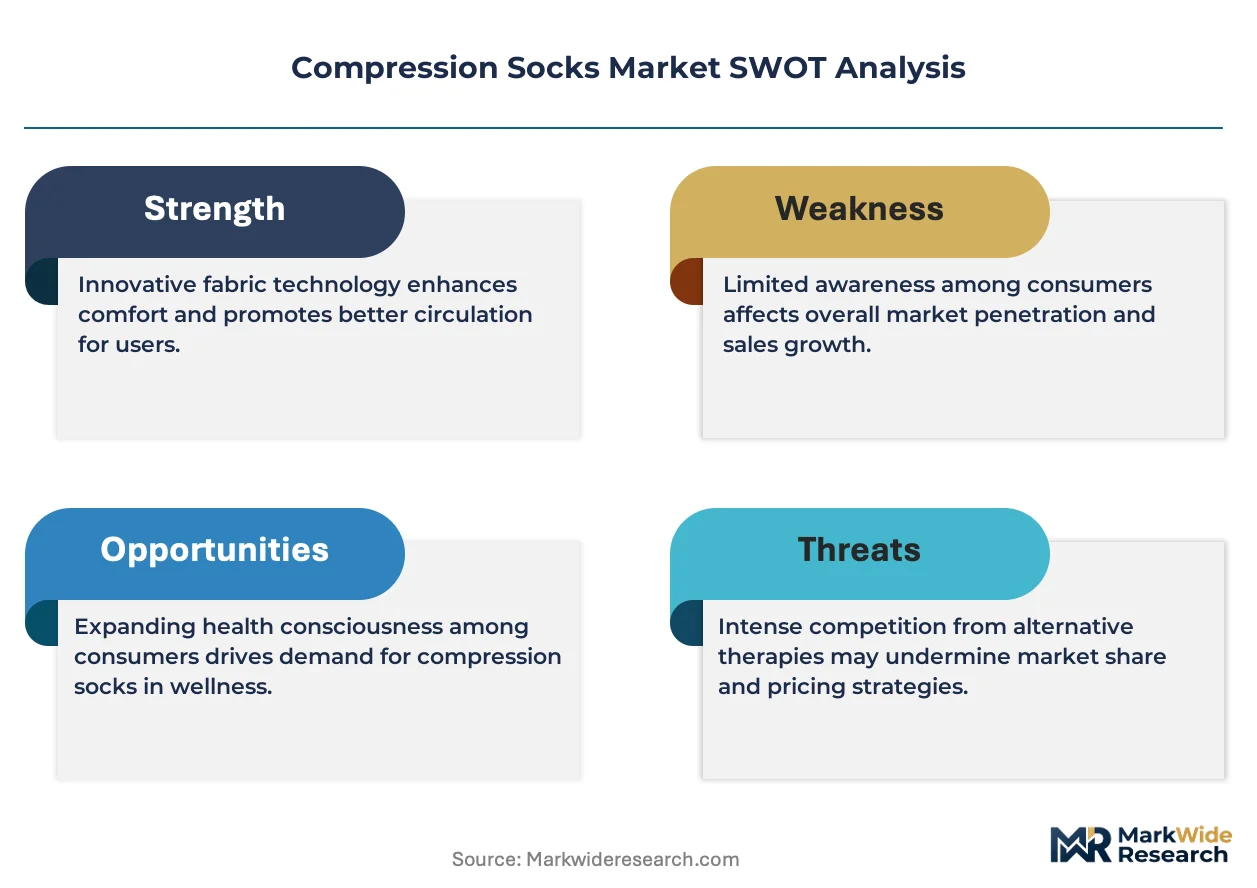
The compression socks market is experiencing structural pressure from the convergence of medical device regulation tightening and athletic performance optimization driving material science investment. This dual-force environment is compressing margins for undifferentiated manufacturers while rewarding vertically integrated specialists with captive elastane production.
Growth Catalysts
- EU MDR Clinical Evidence Requirements:Elevated documentation burdens for therapeutic claims above 20 mmHg are filtering out low-quality competitors and consolidating premium positioning among established manufacturers.
- Sports Science Validation:Circulatory benefit research is expanding athlete adoption of graduated compression for muscle oscillation control and recovery acceleration.
- German Manufacturing Clusters:Concentrated advanced production capabilities around Bauerfeind and Medi GmbH supply chains are setting quality benchmarks that penetrate export markets.
Market Restraints
- Elastane Price Volatility:Medical-grade spandex supply concentration in synthetic fiber manufacturing regions creates input cost instability for mid-tier producers.
- Reimbursement Pathway Fragmentation:Chronic venous insufficiency coverage thresholds vary across national health systems, limiting addressable market expansion for clinical-grade products.
- Cotton-Blend Substitution:Retail travel segment buyers prioritize comfort over medical precision, diverting volume toward lower-margin cotton-polyester compositions.
Strategic Opportunities
- Direct-to-Clinic Subscription Models:SIGVARIS GROUP's recurring revenue programs demonstrate scalable channel innovation bypassing traditional distributor markups.
- Antimicrobial Fiber Coatings:Hospital-grade infection control requirements are opening demand for advanced material science applications in post-surgical populations.
- Japan's JIS Standard Compliance:Textile elasticity retention mandates after repeated laundering create premium positioning for durability-tested manufacturers.
Industry Challenges
- Biocompatibility Testing Timelines:Extended skin contact validation for FDA Class I device classification delays product launch cycles.
- Graduated Pressure Calibration Expertise:Precision mmHg manufacturing requires specialized knitting machinery operation skills that concentrate in legacy textile engineering labor pools.
- Legacy Distribution Integration:Asset-light leasing models for medical device distribution demand reconfiguration of traditional wholesale relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Socks Market |
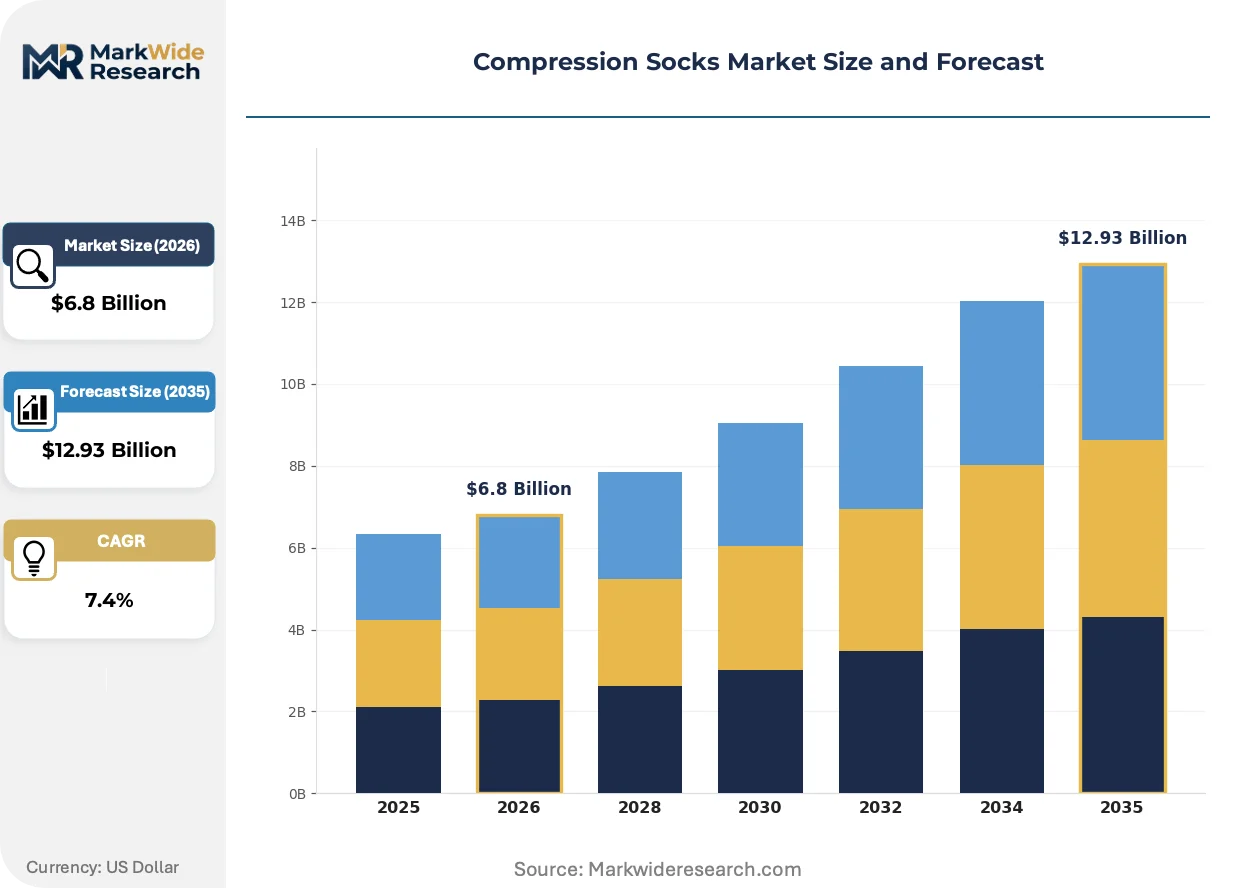
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graduated, Anti-Embolism, Compression Sleeves, Over-the-Calf End User: Athletes, Hospitals, Elderly, Travelers Material: Nylon, Spandex, Cotton, Polyester Size: Small, Medium, Large, Extra Large |
| Companies Covered | SIGVARIS GROUP, Medi GmbH and Co. KG, 3M, Thuasne, Cardinal Health, Bauerfeind, Juzo, Essity, 2XU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Socks Market Evolving Landscape
Material science convergence with digital health monitoring is collapsing traditional boundaries between passive compression garments and active biometric devices. This technological boundary erosion is redefining competitive positioning across medical and athletic segments simultaneously.
Smart textile integration with embedded pressure sensors is collapsing the distinction between diagnostic equipment and therapeutic wearables. Post-surgical monitoring facilities are piloting real-time venous return tracking through conductive fiber networks knitted directly into compression garments. This capability compression is enabling outcome-based reimbursement negotiations previously unavailable to textile manufacturers.
The EU MDR's elevated clinical evidence requirements for therapeutic claims above 20 mmHg are accelerating documentation standardization across European manufacturing. German producers with existing quality management systems are capturing disproportionate certification capacity. This regulatory compression is forcing smaller competitors toward private-label manufacturing or exit.
Athletic procurement patterns are fragmenting across direct-to-consumer digital channels and specialized sports medicine clinics simultaneously. Marathon training programs and professional cycling teams are bypassing traditional sporting goods retail for manufacturer-direct relationships with customized pressure gradient specifications. This channel disintermediation is most visible in North American and Australian endurance sports markets where performance optimization spending concentrates.
Compression Socks Market Segmentation
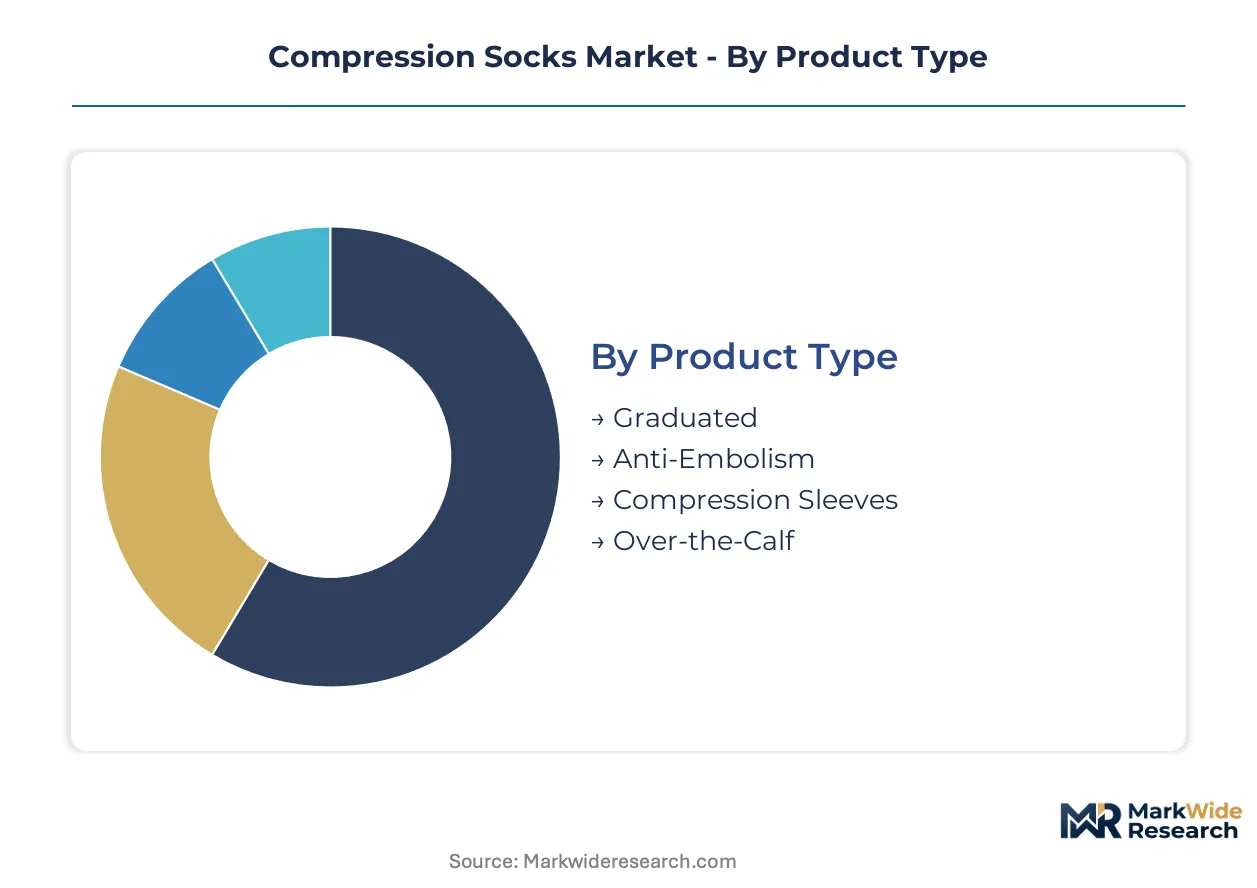
Compression sock segmentation reveals divergent margin profiles across medical certification tiers and athletic performance specifications. Cycle times vary dramatically between hospital procurement contracts and direct-to-consumer athletic channels, reshaping inventory strategies for manufacturers serving both bases.
Product Type:
Replacement cycles stretch from single-use hospital disposables to multi-year athletic investments, creating distinct cash flow rhythms across the four product formats.
- Graduated:Pressure gradients measured in mmHg deliver calibrated venous return enhancement through ankle-to-calf differential compression. Demand concentrates in German manufacturing clusters serving chronic venous insufficiency patients under EU MDR reimbursement pathways, with FDA Class I device classification tightening quality documentation burdens for export-bound producers.
- Anti-Embolism:Standardized 18 mmHg profiles target immobile post-surgical populations with uniform compression rather than graduated gradients. Hospital procurement in the US and Japan drives volume through group purchasing organizations, though JIS laundering durability standards filter out lower-tier suppliers from premium institutional contracts.
- Compression Sleeves:Calf-only coverage addresses athletic muscle oscillation control without foot encumbrance.
- Over-the-Calf:Extended length profiles serve travel and medical segments requiring full lower-leg coverage.
Graduated compression anchors the volume base while compression sleeves gain share at the steepest rate through marathon training program adoption.
End User:
Customer acquisition costs stratify sharply between institutional procurement teams and individual athletic consumers, determining channel investment priorities.
- Athletes:Nylon-spandex moisture-wicking blends engineered for muscle oscillation control dominate endurance sports procurement. Direct-to-consumer digital channels and specialized sports medicine clinics in North America and Australia bypass traditional retail, with customized pressure gradient specifications driving manufacturer-direct relationships.
- Hospitals:Post-surgical and immobile patient populations require antimicrobial fiber coatings meeting infection control protocols. SIGVARIS GROUP subscription programs demonstrate scalable recurring revenue models bypassing distributor markups, though biocompatibility testing timelines for extended skin contact delay product launch cycles.
- Elderly:Chronic venous insufficiency management drives reimbursement-dependent purchasing through Medicare and national health systems.
- Travelers:Retail comfort priorities divert volume toward cotton-polyester compositions with lower medical precision.
Hospitals anchor the volume base while athletes expand most quickly through sports science validation of circulatory benefits.
Material:
Input cost volatility concentrates in synthetic fiber supply chains, squeezing mid-tier producers while rewarding captive elastane manufacturers.
- Nylon:Moisture-wicking synthetic base dominates athletic performance engineering with durability for repeated laundering cycles.
- Spandex:Medical-grade elastane blends require specialized knitting machinery operation skills concentrated in legacy textile engineering labor pools, with price volatility in synthetic fiber manufacturing regions creating margin pressure for non-integrated producers.
- Cotton:Natural fiber comfort prioritization captures retail travel segment volume at lower price points.
- Polyester:Cost-effective synthetic alternative blends with cotton for mass-market accessibility.
Spandex anchors the volume base while nylon climbs the fastest through athletic performance optimization spending.
Size:
Fit precision requirements escalate with medical certification grade, complicating inventory management across distribution channels.
- Small:Narrow calf circumference specifications demand precise pressure gradient calibration for therapeutic efficacy.
- Medium:Standard population coverage captures baseline institutional procurement volume.
- Large:Expanded sizing accommodates demographic shifts in target patient populations.
- Extra Large:Specialized fit requirements for bariatric and edema-presenting patients command premium positioning.
Medium anchors the volume base while extra large gains share fastest through chronic disease prevalence expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chronic venous insufficiency patients and endurance athletes concentrate demand across distinct national health systems and sports medicine infrastructures. Reimbursement pathways and athletic performance spending determine regional penetration rates.
Germany
Chronic venous insufficiency prevalence drives statutory health insurance reimbursement for graduated compression above 20 mmHg. EU MDR clinical evidence requirements filter competitors through elevated documentation burdens. Manufacturing clusters around Bauerfeind and Medi GmbH in Bavaria and North Rhine-Westphalia set quality benchmarks penetrating export markets.
United States
Medicare coverage for compression therapy anchors institutional procurement volume through hospital group purchasing organizations. FDA Class I device classification mandates biocompatibility testing for extended skin contact applications. SIGVARIS GROUP operates direct-to-clinic subscription programs bypassing traditional distributor markups.
Japan
Aging demographics expand chronic disease management demand through national health insurance reimbursement. PMDA enforces JIS standards for textile elasticity retention after repeated laundering cycles. Manufacturing concentrates around Osaka-Kobe industrial zones serving domestic hospital procurement.
Australia
Endurance sports participation drives athletic compression adoption through marathon training programs and professional cycling teams. TGA regulates therapeutic claims for medical-grade products above 15 mmHg. Melbourne and Sydney anchor specialized sports medicine clinic networks facilitating manufacturer-direct relationships.
China
Hospital procurement expansion for post-surgical populations creates volume opportunities through provincial centralized purchasing platforms. NMPA medical device registration requirements concentrate supply among domestic manufacturers with established quality management systems. Yangtze River Delta textile engineering clusters supply knitting machinery expertise.
Compression Socks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin profiles and customer acquisition cost structures. The market exhibits tiered consolidation with premium medical-grade manufacturers consolidating certification capacity while athletic specialists fragment across direct-to-consumer digital channels. Three archetypes dominate: vertically integrated elastane producers with captive manufacturing, material science conglomerates extending industrial expertise into antimicrobial applications, and subscription-model distributors bypassing wholesale markups. Competitive moves concentrate on M&A for regulatory certification assets and capacity expansion in German manufacturing clusters.
Within the vertically integrated tier, Medi GmbH and Co. KG and Bauerfeind anchor positions through German manufacturing heritage and medical-grade elastane blend production. SIGVARIS GROUP exemplifies the subscription-model archetype with recurring revenue programs targeting clinic networks. These three entities represent distinct strategic approaches to channel control and manufacturing integration.
| Leading Market Players |
|---|
| SIGVARIS GROUP |
| Medi GmbH and Co. KG |
| 3M |
| Thuasne |
| Cardinal Health |
| Bauerfeind |
| Juzo |
| Essity |
| 2XU |
| Others |
Value Network & Pricing Analysis
German manufacturing clusters around Bauerfeind and Medi GmbH concentrate medical-grade elastane production, anchoring margin pools in premium certified tiers while mid-tier producers absorb volatility from synthetic fiber supply regions.
Pricing Analysis
Certification level creates the primary spread across the compression socks market, with FDA Class I and EU MDR CE marking above 20 mmHg commanding premium positioning against uncertified retail travel variants. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and reimbursement pathway access, with hospital procurement through GPOs and direct-to-clinic subscriptions reducing price sensitivity versus individual athletic consumers. Pricing pressure stems from cotton-blend substitution in the retail travel segment where comfort priorities override medical precision. Individual athletic consumers show highest price sensitivity, while institutional hospital buyers prioritize clinical evidence and durability over unit cost.
Supply Chain Analysis
Export-control regimes on advanced knitting machinery and medical-grade elastane production technology limit supply chain diversification from German and Japanese manufacturing bases. Production concentrates in Germany, Japan, and China's Yangtze River Delta textile engineering clusters, with raw material dependencies on medical-grade spandex, nylon, and antimicrobial fiber coatings. Single-source vulnerability in specialized knitting machinery operation skills concentrated in legacy textile engineering labor pools creates bottleneck risk. Distribution runs through hospital group purchasing organizations, direct-to-clinic subscription programs, and manufacturer-direct athletic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compression socks represent a service-attach opportunity as direct-to-clinic subscription models and outcome-based reimbursement negotiations expand recurring revenue faster than transactional garment sales.
For Market Incumbents: Build regulatory certification moats through accelerated EU MDR documentation and FDA biocompatibility testing investments. Consolidate German manufacturing capacity to capture disproportionate certification capacity as elevated clinical evidence requirements filter smaller competitors. Channel control through subscription programs defends against distributor disintermediation.
For New Entrants and Emerging Players: Australia's endurance sports markets show underpenetration by specialized sports medicine clinic networks facilitating manufacturer-direct relationships. Target white-space in antimicrobial fiber coatings for hospital-grade post-surgical applications where infection control protocols create premium positioning. Pursue asset-light leasing models for medical device distribution to narrow capital barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed medical device distributors lacking manufacturing integration. Long-term viability favors vertically integrated specialists with captive elastane production and established quality management systems. Watch for inflection signals in reimbursement threshold expansion for chronic venous insufficiency across national health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements above 20 mmHg filter low-quality competitors and consolidate premium positioning. |
| Direct-to-Clinic Subscription Launch | SIGVARIS GROUP's recurring revenue model demonstrates scalable channel innovation bypassing traditional distributor markups. |
| Antimicrobial Fiber Coating Development | 3M's extension of industrial materials science into hospital-grade applications addresses post-surgical infection control demand. |
| Backward Integration into Elastane | Medi GmbH's captive manufacturing of medical-grade blends insulates margin from synthetic fiber price volatility. |
| Smart Textile Sensor Integration | Embedded pressure sensor networks enable real-time venous return tracking and outcome-based reimbursement negotiations. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, sports medicine clinicians, biomedical engineers, and textile manufacturing executives and refined through secondary validation. Sources included FDA 510(k) filings, EU MDR technical documentation databases, hospital group purchasing organization contract records, and German textile engineering association reports. Bottom-up demand modeling across patient populations and athletic segments triangulated with top-down market sizing.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation by product type, end user, material composition, and certification grade. CAGRs derived from elasticity-adjusted adoption curves and reimbursement pathway expansion rates. Forecast inputs incorporated chronic venous insufficiency prevalence trajectories and endurance sports participation growth.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated elastane producers or smart textile specialists would shift outcomes. Material shifts in EU MDR enforcement stringency or Medicare reimbursement threshold adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Swab Cups Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Sequencing Consumables Market