
 Tissue Glue and Bio-Adhesive Sealants Market | 2026-2036
Tissue Glue and Bio-Adhesive Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Glue and Bio-Adhesive Sealants Market Analytics
Hospital procurement for tissue glue and bio-adhesive sealants is consolidating around integrated health systems with centralized surgical supply contracts. Baxter International Inc. leverages its global distribution infrastructure to sustain presence across major acute care networks. Johnson & Johnson anchors its competitive position through deep R&D investment in synthetic sealant platforms. B. Braun Melsungen AG differentiates via specialized hemostatic formulations tailored to cardiovascular and orthopedic applications.
Tissue glue and bio-adhesive sealants comprise biocompatible polymer formulations, fibrin-based compounds, and cyanoacrylate derivatives engineered to achieve tissue approximation, hemostasis, and barrier formation without mechanical suturing. These materials polymerize upon contact with physiological moisture, forming elastic bonds that accommodate tissue movement while maintaining sealing integrity across wound care, cardiovascular, and orthopedic interventions. Surgical adhesives occupy the largest revenue pool due to established reimbursement codes and broad procedural applicability, while hemostatic agents represent the fastest-expanding category as bleeding control protocols tighten in trauma and emergency settings. Pre-filled syringe delivery modes command premium positioning through dosing precision and reduced preparation time in operating rooms.
FDA 510(k) and PMA pathways govern U.S. market entry for sealant devices, while EMA MDR requirements enforce biocompatibility and clinical performance documentation across European markets. Japan's PMDA maintains distinct pharmacological evaluation standards for fibrin-derived products that extend registration timelines but elevate quality benchmarks. ISO 10993 biological evaluation frameworks provide harmonized toxicity testing protocols that reduce redundant study requirements across jurisdictions. Stakeholders must monitor evolving MDR transition deadlines and emerging FDA guidance on synthetic polymer degradation profiles to anticipate compliance investments and portfolio prioritization decisions.
Market Dynamics
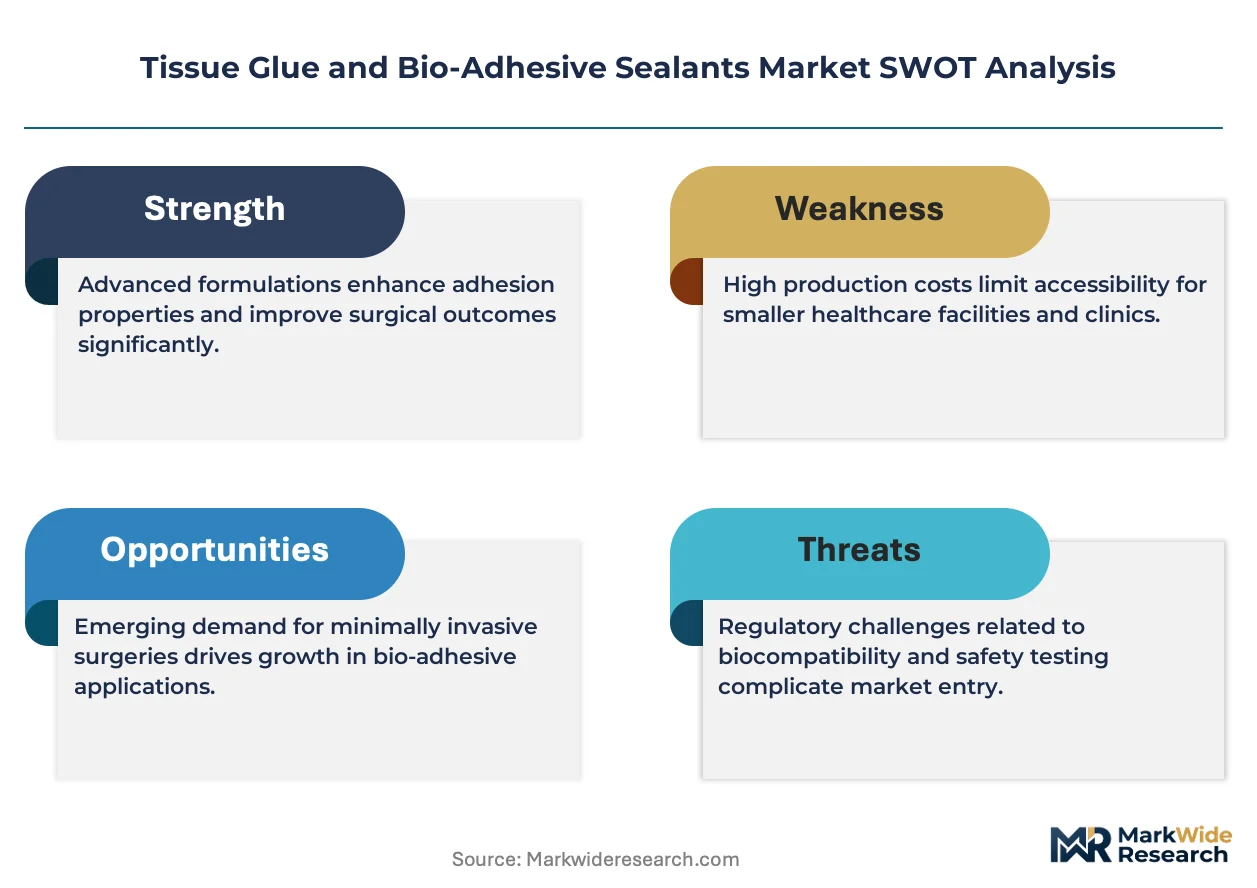
Integrated health system procurement consolidation is compressing vendor margins while elevating technical performance requirements for hemostatic and sealant formulations across acute care networks.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearance timelines for synthetic polymer sealants are enabling faster commercialization of next-generation biocompatible adhesives targeting cardiovascular applications.
- Trauma center protocol standardization:Emergency bleeding control mandates across United States Level I trauma facilities are expanding demand for rapid-polymerizing hemostatic agents in pre-hospital and surgical settings.
- Germany's surgical volume expansion:Aging demographics and orthopedic procedure growth in German hospital networks are driving concentrated procurement of fibrin-based tissue adhesives for wound closure applications.
Market Restraints
- Plasma-derived raw material volatility:Fibrinogen and thrombin sourcing from human plasma collections creates supply concentration risk and price instability for biological sealant manufacturers.
- EMA MDR compliance burden:Extended clinical evaluation requirements and notified body capacity constraints are elongating registration timelines for novel sealant devices entering European markets.
- Synthetic cyanoacrylate performance limitations:Tissue toxicity concerns and brittleness in dynamic wound environments restrict application scope for non-biological adhesive alternatives.
Strategic Opportunities
- Pediatric surgical applications:Underpenetrated neonatal and pediatric cardiac repair segments present white space for biocompatible sealants with enhanced elasticity and resorption profiles.
- Japan PMDA quality premium:Extended pharmacological evaluation pathways for fibrin products create competitive differentiation for manufacturers achieving PMDA registration ahead of rivals.
- Ambulatory surgical center channel expansion:Outpatient procedure migration in United States healthcare delivery is opening direct-to-facility distribution models bypassing traditional hospital supply chains.
Industry Challenges
- Biopolymer formulation expertise scarcity:Limited talent pools combining polymer chemistry and surgical application knowledge constrain R&D velocity for specialized hemostatic development teams.
- ISO 10993 testing timeline compression:Biological evaluation study requirements for cytotoxicity and sensitization create certification bottlenecks that delay product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Glue and Bio-Adhesive Sealants Market |
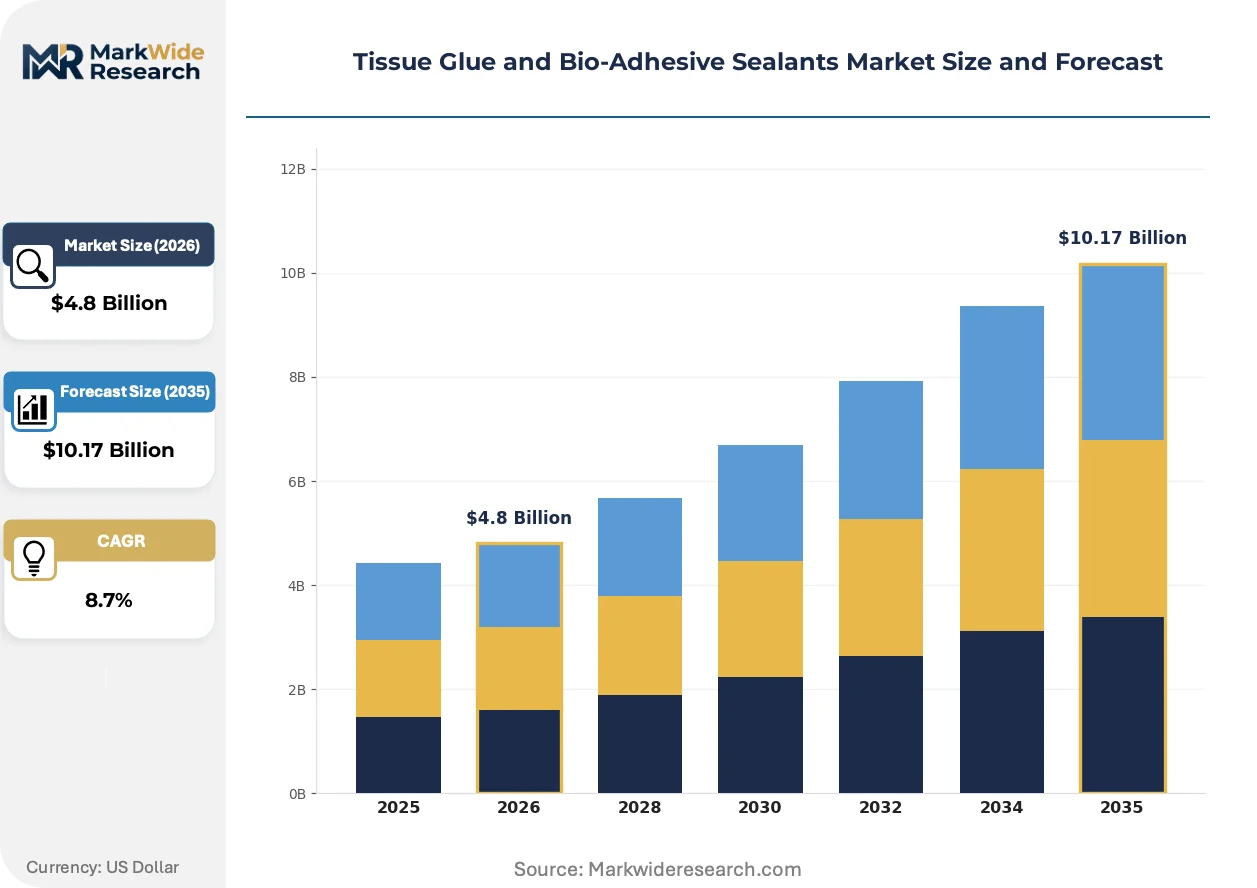
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Adhesives, Tissue Sealants, Hemostatic Agents, Adhesive Products Therapy Area: Wound Care, Orthopedics, Cardiovascular, Neurology End User: Hospitals, Surgical Clinics, Ambulatory Surgical Centers, Emergency Services Delivery Mode: Topical Application, Spray Application, Injection, Pre-filled Syringe |
| Companies Covered | C.R. Bard, Cohera Medical, Inc., B. Braun Melsungen AG, Integra LifeSciences, Luna Innovations Incorporated, Johnson & Johnson, Chemence Medical, Inc., Tissuemed Ltd., Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Glue and Bio-Adhesive Sealants Market Evolving Landscape
Biomaterial convergence with minimally invasive delivery systems is redefining performance benchmarks for tissue approximation across cardiovascular, orthopedic, and trauma interventions.
Photocurable hydrogel sealants engineered from polyethylene glycol derivatives are achieving controlled polymerization through endoscopic light delivery. Academic medical centers in Germany and Japan are piloting these formulations for laparoscopic procedures where suture access remains restricted. The technology is absorbing market share from conventional fibrin sealants in procedures demanding precise dosing and rapid tissue integration.
EMA Medical Device Regulation transition deadlines are forcing portfolio rationalization among sealant manufacturers with legacy CE certificates. Companies must resubmit technical documentation under strengthened biocompatibility and clinical performance standards. Synthetic polymer categories face the heaviest documentation burden, driving some manufacturers to deprioritize European market entry.
Hospital supply chain directors are consolidating vendor relationships around integrated service contracts bundling sealants, hemostats, and delivery devices. This purchasing model displaces fragmented product-by-product procurement across United States health systems. Cardiovascular service lines exhibit the most pronounced concentration, with single-source agreements covering entire adhesive and sealant portfolios.
Tissue Glue and Bio-Adhesive Sealants Market Segmentation
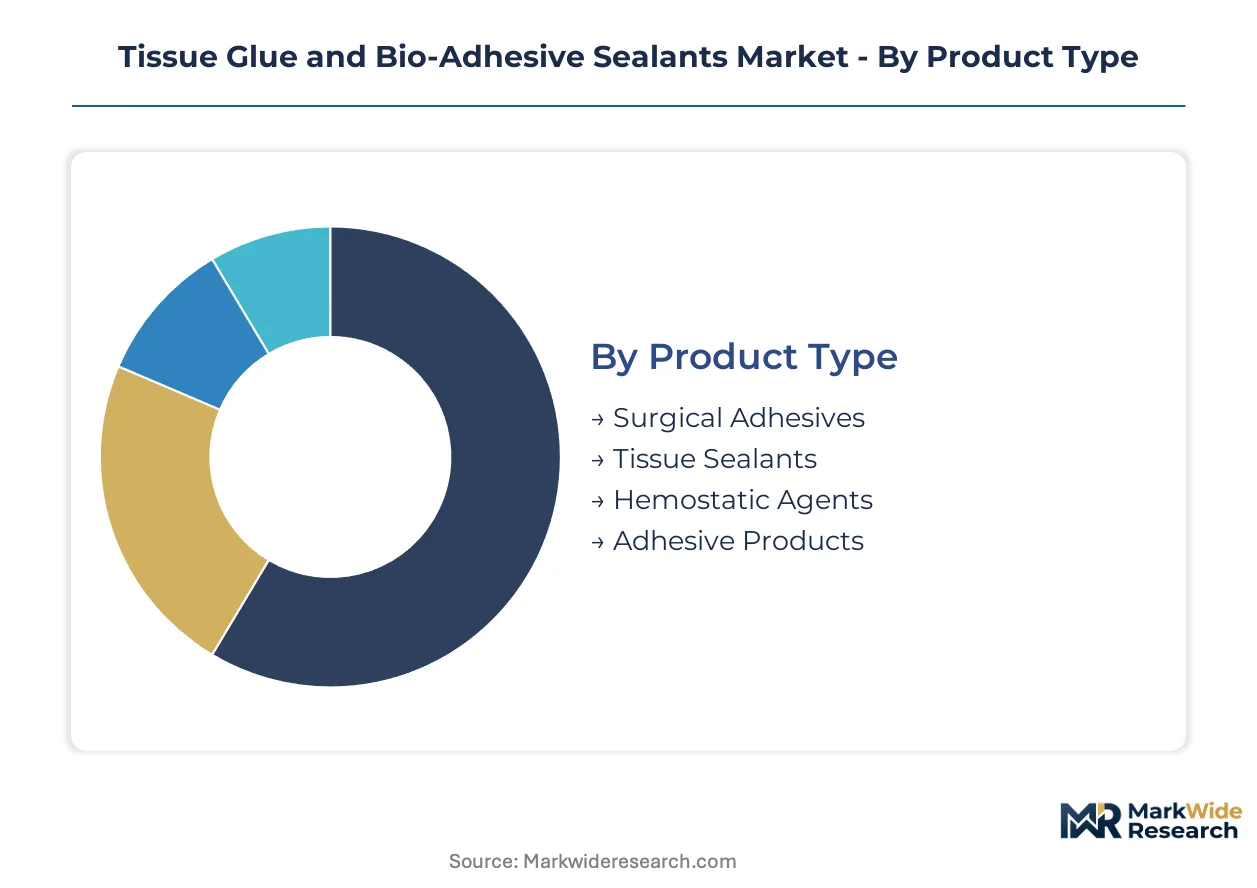
Segmentation in the tissue glue and bio-adhesive sealants market reveals distinct procurement patterns across clinical settings and therapeutic applications. Product type and delivery mode configurations determine reimbursement pathways, while therapy area specialization dictates formulation requirements and regulatory classification.
Product Type:
Volume concentration clusters around established surgical adhesives with broad procedural codes, while premium positioning attaches to specialized hemostatic agents with demonstrated efficacy in bleeding control protocols.
- Surgical Adhesives:Cyanoacrylate and fibrin-based formulations engineered for tissue approximation across general surgery and wound closure applications. Demand concentrates in United States hospital networks where established CPT codes streamline procurement workflows for cardiovascular and orthopedic service lines.
- Hemostatic Agents:Rapid-polymerizing biologics and synthetic compounds targeting acute bleeding control in trauma and emergency surgical settings. German trauma centers and United States Level I facilities are expanding procurement of these agents as bleeding control mandates tighten across emergency protocols.
- Tissue Sealants:Elastic polymer barriers preventing fluid leakage in lung and dural repair procedures.
- Adhesive Products:General-purpose bonding agents for superficial wound management and dermatological applications.
Mature deployment sits with Surgical Adhesives. Newer deployment is concentrated in Hemostatic Agents.
Therapy Area:
Application concentration follows surgical volume distribution, with cardiovascular and orthopedic procedures commanding specialized formulation performance standards.
- Cardiovascular:High-strength sealants withstanding dynamic tissue movement in cardiac and vascular repair. United States academic medical centers and German hospital networks are standardizing procurement of elastic, resorbable formulations for coronary artery bypass and aortic procedures.
- Wound Care:Broad-spectrum adhesives for incision closure and topical barrier formation across general surgery. Ambulatory surgical centers in the United States are expanding adoption of spray-application sealants for superficial wound management.
- Orthopedics:Load-bearing adhesives for tendon and ligament repair with enhanced tensile strength profiles.
- Neurology:Specialized dural sealants preventing cerebrospinal fluid leakage with minimal inflammatory response.
Established clinical validation sits with Wound Care. Steepest expansion trajectory is emerging in Cardiovascular.
End User:
Procurement authority concentrates in integrated health systems, with ambulatory channels gaining direct purchasing autonomy as surgical migration accelerates.
- Hospitals:Centralized surgical supply contracts covering comprehensive sealant portfolios across service lines. United States health systems and German hospital networks are consolidating vendor relationships around bundled adhesive and hemostat agreements.
- Ambulatory Surgical Centers:Outpatient facilities with direct procurement authority for procedure-specific sealant configurations. United States ASCs are bypassing traditional hospital supply chains through direct-to-facility distribution models.
- Surgical Clinics:Specialized outpatient facilities with focused procurement for ophthalmic and dermatological adhesive applications.
- Emergency Services:Pre-hospital and trauma bay deployment of rapid-acting hemostatic agents for bleeding control.
Contract maturity sits with Hospitals. Procurement autonomy is shifting fastest to Ambulatory Surgical Centers.
Delivery Mode:
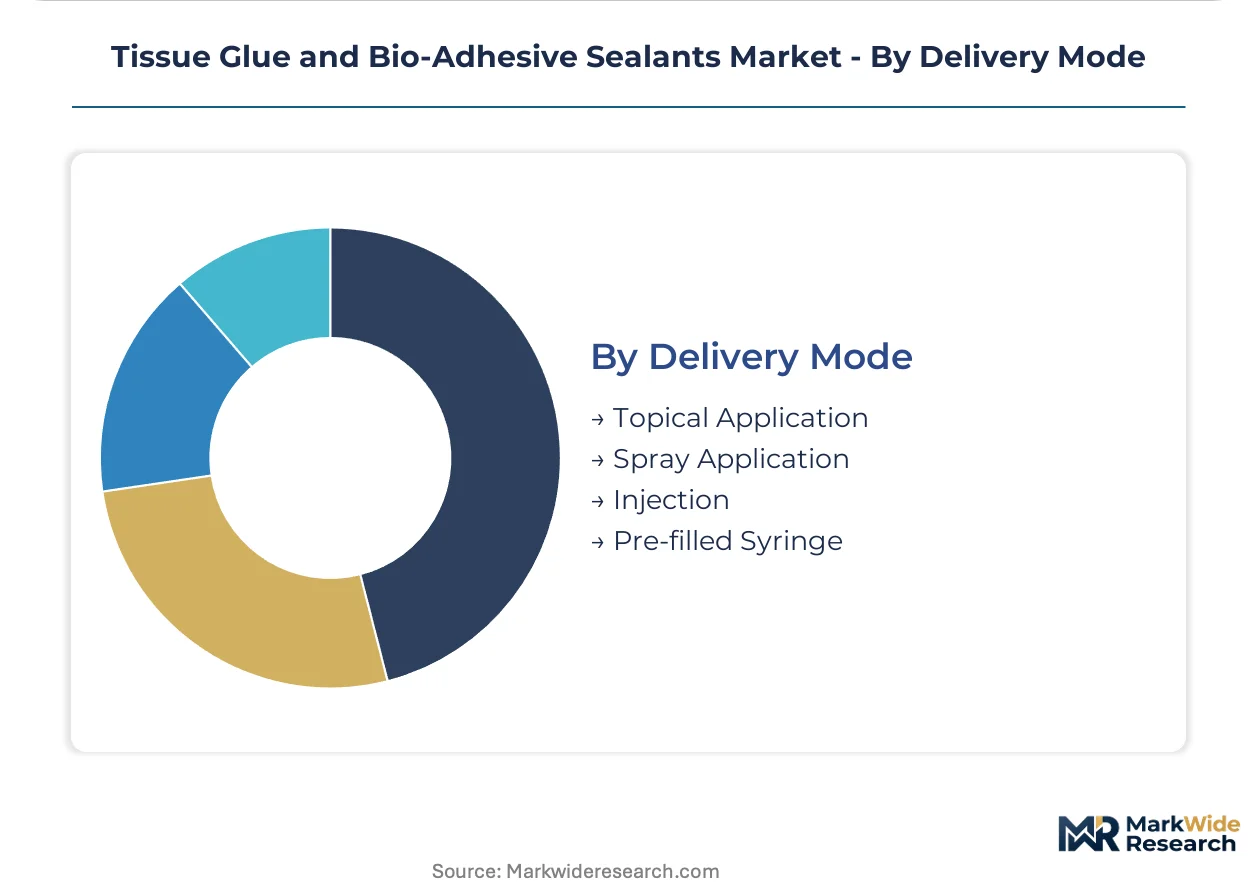
Precision requirements in minimally invasive procedures are elevating pre-filled and spray configurations over conventional topical application.
- Pre-filled Syringe:Unit-dose configurations ensuring dosing accuracy and reduced operating room preparation time. German and Japanese surgical centers are standardizing these formats for laparoscopic and robotic-assisted procedures.
- Spray Application:Aerosolized delivery enabling uniform coverage across irregular wound surfaces. United States trauma centers are expanding procurement for emergency bleeding control in penetrating injury protocols.
- Topical Application:Direct brush or spatula application for superficial wound closure and dermatological procedures.
- Injection:Catheter-delivered formulations for endoscopic and percutaneous sealant deployment.
Operational familiarity sits with Topical Application. Technical adoption is climbing fastest in Pre-filled Syringe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for tissue glue and bio-adhesive sealants concentrates in the United States, Germany, and Japan where aging demographics and surgical volume expansion drive procurement. Hospital networks in these markets are consolidating vendor relationships around integrated adhesive and hemostat contracts. Regulatory pathways in each geography shape product development priorities and commercialization timelines.
United States
Level I trauma centers and academic medical centers in the United States are expanding procurement of rapid-polymerizing hemostatic agents under emergency bleeding control mandates. FDA 510(k) pathway acceleration for synthetic polymer sealants is compressing commercialization timelines for cardiovascular applications. The Cleveland Clinic and Mayo Clinic networks are standardizing elastic, resorbable formulations for cardiac and vascular repair procedures.
Germany
German hospital networks are driving concentrated procurement of fibrin-based tissue adhesives as orthopedic procedure volumes expand with population aging. EMA MDR transition deadlines are forcing portfolio rationalization among sealant manufacturers with legacy CE certificates. The Rhine-Ruhr metropolitan region hosts dense clusters of cardiovascular service lines bundling sealant procurement under single-source agreements.
Japan
Japanese surgical centers are standardizing pre-filled syringe delivery formats for laparoscopic and robotic-assisted procedures. PMDA maintains distinct pharmacological evaluation standards for fibrin-derived products that extend registration timelines but elevate quality benchmarks. Tokyo and Osaka metropolitan areas are piloting photocurable hydrogel sealants for minimally invasive interventions where suture access remains restricted.
United Kingdom
NHS procurement frameworks are consolidating surgical supply contracts around integrated adhesive and hemostat portfolios across acute care trusts. MHRA alignment with EMA MDR requirements is enforcing strengthened biocompatibility documentation for novel sealant devices. London and Manchester hospital networks are expanding adoption of spray-application sealants for emergency bleeding control protocols.
Switzerland
Swiss university hospitals are driving demand for specialized dural sealants in neurology applications with minimal inflammatory response requirements. Swissmedic maintains rigorous clinical performance standards that create competitive differentiation for manufacturers achieving registration. The Basel and Zurich medical clusters are advancing development of next-generation biocompatible polymers for cardiovascular repair.
Tissue Glue and Bio-Adhesive Sealants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized hemostatic formulations and minimally invasive delivery technologies. The market structure reflects moderate consolidation around diversified medical device conglomerates with global distribution infrastructure. Three archetypes dominate: integrated health system suppliers with bundled contract capabilities, specialized hemostatic formulators targeting cardiovascular and orthopedic niches, and synthetic polymer innovators pursuing next-generation biocompatibility profiles. Competitive dynamics center on strategic partnerships with academic medical centers and capacity expansion in pre-filled syringe manufacturing.
Among diversified medical technology conglomerates, Baxter International Inc., Johnson & Johnson, and B. Braun Melsungen AG exemplify the integrated supplier archetype with health system contract penetration. These entities occupy positions spanning surgical adhesive, hemostatic agent, and delivery device portfolios. Cohera Medical, Inc. and Tissuemed Ltd. represent specialized formulators with concentrated expertise in biocompatible polymer development. C.R. Bard and Integra LifeSciences sit within the wound closure and surgical sealant segment with established reimbursement code access. Luna Innovations Incorporated and Chemence Medical, Inc. anchor positions in advanced material science applications for tissue approximation.
| Leading Market Players |
|---|
| C.R. Bard |
| Cohera Medical, Inc. |
| B. Braun Melsungen AG |
| Integra LifeSciences |
| Luna Innovations Incorporated |
| Johnson & Johnson |
| Chemence Medical, Inc. |
| Tissuemed Ltd. |
| Baxter International Inc. |
| Others |
Value Network & Pricing Analysis
Plasma-derived fibrinogen pricing volatility cascades through tissue sealant manufacturing into tiered procurement contracts across United States health systems and German hospital networks. Raw material concentration in biological feedstock collections creates asymmetric cost pass-through to synthetic polymer alternatives.
Pricing Analysis
Volume concentration in surgical adhesives compresses margins while hemostatic agents retain premium positioning through demonstrated efficacy in trauma protocols. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-registered fibrin formulations from FDA 510(k) synthetic alternatives and commodity cyanoacrylate derivatives. Cost compression in standard-tier biological sealants is intensifying because plasma collection bottlenecks constrain fibrinogen supply elasticity. Ambulatory surgical centers exhibit highest price sensitivity due to direct procurement autonomy, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA evaluation pathways are reshaping sourcing toward local plasma collection networks and regional polymer synthesis facilities. Manufacturing concentration clusters in the United States, Germany, and Switzerland, with critical dependence on human plasma collections, recombinant thrombin production, and medical-grade polymer resin supply. Single-source vulnerability in plasma-derived raw materials creates procurement risk during collection disruptions. Distribution runs through integrated health system contracts and direct-to-facility models for ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma collection capacity constraints prop pricing power for manufacturers with secured biological feedstock agreements. Supply scarcity in fibrin-derived formulations sustains margin premiums across the analysis window.
For Market Incumbents: Cement health system contract renewal rates through backward integration into plasma collection networks and captive thrombin production. Synthetic polymer entrants threaten biological sealant market share through FDA 510(k) pathway acceleration. Capacity addition in United States plasma fractionation facilities represents the critical defensive lever against raw material volatility. For New Entrants and Emerging Players: Launch via direct-to-ambulatory-surgical-center distribution models bypassing consolidated hospital supply chains. Pediatric cardiac repair applications present the most penetrable white space due to unmet elasticity requirements in neonatal tissue approximation. Photocurable hydrogel platforms offer the strongest go-to-market angle through academic medical center pilot partnerships in Germany and Japan. For Investors and Strategic Acquirers: The window for entry favors specialized hemostatic formulators with PMDA registration traction ahead of MDR compliance deadlines. Long-term viability rests on biopolymer formulation expertise scarcity constraining competitive replication. Watch EMA notified body capacity constraints as the signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Registration Pathway | Extended Japanese pharmacological evaluation creates quality differentiation against FDA 510(k) rivals. |
| Plasma Collection Integration | Backward control over fibrinogen supply secures raw material cost stability for biological sealant portfolios. |
| Pre-filled Syringe Manufacturing Scale-Up | Capacity expansion in unit-dose formats captures minimally invasive procedure migration in German and Japanese surgical centers. |
| Photocurable Hydrogel Platform Development | Endoscopic light-delivery technology displaces conventional fibrin sealants in laparoscopic applications. |
| Hospital System Partnership | Integrated contract penetration bundles sealants, hemostats, and delivery devices across cardiovascular service lines. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and regulatory submission records underwrites the qualitative findings. Primary interviews with cardiovascular surgeons, trauma center supply directors, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, PMDA pharmacological evaluation standards, and ISO 10993 biological evaluation protocols. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across surgical volume expansion, regulatory pathway acceleration, and raw material supply elasticity informed the analytical framework. Segmentation dimensions modeled include product type, therapy area, end user configuration, and delivery mode complexity across the projection horizon. CAGRs derived from procedure volume trajectories, pricing tier migration patterns, and reimbursement code expansion timelines. Plasma collection growth rates and polymer formulation R&D velocity served as industry-specific forecast inputs.
Regulatory pathway delays, plasma supply disruptions, and MDR notified body capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding surgical migration trends and biocompatibility standard evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Trauma Products Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Wash Bottle Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Tongue Depressors Market