
 OTC Braces and Supports Market | 2026-2036
OTC Braces and Supports Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Braces and Supports Market Analysis
Medical-grade compression specifications and CE-marked performance tiers is redrawing competitive boundaries in consumer orthopedics. DJO Global leverages its rehabilitation technology heritage to dominate professional sports channels. Bauerfeind sustains German engineering credibility through anatomical precision and medical-grade neoprene formulations. Essity competes via mass retail scale and pharmacy shelf presence across European markets.
OTC braces and supports are non-prescription orthopedic devices constructed from neoprene, woven elastic, thermoformable plastics, or composite fabrics, designed to stabilize joints, redistribute load, and limit pathological range of motion without surgical intervention. Knee braces generate the largest revenue pool due to high incidence of ligament and meniscal conditions among active populations. Ankle supports represent the fastest-expanding category as trail running and court sports drive repeat purchases among younger consumers. Online retail channels capture margin pools through direct-to-consumer sizing tools and subscription replenishment models that bypass traditional pharmacy markups.
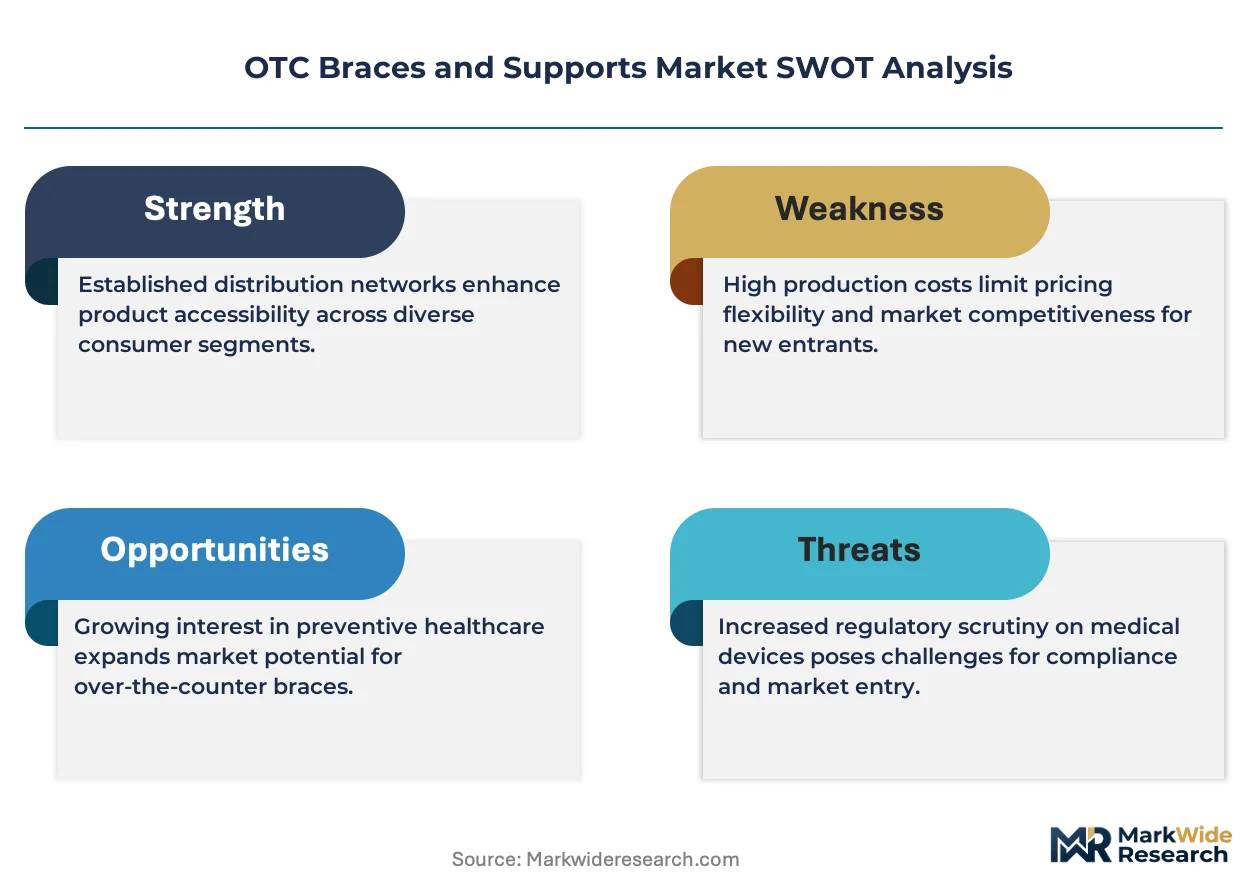
FDA 510(k) submissions govern Class I and II device clearances in the United States, while the EU MDR and CE marking requirements impose clinical evidence standards that filter lower-quality imports from European markets. ISO 13485 quality management certification shapes supplier eligibility for private-label contracts with major pharmacy chains. Stakeholders must monitor how regulatory divergence between FDA substantial equivalence and MDR clinical evaluation pathways affects portfolio rationalization and market entry sequencing.
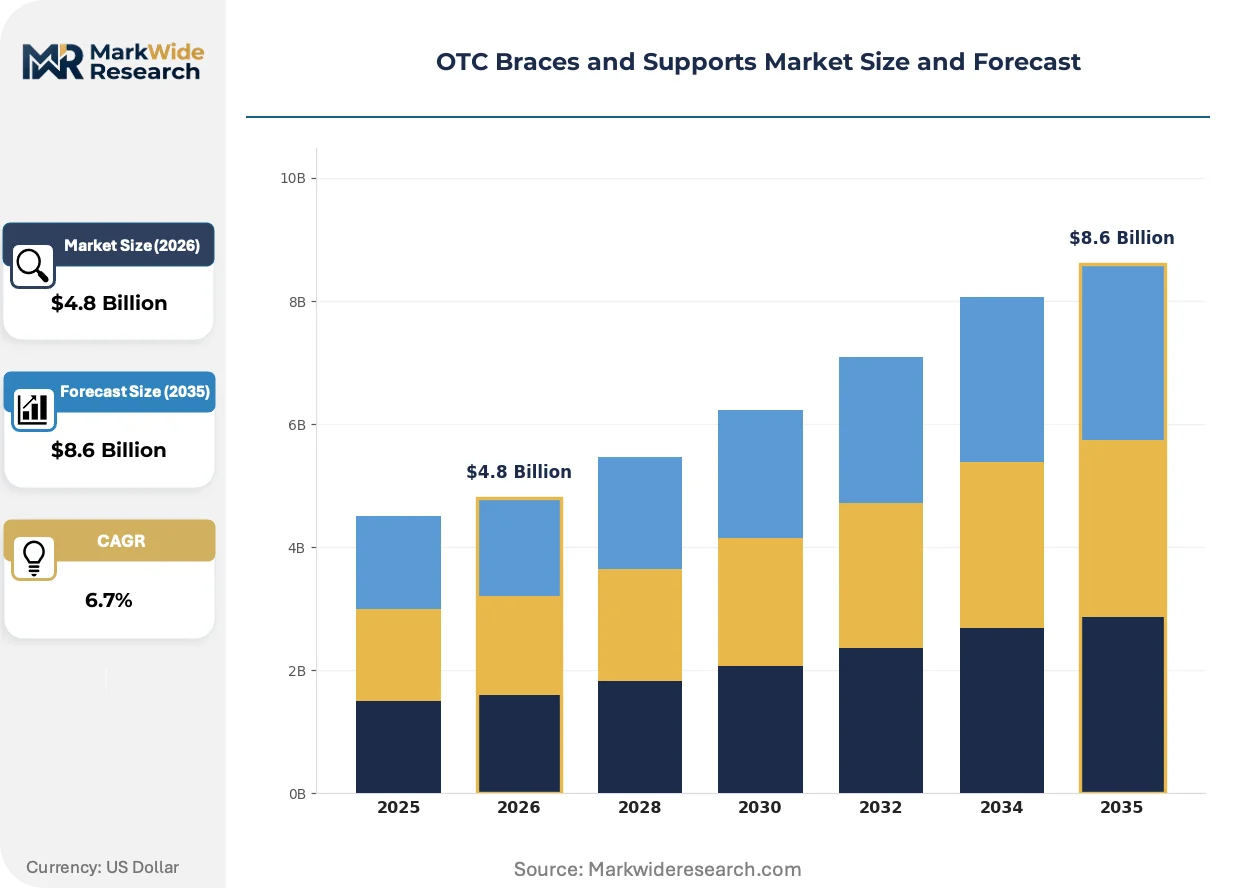
Market Dynamics
EU MDR clinical evaluation requirements are compressing supplier eligibility for European distribution while FDA 510(k) substantial equivalence maintains lower barriers in the United States, creating divergent portfolio rationalization pressures for orthopedic device manufacturers.
Growth Catalysts
- Active aging demographics:Germany, Japan, and the United States exhibit expanding populations over 65 seeking self-managed joint stabilization without surgical referral.
- ISO 13485 certification:Quality management mandates from pharmacy chains and hospital procurement departments are filtering out uncertified private-label competitors.
- Court sports participation:Basketball and volleyball leagues in China and Brazil drive repeat ankle support purchases among athletes aged 18-35.
Market Restraints
- Neoprene price volatility:Petrochemical feedstock fluctuations compress margins for manufacturers dependent on synthetic rubber formulations.
- EU MDR compliance costs:Clinical evidence requirements for CE marking under the 2017/745 regulation block lower-tier Asian suppliers from European market entry.
- Rigid brace substitution:Custom-fabricated orthotics from hospital-based prosthetics departments capture complex trauma cases.
Strategic Opportunities
- Telehealth-integrated sizing:Remote physiotherapy platforms in Australia and Canada create demand for direct-to-consumer measurement tools and subscription replenishment.
- Biodegradable composites:PLA-based thermoformable plastics converge with compostable packaging mandates in France and the Netherlands.
- Pharmacy automation:Robotic dispensing systems in UK and German retail chains open shelf-space for standardized SKUs with barcode-integrated inventory tracking.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized expertise in anatomical load distribution and CAD-based brace design concentrates in Munich, Boston, and Zurich clusters.
- MDR technical documentation timelines:Clinical evaluation report preparation extends certification cycles to 18-24 months for novel hinge mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Braces and Supports Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Braces, Ankle Supports, Wrist Supports, Back Supports Application: Injury Recovery, Pain Relief, Stability Enhancement, Posture Correction Material: Neoprene, Fabric, Plastic, Elastic Distribution Channel: Online Retail, Pharmacies, Sports Stores, Supermarkets |
| Companies Covered | 3M Company, DJO Global, Zimmer Biomet, Bauerfeind, Essity, Össur, Ottobock, Breg, DeRoyal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Braces and Supports Market Emerging Trajectories
Material science advances and regulatory divergence are fragmenting competitive positioning between premium medical-grade tiers and mass-market commodity offerings.
3D-printed lattice structures is bifurcating the performance brace segment from traditional thermoformed plastic shells. Professional sports medicine clinics in Germany and the United States are adopting patient-specific geometries for post-surgical rehabilitation. This customization capability is compressing margins for standardized off-the-shelf alternatives in the premium tier.
EU MDR Annex XIV clinical evaluation requirements are elevating evidence standards for Class IIa orthopedic devices. Manufacturers must now submit post-market surveillance data and risk management files that exceed previous Medical Device Directive thresholds. Knee brace categories with hinge mechanisms face the steepest compliance burden, forcing portfolio consolidation among mid-tier European suppliers.
Subscription-based replenishment models are displacing single-unit pharmacy purchases for compression wear and elastic supports. Direct-to-consumer platforms bypass traditional wholesale markups while capturing recurring revenue from athletic and geriatric segments. This channel shift is most visible in United States and United Kingdom markets where Amazon and specialized orthopedics sites aggregate sizing algorithms with automated refill scheduling.
OTC Braces and Supports Market Segmentation
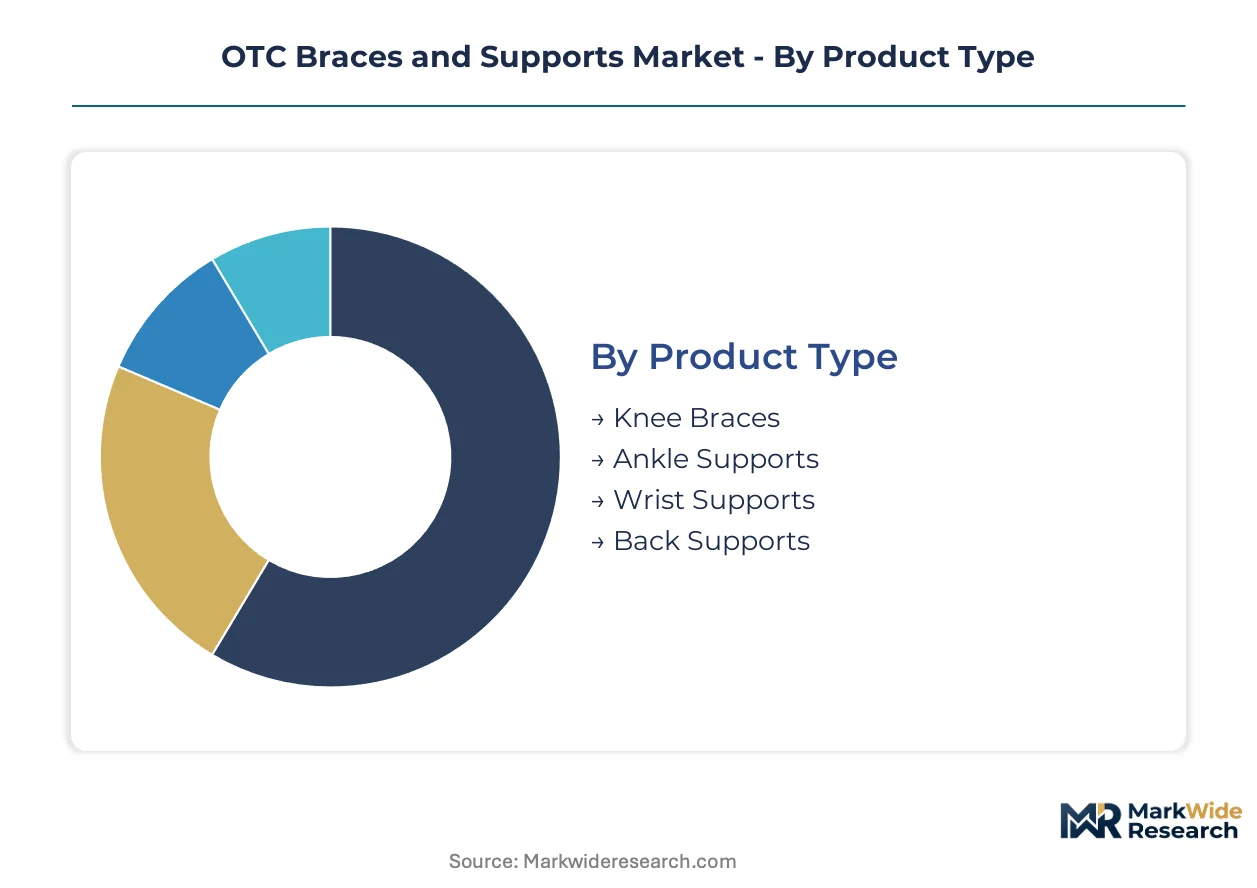
Segmentation in the OTC braces and supports market reveals distinct margin architectures across product tiers and channel structures. Manufacturers optimize portfolio mix by aligning material specifications with regulatory pathways and end-use price elasticity.
Product Type:
Margin pools concentrate in hinge-equipped mechanical braces where FDA 510(k) clearance and CE marking under EU MDR create certification premiums.
- Knee Braces:Hinge mechanisms and adjustable ROM controls fabricated from aluminum alloys and medical-grade polymers command premium positioning in post-surgical rehabilitation. Demand concentrates in Germany and the United States where sports medicine clinics specify ligament-stabilizing configurations for ACL recovery protocols.
- Ankle Supports:Lace-up and stirrup designs using woven elastic and semi-rigid thermoplastic shells dominate court sports procurement. China and Brazil drive volume through basketball and volleyball league replenishment cycles among athletes aged 18-35.
- Wrist Supports:Splint-style and wrap configurations address carpal tunnel and repetitive strain conditions in office-worker demographics across Japan and the United Kingdom.
- Back Supports:Corset and belt designs with integrated stays target manual labor sectors and aging populations seeking lumbar stabilization without surgical referral.
Knee braces hold installed capacity. Ankle supports is rotating up the share rankings.
Application:
Volume distribution tracks injury incidence patterns and self-care behavioral shifts across active aging and athletic cohorts.
- Injury Recovery:Post-traumatic stabilization following ligament tears and fractures requires medical-grade compression specifications and anatomical precision. Germany's rehabilitation clinics and United States orthopedic practices specify CE-marked and FDA-cleared devices for insurance reimbursement eligibility.
- Pain Relief:Compression-based solutions for osteoarthritis and chronic joint inflammation target Medicare-eligible populations in Japan and the United States where self-managed care reduces specialist consultation frequency.
- Stability Enhancement:Prophylactic bracing in competitive sports and occupational settings drives repeat purchase behavior among construction workers and trail runners in Australia and Canada.
- Posture Correction:Thoracic and lumbar support garments address sedentary workforce ergonomics in United Kingdom and Netherlands corporate wellness programs.
Injury recovery commands the steepest pricing tier. Pain relief is gaining share fastest through pharmacy automation and direct-to-consumer channels.
Material:
Cost structures bifurcate between petrochemical-dependent synthetics and emerging biodegradable alternatives responding to EU packaging mandates.
- Neoprene:Synthetic rubber formulations deliver compression consistency and thermal retention for athletic and medical applications. Price volatility in petrochemical feedstocks compresses margins for manufacturers dependent on chloroprene supply chains.
- Fabric:Woven cotton-polyester blends and moisture-wicking textiles target comfort-sensitive consumers in tropical climates and extended-wear scenarios.
- Plastic:Thermoformable polyethylene and polypropylene shells enable rigid stabilization for trauma cases, with 3D-printed lattice structures emerging in Munich and Boston sports medicine clusters.
- Elastic:Woven elastane and rubber-core bandages provide adjustable compression for mild sprains and preventive use in mass retail price tiers.
Neoprene retains the largest installed base. Fabric compositions are climbing the fastest as sustainability preferences reshape procurement specifications in France and the Netherlands.
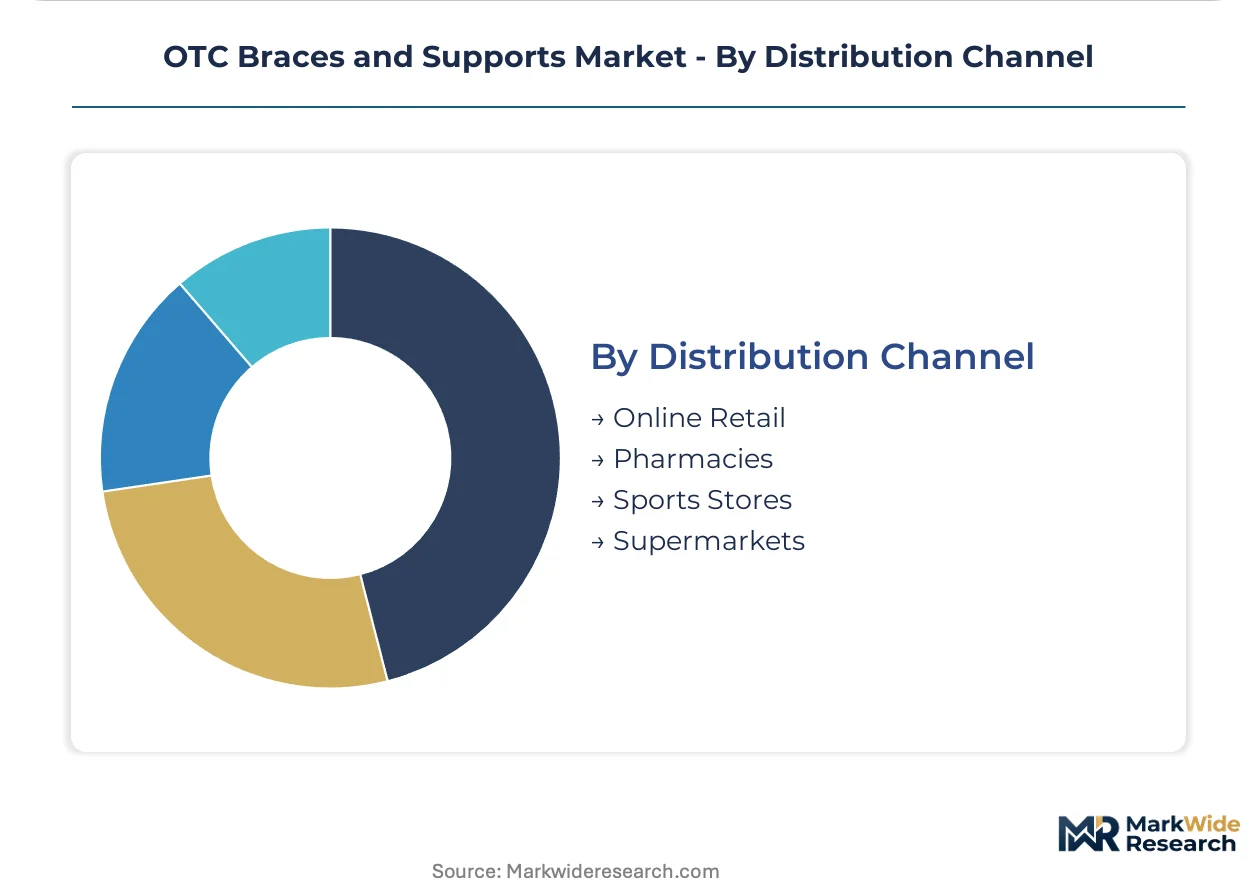
Distribution Channel:
Channel economics determine pricing architecture through markup layering and inventory velocity requirements.
- Online Retail:Direct-to-consumer platforms deploy AI-driven sizing algorithms and subscription replenishment models that bypass wholesale markups. Amazon and specialized orthopedics sites aggregate recurring revenue from athletic and geriatric segments in United States and United Kingdom markets.
- Pharmacies:Robotic dispensing systems in Boots and DM retail chains open shelf-space for standardized SKUs with barcode-integrated inventory tracking across United Kingdom and Germany.
- Sports Stores:Specialist retailers in Australia and Canada provide fitting services and brand authority for premium brace categories targeting competitive athletes.
- Supermarkets:Mass merchandisers in Brazil and China capture impulse purchases for elastic supports and basic compression garments through high-visibility placement.
Pharmacies hold established infrastructure. Online retail is expanding most quickly through telehealth-integrated sizing platforms in Australia and Canada.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for basic elastic supports peaks in Brazil and China where pharmacy chains compete on unit economics, while German and United States buyers absorb premiums for CE-marked and FDA-cleared mechanical braces through insurance reimbursement channels.
United States
Medicare-eligible populations over 65 drive self-managed joint stabilization purchases through direct-to-consumer platforms and specialty retailers. FDA 510(k) clearance pathways maintain lower regulatory barriers than European equivalents, enabling faster product iteration for hinged knee braces. Boston and Minneapolis medical device clusters concentrate biomechanical engineering talent for CAD-based brace design.
Germany
Sports medicine clinics and rehabilitation facilities specify anatomically precise braces for post-surgical ACL recovery protocols. EU MDR Annex XIV clinical evaluation requirements filter lower-quality imports while elevating evidence standards for CE-marked hinge mechanisms. Munich and Düsseldorf engineering clusters specialize in medical-grade neoprene formulations and 3D-printed lattice structures for patient-specific geometries.
China
Basketball and volleyball league participation among athletes aged 18-35 generates repeat ankle support purchases through e-commerce platforms and sports specialty stores. The National Medical Products Administration oversees Class II device registrations with streamlined pathways for domestically manufactured compression garments. Guangdong and Zhejiang manufacturing bases supply woven elastic and thermoplastic components for both domestic consumption and export markets.
Brazil
Court sports participation and occupational manual labor drive volume demand for entry-level elastic supports and lumbar belts through supermarket and pharmacy channels. ANVISA registration requirements for medical devices remain less stringent than FDA or MDR standards, enabling price-competitive imports from Asian suppliers. São Paulo retail chains dominate procurement for standardized SKUs targeting construction and logistics workforces.
United Kingdom
Corporate wellness programs and NHS procurement frameworks create dual demand for posture correction garments and clinical-grade stabilization devices. Boots and other pharmacy chains deploy robotic dispensing systems that favor barcode-integrated inventory tracking for standardized product lines. London and Manchester telehealth platforms integrate remote physiotherapy with direct-to-consumer sizing tools for subscription replenishment models.
OTC Braces and Supports Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the OTC braces and supports market. Premium-tier manufacturers concentrate in German and United States medical device clusters where ISO 13485 certification and regulatory clearance capabilities create entry barriers. Mid-tier competitors compete through pharmacy shelf presence and private-label contracts with retail chains. Scale-driven players and specialized orthopedic fabricators represent the two dominant strategic archetypes, with competitive moves centering on portfolio diversification into adjacent compression wear categories and backward integration into neoprene and woven textile supply chains.
Among German engineering-heritage specialists, Bauerfeind occupies a position exemplifying anatomical precision and medical-grade material formulations. DJO Global represents the rehabilitation technology archetype with professional sports channel dominance. Essity anchors the mass retail scale segment through pharmacy shelf presence across European markets. These three companies illustrate how certification grade, distribution channel control, and geographic origin stratify competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| 3M Company |
| DJO Global |
| Zimmer Biomet |
| Bauerfeind |
| Essity |
| Össur |
| Ottobock |
| Breg |
| DeRoyal Industries |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month MDR technical documentation timelines compress inventory turns for hinge mechanism suppliers while concentrating pricing power among ISO 13485-certified manufacturers with established EU notified body relationships. This lead-time band forces buyers into long-term offtake commitments that lock in premium tier positioning for CE-marked mechanical braces.
Pricing Analysis
Subscription replenishment revenue for compression wear and elastic supports now exceeds initial unit sales lifetime value for direct-to-consumer platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and anatomical precision, with FDA 510(k) cleared hinge mechanisms commanding substantial premiums over basic elastic wraps. Cost compression in neoprene-dependent tiers is intensifying because petrochemical feedstock volatility compresses margins for synthetic rubber formulations. Pharmacy chains and hospital procurement departments show least price sensitivity for CE-marked and FDA-cleared devices, while supermarket channels in Brazil and China absorb maximum elasticity for entry-level elastic supports.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for woven textile components sourced from Guangdong and Zhejiang manufacturing bases. Raw material supply concentrates in China for chloroprene rubber and woven elastane, Germany for medical-grade polymer formulations, and the United States for aluminum alloy hinge components. The supply chain rests on single-source vulnerability for specialized neoprene formulations with medical-grade compression specifications. Distribution runs through pharmacy retail chains with robotic dispensing infrastructure in Germany and the United Kingdom, alongside direct-to-consumer platforms bypassing wholesale markups in United States and Australian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomechanical engineering talent scarcity in anatomical load distribution and CAD-based brace design creates persistent capability gaps that stratify competitive performance between Munich-Boston-Zurich clusters and peripheral manufacturing regions.
For Market Incumbents: Shield premium positioning by deepening captive supply of medical-grade neoprene formulations and securing exclusive notified body relationships for EU MDR Annex XIV clinical evaluation pathways. Add ISO 13485-certified capacity in Germany to defend against 3D-printed lattice substitution from hospital-based prosthetics departments. Channel control through sports medicine clinic specification networks remains the critical defensive lever. For New Entrants and Emerging Players: Differentiate on telehealth-integrated sizing algorithms targeting Australia's remote physiotherapy platforms and Canada's subscription replenishment channels. White-space concentrates in biodegradable PLA-based thermoformable plastics for French and Dutch compostable packaging mandates. Court sports ankle supports in Brazil's supermarket channels offer the most penetrable volume tier with minimal regulatory friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR compliance infrastructure and 3D-printed patient-specific geometry capabilities. Long-term viability favors acquisition targets with established notified body technical documentation files and hospital GPO contract relationships. Watch FDA 510(k) substantial equivalence pathway modifications as the primary regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex XIV Clinical Evaluation Pathway | CE marking for hinge mechanisms requires post-market surveillance data exceeding previous MDD thresholds. |
| Telehealth-Integrated Sizing Platform Development | Australian and Canadian remote physiotherapy platforms create direct-to-consumer measurement tool demand. |
| Biodegradable Composite Material Transition | PLA-based thermoformable plastics align with French and Dutch compostable packaging mandates. |
| Pharmacy Automation Shelf-Space Capture | Robotic dispensing systems in Boots and DM retail chains favor barcode-integrated standardized SKUs. |
| Hospital System Partnership for Post-Surgical Protocols | German and United States sports medicine clinics specify ligament-stabilizing configurations for ACL recovery. |
Methodological Framework
The analysis maps knee brace hinge mechanisms, ankle support stirrup designs, wrist splint configurations, and lumbar belt corset structures, each validated through procurement managers at hospital GPOs, biomedical engineers at sports medicine clinics, pharmacy category buyers, and neoprene formulation specialists. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) clearance databases, EU MDR notified body technical documentation files, ISO 13485 certification registries, and hospital procurement contract disclosures. Bottom-up unit volume estimates triangulated against top-down spending flows from Medicare claims data and European pharmacy retail audit records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type segmentation by mechanical complexity, application segmentation by clinical versus prophylactic use case, material segmentation by petrochemical versus biodegradable feedstock, and distribution channel segmentation by inventory velocity requirements. CAGRs derived from procedure volume growth rates in ligament reconstruction and meniscal repair, cross-referenced with aging demographic projections and court sports participation indices.
Material uncertainties — neoprene price volatility, EU MDR implementation timeline extensions, and 3D-printed orthotics substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and petrochemical feedstock supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plastic Bandages Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Skin Tac Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Cryotubes Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market