
 Global Medical Foam Market | 2026-2036
Global Medical Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Foam Market Foresight
Hospital procurement networks is rewriting vendor qualification standards across the Global Medical Foam Market. 3M Company leverages its adhesive science platform to dominate advanced wound dressing categories. Sekisui Chemical Co. Ltd. anchors supply chains in Asia through precision-controlled polymerization capabilities. Zotefoams plc specializes in high-performance cross-linked polyethylene foams for orthopedic bracing applications.
Medical foam encompasses cellular polymer structures engineered with controlled pore sizes ranging from 10 to 800 microns, manufactured via batch foaming, extrusion, or reaction injection molding to deliver cushioning, absorption, filtration, or barrier functions in clinical environments. Polyurethane foam leads product type volumes due to its tunable hydrophilicity and established sterilization compatibility, while silicone foam captures premium margin pools in long-term implantable applications where biostability commands price premiums. Wound care therapy areas sustain the broadest demand base across acute and chronic settings, though custom molded form factors are gaining traction as device OEMs integrate patient-specific geometries.
FDA 21 CFR Part 820 quality system requirements and EU MDR biocompatibility standards shape product development timelines and testing burdens for manufacturers seeking dual-market access. ISO 10993 biological evaluation protocols and REACH chemical substance restrictions further constrain material selection and supplier qualification processes. Stakeholders must monitor evolving notified body capacity constraints in Europe and upcoming FDA guidance on 3D-printed foam scaffolds to anticipate compliance cost trajectories and competitive positioning shifts.
Market Dynamics
Hospital procurement networks are rewriting vendor qualification standards, forcing foam manufacturers to demonstrate validated sterilization protocols and lot-to-lot consistency before contract award. This buyer-side consolidation is compressing supplier margins while elevating technical documentation burdens.
Growth Catalysts
- EU MDR biocompatibility mandates:Implantable foam categories face expanded testing requirements that favor established manufacturers with in-house toxicology capabilities, filtering out smaller competitors.
- Japan's aging demographic profile:Chronic wound prevalence among patients over 65 drives sustained demand for hydrophilic polyurethane dressings in Tokyo and Osaka hospital networks.
- Reaction injection molding advances:Precision-controlled polymerization enables pore-size tailoring for patient-specific orthopedic bracing, opening custom-form factor revenue streams.
Market Restraints
- Isocyanate feedstock volatility:Polyurethane precursor costs fluctuate with crude oil and benzene derivatives, squeezing margin predictability for high-volume dressing manufacturers.
- German TÜV notified body bottlenecks:EU MDR certification queues extend 18-24 months for novel implantable foams, delaying commercialization timelines.
- Silicone foam substitution pressure:Long-term implant applications increasingly specify silicone over polyurethane for superior biostability, threatening material share in premium segments.
Strategic Opportunities
- India's underserved tier-2 cities:Hospital infrastructure expansion in Pune and Ahmedabad creates first-mover advantages for wound care foam suppliers with localized distribution.
- 3D-printed scaffold convergence:Integration of additive manufacturing with programmable porosity enables patient-matched cranial implants and bone void fillers.
- FDA breakthrough device designation:Expedited review pathways for antimicrobial foam dressings accelerate time-to-revenue for qualifying innovations.
Industry Challenges
- ISO 10993-18 chemist scarcity:Specialized toxicologists capable of conducting extractables and leachables studies command premium salaries, constraining testing capacity.
- Cleanroom capex intensity:Implantable foam production requires ISO Class 7 or better environments, demanding $15-25 million facility investments that deter mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Foam Market |
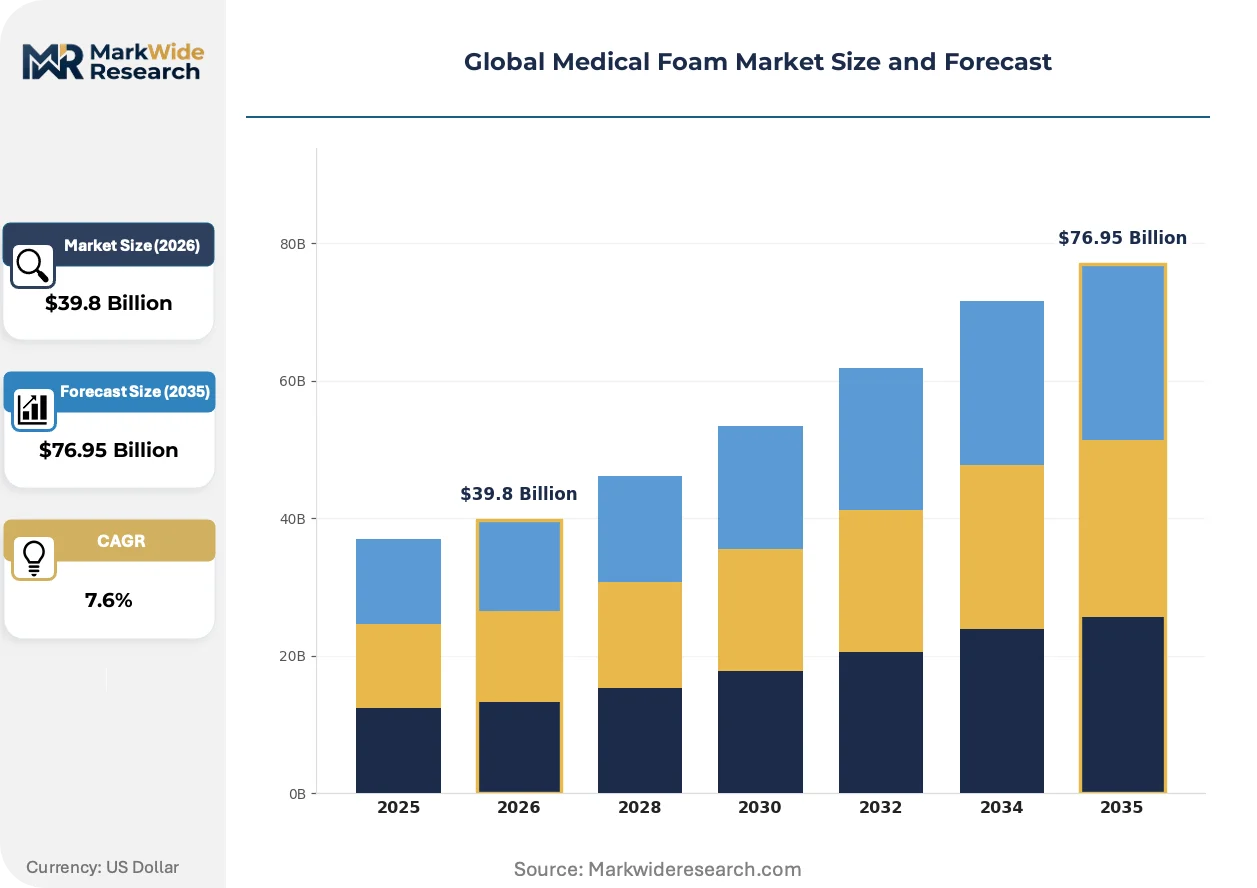
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $76.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Silicone Foam, PVC Foam, Polyethylene Foam, Polystyrene Foam Therapy Area: Wound Care, Orthopedics, Surgical Dressings, Pressure Ulcers, Burn Treatment End User: Hospitals, Clinics, Ambulatory Surgical Centers, Long-Term Care Facilities, Home Healthcare Form Factor: Sheet, Roll, Pad, Tape, Custom Molded |
| Companies Covered | UFP Technologies Inc., Avery Dennison Corp., 3M Company, General Plastics Manufacturing Company Inc., Rogers Corp., Sekisui Chemical Co. Ltd., Zotefoams plc, Foamtec Medical, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Foam Market Shifts & Advancements
Digital manufacturing workflows and predictive biocompatibility modeling are compressing product development cycles while regulatory authorities tighten post-market surveillance requirements. These forces are redistributing competitive advantage toward technology-integrated suppliers.
Computational foam design platforms are virtualizing traditional empirical prototyping. Medical device OEMs in Germany and the United States now simulate cell infiltration and fluid transport through virtual pore architectures before physical mold fabrication. This capability compresses iteration cycles from months to weeks, enabling faster response to surgeon-specific geometry requests while reducing material waste.
REACH chemical substance restrictions are expanding testing obligations for foam additives and residual catalysts. Manufacturers serving European markets must now document safe-use thresholds for isocyanate residuals and tin-based catalysts across complete product lifecycles. Wound care segments with frequent skin contact face the heaviest documentation burdens, driving reformulation investments toward water-blown blowing agents.
Hospital group purchasing organizations are consolidating supplier panels around integrated service capabilities. Large US health systems now specify foam dressing vendors who deliver inventory management, staff training, and outcomes data analytics as bundled offerings. This behavioral shift disadvantages pure product manufacturers while rewarding partners with clinical education infrastructure, particularly visible in integrated delivery networks across Texas and California.
Global Medical Foam Market Segmentation
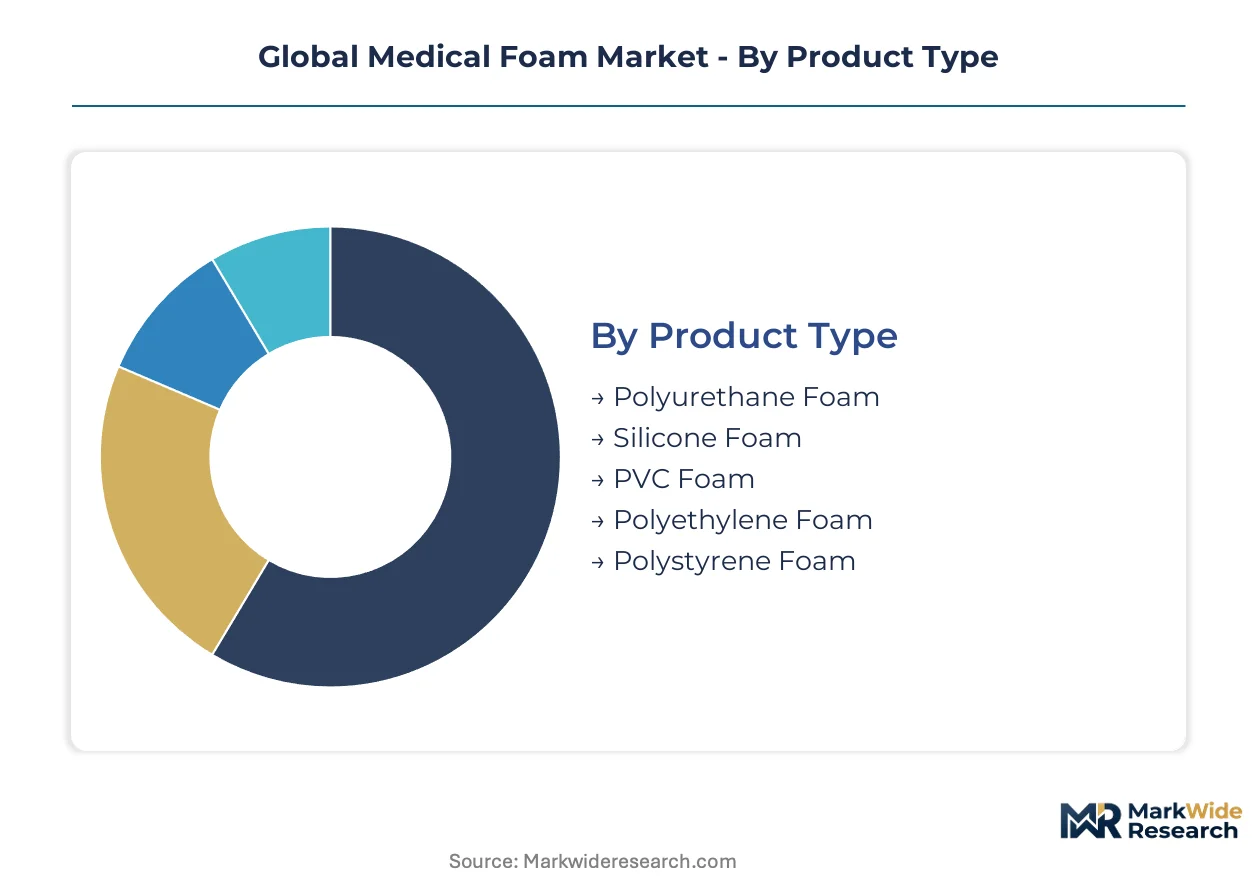
Medical foam segmentation reveals how material science, clinical application, and delivery format intersect to create distinct value pools. Manufacturers configure production assets around specific segment combinations to capture margin premiums or volume scale.
Product Type:
Polymer chemistry determines sterilization compatibility, biostability duration, and cost structure across clinical use cases.
- Polyurethane Foam:Hydrophilic open-cell structures absorb exudate while maintaining breathability. German hospital networks specify polyurethane for chronic wound protocols due to established reimbursement pathways and tunable density grades.
- Silicone Foam:Cross-linked elastomeric matrices resist hydrolytic degradation over multi-year implantation periods. Long-term cardiac and neurological implants in Japanese tertiary centers specify silicone for biostability certification under PMDA guidance.
- PVC Foam:Closed-cell construction delivers rigid cushioning for orthopedic bracing applications.
- Polyethylene Foam:Chemically inert closed-cell structure suits single-use surgical positioning devices.
- Polystyrene Foam:Lightweight rigid cores provide thermal insulation for temperature-sensitive pharmaceutical transport.
Established volume favors polyurethane foam; emerging adoption favors silicone foam.
Therapy Area:
Clinical outcome requirements shape foam specification from absorption capacity to antimicrobial integration.
- Wound Care:Acute and chronic dressings demand controlled moisture balance and non-adherent contact layers. US integrated delivery networks in Texas and California bundle foam dressing procurement with staff training contracts, consolidating vendor relationships around outcomes data capabilities.
- Orthopedics:Load-distribution foams reduce pressure points in casting and bracing applications. Custom-molded polyurethane pads for patient-matched prosthetic sockets are expanding most quickly in German rehabilitation centers with digital scanning workflows.
- Surgical Dressings:Sterile barrier foams prevent cross-contamination in operating theater environments.
- Pressure Ulcers:Redistribution surfaces address immobility complications in aged care populations.
- Burn Treatment:Non-adherent silicone-coated foams minimize trauma during dressing changes.
Procurement concentration favors wound care; technology differentiation favors orthopedics.
End User:
Site-of-care economics determine packaging, sterility assurance, and logistics requirements.
- Hospitals:Centralized sterilization departments and group purchasing organizations dominate foam dressing procurement. Large US health systems now require vendors to deliver inventory management and usage analytics as bundled service components.
- Clinics:Outpatient wound care centers prioritize single-use sterile packaging and compact storage footprints.
- Ambulatory Surgical Centers:Same-day discharge protocols favor pre-sterilized foam positioning devices.
- Long-Term Care Facilities:Pressure injury prevention programs drive recurring mattress overlay purchases.
- Home Healthcare:Self-application dressings require intuitive adhesive systems and consumer-friendly instructions.
Contract scale favors hospitals; margin expansion favors home healthcare.
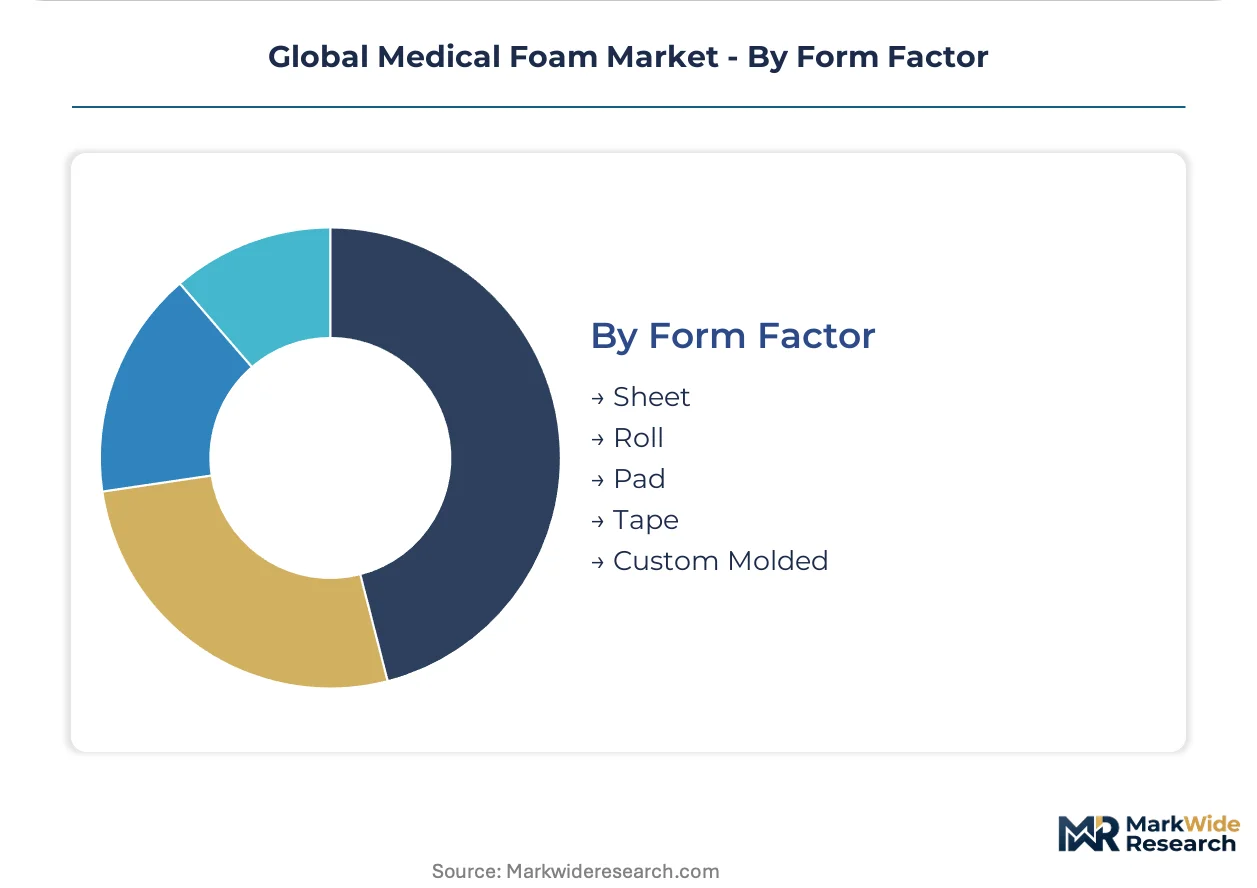
Form Factor:
Manufacturing process selection—batch foaming, extrusion, or reaction injection molding—locks in dimensional precision and unit economics.
- Sheet:Continuous roll production enables die-cutting flexibility for high-volume dressing manufacturers. Japanese medical converters source polyurethane sheets from domestic polymerization facilities with ISO 10993 pre-certified resin streams.
- Roll:Bulk wound care supply chains favor roll formats for automated packaging lines.
- Pad:Pre-cut dimensions reduce clinical preparation time in emergency departments.
- Tape:Adhesive-laminated foams combine cushioning with secure fixation.
- Custom Molded:Reaction injection molding produces patient-specific cranial and orthopedic geometries. German device OEMs now integrate computational design platforms to simulate cell infiltration through virtual pore architectures before physical mold fabrication.
Production efficiency favors sheet and roll formats; value capture favors custom molded.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German wound care foam commands 40-50% price premiums over Indian equivalents due to EU MDR certification burdens and automated production infrastructure. Japanese silicone foam implants trade at comparable premiums in Tokyo tertiary centers where PMDA biostability requirements filter out lower-cost suppliers.
United States
Hospital group purchasing organizations in Texas and California consolidate vendor panels around bundled service contracts. FDA 21 CFR Part 820 quality system requirements extend product development timelines for dual-market access seekers. Boston and Minneapolis medical device clusters drive demand for custom-molded orthopedic foams with patient-specific geometries.
Germany
Chronic wound prevalence among patients over 75 sustains polyurethane dressing volumes across Bavarian and North Rhine-Westphalian hospital networks. EU MDR biocompatibility mandates and TÜV notified body bottlenecks extending 18-24 months filter out smaller competitors. Stuttgart and Munich precision manufacturing corridors anchor reaction injection molding capacity for patient-matched prosthetic sockets.
Japan
Aging demographic concentration in Tokyo and Osaka metropolitan areas drives sustained demand for hydrophilic polyurethane dressings and long-term implantable silicone foams. PMDA guidance on biostability certification shapes material selection for cardiac and neurological applications. Kansai region chemical polymerization facilities supply pre-certified resin streams to domestic medical converters.
India
Hospital infrastructure expansion in Pune and Ahmedabad creates procurement opportunities for wound care foam suppliers with localized distribution networks. CDSCO medical device regulations and BIS standards constrain import-dependent supply chains while favoring domestic manufacturing investments. Gujarat pharmaceutical and medical device clusters attract polyurethane foam fabricators serving tier-2 city hospital networks.
China
NMPA medical device registration requirements and GB standards shape sterilization protocol documentation for wound care foam imports. Yangtze River Delta medical device manufacturing corridors in Shanghai and Suzhou concentrate extrusion and batch foaming capacity for export-oriented suppliers. Domestic demand for surgical positioning foams accelerates with ambulatory surgical center expansion in provincial capitals.
Global Medical Foam Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material science differentiation. The vendor base stratifies between adhesive-platform multinationals with hospital contracting infrastructure and mid-scale polymerization houses with ISO 10993 pre-certified resin streams. Three archetypes dominate: integrated adhesive-science platforms, precision polymerization specialists, and regional fabrication houses with cleanroom conversion capabilities. Competitive moves concentrate on M&A for toxicology testing capacity and strategic partnerships with 3D-printing scaffold developers.
Among platform integrators, 3M Company exemplifies adhesive-science leverage into advanced wound dressing categories. Sekisui Chemical Co. Ltd. anchors the precision polymerization tier with Asia-centric supply chain control. Zotefoams plc occupies a position in high-performance cross-linked polyethylene foams for orthopedic applications. These three represent distinct competitive vectors: platform breadth, regional supply chain anchoring, and material specialization.
| Leading Market Players |
|---|
| UFP Technologies Inc. |
| Avery Dennison Corp. |
| 3M Company |
| General Plastics Manufacturing Company Inc. |
| Rogers Corp. |
| Sekisui Chemical Co. Ltd. |
| Zotefoams plc |
| Foamtec Medical |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Undercapacity in German TÜV notified body certification queues compresses supplier margins while elevating price premiums for EU MDR-compliant implantable foams. This utilization squeeze forces manufacturers to absorb extended validation timelines or pass costs downstream, reshaping procurement negotiations with hospital group purchasing organizations.
Pricing Analysis
The customization-premium spread separates standard polyurethane dressing rolls from patient-matched orthopedic molds by threefold or greater. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and sterilization protocol complexity. Price differentiation hinges on ISO 10993 biocompatibility tier and volume scale, with wound care rolls facing acute price erosion from Asian converters while silicone implant foams retain pricing power. Cost compression in high-volume segments is intensifying because hospital procurement networks consolidate vendor panels around bundled service contracts.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for polyurethane precursor imports. Manufacturing gravity centers on Germany, Japan, and the United States for implant-grade foams, with India emerging for wound care conversion. Raw material dependencies rest on isocyanate feedstocks, medical-grade silicone polymers, and tin-based catalyst systems. Single-source vulnerability concentrates in specialized toxicology testing capacity for EU MDR compliance. Distribution runs through hospital group purchasing organizations in Texas and California, regional medical converters in Kansai, and tier-2 city distributors in Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 10993-18 chemist scarcity constrains testing throughput and extends product development timelines, creating a bottleneck that filters market participation toward capital-rich incumbents with captive toxicology capabilities.
For Market Incumbents: Entrench market position through backward integration into pre-certified resin polymerization and expansion of cleanroom conversion capacity in Stuttgart or Munich corridors. Silicone foam substitution pressure in long-term implants demands accelerated biostability certification investments. Channel control through hospital staff training infrastructure defends margin pools against Asian converters. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 city hospital networks, where localized distribution partnerships overcome import-dependent supply chain constraints. Pune and Ahmedabad infrastructure expansion offers first-mover positioning with lower certification burdens than EU or US markets. A direct-to-clinic model bypassing consolidated procurement panels accelerates initial traction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision polymerization specialists with ISO 10993 pre-certified resin streams and long-term supply agreements with Japanese medical device OEMs. Long-term viability across the analysis window favors acquisition targets with in-house toxicology capabilities and reaction injection molding assets. Monitor FDA breakthrough device designation awards as inflection indicators for antimicrobial foam innovation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | TÜV notified body capacity constraints filter competition toward prepared manufacturers with validated quality systems. |
| Reaction Injection Molding Scale-Up | Patient-specific orthopedic bracing in German rehabilitation centers demands programmable porosity capabilities. |
| 3D-Printed Scaffold Partnership | Additive manufacturing convergence enables cranial implant geometries matched to surgeon-specific requests. |
| Antimicrobial Foam FDA Submission | Breakthrough device designation accelerates review timelines for qualifying wound care innovations. |
| India Distribution Localization | CDSCO compliance and Gujarat manufacturing clusters reduce import dependency for tier-2 city hospitals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, hospital GPO contract databases, and polymer trade flow records. Interviews with biomedical engineers, hospital purchasing committee members, foam manufacturing plant managers, and regulatory affairs specialists at device OEMs provided operational validation. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators ensures cross-verified outputs.
Forecast inputs include therapy area demand trajectories, polymer chemistry substitution patterns, and regulatory approval velocity across jurisdictions. Segmentation dimensions span product type, therapy area, end user, and form factor, with regional production hub clustering as an additional modeling layer. CAGRs derive from slope analysis of historical volume trends adjusted for structural shifts in procurement behavior and certification timelines. Isocyanate feedstock cost volatility and notified body queue lengths inform scenario-weighted projections.
Stress conditions across raw material price spikes, EU MDR implementation delays, and hospital consolidation trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and reimbursement pathway continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Sterilization Box Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Healthcare Cleanroom Consumables Market