
 Intranasal Splints Market | 2026-2036
Intranasal Splints Market Size, Share, and Industry Trends Forecast 2026-2036
Intranasal Splints Market Insights
ENT clinic procurement is decoupling from hospital-centered supply chains as ambulatory settings expand their nasal surgery caseloads. Medtronic leverages its broad ENT portfolio to sustain channel presence across both inpatient and outpatient environments. Smith & Nephew anchors its competitive stance through specialized post-surgical care solutions that differentiate on material biocompatibility. Boston Medical Products Inc. competes via focused product engineering for otolaryngology specialists.
Intranasal splints are medical devices inserted into the nasal cavity to maintain patency, support tissue alignment, and prevent adhesion formation following septoplasty, rhinoplasty, or trauma repair; they are manufactured from silicone, thermoplastic, or bioabsorbable polymers with specifications for controlled flexibility and mucosal surface compatibility. Silicone splints dominate current volume due to established clinical familiarity and reusable processing economics, while bioabsorbable splints represent the fastest-expanding category as surgeons seek to eliminate retrieval procedures. Post-surgical care applications command the largest share of value, though trauma management segments show accelerated growth tied to emergency department protocol standardization.
FDA 510(k) clearance requirements shape product entry timelines and clinical evidence standards for manufacturers targeting the United States market, while ISO 13485 quality management certification operates as a baseline for supplier qualification across developed economies. The EU Medical Device Regulation imposes strengthened post-market surveillance obligations that extend compliance costs for European market access. Stakeholders must monitor evolving biopolymer degradation profiles and shifting site-of-care economics to align portfolio investments with where surgical volumes are migrating.
Market Dynamics
Ambulatory surgical center expansion in the United States is fragmenting traditional hospital procurement hierarchies and forcing manufacturers to rebuild distribution networks around outpatient credentialing requirements.
Growth Catalysts
- EU Medical Device Regulation (MDR):Strengthened post-market surveillance obligations are accelerating manufacturer investments in biopolymer traceability systems.
- Silicone processing economics:Reusable sterilization protocols in high-volume ENT clinics sustain demand for established silicone splint formats.
- Trauma protocol standardization:Emergency department adhesion prevention protocols are expanding splint utilization beyond elective surgical indications.
Market Restraints
- Biopolymer input cost volatility:Specialized bioabsorbable polymer feedstock pricing fluctuates with pharmaceutical-grade resin allocation competition.
- FDA 510(k) evidentiary burden:Clinical equivalence documentation requirements extend product entry timelines for novel material formulations.
- Silicone splint substitution ceiling:Reusable processing infrastructure investments in outpatient settings create switching friction against bioabsorbable alternatives.
Strategic Opportunities
- India CDSCO pathway acceleration:Streamlined Class B medical device registration is opening access to price-sensitive South Asian surgical markets.
- Direct-to-clinic distribution:Bypassing hospital-centered supply chains captures margin compression from group purchasing organization consolidation.
- 3D-printed patient-specific splints:Converging additive manufacturing with otolaryngology CAD workflows enables anatomically matched trauma repair solutions.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlog delays quality management system validation for emerging market entrants.
- Legacy hospital inventory integration:Outpatient clinic procurement systems require API connectivity investments to synchronize with manufacturer ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intranasal Splints Market |
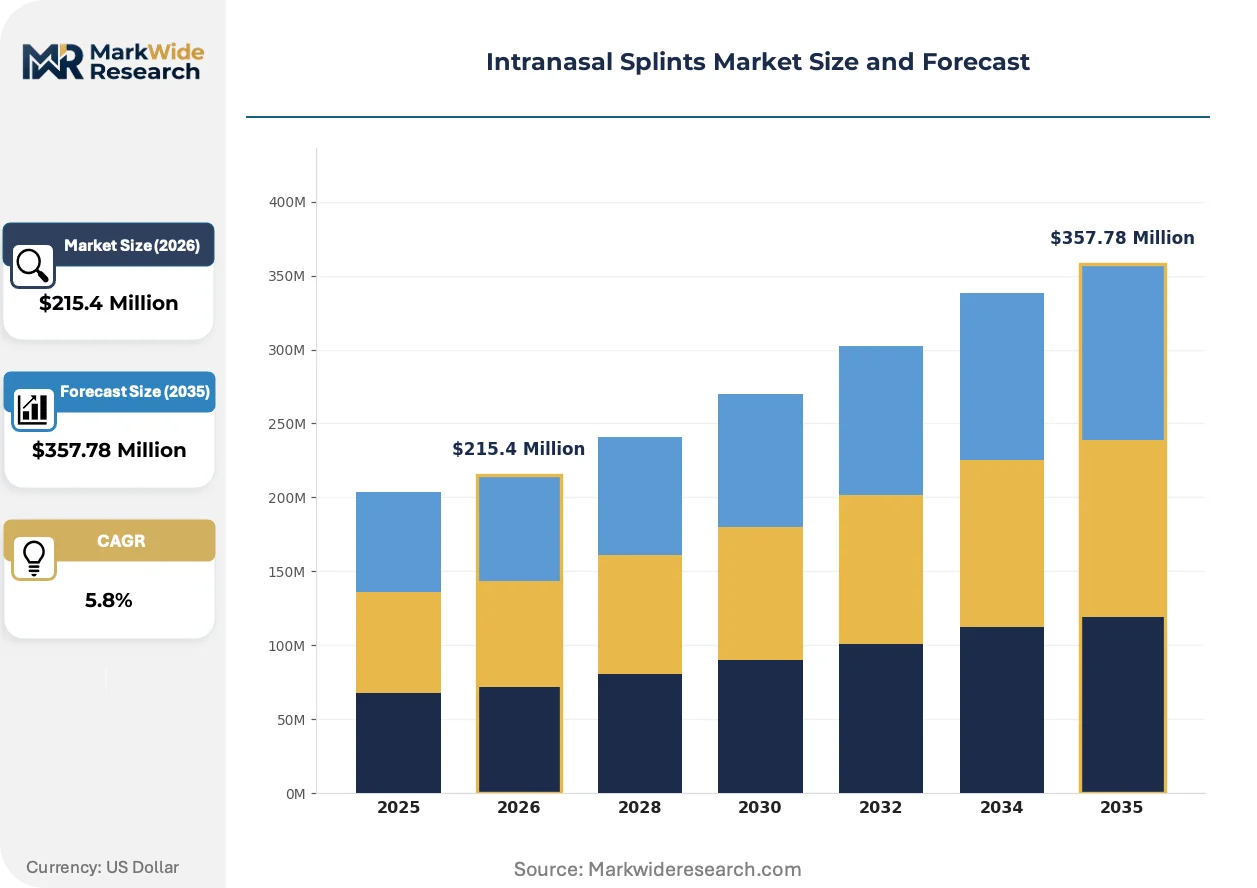
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Splints, Plastic Splints, Bioabsorbable Splints, Others End User: Hospitals, Ambulatory Surgical Centers, ENT Clinics, Home Care Application: Post-Surgical Care, Nasal Congestion, Trauma Management, Others Material: Polyethylene, Polypropylene, Biopolymer, Elastomer |
| Companies Covered | Olympus Corporation, Medtronic, Smith & Nephew, Teleflex Inc., Stryker Corporation, Boston Medical Products Inc, Surgiform Innovative Surgical Products, Anthony Products Inc., Audio Technologies SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intranasal Splints Market Trends and Innovations
Bioabsorbable polymer degradation science is compressing retrieval procedure economics while regulatory evidence standards harden around material safety profiles.
Polylactic-co-glycolic acid (PLGA) composite splints are absorbing the functional role of silicone in septoplasty aftercare by eliminating second-visit retrieval requirements. Academic medical center otolaryngology departments are piloting these formats for complex revision cases. The technology is absorbing retrieval labor costs into upfront material pricing, restructuring total procedure economics for ambulatory facilities.
REACH substance restriction frameworks are compelling European manufacturers to reformulate plasticizer chemistries in thermoplastic splint compositions. Industrial consequence includes accelerated R&D allocation toward bio-based alternative plasticizers. German ENT device suppliers are most affected, responding with supply chain requalification programs for affected polymer grades.
Site-of-care purchasing authority is migrating from hospital materials management to individual clinic administrators as nasal surgery volumes shift outpatient. Distributor relationships that historically served centralized procurement offices are being displaced by manufacturer-direct field representatives. This behavioral shift is most visible in United States metropolitan markets with dense ambulatory surgery center clustering.
Intranasal Splints Market Segmentation
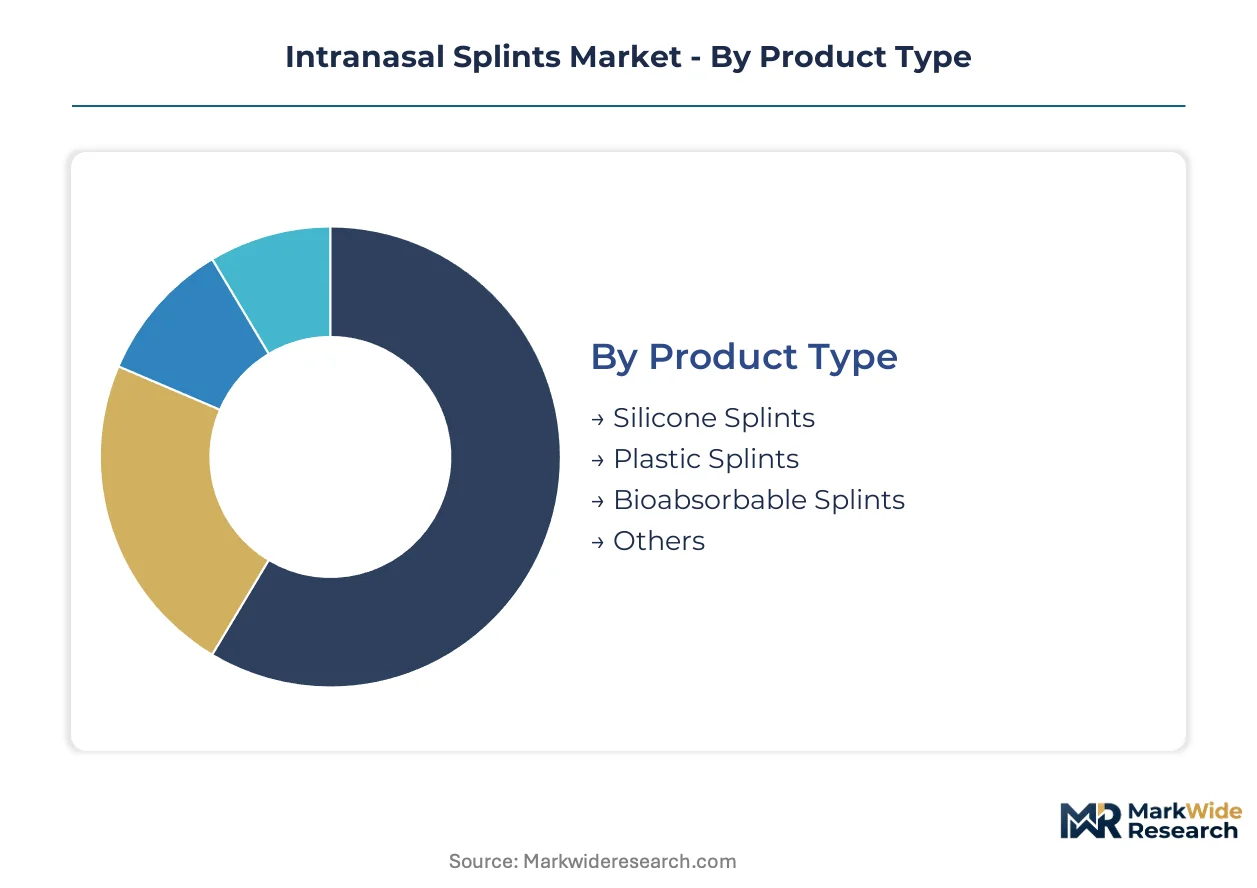
Intranasal splint manufacturers must align capital allocation with divergent production economics across material platforms and site-of-care purchasing authority. Segment boundaries reflect where sterilization infrastructure, biopolymer R&D, and direct-to-clinic distribution investments yield differentiated returns.
Product Type:
Silicone processing lines demand the heaviest upfront capital for reusable sterilization infrastructure, while bioabsorbable extrusion systems require specialized cleanroom investments for pharmaceutical-grade polymer handling.
- Silicone Splints:Thermoset silicone formulations deliver controlled flexibility and mucosal surface compatibility through established molding processes. Demand concentrates in high-volume United States ENT clinics where reusable sterilization protocols amortize equipment costs across thousands of procedures annually.
- Bioabsorbable Splints:Polylactic-co-glycolic acid composites eliminate retrieval visits by controlled degradation over 7-14 days. Academic medical centers in Germany and the United States pilot these formats for complex revision septoplasty, absorbing retrieval labor costs into upfront material pricing.
- Plastic Splints:Thermoplastic elastomer variants offer intermediate cost positioning for price-sensitive hospital procurement.
- Others:Hybrid constructions and experimental polymer formats serve niche trauma indications.
Most installed capacity flows through Silicone Splints. Expansion is steepest in Bioabsorbable Splints.
End User:
Procurement authority fragmentation distinguishes segments by credentialing complexity and contract structure rather than clinical indication alone.
- Ambulatory Surgical Centers:Independent purchasing decisions in United States metropolitan markets enable manufacturer-direct relationships bypassing group purchasing organization consolidation. Volume migration from inpatient settings accelerates as nasal surgery protocols standardize for same-day discharge.
- ENT Clinics:Decoupled supply chains from hospital materials management require API-integrated ERP connectivity for inventory synchronization. Clinic administrators in Texas and California clusters now control splint selection independently.
- Hospitals:Centralized procurement maintains volume concentration but loses share as cases shift outpatient.
- Home Care:Limited penetration restricted to post-trauma stabilization in markets with established home nursing infrastructure.
Revenue concentration tilts toward Ambulatory Surgical Centers. ENT Clinics are gaining share fastest.
Application:
Procedure reimbursement economics and protocol standardization maturity separate segments by evidence requirements and sales cycle length.
- Post-Surgical Care:Septoplasty and rhinoplasty aftercare commands established reimbursement codes across United States commercial payers. Silicone splint retrieval scheduling integrates with routine post-operative visit workflows in hospital-affiliated outpatient departments.
- Trauma Management:Emergency department adhesion prevention protocols expand utilization beyond elective indications. Level I trauma centers in Illinois and Pennsylvania standardize splint placement for nasal fracture reduction.
- Nasal Congestion:Chronic obstruction management represents off-label expansion opportunity with limited formal indication.
- Others:Congenital anomaly repair and revision rhinoplasty comprise specialized case volumes.
Post-Surgical Care absorbs the majority of current utilization. Trauma Management shows the steepest expansion trajectory.
Material:
Feedstock sourcing concentration and regulatory qualification burden differentiate segments by supply security and formulation agility.
- Biopolymer:Pharmaceutical-grade PLGA and polylactic acid resins face allocation competition from drug delivery and suture manufacturers. FDA 510(k) clearance pathways require extensive degradation profile documentation extending development timelines.
- Elastomer:Medical-grade silicone supply concentrates with German and United States chemical processors offering established biocompatibility master files.
- Polyethylene:Commodity resin pricing enables cost leadership positioning for high-volume contract manufacturing.
- Polypropylene:Stiffness characteristics suit structural support applications with lower flexibility requirements.
Volume leadership resides with Elastomer. Biopolymer claims the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Otolaryngology specialist concentrations in Germany, the United States, Japan, India, and the United Kingdom anchor regional production and procurement patterns for intranasal splints. Each market exhibits distinct regulatory pathways and site-of-care migration trends.
United States
Ambulatory surgical center networks in Texas and California clusters are decoupling splint procurement from hospital materials management. FDA 510(k) clearance pathways shape product entry timelines for bioabsorbable polymer formulations. Greater Boston academic medical centers pilot PLGA composite splints for complex revision septoplasty cases.
Germany
REACH substance restriction frameworks are compelling manufacturers to reformulate thermoplastic splint plasticizer chemistries. EU Medical Device Regulation post-market surveillance obligations extend compliance costs for domestic suppliers. Bavarian ENT device manufacturers are executing supply chain requalification programs for affected polymer grades.
Japan
PMDA medical device approval pathways prioritize clinical evidence standards for novel biopolymer degradation profiles. Tokyo metropolitan otolaryngology departments maintain preference for silicone splint formats with established sterilization protocols. Kansai region manufacturers concentrate on thermoplastic elastomer variants for intermediate cost positioning.
India
CDSCO streamlined Class B medical device registration is opening price-sensitive South Asian surgical markets to foreign suppliers. Maharashtra and Gujarat manufacturing clusters are expanding contract production capacity for polyethylene-based splint formats. Delhi-NCR ENT clinics are adopting direct-to-clinic distribution models bypassing traditional hospital procurement.
United Kingdom
NHS procurement frameworks are standardizing post-surgical splint specifications across hospital trusts and affiliated outpatient departments. London/Southeast otolaryngology networks are consolidating purchasing authority through regional procurement hubs. Midlands-based distributors are rebuilding field representative networks to serve independent clinic administrators directly.
Intranasal Splints Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures concentrate among mid-scale manufacturers lacking vertical integration into polymer feedstock supply. Three strategic archetypes dominate: diversified medical device conglomerates with broad ENT portfolios, specialized post-surgical care pure-plays, and regional contract manufacturers serving price-sensitive procurement segments. Dominant competitive moves include M&A activity targeting bioabsorbable polymer capabilities and direct-to-clinic distribution network expansion.
Among diversified conglomerates, Medtronic and Stryker Corporation exemplify scale-driven positioning across inpatient and outpatient environments. Smith & Nephew occupies a specialist tier focused on material biocompatibility differentiation. Boston Medical Products Inc. represents the focused pure-play archetype serving otolaryngology specialists through concentrated product engineering.
| Leading Market Players |
|---|
| Olympus Corporation |
| Medtronic |
| Smith & Nephew |
| Teleflex Inc. |
| Stryker Corporation |
| Boston Medical Products Inc |
| Surgiform Innovative Surgical Products |
| Anthony Products Inc. |
| Audio Technologies SRL |
| Others |
Pricing and Supply Chain Analysis
Material-grade bifurcation between pharmaceutical-grade biopolymers and commodity thermoplastics manifests in divergent pricing architectures and procurement network configurations. FDA 510(k) clearance tiers anchor premium positioning for bioabsorbable formats while silicone splint economics rest on sterilization infrastructure amortization across high-volume United States ENT clinics.
Pricing Analysis
Capacity additions in Maharashtra and Gujarat contract manufacturing clusters are reshaping price floors for polyethylene-based splint formats. Three-tier pricing structure across premium bioabsorbable, standard silicone, and economy thermoplastic levels separates retrieval-elimination value from reusable processing economics. Cost compression in plastic splint tiers intensifies because CDSCO streamlined registration invites price-sensitive South Asian competition. Ambulatory surgical centers in Texas metropolitan markets exhibit highest price sensitivity due to direct procurement authority without GPO buffer, while academic medical centers in Greater Boston absorb premium bioabsorbable pricing to eliminate retrieval labor.
Supply Chain Analysis
Regional distribution centers in Chicago and Dallas operate hub-and-spoke patterns serving United States ambulatory surgery center networks. Pharmaceutical-grade PLGA resin supply concentrates with German and United States chemical processors, while medical-grade silicone feedstock draws from established biocompatibility master file holders. Single-source vulnerability in pharmaceutical-grade polymer allocation competition from drug delivery manufacturers threatens bioabsorbable splint production continuity. Distribution runs through manufacturer-direct field representatives targeting independent clinic administrators, displacing historical hospital-centered procurement office relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in intranasal splints hinges on eliminating retrieval procedure economics through bioabsorbable material premiums and capturing ambulatory procurement authority via direct distribution infrastructure.
For Market Incumbents: Deepen backward integration into pharmaceutical-grade polymer feedstock supply to secure PLGA allocation against drug delivery sector competition. Fortify direct-to-clinic ERP connectivity investments to synchronize inventory with Texas and California ENT clinic procurement systems, defending channel position against emerging contract manufacturers leveraging CDSCO pathway acceleration. For New Entrants and Emerging Players: Begin with trauma management protocol standardization in Level I emergency departments across Illinois and Pennsylvania, where adhesion prevention guidelines remain underpenetrated by established silicone formats. Capture share through 3D-printed patient-specific splint pilots for complex nasal fracture reduction, leveraging additive manufacturing partnerships with academic otolaryngology departments. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale manufacturers lack captive supply of biopolymer feedstock or ISO 13485 certification body relationships. Target acquisition candidates with established FDA 510(k) clearance portfolios and ambulatory surgery center distribution contracts. Signal to watch: CDSCO registration acceleration triggering price competition that compresses margins for non-integrated polyethylene splint producers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates bioabsorbable polymer entry into United States academic medical center pilot programs. |
| Direct-to-Clinic Distribution Expansion | Bypasses GPO consolidation to capture margin in Texas and California metropolitan clusters. |
| Biopolymer Feedstock Backward Integration | Secures PLGA allocation against pharmaceutical sector competition for resin supply. |
| 3D-Printed Patient-Specific Development | Enables anatomically matched trauma repair solutions through otolaryngology CAD workflows. |
| ISO 13485 Certification Investment | Overcomes auditor capacity constraints delaying emerging market entrant qualification. |
Research Methodology
Multiple input streams — otolaryngology department purchasing committees, ambulatory surgery center administrators, biomedical engineers at academic medical centers, and GPO contracts managers — were reconciled against secondary validation from FDA 510(k) filings, CDSCO registration databases, hospital procurement records, and EU MDR post-market surveillance disclosures. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation across the analysis window.
Data-stream reconciliation applied segmentation dimensions spanning material platform, site-of-care purchasing authority, and application protocol maturity. CAGRs derived from procedure volume migration trends and pricing elasticity by splint format. Forecast inputs incorporated REACH substance restriction timelines and ambulatory surgery center network expansion trajectories without year-specific assumptions.
Several conditions sit outside the modeled scope, including unforeseen biopolymer degradation profile safety events and abrupt shifts in United States nasal surgery reimbursement codes. Forecasts reflect assumptions about regulatory pathway stability and feedstock allocation competition. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Global Lancets Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Europe Syringe Market