
 Europe Ostomy Drainage Bags Market | 2026-2036
Europe Ostomy Drainage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ostomy Drainage Bags Market Analytics
Aftermarket service revenue from pouch replacement programs is narrowing as manufacturers bundle subscription-style replenishment into initial device contracts. Coloplast leverages its direct-to-patient logistics network across Nordic markets to sustain recurring revenue streams. Hollister competes through specialized stoma care nurse training programs that anchor clinician loyalty in the United Kingdom and Ireland.
Europe ostomy drainage bags are sterile, single-use collection devices typically constructed from multi-layer odor-barrier films combining polyethylene with activated carbon filters, designed to receive and contain effluent from surgically created stomas. Drainable bags dominate the product type landscape due to extended wear time and lower per-use cost for ileostomy patients, while closed bags command premium positioning in colostomy cases where disposal convenience outweighs emptying frequency. Silicone interfaces are gaining material share against standard vinyl construction as skin-friendly adhesion properties reduce peristomal complications and extend wear duration.
The EU Medical Device Regulation (MDR) and CE marking framework mandate clinical evidence portfolios for ostomy appliance re-certification, elevating compliance costs for smaller manufacturers while reinforcing barriers for non-European entrants. EMA-aligned vigilance reporting requirements for adverse events shape post-market surveillance obligations across member states. Stakeholders must monitor reimbursement recalibrations under France's CEPS and Germany's G-BA as these bodies tighten evidence requirements for stoma care product inclusion in statutory benefit catalogs.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing competitive timelines by demanding clinical evidence portfolios for ostomy appliance re-certification, forcing manufacturers to consolidate R&D spending or exit the market entirely.
Growth Catalysts
- MDR compliance frameworks:CE marking mandates under the EU Medical Device Regulation are filtering out marginal competitors and concentrating procurement authority among certified suppliers.
- Silicone interface adoption:Skin-friendly adhesion properties in silicone-based flange systems are reducing peristomal complications and extending wear duration for ileostomy patients.
- German statutory health insurance:The G-BA reimbursement corridor maintains predictable demand volumes for drainable systems across ambulatory care networks.
Market Restraints
- Multi-layer film input costs:Polyethylene and activated carbon filter supply chains face petrochemical price volatility that squeezes margin structures.
- Regulatory friction from EMA vigilance:Post-market surveillance obligations for adverse event reporting extend compliance timelines and elevate legal exposure.
- Closed-system substitutes:Internal continent devices and surgical reconstructions present long-term displacement risk for external collection appliances.
Strategic Opportunities
- France CEPS recalibration:Tightened evidence requirements for stoma care product inclusion create first-mover advantage for manufacturers with robust clinical portfolios.
- Direct-to-patient logistics:Subscription-style replenishment models bypass traditional hospital purchasing networks and capture recurring revenue streams.
- Nordic home care expansion:Drainable system procurement by decentralized home care providers is outpacing institutional volume growth in Denmark and Sweden.
Industry Challenges
- Stoma care nurse certification timelines:Specialized training programs require 18-24 month accreditation cycles that constrain sales force deployment speed.
- Legacy vinyl inventory integration:Manufacturers maintaining dual material lines face working capital strain during silicone transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ostomy Drainage Bags Market |
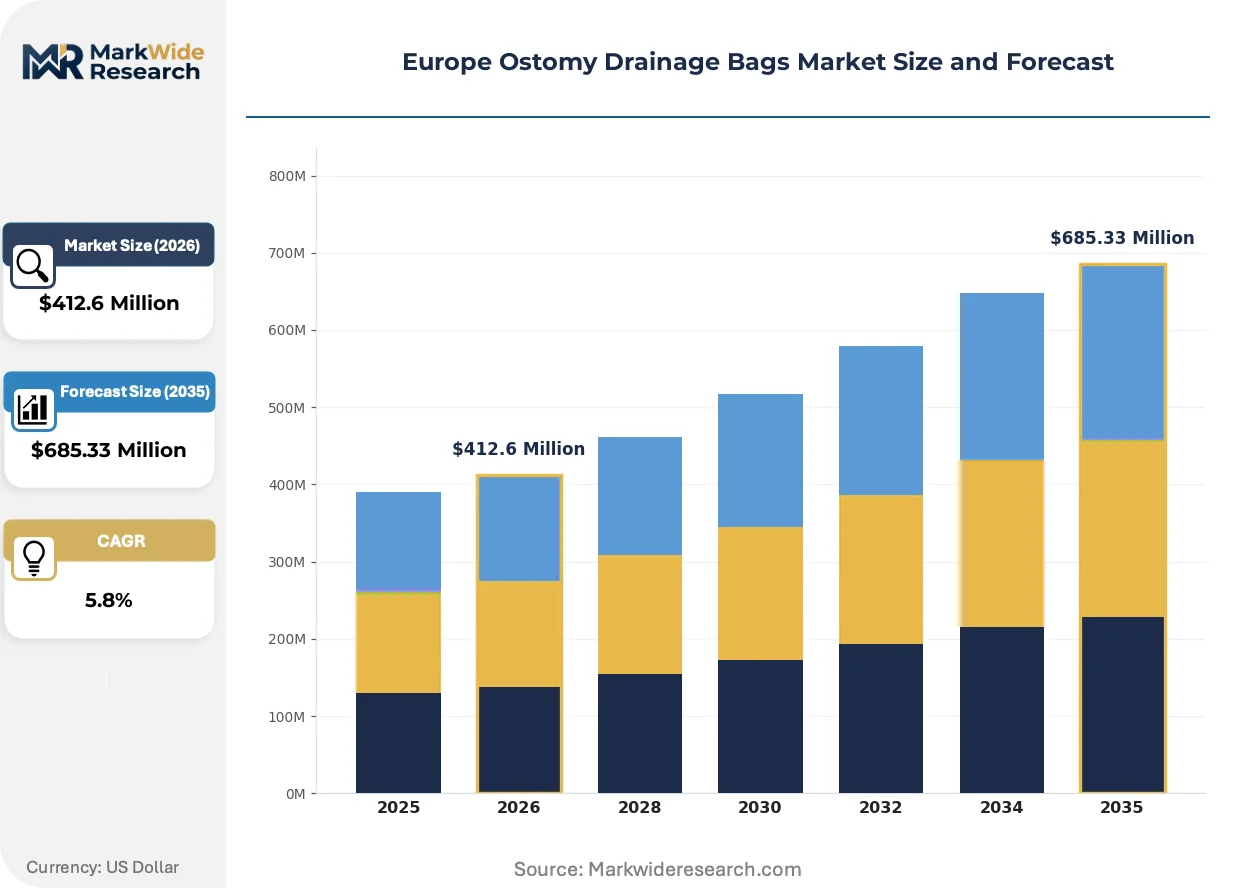
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Bags, Closed Bags, Drainable Bags, Non-drainable Bags Material: Plastic, Vinyl, Silicone, Rubber Application: Colostomy, Ileostomy, Urostomy, Pouching System End User: Hospitals, Home Care, Long-term Care, Rehabilitation Centers |
| Companies Covered | Coloplast, ConvaTec Group, Hollister, B. Braun Melsungen, Dansac, Salts Healthcare, Welland Medical, Flexicare Medical, Alcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ostomy Drainage Bags Market Evolving Landscape
Odor-barrier film engineering and adhesion chemistry are converging to extend wear intervals, while regulatory evidence requirements and procurement centralization are reshaping how manufacturers access patients.
Activated carbon-integrated multi-layer films with enhanced gas permeability control are rendering obsolete standard single-barrier constructions that required more frequent replacement cycles. Ileostomy patients in Germany and France are adopting these systems at accelerating rates. Extended wear duration is compressing per-patient annual unit consumption and forcing manufacturers to recalibrate pricing architectures.
EU MDR clinical evidence mandates are elevating documentation burdens for ostomy appliance re-certification. Smaller manufacturers without dedicated regulatory affairs functions are surrendering market positions rather than absorbing compliance costs. Western European reimbursement corridors, particularly the German statutory framework, are tightening supplier qualification criteria in response.
Hospital purchasing networks are consolidating procurement authority through centralized tendering platforms that disaggregate device selection from individual clinician preference. France's CEPS and regional hospital groups are driving this concentration. The United Kingdom and Ireland exhibit the most advanced centralization, with stoma care nurse training programs becoming the residual channel for manufacturer influence.
Europe Ostomy Drainage Bags Market Segmentation
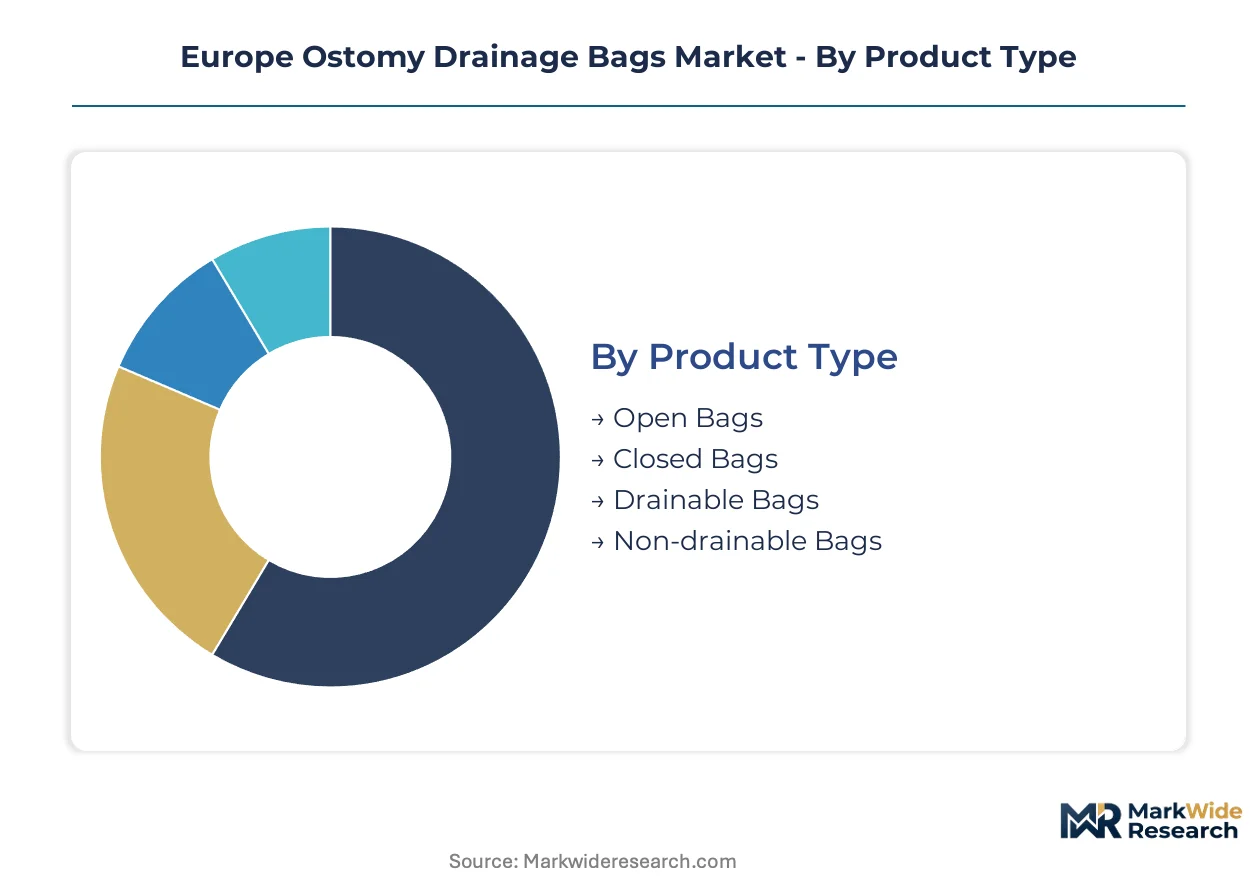
Segmentation in ostomy drainage bags determines procurement rhythms, reimbursement tiers, and inventory turnover across European healthcare networks. Cycle times vary dramatically by product format and patient setting, creating distinct margin profiles that manufacturers must navigate.
Product Type:
Replacement frequency separates segments sharply—drainable systems extend wear intervals while closed bags demand higher per-unit throughput.
- Drainable Bags:Multi-layer odor-barrier films with integrated carbon filters allow 3-7 day wear cycles for ileostomy patients. German statutory health insurance reimburses these preferentially for home-based care, compressing annual unit volumes per patient while stabilizing recurring revenue streams.
- Closed Bags:Single-use sealed systems eliminate emptying but require complete replacement after each bowel movement. Colostomy patients in France and the United Kingdom favor these for discretion in workplace and social settings, driving premium pricing despite higher consumption rates.
- Open Bags:Re-closable aperture designs suit high-output stomas requiring frequent inspection.
- Non-drainable Bags:Fixed-volume construction limits application to predictable-output cases with caregiver support.
Drainable bags dominate installed base. Closed bags are where expansion concentrates.
Material:
Cost tiers stratify sharply—silicone commands 40-60% premiums over vinyl while rubber and plastic occupy economy positioning.
- Silicone:Hypoallergenic flange interfaces reduce peristomal dermatitis and extend adhesion duration to 5-10 days. Nordic home care networks in Denmark and Sweden are standardizing procurement around silicone despite higher unit costs, recognizing total cost-of-care savings from reduced complication rates.
- Vinyl:Standard thermoplastic construction maintains lowest per-unit manufacturing cost but shorter wear duration limits reimbursement appeal. Legacy inventory still circulates in price-sensitive Southern European markets transitioning to MDR-compliant alternatives.
- Plastic:Polyethylene-based multi-layer films balance barrier performance with processability for high-volume production.
- Rubber:Natural latex and synthetic elastomer variants persist in specialized high-flexibility applications.
Silicone is gaining share fastest in reimbursed channels. Vinyl retains volume in cash-pay segments.
Application:
Stoma type dictates output volume, acidity, and wear-time requirements that reshape bag specification.
- Ileostomy:Liquid effluent and enzymatic activity demand superior barrier films and secure flange adhesion. Patients across Germany and the Netherlands show strongest adoption of extended-wear drainable systems, where output consistency permits longer intervals between changes.
- Colostomy:Formed stool output enables closed-bag convenience and predictable replacement schedules. French hospital purchasing networks concentrate procurement authority here, favoring suppliers with CEPS-negotiated pricing tiers.
- Urostomy:Continuous urine flow requires specialized anti-reflux valves and odor control distinct from fecal applications.
- Pouching System:Integrated two-piece flange-and-bag combinations dominate institutional procurement for flexibility and skin protection.
Ileostomy applications drive technology premiumization. Colostomy represents the largest addressable patient population.
End User:
Customer type determines purchasing authority, reimbursement pathway, and inventory management intensity.
- Home Care:Decentralized procurement across regional nursing services and direct-to-patient logistics platforms is outpacing institutional growth. Sweden and Denmark exhibit the most advanced home-care-first models, with drainable system subscriptions replacing hospital-based dispensing.
- Hospitals:Centralized tendering platforms in France and the United Kingdom aggregate purchasing power and disaggregate clinician preference from supplier selection. Stoma care nurse training programs have become the residual channel for manufacturer influence in these settings.
- Long-term Care:Nursing home procurement emphasizes staff efficiency and reduced per-change labor time over patient self-management features.
- Rehabilitation Centers:Transitional care settings bridge acute discharge and permanent home care configuration.
Home care is climbing the fastest as procurement decentralizes. Hospitals retain volume concentration through tender aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across reimbursement regimes. German statutory insurance absorbs most patient costs, while Southern European cash-pay segments demand economy alternatives. Nordic markets prioritize total cost-of-care over unit pricing.
Germany
The G-BA reimbursement corridor stabilizes demand for drainable systems across ambulatory networks. EU MDR re-certification deadlines are compressing supplier qualification timelines. Berlin and Munich host the densest clusters of stoma care nurse training programs, anchoring manufacturer influence in hospital purchasing.
France
CEPS-negotiated pricing tiers concentrate procurement authority through regional hospital groups. Closed-bag preference among colostomy patients drives premium positioning in workplace settings. The Île-de-France region aggregates tender volumes that disaggregate individual clinician choice from supplier selection.
United Kingdom
NHS centralized tendering platforms have advanced furthest in disaggregating device selection from stoma care nurse preference. Silicone interface adoption is accelerating through home care prescribing pathways. London and Manchester purchasing consortia dominate volume allocation decisions.
Sweden
Decentralized home care procurement is outpacing institutional growth through direct-to-patient logistics subscriptions. Silicone flange systems command standard-of-care status despite higher unit costs. Stockholm and Gothenburg nursing services lead the shift from hospital-based dispensing.
Denmark
Regional nursing services standardize around extended-wear drainable systems for ileostomy patients. EU MDR vigilance reporting requirements shape post-market surveillance obligations. Copenhagen's home care networks exemplify the procurement decentralization trend across Nordic markets.
Europe Ostomy Drainage Bags Market Competitive Landscape
Full-line manufacturers and specialized stoma care suppliers split the market into distinct competitive spheres. Consolidation pressures from EU MDR compliance costs are filtering out marginal participants while reinforcing positions of established CE-marked suppliers. Three archetypes dominate: integrated medical device conglomerates with diversified surgical portfolios, dedicated ostomy care specialists with nurse-training ecosystems, and regional fabricators serving price-sensitive segments. Vertical integration into odor-barrier film production and strategic partnerships with home care logistics platforms represent the dominant competitive moves reshaping supplier economics.
Within the dedicated ostomy care tier, Coloplast and Hollister exemplify contrasting geographic anchoring strategies. Coloplast leverages its Nordic direct-to-patient infrastructure to capture recurring revenue streams outside hospital purchasing networks. Hollister competes through clinician-facing training investments that sustain loyalty in United Kingdom and Ireland tender environments. Among diversified surgical suppliers, B. Braun Melsungen occupies a position bridging acute care procurement and ambulatory stoma management, reflecting the broader conglomerate pattern of cross-selling across surgical procedure portfolios.
| Leading Market Players |
|---|
| Coloplast |
| ConvaTec Group |
| Hollister |
| B. Braun Melsungen |
| Dansac |
| Salts Healthcare |
| Welland Medical |
| Flexicare Medical |
| Alcare |
| Others |
Value Network & Pricing Analysis
Rhineland petrochemical clusters anchor multi-layer film production for odor-barrier materials, concentrating upstream capacity that feeds downstream pricing power to manufacturers with captive supply arrangements. German and French procurement networks absorb this concentration through long-term contracting, while peripheral markets face spot-price exposure that amplifies margin volatility.
Pricing Analysis
Aftermarket service revenue from pouch replacement programs now drives lifetime value capture as manufacturers bundle subscription-style replenishment into initial device contracts. Three-tier pricing structure across premium silicone, standard vinyl, and economy plastic tiers separates reimbursement-eligible systems from cash-pay alternatives. Cost compression in economy vinyl segments is intensifying because Southern European markets resist MDR-compliant upgrades. Home care networks in Nordic countries exhibit lowest price sensitivity due to total cost-of-care accounting, while hospital purchasing committees in France and the United Kingdom drive hardest bargain through centralized tender aggregation.
Supply Chain Analysis
Polyethylene feedstock and activated carbon filter supply chains draw from German, Dutch, and Belgian petrochemical complexes that dominate European specialty film production. Raw material dependencies rest on naphtha-derived ethylene, medical-grade carbon substrates, and silicone elastomer precursors sourced from industrial chemical networks. Single-source vulnerability concentrates in carbon filter manufacturing where two suppliers control qualification pathways for MDR-compliant appliances. Distribution runs through hospital purchasing consortia in France and the United Kingdom, direct-to-patient logistics platforms in Nordic markets, and regional nursing service networks across Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance timelines fragment competitive structure, creating niches for specialized entrants as smaller manufacturers surrender positions rather than absorb re-certification costs. Home care procurement decentralization accelerates this fragmentation by opening channels outside hospital purchasing concentration.
For Market Incumbents: Build regulatory affairs capability moats by consolidating CE marking documentation across product portfolios before MDR re-certification deadlines compress. Absorb or partner with Nordic direct-to-patient logistics operators to lock recurring revenue streams outside tender-based hospital procurement. Anchor clinician loyalty through expanded stoma care nurse training programs in United Kingdom and Ireland where purchasing authority centralization threatens direct sales access. For New Entrants and Emerging Players: Pursue white-space positioning in silicone flange systems for Nordic home care networks where reimbursement frameworks recognize total cost-of-care savings over unit pricing. Target Southern European cash-pay segments transitioning from legacy vinyl inventory to MDR-compliant alternatives. Enter through specialized distribution partnerships with regional nursing services rather than direct hospital contracting. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MDR compliance costs will filter marginal participants and concentrate procurement authority among full-line suppliers with dedicated regulatory functions. Acquisition target archetype: mid-tier manufacturers with established CE marking portfolios but undercapitalized for MDR re-certification. Watch CEPS and G-BA reimbursement recalibrations as inflection signals for stoma care product inclusion criteria tightening.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR clinical evidence portfolios compress competitive timelines and elevate barriers for non-European entrants. |
| Direct-to-Patient Logistics Buildout | Subscription replenishment models bypass hospital purchasing networks and capture recurring revenue in Nordic markets. |
| Silicone Material Transition | Skin-friendly flange systems reduce peristomal complications and extend wear duration for reimbursed ileostomy patients. |
| Stoma Care Nurse Training Investment | Specialized accreditation programs anchor clinician loyalty in United Kingdom and Ireland tender environments. |
| Backward Integration into Film Production | In-house odor-barrier manufacturing captures margin from petrochemical volatility and secures supply continuity. |
Research Methodology
A spread of perspectives from stoma care nurses, hospital procurement managers, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying volume and value estimates. Primary field engagement combined structured interviews with secondary validation against hospital procurement databases, GPO contract filings, EMA vigilance reports, and national reimbursement catalogs. Bottom-up patient population modeling triangulated against top-down manufacturer shipment analysis to constrain estimate variance.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, material tier, stoma application, and end-user channel. CAGRs derived from fitted growth curves applied to installed base dynamics and replacement frequency trends. Reimbursement recalibration schedules under France's CEPS and Germany's G-BA, alongside MDR compliance cost absorption rates, served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical pricing, euro exchange rates, or healthcare expenditure growth would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and reimbursement stability. Cross-checking against EMA vigilance reporting trends and national health insurance expenditure data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Global Syringe Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Disposable Lead Wires Market