
 Europe Incontinence Devices and Ostomy Market | 2026-2036
Europe Incontinence Devices and Ostomy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Incontinence Devices and Ostomy Market Foresight
The premium catheter segment is repositioning away from commodity drainage bags through hydrophilic coatings and closed-system designs. Coloplast A/S leverages its silicone portfolio to dominate Nordic home care channels. Hollister Incorporated anchors its position through advanced skin barrier adhesives that reduce peristomal complications. Essity AB differentiates via private-label scale across European pharmacy retail networks.
Europe Incontinence Devices and Ostomy encompasses urine and fecal management systems including intermittent catheters with hydrophilic polymer coatings, one-piece and two-piece ostomy appliances with integrated charcoal filters, and drainage collection systems manufactured through extrusion blow-molding and thermoforming processes. These devices serve patients with neurogenic bladder, spinal cord injury, colorectal cancer, and inflammatory bowel disease across acute and community care settings. Urinary catheters lead volume due to aging-related bladder dysfunction prevalence, while skin barriers capture disproportionate margin pools through adhesive formulation specialization. Home care represents the fastest-growing end user channel as reimbursement shifts favor outpatient management across France and the Netherlands.
The EU Medical Device Regulation (MDR) and EMA oversight of companion diagnostics are elevating clinical evidence requirements for ostomy appliance certification. REACH compliance on phthalate-free materials is reshaping polyurethane and latex sourcing decisions for catheter manufacturers. Stakeholders must monitor reimbursement harmonization progress under cross-border healthcare directives and national health technology assessment divergences between Germany's G-BA and France's HAS.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing certification timelines and forcing manufacturers to rebuild clinical evidence portfolios for legacy ostomy appliances. This regulatory shock is accelerating consolidation among mid-tier suppliers unable to absorb notified body bottlenecks and biocompatibility testing costs.
Growth Catalysts
- MDR compliance mandates:Stricter clinical evidence requirements under EU MDR are filtering out marginal competitors and concentrating market share among established manufacturers with dedicated regulatory affairs teams.
- France home care reimbursement:HAS and regional health agencies are expanding catheter and appliance coverage for outpatient management, redirecting volume from acute settings to community channels.
- Hydrophilic polymer coatings:Advanced lubricious surface technologies are reducing urethral trauma incidence and extending dwell times for intermittent catheter users across Nordic markets.
Market Restraints
- Medical-grade silicone supply:European polymer converters face allocation constraints from specialty chemical suppliers, inflating raw material costs for ostomy barrier rings and catheter tubing extrusion.
- Notified body capacity:MDR-designated conformity assessment organizations in Germany and the Netherlands carry 18-24 month backlogs, freezing new product introductions for catheter manufacturers.
- Reusable intermittent catheters:Single-use plastic substitution campaigns in Belgium and Austria are threatening standard hydrophilic catheter volumes through environmental procurement criteria.
Strategic Opportunities
- Netherlands community nursing networks:Underpenetrated district nurse prescribing channels offer direct-to-patient appliance distribution outside pharmacy retail concentration.
- Closed-system catheter integration:Convergence of touch-free insertion technology with pre-lubricated hydrophilic coatings enables premium positioning in spinal cord injury rehabilitation centers.
- Cross-border healthcare directives:Reimbursement portability frameworks are unlocking patient mobility for ostomy care, creating service arbitrage between high-cost German and lower-cost Polish providers.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face 6-9 month queues at contract laboratories, delaying MDR technical documentation completion.
- Legacy ERP integration:Medical device manufacturers struggle to embed UDI (Unique Device Identification) traceability into existing manufacturing execution systems without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Incontinence Devices and Ostomy Market |
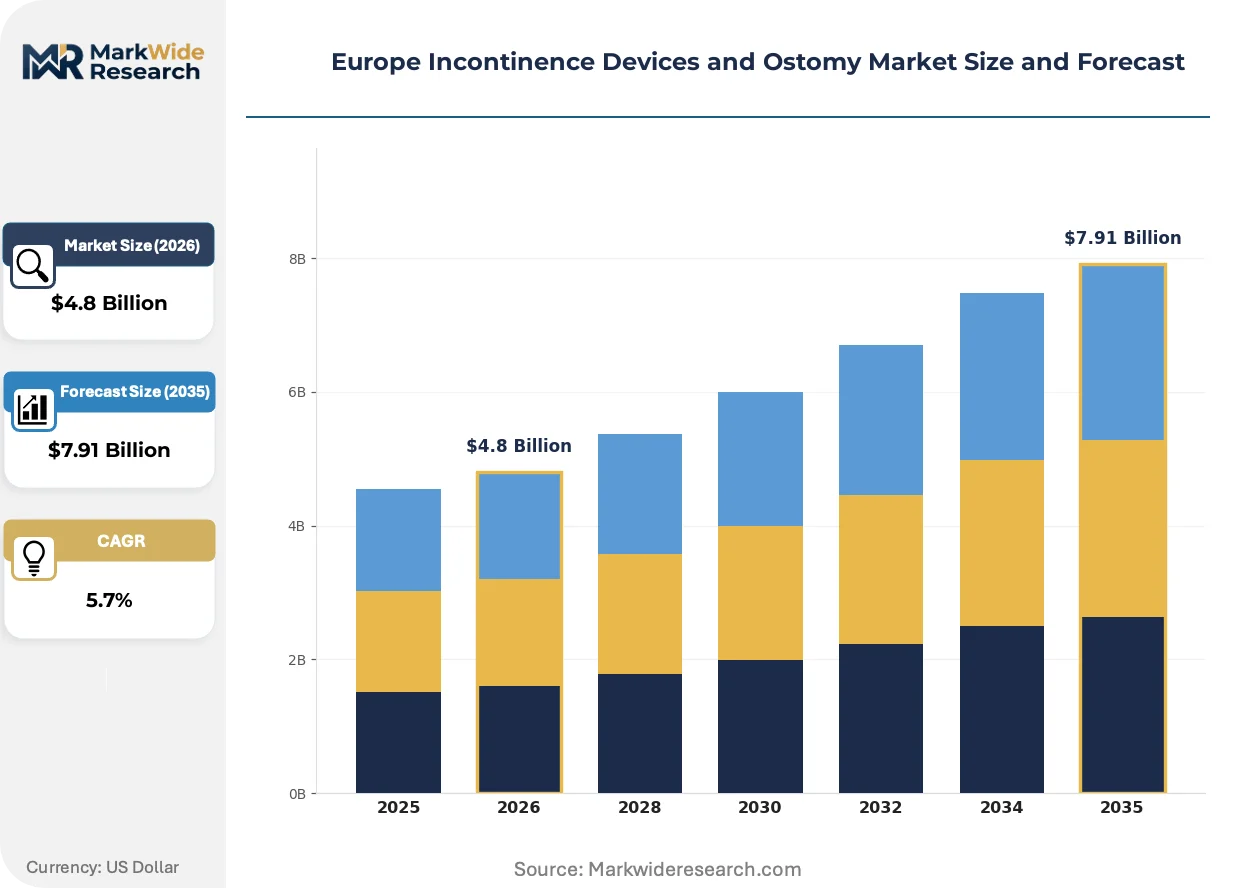
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urinary Catheters, Colostomy Bags, Drainage Bags, Skin Barriers End User: Home Care, Hospitals, Clinics, Long-Term Care Facilities Distribution Channel: Pharmacies, Online Retail, Medical Supply Stores, Direct Sales Material: Silicone, Latex, Polyurethane, Plastic |
| Companies Covered | Coloplast A/S, Hollister Incorporated, ConvaTec Group Plc, B. Braun Melsungen AG, Essity AB, Kimberly-Clark Corporation, Hartmann Group, Ontex BV, ABENA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Incontinence Devices and Ostomy Market Shifts & Advancements
Product architecture and distribution economics are diverging sharply as premium catheter technologies command price premiums while standard drainage systems commoditize through pharmacy retail consolidation.
Pre-lubricated hydrophilic intermittent catheters with integrated saline activation are overtaking traditional gel-based lubrication systems in spinal cord injury and multiple sclerosis patient populations. German rehabilitation clinics and French urology centers are standardizing on closed-system designs that eliminate hand-to-catheter contact. This technology compression is collapsing the mid-tier catheter segment into a bifurcated market of premium hydrophilic and economy PVC alternatives.
REACH Annex XVII restrictions on phthalate plasticizers are compelling catheter manufacturers to validate alternative plasticizers or shift toward thermoplastic elastomer formulations. ECHA substance evaluation workflows are extending material qualification timelines by 12-18 months for polyurethane suppliers. Pediatric and long-term indwelling catheter segments are most affected, with manufacturers accelerating DEHP-free compound submissions to maintain market access.
Hospital procurement consortia in the United Kingdom and Italy are consolidating ostomy appliance purchasing through framework agreements that bundle skin barriers, pouches, and accessories under single-supplier contracts. This buyer concentration is displacing fragmented pharmacy-based dispensing for stable stoma patients. The Netherlands and Belgium exhibit the most advanced tender aggregation, with regional hospital networks capturing 40-60% volume discounts against list pricing.
Europe Incontinence Devices and Ostomy Market Segmentation
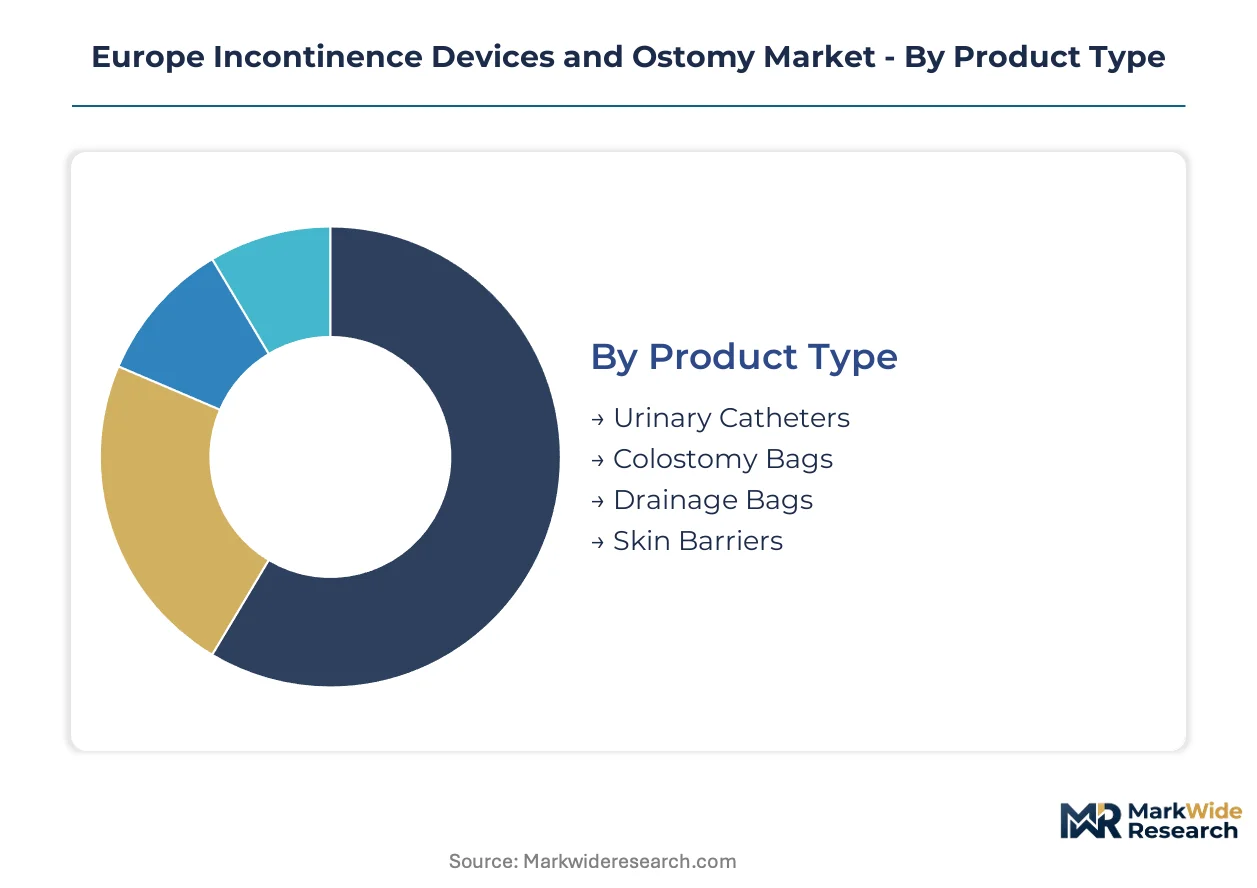
Product architecture and reimbursement pathways diverge sharply across patient settings in Europe, with hydrophilic coatings commanding premium positioning while standard drainage systems face procurement consolidation. Material qualification under REACH and MDR compliance timelines are reshaping competitive access by segment.
Product Type:
Clinical outcomes and reimbursement tiers separate premium hydrophilic systems from commodity alternatives.
- Urinary Catheters:Hydrophilic polymer coatings with integrated saline activation reduce urethral trauma in spinal cord injury patients across German rehabilitation networks. France's HAS expanded outpatient catheter reimbursement, redirecting volume from acute settings to home care channels.
- Skin Barriers:Advanced silicone and hydrocolloid adhesive formulations minimize peristomal skin complications in colorectal cancer patients. Nordic home care programs prioritize barrier rings with extended wear times, capturing disproportionate margin pools through formulation specialization.
- Colostomy Bags:One-piece and two-piece systems with integrated charcoal filters serve inflammatory bowel disease populations in Dutch community nursing networks.
- Drainage Bags:Extrusion blow-molded collection systems face tender aggregation pressure from UK hospital procurement consortia.
Volume sits with Urinary Catheters; growth tilts toward Skin Barriers.
End User:
Reimbursement portability and patient mobility are redistributing care delivery across institutional boundaries.
- Home Care:District nurse prescribing channels in the Netherlands and regional health agency coverage expansion in France are accelerating catheter and appliance distribution outside pharmacy retail concentration. Cross-border healthcare directives enable German patients to access lower-cost Polish ostomy services.
- Hospitals:Framework agreements in Italy and the United Kingdom bundle skin barriers, pouches, and accessories under single-supplier contracts, displacing fragmented dispensing for stable stoma patients.
- Clinics:French urology centers standardize on closed-system catheter designs that eliminate hand-to-catheter contact.
- Long-Term Care Facilities:Belgian and Austrian environmental procurement criteria threaten single-use hydrophilic catheter volumes through reusable plastic substitution campaigns.
Revenue concentrates in Hospitals; patient volume is climbing fastest in Home Care.
Distribution Channel:
Channel economics reflect regulatory traceability requirements and patient access convenience trade-offs.
- Pharmacies:Private-label scale dominates European pharmacy retail networks through Essity AB's continent-wide presence, capturing volume through reimbursement formulary alignment.
- Online Retail:Direct-to-patient platforms bypass traditional dispensing for intermittent catheter users with established prescriptions, accelerating in Nordic markets with high digital health adoption.
- Medical Supply Stores:Specialized ostomy retailers maintain service relationships for complex stoma care in Germany and Switzerland.
- Direct Sales:Manufacturer field teams serve spinal cord injury rehabilitation centers with closed-system catheter integration and training support.
Pharmacies retain volume leadership; Online Retail is gaining share fastest among younger patient cohorts.
Material:
REACH Annex XVII phthalate restrictions and MDR biocompatibility documentation are restructuring supplier qualification.
- Silicone:Medical-grade silicone faces allocation constraints from European polymer converters, inflating raw material costs for ostomy barrier rings and catheter tubing extrusion. Coloplast A/S leverages Nordic supply relationships to dominate home care channels.
- Polyurethane:Thermoplastic elastomer formulations are replacing DEHP-plasticized compounds for pediatric and long-term indwelling segments, with ECHA substance evaluation workflows extending qualification timelines.
- Latex:Allergen sensitivity concerns limit application to specific patient populations with compatibility requirements.
- Plastic:PVC alternatives serve economy catheter segments facing environmental procurement pressure in Belgium and Austria.
Silicone commands premium positioning; Polyurethane is expanding most quickly as DEHP-free substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European distribution for ostomy appliance logistics, while Eindhoven hosts advanced polymer coating research clusters serving catheter manufacturers across the continent.
Germany
Spinal cord injury rehabilitation centers in Berlin and Munich drive closed-system catheter standardization. The G-BA national health technology assessment body mandates outcome documentation for outpatient appliance reimbursement. North Rhine-Westphalia's Ruhr industrial corridor concentrates medical-grade silicone extrusion capacity for barrier ring production.
France
Regional health agencies in Île-de-France and Provence-Alpes-Côte d'Azur expanded HAS reimbursement for home-based catheter management. ANSM pharmacovigilance oversight elevates clinical evidence requirements for pediatric hydrophilic systems. Lyon hosts formulation specialists advancing hydrocolloid adhesive research for extended-wear skin barriers.
United Kingdom
NHS England procurement consortia in London and the Midlands bundle ostomy appliances under framework agreements displacing pharmacy dispensing. MHRA post-Brexit regulatory divergence creates parallel certification tracks alongside EU MDR. Greater Manchester's medical device cluster concentrates drainage bag blow-molding operations.
Netherlands
District nurse prescribing networks in the Randstad accelerate direct-to-patient appliance distribution outside retail pharmacy channels. Dutch environmental procurement criteria advance reusable intermittent catheter pilots threatening single-use volumes. Eindhoven's polymer research institutes collaborate with manufacturers on DEHP-free thermoplastic elastomer validation.
Poland
Cross-border healthcare directive portability enables German patients to access lower-cost ostomy services in Warsaw and Kraków medical centers. Polish reimbursement harmonization under EU patient mobility frameworks attracts volume from Western European markets. Silesia's emerging medical device manufacturing zone supplies economy catheter segments to Central European distribution networks.
Europe Incontinence Devices and Ostomy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across catheter coating and adhesive formulation segments. The vendor base concentrates among Nordic and North American multinationals with dedicated regulatory affairs infrastructure. Three archetypes dominate: integrated silicone processors, private-label scale operators, and specialized rehabilitation channel suppliers. Consolidation accelerates through M&A among mid-tier notified body-constrained manufacturers, while premium players expand capacity in hydrophilic coating application lines.
Within the integrated silicone processing tier, Coloplast A/S and Hollister Incorporated occupy positions defined by Nordic supply relationships and adhesive formulation specialization respectively. ConvaTec Group Plc exemplifies the diversified medical technology archetype with ostomy portfolios spanning barrier technologies. These three anchors represent distinct competitive vectors: geographic supply chain control, materials science differentiation, and multi-category clinical presence.
| Leading Market Players |
|---|
| Coloplast A/S |
| Hollister Incorporated |
| ConvaTec Group Plc |
| B. Braun Melsungen AG |
| Essity AB |
| Kimberly-Clark Corporation |
| Hartmann Group |
| Ontex BV |
| ABENA |
| Others |
Supply & Pricing Matrix
Captive silicone processing in Denmark and Germany anchors supply positions for premium ostomy barriers while simultaneously defending margin pools against commodity catheter imports. This backward integration into medical-grade polymer extrusion enables manufacturers to buffer raw material allocation shocks from European specialty chemical suppliers and sustain pricing power in hydrophilic coating segments.
Pricing Analysis
Outcome-linked reimbursement anchors value-based pricing for hydrophilic intermittent catheters in French and German spinal cord injury protocols. Three-tier pricing structure across premium hydrophilic, standard PVC, and economy uncoated levels separates clinical-grade coatings from basic drainage systems. Cost compression in standard catheter tiers intensifies because UK hospital procurement consortia aggregate volume under framework agreements. Long-term care facilities exhibit highest price sensitivity due to environmental procurement criteria, while rehabilitation centers accept premium positioning for closed-system designs.
Supply Chain Analysis
Freight cost differentials between Nordic silicone hubs and Central European compounding centers favor localized extrusion capacity for barrier ring production. Germany, Denmark, and the Netherlands concentrate medical-grade silicone supply for ostomy appliances and catheter tubing. Raw material flows draw from specialty polymer converters, hydrocolloid adhesive formulators, and DEHP-free plasticizer suppliers. Single-source vulnerability sits with notified body-designated conformity assessment organizations carrying extended certification backlogs. Distribution runs through hospital procurement consortia, pharmacy retail networks, and direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race into medical-grade silicone extrusion and hydrophilic coating application lines is reshaping competitive economics. Players are pursuing captive polymer supply to defend margin pools against raw material allocation constraints.
For Market Incumbents: Extend hydrophilic coating capacity in Nordic supply corridors to preempt allocation bottlenecks from European polymer converters. Deepen direct sales presence in Dutch district nurse networks before pharmacy retail consolidation hardens. MDR compliance mandates filter marginal competitors; accelerate biocompatibility documentation completion to capture stranded market share. For New Entrants and Emerging Players: EU MDR in Europe opens a window for specialized rehabilitation channel suppliers lacking legacy appliance portfolios requiring recertification. Target underpenetrated community nursing networks in Belgium and Austria with closed-system catheter training bundles. Reimbursement portability under cross-border healthcare directives enables service arbitrage positioning between German and Polish markets. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier manufacturers facing notified body capacity constraints and seeking regulatory affairs infrastructure. Long-term viability favors asset-light designers with coating specialization over capital-heavy extrusion operators. Watch ECHA substance evaluation timelines for DEHP-free compound approvals as inflection indicator for pediatric segment access.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation completion unlocks market access amid notified body bottlenecks. |
| Backward Integration into Silicone Extrusion | Captive polymer supply buffers raw material allocation shocks from European specialty chemical suppliers. |
| Hospital System Partnership | Framework agreements with UK and Italian procurement consortia displace fragmented pharmacy dispensing. |
| Reimbursement Strategy | HAS and G-BA outpatient coverage expansion redirects volume from acute settings to home care channels. |
| Software Companion Development | Digital adherence platforms for intermittent catheter users strengthen premium positioning in Nordic markets. |
Research Methodology
EMA guidance documents, ECHA substance evaluation workflows, and EU cross-border healthcare directive filings formed the secondary backbone for regulatory pathway mapping. Primary interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and district nurse prescribing leads validated demand-side assumptions. Bottom-up and top-down triangulation reconciled catheter volume estimates against ostomy appliance reimbursement data.
Bottom-up modeling anchored forecast outputs while top-down macro health expenditure trends provided boundary checks across the analysis window. Segmentation dimensions spanned product architecture, end-user setting, distribution channel, and material formulation compliance tier. CAGRs derived from patient population prevalence trajectories, reimbursement schedule adjustments, and technology substitution rates for hydrophilic versus standard catheter systems.
The model assumes a particular technology adoption path; alternative pathways for reusable intermittent catheter substitution would alter the outlook for single-use hydrophilic volumes. Forecasts reflect assumptions on MDR certification timeline resolution and REACH Annex XVII enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Gel Implants Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Snare Devices Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Implantable Collamer Lens Market
Medical Devices
Global Pessary Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market