
 Mortuary Bags Market | 2026-2036
Mortuary Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Mortuary Bags Market Intelligence
The gap between premium and commodity tiers is broadening as funeral homes demand reinforced polyethylene construction with heat-sealed seams while budget-constrained municipal agencies accept basic PVC alternatives. Mopec leverages its vertical integration into medical-grade polymer sourcing to sustain margin control across North American distribution. HYGECO anchors European demand through specialized cold-chain body bag systems for forensic applications. Classic Plastics Corporation competes on manufacturing scale, operating high-throughput extrusion lines that service bulk government contracts.
Mortuary bags are leak-resistant containment enclosures manufactured from polyethylene, PVC, or fabric composites, designed to transport human remains while preventing fluid egress and cross-contamination; specifications typically include tensile strength thresholds, zipper or heat-seal closure integrity, and compliance with biohazard handling protocols. Polyethylene formulations dominate volume due to cost efficiency and heat-seal compatibility, though biodegradable alternatives are gaining traction where environmental regulations tighten procurement criteria. Funeral homes represent the most stable demand channel, while hospitals drive specification upgrades through infection control committees that mandate higher-grade material certifications.
OSHA bloodborne pathogen standards and EPA medical waste regulations govern U.S. product specifications, requiring fluid-proof construction and proper labeling that elevates compliance costs for new entrants. The EU MDR and REACH frameworks increasingly influence material composition decisions for suppliers serving European funeral homes and hospital systems. Stakeholders must monitor evolving biodegradable certification requirements and regional procurement centralization trends that favor vendors with multi-standard compliance documentation.
Market Dynamics
OSHA bloodborne pathogen enforcement is compressing procurement cycles for polyethylene-based mortuary bags as funeral homes accelerate compliance-driven specification upgrades ahead of inspection schedules.
Growth Catalysts
- OSHA compliance deadlines:United States funeral homes face stepped-up enforcement of bloodborne pathogen standards, forcing replacement of non-compliant PVC inventory with heat-sealed polyethylene alternatives.
- Hospital infection control mandates:Infection control committees within North American health systems now require medical-grade polymer certifications for all mortuary transport materials.
- Biodegradable material R&D:European suppliers accelerate compostable polymer development as REACH frameworks tighten procurement criteria for municipal contracts.
Market Restraints
- Medical-grade resin concentration:Polyethylene feedstock supply clusters among Gulf Coast petrochemical producers, exposing bag manufacturers to hurricane-season disruption risk.
- REACH compliance costs:European chemical registration requirements impose documentation burdens that freeze smaller regional suppliers out of hospital procurement pools.
- Reusable transport alternatives:Some forensic pathology departments pilot stainless-steel containment systems for high-frequency caseload facilities, threatening disposable bag volume in niche segments.
Strategic Opportunities
- EU Green Deal alignment:Biodegradable certification pathways open preferential procurement status for suppliers achieving EN 13432 compostability validation.
- Cold-chain forensic expansion:Specialized insulated body bag systems for disaster victim identification and mass casualty events represent untapped specification tier.
- Direct hospital contracting:Bypassing traditional funeral home distribution through GPO-negotiated supply agreements captures infection-control-driven premium pricing.
Industry Challenges
- Heat-seal technician training:Quality assurance protocols require certified operators for medical-grade seam integrity, constraining production scaling.
- Multi-standard documentation:Suppliers serving both EPA medical waste and EU MDR jurisdictions must maintain parallel certification tracks, extending product launch timelines.
- Legacy PVC inventory stranding:Funeral homes holding pre-compliance stock face write-down pressure as OSHA inspection frequency intensifies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortuary Bags Market |
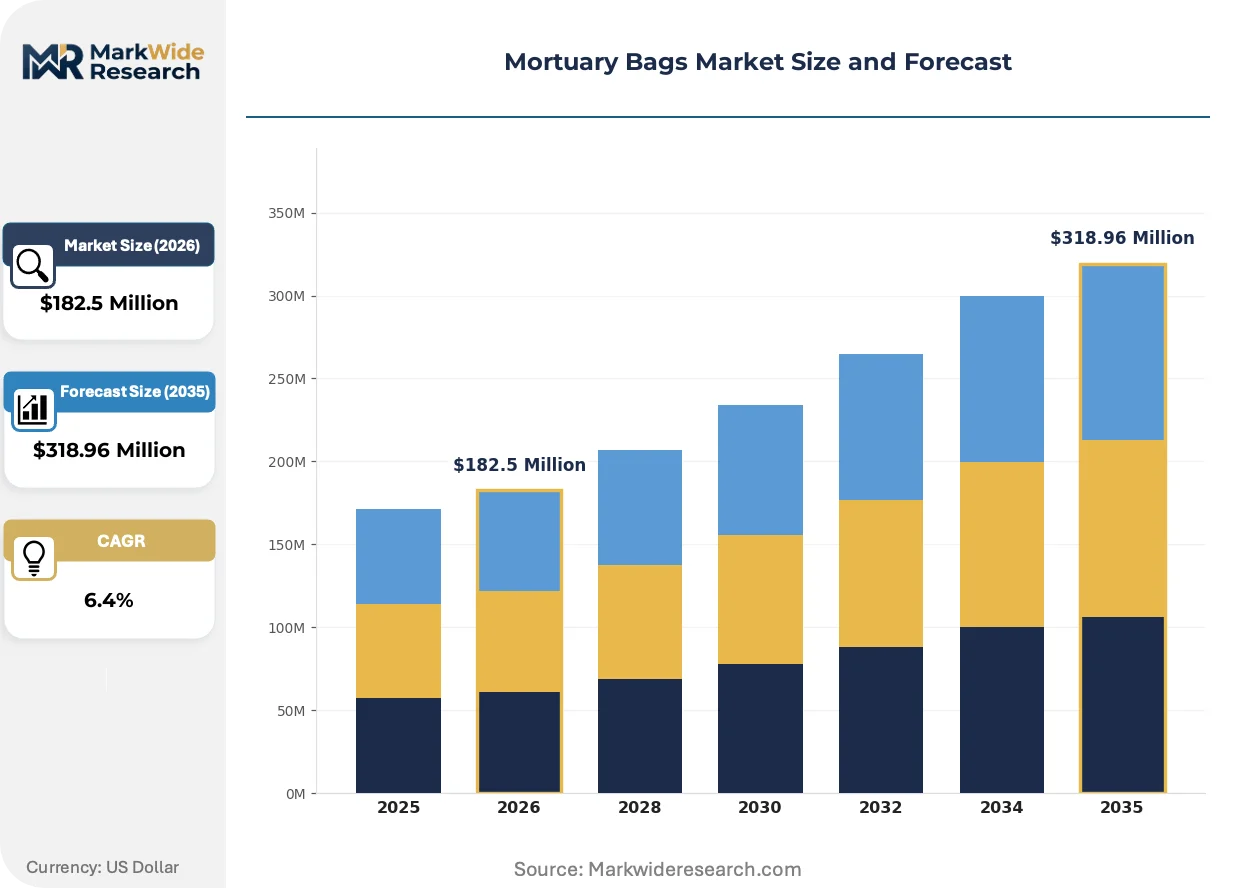
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $318.96 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Zipper Bags, Resealable Bags, Body Bags Material: Polyethylene, PVC, Fabric, Biodegradable End User: Funeral Homes, Hospitals, Medical Schools, Government Agencies Packaging Type: Rolls, Individually Packed, Bulk Packs, Custom |
| Companies Covered | Mopec, HYGECO, Classic Plastics Corporation, Peerless Plastics, CEABIS, Auden Funeral Supplies Limited, Flexmort, Isofroid, SmartChoice Funeral Supplies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortuary Bags Market Strategic Shifts & Innovations
Material science advances and procurement centralization are rewriting competitive boundaries as compliance requirements fragment product portfolios across regional regulatory regimes.
Biodegradable starch-polymer blends are rewriting supplier R&D priorities in Europe. German and Dutch funeral cooperatives pilot compostable mortuary bags for green burial programs. This material transition is compressing conventional polyethylene margin structures as municipalities embed environmental criteria in tender specifications.
REACH substance restrictions are tightening allowable plasticizer content in PVC formulations. European mortuary bag suppliers reformulate product lines to eliminate phthalate-based softening agents. Hospital systems in France and Belgium now require full material disclosure documentation, shifting procurement preference toward polyethylene alternatives with simpler chemical profiles.
Group purchasing organizations are consolidating funeral home and hospital procurement under unified infection-control standards. United States health systems negotiate enterprise-wide mortuary bag contracts that override traditional funeral home supplier relationships. This channel compression is visible most acutely in Midwestern states where Catholic health networks dominate regional mortality services.
Mortuary Bags Market Segmentation
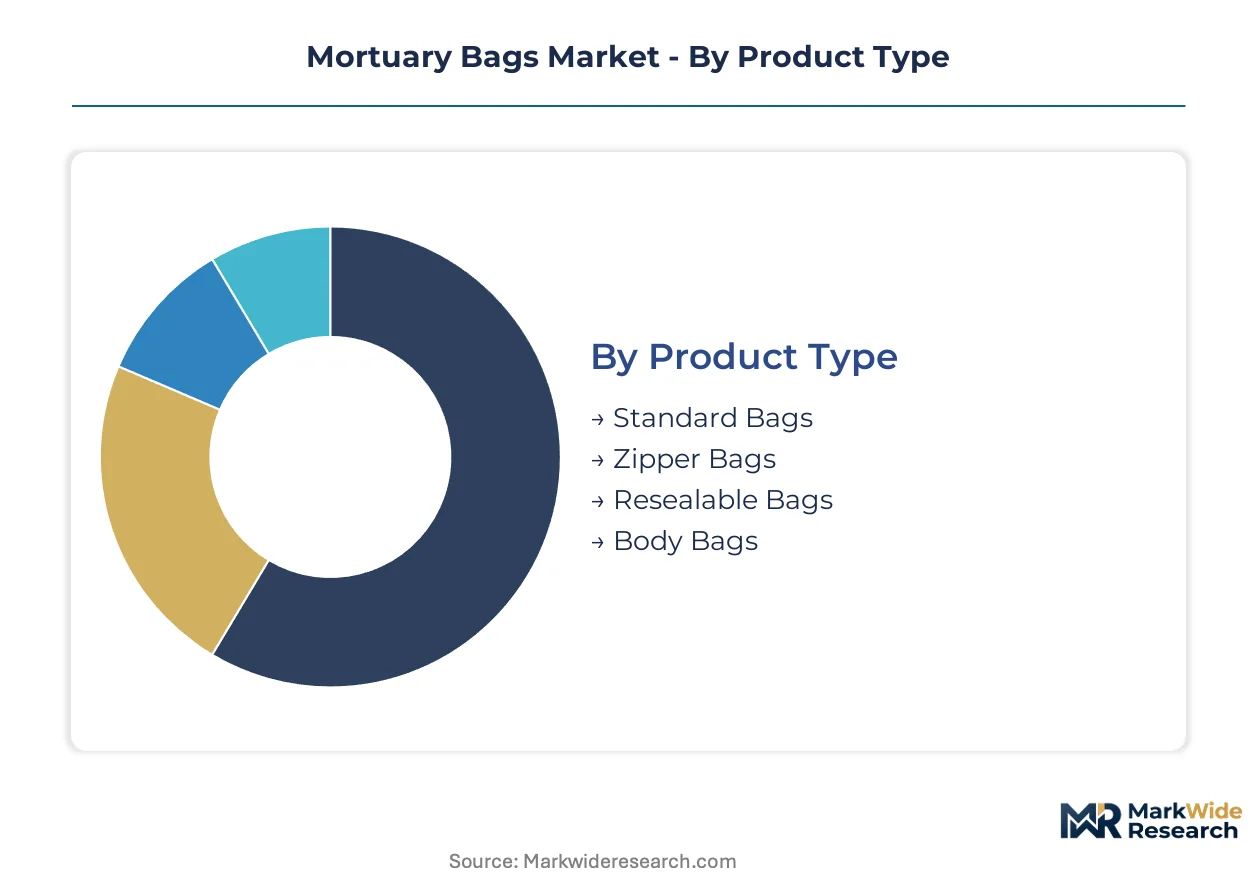
Mortuary bag procurement splits sharply between high-volume commodity contracts and premium specification tiers. Segmentation discipline reveals where compliance investments concentrate versus where price competition dominates procurement decisions.
Product Type:
Volume concentrates in basic containment designs while premium tiers command specification premiums through closure integrity and reusability features.
- Standard Bags:Heat-sealed polyethylene construction with welded seam integrity dominates hospital procurement under OSHA bloodborne pathogen protocols. United States health systems mandate these for all regulated medical waste transport, driving consistent replacement cycles.
- Zipper Bags:Mechanical closure systems with dual-track zipper mechanisms serve forensic pathology departments requiring repeated access for examination. German and Dutch municipal morgues specify these for disaster victim identification workflows where body integrity must be maintained across multiple handling stages.
- Resealable Bags:Adhesive-strip closure systems balance containment security with field accessibility for emergency medical services.
- Body Bags:Heavy-duty reinforced designs with integrated handles and rigging points serve military and mass casualty response applications.
Today's leader: Standard Bags. Tomorrow's challenger: Zipper Bags.
Material:
Feedstock selection determines regulatory compliance pathways and margin structures across funeral home and hospital channels.
- Polyethylene:Linear low-density formulations with medical-grade resin certification dominate North American volume. Heat-seal compatibility and fluid-proof performance satisfy EPA medical waste regulations while maintaining cost efficiency for high-turnover funeral home operations.
- Biodegradable:Starch-polymer blends with EN 13432 compostability validation are gaining procurement preference in European municipal contracts. REACH substance restrictions on conventional plasticizers accelerate this transition in France and Belgium where green burial programs embed environmental criteria.
- PVC:Phthalate-softened formulations face inventory stranding as REACH compliance deadlines eliminate legacy specifications.
- Fabric:Multi-layer composite materials with absorbent cores serve specialized military and disaster response applications.
Polyethylene holds current volume leadership. Biodegradable alternatives show the steepest expansion trajectory.
End User:
Procurement authority is shifting from traditional funeral home distributors toward centralized health system contracting.
- Funeral Homes:Steady demand from independent operators and consolidated chains drives polyethylene standard bag volume. OSHA compliance inspections accelerate replacement of pre-standardization inventory across United States facilities.
- Hospitals:Infection control committees now mandate medical-grade polymer certifications with full material disclosure documentation. Group purchasing organizations consolidate enterprise-wide contracts that override traditional supplier relationships in Midwestern Catholic health networks.
- Government Agencies:Municipal morgues and coroner's offices specify cold-chain compatible systems for forensic applications.
- Medical Schools:Cadaver handling programs require specialized containment for anatomical education and research transport.
Funeral homes anchor present demand. Hospital systems are capturing procurement authority fastest.
Packaging Type:
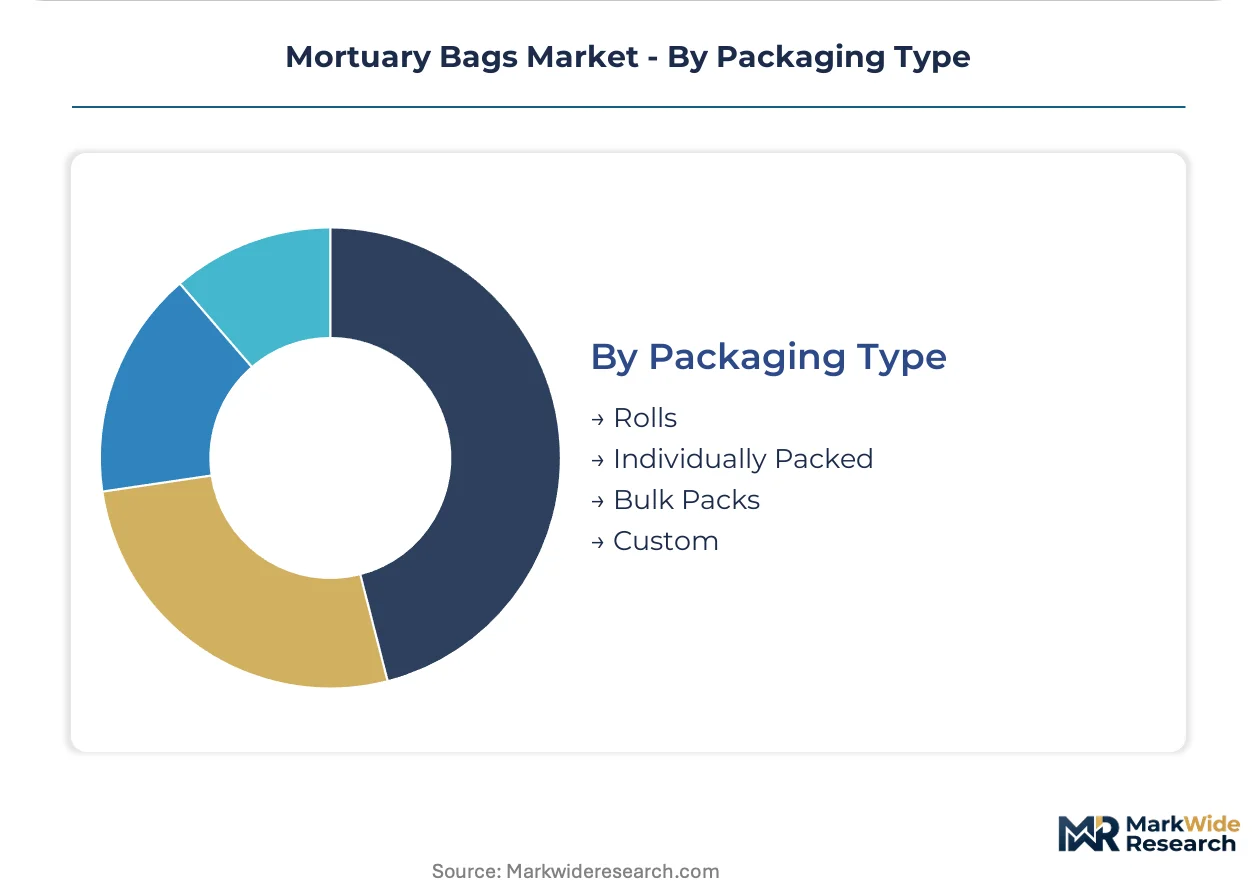
Distribution economics and inventory management requirements shape format selection across customer segments.
- Individually Packed:Sterile single-unit packaging with lot traceability satisfies hospital infection control mandates. United States health systems require this format for all regulated medical waste handling to maintain chain-of-custody documentation.
- Bulk Packs:Unboxed quantities in sealed outer containers serve high-volume funeral home operations with established storage protocols and rapid turnover requirements.
- Rolls:Continuous perforated formats reduce packaging waste for large-scale municipal procurement.
- Custom:Branded or specification-modified configurations serve institutional customers with proprietary handling protocols.
Individually packed formats dominate hospital procurement. Bulk packs retain funeral home cost advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mortuary bag procurement concentrates where hospital system consolidation and funeral home regulation enforcement create sustained specification demand. Workforce density in healthcare administration and funeral services drives regional market intensity.
United States
OSHA bloodborne pathogen enforcement compresses replacement cycles for polyethylene standard bags across independent funeral homes and consolidated chains. Hospital infection control committees in Midwestern Catholic health networks mandate medical-grade polymer certifications with full material disclosure. The Gulf Coast petrochemical corridor supplies medical-grade resin feedstock, though hurricane exposure creates seasonal supply vulnerability.
Germany
REACH substance restrictions accelerate the phase-out of phthalate-softened PVC formulations in municipal morgue procurement. Funeral cooperatives in North Rhine-Westphalia pilot compostable starch-polymer blends for green burial programs. The Eindhoven-Düsseldorf logistics cluster enables cold-chain distribution of specialized forensic body bag systems across Benelux markets.
France
Hospital systems in Île-de-France now require complete chemical composition documentation under strengthened EU MDR implementation. ANSM oversight of medical device classification elevates compliance costs for imported polyethylene alternatives. The Lyon-Grenoble polymer research corridor advances biodegradable certification pathways aligned with EU Green Deal procurement preferences.
United Kingdom
NHS procurement centralization drives enterprise-wide mortuary bag contracting that bypasses traditional funeral home distributors. Infection control mandates from NHS England accelerate specification upgrades in acute hospital trusts. The Midlands manufacturing belt hosts extrusion operations serving bulk government contracts with high-throughput production lines.
Japan
PMDA medical device registration requirements create documentation barriers for European and North American suppliers seeking hospital access. METI industrial standards for biohazard containment materials shape municipal procurement specifications. The Kansai region's funeral service concentration sustains demand for zipper-closure systems requiring repeated examination access.
Mortuary Bags Market Key Industry Players
Top-tier vendors anchor premium specification tiers, while mid-scale fabricators compete on polyethylene volume and regional compliance documentation. The vendor base splits between vertically integrated polymer processors and specialized medical-device contract manufacturers. Three archetypes dominate: Gulf Coast resin-integrated producers, European cold-chain forensic specialists, and Asian scale-driven exporters. Capacity expansion and strategic certification investments represent the primary competitive moves as multi-standard documentation requirements extend product launch timelines.
Among North American resin-integrated producers, Mopec exemplifies backward integration into medical-grade polymer sourcing that sustains margin control across distribution channels. HYGECO anchors European demand through specialized cold-chain systems, occupying a position within forensic application tiers. Classic Plastics Corporation represents scale-driven manufacturing archetypes with high-throughput extrusion capabilities serving bulk government procurement.
| Leading Market Players |
|---|
| Mopec |
| HYGECO |
| Classic Plastics Corporation |
| Peerless Plastics |
| CEABIS |
| Auden Funeral Supplies Limited |
| Flexmort |
| Isofroid |
| SmartChoice Funeral Supplies |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between medical-grade polyethylene and basic PVC alternatives manifests in both procurement premiums and feedstock sourcing configurations. Hospital systems in the United States mandate heat-sealed seam integrity with full OSHA bloodborne pathogen documentation, while municipal agencies accept lower-tier alternatives sourced through distributed petrochemical channels.
Pricing Analysis
Service bundling separates funeral home distributors offering compliance consulting from transactional commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth: medical-grade polymer certifications command 40-60% premiums over municipal-grade alternatives. Cost compression in the PVC tier intensifies because REACH substance restrictions strand legacy inventory. Group purchasing organizations exhibit lowest price sensitivity; independent funeral homes negotiate most aggressively on per-unit costs.
Supply Chain Analysis
Medical-grade polyethylene resin draws from Gulf Coast petrochemical producers, European polymer compounders, and Asian specialty chemical manufacturers. Linear low-density formulations hinge on alpha-olefin co-monomer availability and medical-device-grade extrusion equipment. Single-source vulnerability concentrates in hurricane-exposed Texas-Louisiana production corridors. Distribution runs through funeral home supply cooperatives, hospital group purchasing organizations, and direct government contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mortuary bag demand compounds steadily as OSHA inspection cycles and hospital infection control mandates drive predictable replacement revenue. Regulatory compliance creates durable competitive moats for certified suppliers.
For Market Incumbents: To counter biodegradable material displacement in European procurement, deepen backward integration into medical-grade resin sourcing and accelerate EN 13432 certification pathways. Channel control through GPO-negotiated supply agreements locks out price-competitive challengers in Midwestern health networks. Capacity addition in Gulf Coast corridors secures feedstock access against hurricane-season disruption. For New Entrants and Emerging Players: Compostable polymer formulation expertise offers entry into French and Dutch municipal contracts where environmental criteria tighten. The forensic cold-chain segment remains underpenetrated by generalist suppliers. Direct hospital contracting through infection-control committee engagement bypasses entrenched funeral home distribution relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-standard documentation requirements exceed smaller regional suppliers' compliance budgets. Five-to-ten-year viability favors vertically integrated producers with captive polymer supply and dual EPA-EU certification tracks. The signal to watch is REACH substance restriction expansion accelerating PVC inventory stranding across European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Resin | Captive polyethylene supply insulates margin control against Gulf Coast petrochemical volatility. |
| EN 13432 Compostability Certification | Biodegradable validation unlocks preferential procurement status under EU Green Deal frameworks. |
| Cold-Chain Forensic System Development | Specialized insulated body bags capture disaster victim identification and mass casualty specifications. |
| GPO-Negotiated Hospital Contracts | Enterprise-wide supply agreements override traditional funeral home distribution in consolidated health systems. |
| Heat-Seal Technician Certification Programs | Quality assurance training constrains competitor production scaling while securing seam integrity premiums. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged funeral home procurement directors, hospital infection control committee members, GPO contracts managers, and biomedical engineering leads. Secondary validation drew from OSHA enforcement records, EPA medical waste regulations, EU MDR documentation requirements, and REACH substance restriction databases. Bottom-up demand modeling triangulated against top-down polymer feedstock consumption patterns.
Segment-weighting distributed volume across product type, material formulation, end-user channel, and packaging configuration dimensions. Growth trajectories across the analysis window derived from replacement cycle analysis, compliance deadline scheduling, and procurement centralization trends. Hospital system consolidation patterns and biodegradable certification adoption curves served as industry-specific forecast inputs.
The model holds under steady regulatory enforcement and stable resin supply conditions; deviation in REACH substance restriction timing or Gulf Coast petrochemical disruption would shift replacement cycle assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Global Lancets Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Hospital Consumables Market