
 Flexible Packaging for Healthcare Market | 2026-2036
Flexible Packaging for Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Packaging for Healthcare Market Analysis
Subscription-based technical support for serialization compliance is expanding how packaging vendors monetize their relationships with pharmaceutical clients. Amcor plc leverages its integrated film extrusion network to control substrate quality from resin to finished pouch. Berry Global anchors North American capacity through multi-site blown film operations serving regional drug manufacturers. Constantia Flexibles specializes in cold-form foil laminates for moisture-sensitive APIs, occupying a defensible niche in European pharmaceutical supply chains.
Flexible packaging for healthcare comprises multi-layer polymer, foil, or paper-based structures engineered to provide barrier protection against moisture, oxygen, and light while accommodating sterilization methods such as gamma irradiation or ethylene oxide treatment. These materials serve primarily to maintain drug efficacy, extend shelf life, and enable patient-compliant dosing formats across distributed care settings. Blister packs lead pharmaceutical dispensing formats due to their compatibility with high-speed thermoforming and child-resistant compliance requirements. Stand-up pouches represent the fastest-growing configuration as nutraceutical brands adopt resealable formats for powder and liquid supplements. Roll stock sustains margin pools among converters serving automated form-fill-seal operations for medical device kits.
The FDA enforces strict extractables and leachables profiling under container closure system guidelines, compelling suppliers to invest in analytical chemistry capabilities and documented material traceability. The European Medicines Agency applies CE marking and Medical Device Regulation requirements to sterile barrier systems, creating divergent compliance pathways for multinational suppliers. ISO 11607 standards govern sterile barrier performance validation, directly influencing material selection and seal integrity testing protocols. Stakeholders must monitor how evolving sustainability mandates from the EU Green Deal and state-level extended producer responsibility laws reshape polymer sourcing decisions without compromising barrier performance.
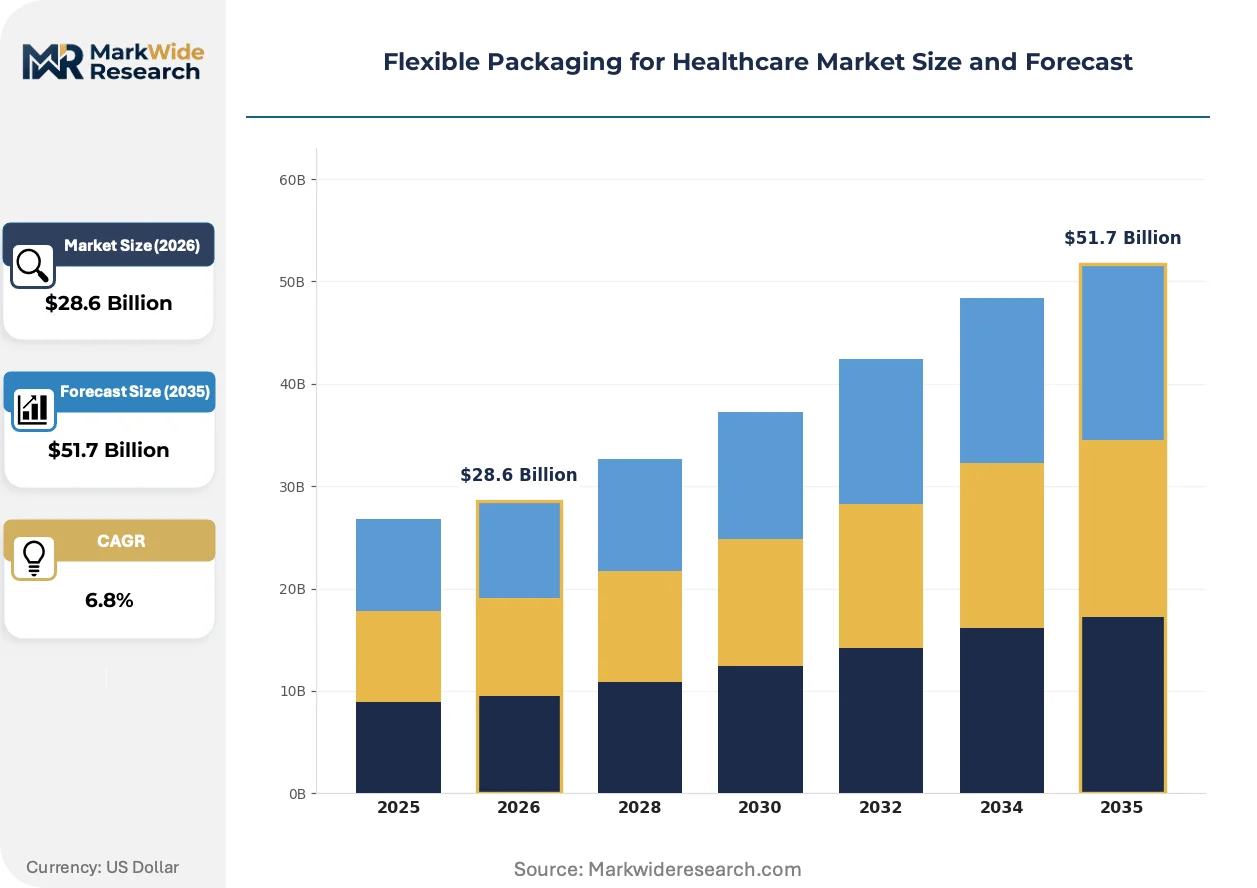
Market Dynamics
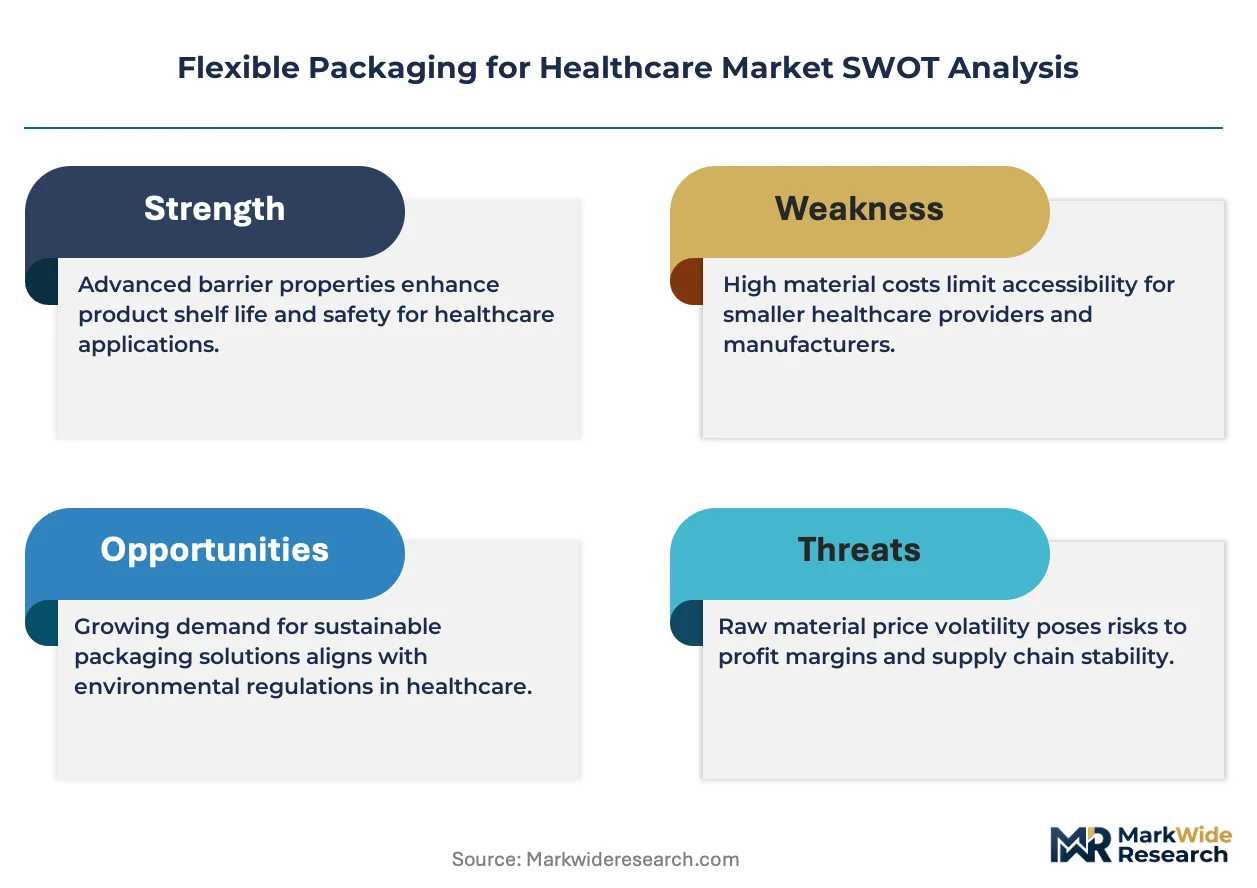
Barrier-enhanced pouch formats are displacing rigid containers as pharmaceutical manufacturers pursue unit-dose compliance and cold-chain efficiency. FDA extractables and leachables testing protocols are forcing material requalification across substrate supply chains.
Growth Catalysts
- EMA Medical Device Regulation:Sterile barrier system requirements under MDR are accelerating validation investments for foil-laminate converters serving European pharmaceutical distribution.
- Gamma irradiation compatibility:Polymer structures engineered for terminal sterilization are capturing share from ethylene oxide-dependent formats in biologics packaging.
- German contract packaging concentration:Central European pharmaceutical logistics hubs are consolidating procurement through multi-year supply agreements with regional film extruders.
Market Restraints
- Ethylene oxide emission restrictions:EPA and state-level air quality regulations are constraining sterilization capacity for traditional medical device pouch formats.
- Specialty resin supply concentration:Cyclic olefin copolymer and high-barrier nylon feedstocks depend on concentrated Asian petrochemical production.
- Aluminum foil substitution limits:Cold-form blister applications lack technically viable polymer-only alternatives for oxygen transmission rates below 0.01 cc/m²/day.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO quality mandate alignment is creating qualification demand for export-compliant barrier films among domestic converters.
- Resealable stand-up pouch formats:Nutraceutical powder and liquid supplement brands are adopting child-resistant zipper technologies previously limited to food applications.
- EU Green Deal polymer sourcing mandates:Mechanical recycling content requirements are opening specification windows for chemically recycled polyolefin structures in secondary packaging tiers.
Industry Challenges
- Analytical chemistry talent scarcity:Extractables profiling under ISO 10993-18 requires mass spectrometry specialists that contract laboratories struggle to retain.
- Validation timeline compression:Accelerated stability studies for material changes are colliding with 24-month shelf-life demonstration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Packaging for Healthcare Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Blister Packs, Roll Stock, Sachets Material: Polyethylene, Polypropylene, Foil, Paper End User: Hospitals, Pharmacies, Clinics, Research Laboratories Application: Medical Devices, Pharmaceuticals, Nutraceuticals, Diagnostics |
| Companies Covered | Amcor plc, Berry Global, WestRock Company, Sonoco Products Company, Sealed Air, Mondi, Huhtamaki, Constantia Flexibles, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Packaging for Healthcare Market Emerging Trajectories
Multi-layer coextrusion and digital printing technologies are compressing development cycles for pharmaceutical packaging formats. Sustainability compliance is becoming inseparable from barrier performance specification.
High-barrier coextruded films with embedded desiccant layers are consolidating moisture protection and structural integrity into single-substrate solutions. Biologics manufacturers in Switzerland and Germany are specifying these structures for monoclonal antibody vial overwrap. The technology is consolidating previously separate pouch and canister desiccant supply chains into unified material procurement.
REACH SVHC disclosure requirements are expanding documented substance reporting throughout polymer additive supply chains. European converters must now map plasticizer and slip agent composition back to resin batch records. Cold-form foil laminate producers serving moisture-sensitive APIs face the steepest compliance cost escalation.
Hospital and pharmacy buying groups are unbundling technical support from material supply contracts. Pharmaceutical procurement teams in the United States are negotiating standalone serialization compliance subscriptions with packaging vendors. This purchasing pattern is most visible among mid-size generic drug manufacturers lacking in-house track-and-trace infrastructure.
Flexible Packaging for Healthcare Market Segmentation
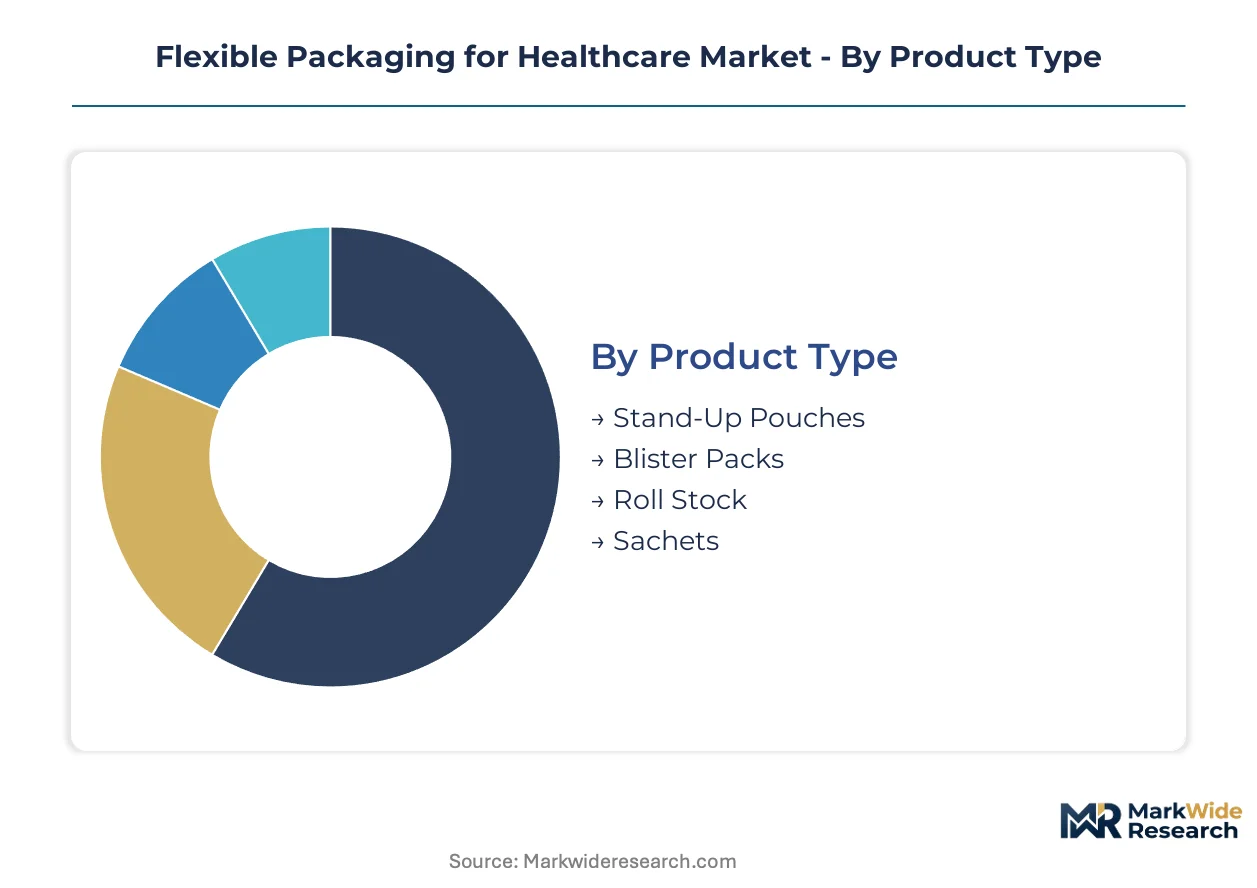
Flexible packaging configurations in healthcare serve distinct sterilization, dispensing, and compliance workflows. Material selection and format geometry determine barrier performance, regulatory pathway, and total cost of ownership across pharmaceutical and medical device supply chains.
Product Type:
Format transitions follow sterilization method shifts and patient compliance requirements rather than pure cost optimization.
- Blister Packs:Thermoformed polymer or cold-form foil cavities sealed to lidding material provide unit-dose integrity and child-resistant compliance. Demand concentrates in Germany and Switzerland where high-speed pharmaceutical lines require validated forming and sealing consistency for moisture-sensitive oral solids.
- Stand-Up Pouches:Gusseted bottom structures with resealable closures accommodate powder supplements and liquid nutraceuticals. German contract packaging organizations are specifying these formats for Central European distribution networks serving direct-to-consumer supplement brands.
- Roll Stock:Continuous web substrates fed into automated form-fill-seal equipment support medical device kit packaging and hospital supply centralization.
- Sachets:Small-format sealed pouches deliver single-use diagnostic reagents and unit-dose topical formulations in clinic and field settings.
Volume placements concentrate in Blister Packs; the faster expansion belongs to Stand-Up Pouches.
Material:
Barrier specifications and sterilization compatibility drive material substitution cycles more than commodity resin pricing.
- Foil:Aluminum laminates deliver oxygen transmission rates below 0.01 cc/m²/day for moisture-sensitive APIs. Cold-form applications in Swiss and German pharmaceutical manufacturing lack polymer-only alternatives at equivalent barrier performance.
- Polyethylene:LDPE and LLDPE layers provide seal integrity and puncture resistance in gamma-irradiation-compatible pouch structures. Biologics manufacturers are specifying these polymers for terminal sterilization formats displacing ethylene oxide-dependent alternatives.
- Polypropylene:Oriented PP films offer clarity and stiffness for blister lidding and diagnostic device visibility requirements.
- Paper:Bleached kraft and medical-grade papers serve sterilization wrap and secondary packaging where breathability and sustainability positioning outweigh barrier demands.
Revenue pools favor Foil for high-value pharmaceutical applications; Polyethylene captures the steepest expansion trajectory from biologics packaging conversion.
End User:
Procurement sophistication and validation requirements segment demand across institutional settings.
- Pharmacies:Retail and hospital pharmacy operations drive unit-dose compliance packaging for medication adherence programs. US pharmacy buying groups are unbundling technical support from material supply contracts, creating standalone serialization compliance subscriptions.
- Hospitals:Central sterile supply departments specify sterile barrier systems validated to ISO 11607 for surgical kit and implant packaging.
- Clinics:Outpatient settings generate demand for simplified dispensing formats and point-of-care diagnostic pouch configurations.
- Research Laboratories:Clinical trial material packaging requires documented batch traceability and stability data for investigational drug supplies.
Contract value concentrates in Pharmacies; validation complexity peaks with Research Laboratories.
Application:
Regulatory pathway divergence separates pharmaceutical and medical device packaging specifications.
- Pharmaceuticals:Container closure system validation under FDA extractables and leachables guidelines dominates material qualification protocols. EMA Medical Device Regulation requirements are accelerating sterile barrier investments for foil-laminate converters serving European distribution.
- Medical Devices:Sterile barrier systems for implants and surgical instruments require seal integrity demonstration and accelerated aging validation per ISO 11607.
- Nutraceuticals:Powder and liquid supplement brands are adopting child-resistant zipper technologies from food packaging, expanding resealable stand-up pouch specifications.
- Diagnostics:Point-of-care test kits and reagent packaging demand moisture barrier performance with ambient storage stability.
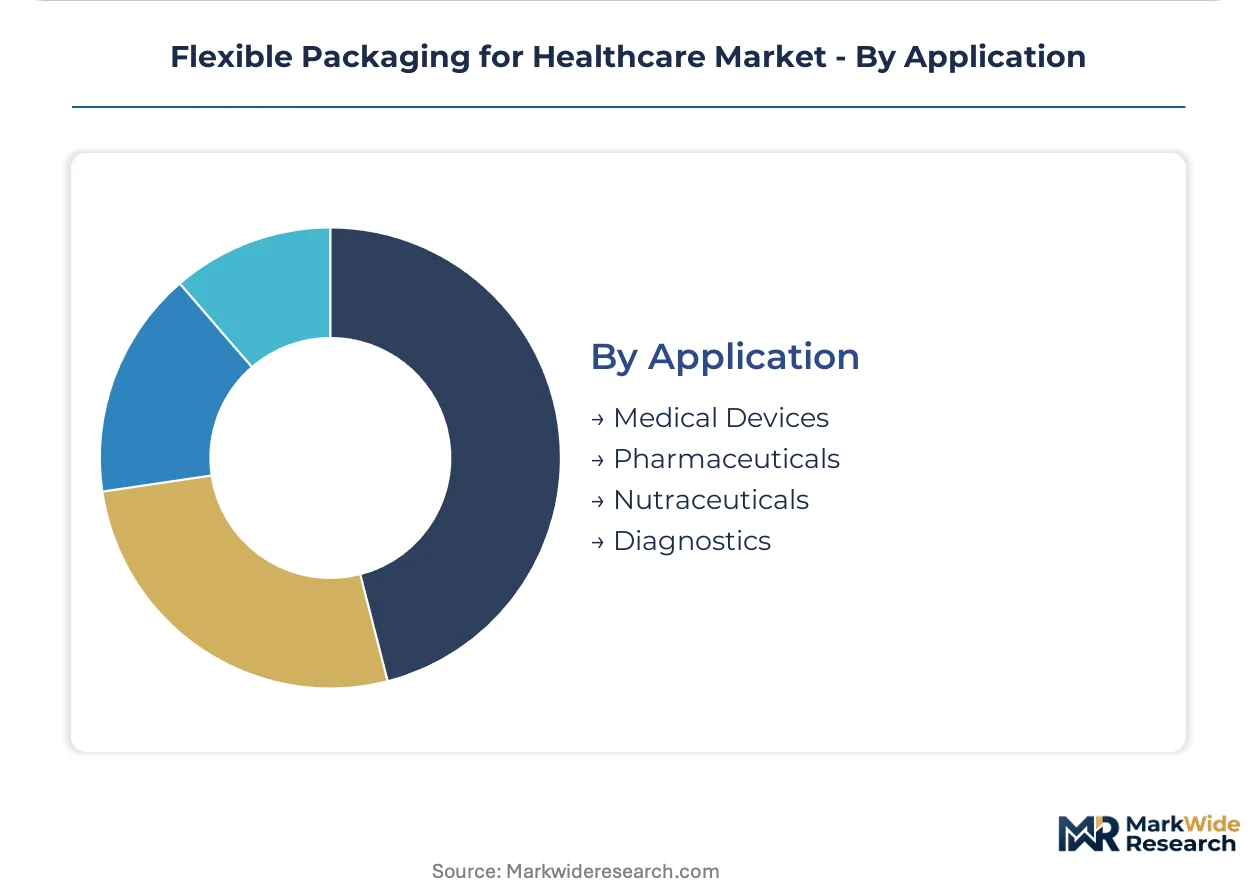
Specification intensity clusters in Pharmaceuticals; format innovation originates in Nutraceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors European pharmaceutical packaging demand through Novartis and Roche headquarters operations driving barrier film specifications. German contract packaging corridors radiate from this Swiss hub into Central European distribution networks. Indian pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad are accelerating qualification demand for export-compliant barrier substrates.
United States
FDA extractables and leachables enforcement is compelling material requalification across substrate supply chains. Pharmacy buying groups in the Midwest and Southeast are unbundling technical support from material contracts. Boston's biologics manufacturing corridor specifies gamma-irradiation-compatible pouch structures for terminal sterilization formats.
Germany
EMA Medical Device Regulation requirements are accelerating sterile barrier validation investments for foil-laminate converters. Contract packaging organizations in North Rhine-Westphalia serve Central European pharmaceutical distribution through multi-year supply agreements. The Rhine-Main logistics hub concentrates procurement for moisture-sensitive API packaging.
Switzerland
Swissmedic oversight of sterile barrier systems drives specification intensity for monoclonal antibody vial overwrap applications. REACH SVHC disclosure requirements are expanding documented substance reporting throughout polymer additive supply chains. Basel's pharmaceutical headquarters operations anchor high-barrier coextruded film demand.
India
CDSCO quality mandate alignment is creating qualification demand for export-compliant barrier films among domestic converters. Pharmaceutical manufacturing expansion in Hyderabad and Ahmedabad requires validated forming and sealing consistency. Western India packaging corridors are consolidating procurement through regional film extruder relationships.
China
NMPA container closure system guidelines are reshaping material qualification protocols for multinational pharmaceutical packaging. Yangtze River Delta converters serve domestic biologics manufacturers adopting gamma-irradiation-compatible formats. Shanghai's pharmaceutical logistics hub concentrates demand for high-barrier nylon and cyclic olefin copolymer structures.
Flexible Packaging for Healthcare Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across substrate specification and validation services. The vendor base separates between integrated film extruders controlling resin-to-pouch quality and specialized converters purchasing roll stock. Three archetypes dominate: multi-site blown film operators, cold-form foil laminate specialists, and subscription-based technical support providers. Capacity expansion in gamma-irradiation-compatible polymers and strategic partnerships for desiccant-embedded coextrusion represent the dominant competitive vectors.
Within the integrated extrusion tier, Amcor plc and Berry Global exemplify capital-heavy positioning through captive film production networks. Constantia Flexibles occupies a specialist position in European pharmaceutical supply chains. These three anchors represent distinct strategic postures: global multi-site coverage, North American regional density, and defensible niche concentration in moisture-sensitive API formats.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| WestRock Company |
| Sonoco Products Company |
| Sealed Air |
| Mondi |
| Huhtamaki |
| Constantia Flexibles |
| 3M |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up converters across Germany and Switzerland have compressed supplier margins while consolidating procurement leverage among pharmaceutical contract packaging organizations. This ownership pattern concentrates pricing power downstream and forces upstream film extruders into multi-year supply agreements with thin margin buffers.
Pricing Analysis
Throughput-based pricing anchors flexible packaging contracts in the healthcare sector, with converters charging per validated production run rather than pure material weight. Price differentiation separates FDA-validated barrier films from standard medical-grade substrates, with certification tier and volume scale driving tiered contract structures. Cost compression in standard polyethylene pouch formats is intensifying because biologics manufacturers are consolidating supplier panels. Mid-size generic drug manufacturers exhibit the highest price sensitivity due to limited in-house serialization infrastructure, while Swiss monoclonal antibody producers prioritize barrier performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired pharmaceutical returns and recalled medical device kits are forcing converters to maintain traceable batch records back to resin extrusion lots. Raw material supply concentrates in Germany for foil-laminate production, China for high-barrier nylon and cyclic olefin copolymer feedstocks, and the United States for gamma-irradiation-compatible polyethylene structures. The supply chain draws from concentrated Asian petrochemical production for specialty resins, creating single-source vulnerability during geopolitical trade disruptions. Distribution runs through Central European logistics hubs radiating from Basel and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible packaging for healthcare market has become a vertical-integration race where control over film extrusion networks determines margin capture and regulatory qualification speed. Players are pursuing backward integration into resin compounding to secure batch traceability for FDA extractables documentation.
For Market Incumbents: Cement market position by acquiring regional contract packaging organizations in Germany to lock in multi-year offtake commitments for barrier-enhanced pouch capacity. Expand captive film extrusion networks into gamma-irradiation-compatible polymer structures before EPA ethylene oxide restrictions accelerate format conversion. The threat of analytical chemistry talent scarcity in mass spectrometry specialists requires immediate investment in ISO 10993-18 compliant laboratory capabilities.
For New Entrants and Emerging Players: CDSCO quality mandate alignment in India opens a window for domestic converters to capture qualification demand from Hyderabad and Ahmedabad pharmaceutical manufacturing clusters. Target resealable stand-up pouch formats for nutraceutical powder brands adopting child-resistant zipper technologies from food packaging applications. A go-to-market angle anchored in subscription-based serialization compliance services bypasses capital-intensive film extrusion requirements.
For Investors and Strategic Acquirers: Subscription unbundling by US pharmacy buying groups is the leading indicator that technical support monetization will separate winning vendors from commodity converters. The five-to-ten year viability window favors asset-light designers with regulatory validation expertise over capital-heavy extruders facing resin price volatility. Target acquisition profiles should emphasize cold-form foil laminate specialists with documented REACH SVHC compliance. Monitor EMA Medical Device Regulation enforcement intensity as the inflection signal for sterile barrier validation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of batch-traceable polymers satisfies FDA extractables documentation requirements for pharmaceutical clients. |
| Gamma Irradiation Capacity Expansion | Terminal sterilization compatibility displaces ethylene oxide-dependent formats constrained by EPA emission regulations. |
| Desiccant-Embedded Coextrusion Partnership | Unified material procurement consolidates previously separate pouch and canister desiccant supply chains for biologics manufacturers. |
| Subscription-Based Serialization Services | Standalone compliance subscriptions monetize technical support relationships with mid-size generic drug manufacturers. |
| REACH SVHC Compliance Documentation | Documented substance reporting throughout polymer additive supply chains protects European converter market access. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this flexible packaging for healthcare market analysis. Primary interviews with pharmaceutical packaging engineers, contract manufacturing organization procurement directors, sterile barrier validation specialists, and FDA regulatory affairs consultants combined with secondary validation from FDA container closure system guidance documents, EMA Medical Device Regulation submissions, and ISO 11607 certification databases. Bottom-up modeling of film extrusion capacity and top-down triangulation against pharmaceutical packaging expenditure patterns ensured cross-verification.
Segmentation granularity extended to product type, material substrate, sterilization method compatibility, and end-user procurement sophistication across the projection horizon. CAGRs were derived from validated formation and sealing consistency requirements for moisture-sensitive APIs, gamma irradiation adoption curves displacing ethylene oxide formats, and nutraceutical resealable pouch format penetration. Forecast inputs incorporated CDSCO export compliance qualification timelines, EU Green Deal polymer sourcing mandate implementation, and hospital pharmacy buying group consolidation patterns.
The model assumes a particular technology adoption path; alternative pathways for aluminum foil substitution in cold-form blister applications would alter the outlook if polymer-only barriers achieve oxygen transmission rates below 0.01 cc/m²/day. Forecasts reflect assumptions about EMA MDR enforcement continuity, specialty resin supply chain stability, and analytical chemistry laboratory capacity expansion. Practitioners should monitor EPA ethylene oxide emission regulation tightening, REACH SVHC list expansion, and Indian pharmaceutical manufacturing cluster growth rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Enteral Syringes Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Amniotic Products Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
GCC Intravenous Solutions Market