
 Tongue Depressors Market | 2026-2036
Tongue Depressors Market Size, Share, and Industry Trends Forecast 2026-2036
Tongue Depressors Market Outlook
The EU Green Deal is decoupling European hospital procurement from petroleum-based plastic disposables. Medline Industries leverages its vertically integrated wood sourcing to sustain cost advantages across Nordic markets. Puritan Medical Products anchors North American supply through its Maine-based birchwood milling operations. B. Braun SE differentiates via sterilization-ready metal depressors targeting German dental chains.
Tongue depressors are flat, blade-shaped instruments, typically measuring 150 mm by 18 mm, manufactured from white birchwood, polystyrene, or stainless steel, designed to depress the tongue for oral cavity examination during diagnostic or educational procedures. Wooden variants dominate volume due to biodegradability and low per-unit cost, while plastic depressors retain share in pediatric applications where splinter resistance matters. Dental end users command premium positioning as infection control protocols in Germany, France, and Japan mandate single-patient use with documented material traceability.
The FDA regulates tongue depressors as Class I medical devices under 21 CFR 880.6230, requiring adherence to biocompatibility and sterility standards, while the EU Medical Device Regulation (MDR) imposes stricter post-market surveillance and Unique Device Identification (UDI) obligations. ISO 15223-1 labeling requirements and REACH substance restrictions further constrain material choices for manufacturers accessing European markets. Stakeholders must monitor evolving extended producer responsibility frameworks in France and Germany that will soon assign end-of-life disposal costs directly to instrument makers.
Market Dynamics
The EU Green Deal is forcing material substitution across European hospital supply chains, decoupling procurement from petroleum-based plastic disposables and redirecting volume toward sustainably sourced birchwood alternatives. This regulatory pressure intersects with FDA single-use device guideline updates to reshape competitive positioning.
Growth Catalysts
- EU Green Deal procurement mandates:European hospitals must eliminate petroleum-based plastic disposables from contracted supply lists, creating guaranteed demand pull for certified biodegradable alternatives.
- German outpatient dental standardization:Dental networks across Bavaria and North Rhine-Westphalia mandate autoclave-compatible instruments with full material traceability, locking in premium single-use volumes.
- REACH substance restrictions:The ECHA framework constrains plasticizer formulations in polystyrene variants, accelerating hospital conversion to wooden substitutes ahead of compliance deadlines.
Market Restraints
- Birchwood input cost volatility:Nordic pulp supply fluctuates with forestry harvest cycles and energy costs for kiln-drying operations, compressing margin stability for non-integrated manufacturers.
- Supply concentration in Maine and Nordic regions:North American birchwood milling clusters in a single U.S. state, creating geographic vulnerability to weather disruptions and labor constraints.
- Polystyrene splinter resistance in pediatric use:Plastic retains structural advantage where tongue trauma risk must be minimized, limiting wooden substitution in children's hospitals.
Strategic Opportunities
- Extended producer responsibility frameworks:France and Germany will soon assign end-of-life disposal costs directly to instrument makers, rewarding early movers with closed-loop collection infrastructure.
- Metal depressor sterilization services:Stainless steel variants enable rental-and-sterilize models for high-volume dental chains, capturing recurring revenue streams beyond disposable unit economics.
- Japanese dental clinic consolidation:METI-backed clinic network mergers create centralized procurement entities with standardized infection control protocols favoring traceable single-use instruments.
Industry Challenges
- UDI compliance timeline compression:The EU MDR mandates Unique Device Identification implementation across all Class I devices, requiring label system overhauls and database integration for wooden and plastic variants alike.
- ISO 15223-1 symbol validation:Manufacturers must recertify labeling schemes for international markets, creating documentation bottlenecks that delay product launches in export channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tongue Depressors Market |
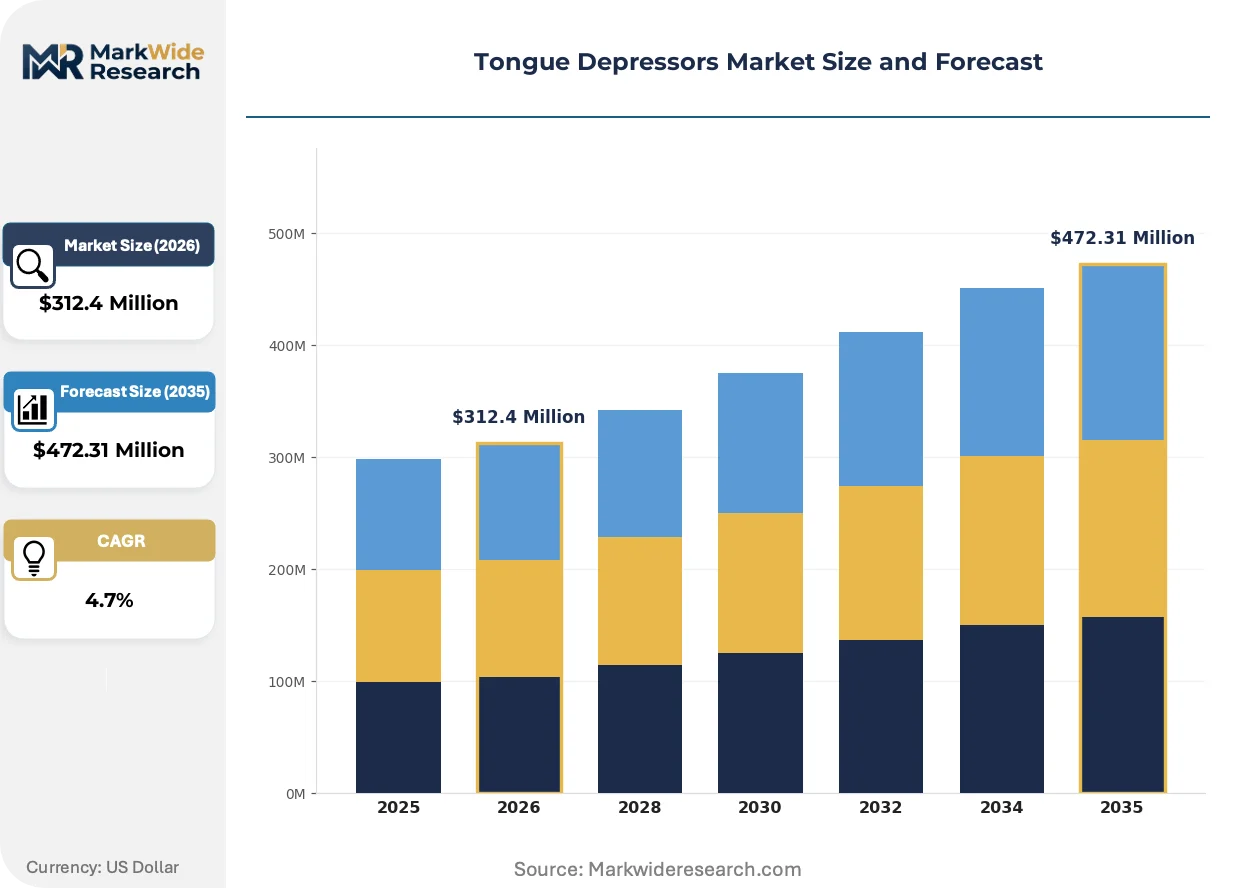
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden, Plastic, Metal, Disposable End User: Dentists, Hospitals, Clinics, Home Care Distribution Channel: Online, Retail, Wholesalers, Direct Sales Application: Medical, Educational, Dental, Veterinary |
| Companies Covered | Medline Industries, Puritan Medical Products, AliMed, Inc., B. Braun SE, DTR Medical Ltd., Dukal Corporation, Cardinal Health, Henry Schein, Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tongue Depressors Market Strategic Shifts
Sustainability certification is overtaking price as the primary procurement filter, while sterilization technology and supply chain transparency reshape product specifications across end-use verticals.
Laser-etched batch coding on birchwood depressors is overtaking ink-printed labels as the compliance standard for traceability. German dental chains and French hospital purchasing consortia now require permanent marking that survives autoclave cycles and chemical disinfection. This technology is overtaking adhesive-label alternatives by eliminating delamination risks during sterilization protocols.
The FDA's updated single-use medical device guidelines under 21 CFR 880.6230 are tightening biocompatibility documentation requirements for wooden instruments. Manufacturers must now submit extractables testing for natural resins and surface treatments, extending regulatory approval timelines. U.S. primary care clinics and urgent care networks are responding by consolidating supplier relationships with vertically integrated producers capable of in-house laboratory validation.
Hospital buying cooperatives are consolidating vendor panels to reduce audit burden, replacing fragmented multi-source procurement with single-framework agreements. Group purchasing organizations in the United States and purchasing alliances in Germany now demand annual sustainability reporting alongside unit pricing. This concentration is most visible in Nordic markets, where regional health authorities bundle tongue depressor contracts within broader disposable instrument tenders.
Tongue Depressors Market Segmentation
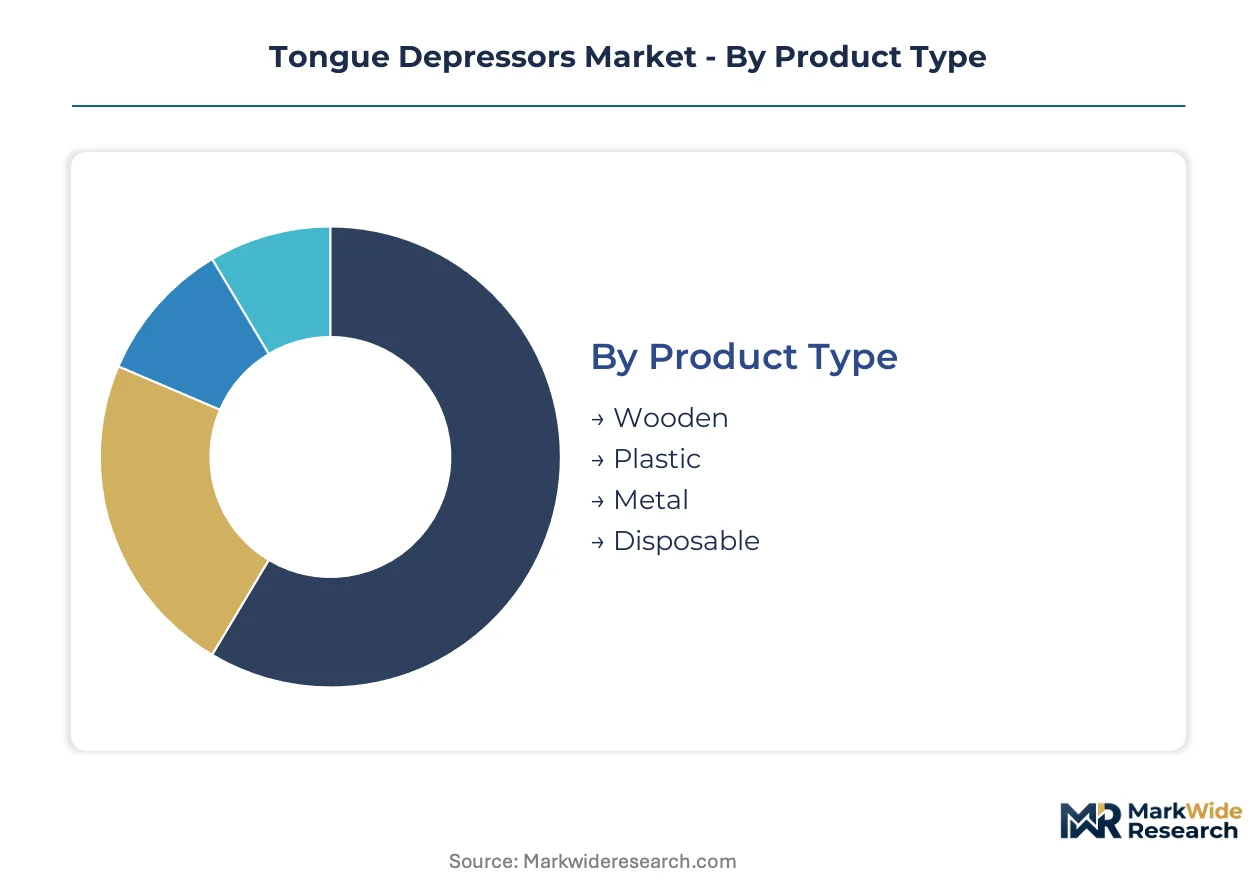
Tongue depressor procurement patterns diverge sharply across material grades, end-use protocols, and channel economics. Segment boundaries are hardening as EU Green Deal mandates and FDA biocompatibility rules force buyers into narrower supplier pools with validated certification trails.
Product Type:
Customization intensity spans from commodity birchwood to precision-milled stainless steel, with sterilization compatibility and traceability requirements determining specification depth.
- Wooden:White birchwood construction measuring 150 mm by 18 mm dominates procurement volumes due to biodegradability credentials and per-unit cost efficiency. German outpatient dental networks and French hospital purchasing consortia now mandate laser-etched batch coding for autoclave survival, locking in premium-grade wooden contracts with vertically integrated Nordic suppliers.
- Plastic:Polystyrene variants retain structural advantage in pediatric applications where splinter resistance outweighs sustainability metrics. REACH substance restrictions on plasticizer formulations are compressing hospital conversion timelines toward wooden substitutes, though children's hospitals in the United States maintain plastic procurement for trauma-risk minimization.
- Metal:Stainless steel depressors enable rental-and-sterilize service models for high-volume dental chains, with B. Braun SE targeting German Bavarian and North Rhine-Westphalia networks with autoclave-compatible instrument programs.
- Disposable:Single-use certification drives procurement consolidation among primary care clinics and urgent care networks seeking reduced audit burden through simplified inventory protocols.
Leading the category by volume: Wooden. Expanding most quickly: Metal.
End User:
Cost tier stratification separates infection-control-intensive institutional buyers from price-sensitive decentralized purchasers.
- Dentists:German dental chains command premium positioning through mandated single-patient use with documented material traceability under EU MDR UDI requirements, with METI-backed clinic network mergers in Japan creating similar centralized procurement gravity.
- Hospitals:European hospital buying cooperatives are consolidating vendor panels to reduce audit burden, replacing fragmented multi-source procurement with single-framework agreements that bundle tongue depressor contracts within broader disposable instrument tenders.
- Clinics:United States primary care and urgent care networks are expanding procurement of disposable wooden variants in response to FDA updated single-use device guidelines.
- Home Care:Retail-channel dependency and lower sterilization protocol requirements position this segment at the economy tier of the pricing spectrum.
Dentists capture the steepest pricing premium. Clinics drive volume expansion.
Distribution Channel:
Supply concentration geography determines channel efficiency, with Maine-based milling operations and Nordic forestry clusters shaping fulfillment economics.
- Online:E-procurement platforms serving smaller clinic networks and home care segments with reduced minimum order quantities and rapid fulfillment.
- Retail:Pharmacy and medical supply store networks targeting individual practitioners and educational institutional purchasers with immediate availability.
- Wholesalers:Group purchasing organizations in the United States and purchasing alliances in Germany consolidate volume through annual sustainability reporting requirements alongside unit pricing negotiations.
- Direct Sales:Vertically integrated manufacturers with captive birchwood sourcing leverage direct relationships to bypass distributor margins in Nordic markets.
Wholesalers command the largest volume share. Online channels are gaining share fastest.
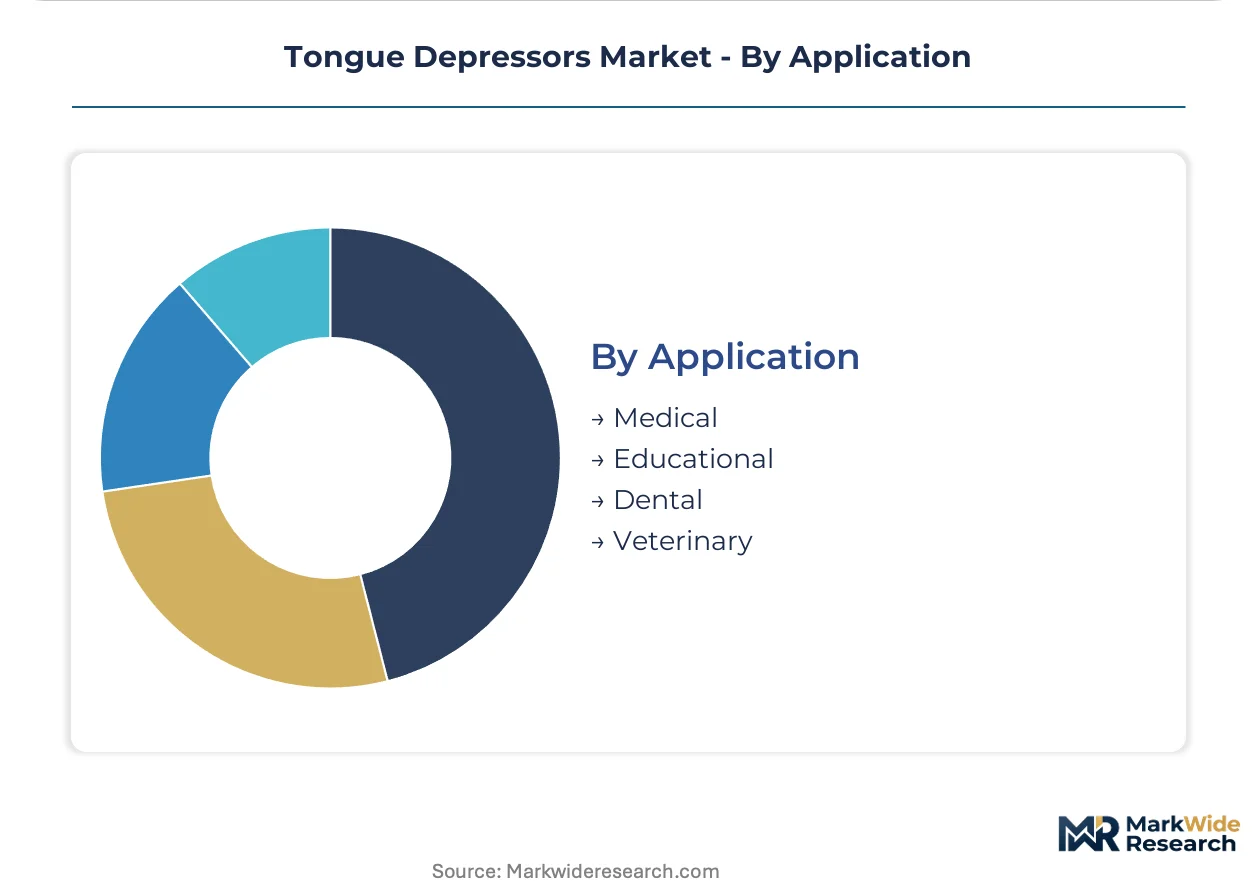
Application:
Maturity differentiation separates regulated diagnostic use from emerging veterinary and educational segments with lighter compliance burdens.
- Medical:Diagnostic oral cavity examination in primary care and hospital settings drives the core revenue base, with FDA Class I device classification under 21 CFR 880.6230 and EU MDR UDI obligations constraining supplier eligibility.
- Educational:Medical and dental training programs utilize depressors for anatomical demonstration, with lower sterilization requirements enabling broader supplier participation.
- Dental:Specialized infection control protocols in Germany, France, and Japan mandate single-patient use with full material traceability, creating premium segment isolation from general medical procurement.
- Veterinary:Animal health applications are expanding as pet care expenditure rises, though regulatory frameworks remain less stringent than human medical counterparts.
Medical applications dominate revenue. Veterinary represents the fastest-climbing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maine anchors North American birchwood milling capacity, with clusters in Aroostook and Penobscot counties supplying domestic primary care networks. Nordic forestry operations in Sweden and Finland feed European hospital procurement. German dental chains and Japanese clinic consolidations reshape demand geography across three continents.
United States
Primary care clinics and urgent care networks drive wooden depressor procurement volumes. FDA single-use device guidelines under 21 CFR 880.6230 tighten biocompatibility documentation requirements. Maine-based milling operations concentrate supply in Aroostook County, where vertically integrated producers manage in-house laboratory validation.
Germany
Outpatient dental networks across Bavaria and North Rhine-Westphalia mandate autoclave-compatible instruments with full material traceability. EU MDR imposes Unique Device Identification obligations and post-market surveillance requirements. The Stuttgart medical technology corridor hosts sterilization-ready metal depressor programs serving regional dental chains.
Japan
METI-backed dental clinic network mergers create centralized procurement entities with standardized infection control protocols. PMDA oversight aligns with international biocompatibility standards for single-patient use instruments. The Osaka-Kobe manufacturing belt supplies precision-milled alternatives to consolidated clinic buyers.
France
Hospital purchasing consortia demand annual sustainability reporting alongside unit pricing in bundled disposable instrument tenders. Extended producer responsibility frameworks assign end-of-life disposal costs directly to instrument makers. The Lyon-Grenoble medical supply cluster advances laser-etched batch coding for autoclave survival.
Sweden
Nordic regional health authorities bundle tongue depressor contracts within broader disposable instrument tenders favoring certified biodegradable alternatives. EU Green Deal procurement mandates eliminate petroleum-based plastic disposables from contracted supply lists. Västerbotten and Norrbotten forestry districts sustain kiln-dried birchwood output for continental European buyers.
Tongue Depressors Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and traceability infrastructure. The vendor base stratifies between vertically integrated forestry operators, specialized sterilization service providers, and diversified medical supply distributors. Three archetypes dominate: captive birchwood sourcers with in-house milling, metal instrument specialists with autoclave-compatible rental programs, and broadline distributors leveraging group purchasing organization relationships. Competitive moves concentrate on sustainability certification acquisition and direct sales channel expansion into Nordic markets.
Among North American-based suppliers, Puritan Medical Products and Medline Industries exemplify the integrated sourcing archetype, while B. Braun SE anchors European metal depressor positioning. Puritan Medical Products occupies a position tied to Maine forestry clusters. Medline Industries represents vertically controlled supply chain configuration. B. Braun SE sits within the sterilization-ready instrument tier serving German dental networks.
| Leading Market Players |
|---|
| Medline Industries |
| Puritan Medical Products |
| AliMed, Inc. |
| B. Braun SE |
| DTR Medical Ltd. |
| Dukal Corporation |
| Cardinal Health |
| Henry Schein |
| Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal procurement mandates gate qualified supply access and premium-tier pricing power, restricting hospital contracts to certified biodegradable birchwood producers while excluding petroleum-based plastic alternatives from contracted supply lists. This sustainability filter concentrates purchasing power among vertically integrated Nordic and Maine-based suppliers capable of documenting certified sourcing.
Pricing Analysis
Throughput-based rental pricing for sterilization-ready metal depressors anchors the premium tier, with B. Braun SE and German dental chains structuring per-procedure fees that bundle instrument provision with autoclave logistics. Price differentiation rests on certification grade (FDA 21 CFR 880.6230 vs. EU MDR UDI tiers) and volume scale, with hospital buying cooperatives extracting standard-tier discounts through consolidated framework agreements. Cost compression in commodity wooden variants is intensifying because kiln-drying energy expenses and Nordic pulp harvest cycles feed raw material volatility. Home care retail channels exhibit highest price sensitivity, while German outpatient dental networks accept premium positioning for documented traceability.
Supply Chain Analysis
ISO 15223-1 symbol validation and REACH substance compliance gate supplier eligibility, with ECHA framework constraints eliminating non-conforming polystyrene producers from European hospital vendor panels. Geographic supply concentrates in Sweden, Finland, and Maine, where captive birchwood forestry operations feed kiln-dried output to continental buyers. Raw material dependencies center on Nordic pulp supply, Maine milling capacity, and stainless steel sheet stock for metal variants. Single-source vulnerability runs through Aroostook County clustering, where weather disruptions and labor constraints threaten North American fulfillment. Distribution runs through group purchasing organizations in the United States and purchasing alliances in Germany that bundle tongue depressor contracts within broader disposable instrument tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Birchwood milling capacity scarcity in Maine and Nordic regions props pricing power for qualified suppliers, constraining volume expansion for non-integrated competitors.
For Market Incumbents: Deploy laser-etched batch coding infrastructure to capture German and French hospital contracts requiring autoclave-survivable traceability. Lock in backward integration into Västerbotten and Norrbotten forestry districts to secure kiln-dried birchwood feedstock against harvest cycle volatility. Consolidate GPO relationships before EU MDR UDI compliance deadlines compress vendor panels.
For New Entrants and Emerging Players: Launch via e-procurement platforms serving smaller clinic networks with reduced minimum order quantities, bypassing entrenched wholesaler relationships. Target Japanese dental clinic consolidations created by METI-backed network mergers, where standardized infection control protocols favor new suppliers with full material traceability. Position stainless steel rental-and-sterilize service models to capture recurring revenue from high-volume dental chains.
For Investors and Strategic Acquirers: FDA extractables testing requirement extensions for wooden instruments are the leading indicator that regulatory validation capabilities will determine acquisition premiums. Vertically integrated producers with in-house laboratory infrastructure and certified Nordic forestry sourcing represent the optimal target archetype for five-to-ten year positioning. Watch for Maine-based milling operation distress as birchwood input cost volatility compresses margin stability for non-integrated manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Etched Batch Coding Investment | Captures German dental chain contracts requiring autoclave-survivable UDI compliance. |
| Backward Integration into Nordic Forestry | Secures kiln-dried birchwood supply against pulp harvest cycle volatility. |
| Metal Depressor Rental Program Launch | Enables recurring revenue capture from Bavarian sterilization-service dental networks. |
| E-Procurement Platform Partnership | Bypasses wholesaler margins to reach fragmented United States urgent care networks. |
| Extended Producer Responsibility Infrastructure | Positions early movers for French and German end-of-life disposal cost assignment. |
Study Parameters
Multi-period observation of FDA 21 CFR 880.6230 guidance evolution, EU MDR UDI implementation timelines, and Nordic pulp pricing indices anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, dental clinic procurement leads, and sustainability certification officers. Secondary validation drew from FDA device classification databases, ECHA REACH substance restriction filings, EU Green Deal procurement mandate documentation, and hospital tender records. Bottom-up segment sizing triangulated against top-down macro healthcare expenditure trends.
Input-output matrices modeled material-grade supply costs, sterilization-service pricing structures, and channel margin stacks across the projection horizon. Segmentation dimensions spanned product type (wooden, plastic, metal, disposable), end user (dentists, hospitals, clinics, home care), distribution channel (online, retail, wholesalers, direct sales), and application (medical, educational, dental, veterinary). CAGRs were derived from regression analysis of historical procurement volume patterns against regulatory compliance deadline schedules and sustainability mandate adoption curves.
Regulatory timeline delays, birchwood harvest shortfalls, and EU MDR database integration bottlenecks are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding compliance cost pass-through rates and hospital vendor panel consolidation velocity. A model refresh is warranted upon material change in FDA extractables testing requirement scope or Nordic forestry district output capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Microcarrier Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Global Needles Market
Medical Supplies
Casting and Splints Market