
 Leukocytapheresis Device Market | 2026-2036
Leukocytapheresis Device Market Size, Share, and Industry Trends Forecast 2026-2036
Leukocytapheresis Device Market Analytics
Japanese membrane filtration manufacturers is expanding domestic cleanroom capacity to serve leukocytapheresis device assembly. Asahi Kasei Medical leverages its hollow-fiber membrane expertise to anchor supply for autoimmune indication systems. Haemonetics Corporation sustains North American hospital placements through integrated disposable-to-hardware platforms. Terumo BCT competes on centrifugation technology leadership in hematological disease protocols.
Leukocytapheresis devices separate and remove white blood cells from circulating blood through extracorporeal processing, typically achieving leukocyte depletion rates exceeding 90% per session using membrane filtration or centrifugal force technologies. These systems serve primarily to modulate pathological immune responses in conditions such as ulcerative colitis and leukostasis syndrome. Continuous flow systems dominate installed base volumes due to shorter treatment durations and higher throughput capacity, while automated systems capture expanding margin pools as hospitals prioritize labor reduction and protocol standardization. Membrane filtration technology leads autoimmune applications for its selectivity, whereas centrifugation retains primacy in hematological disease settings requiring bulk cell removal.
FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards govern device commercialization in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for apheresis equipment marketed in Europe. Japan's PMDA maintains distinct pharmaceutical-medical device hybrid classification rules that extend review timelines for leukocytapheresis systems with adsorptive columns. Stakeholders must monitor evolving harmonization gaps between FDA breakthrough device designations and EMA parallel consultation frameworks to optimize multi-regional launch sequencing.
Market Dynamics
Membrane filtration technology is consolidating its position in autoimmune applications while centrifugation retains hematological dominance, creating divergent R&D investment patterns across device categories. Japanese hollow-fiber membrane supply chains concentrate manufacturing capacity, shaping procurement strategies for hospital systems worldwide.
Growth Catalysts
- Hospital-based autoimmune treatment programs:Expanding ulcerative colitis and leukostasis syndrome protocols in tertiary care centers drive device utilization. Japan's PMDA pharmaceutical-medical device hybrid classification framework accelerates adsorptive column approvals.
- FDA 510(k) clearance pathway evolution:Streamlined apheresis device safety reviews reduce commercialization timelines for membrane filtration systems. US hospital systems respond with faster technology adoption cycles.
- Continuous flow system throughput advantages:Shorter treatment durations align with outpatient cost-containment mandates. Automated systems capture margin pools as labor reduction priorities intensify.
Market Restraints
- Biocompatibility certification costs:ISO 10993 testing requirements for extracorporeal circuits impose substantial pre-market expenditure. Smaller manufacturers face capital constraints for multi-market submissions.
- Japanese membrane supply concentration:Hollow-fiber production clusters in Osaka and Tokyo prefectures create geographic vulnerability. Disruption risks elevate procurement contingency planning costs.
- Centrifugation technology substitution pressure:Bulk cell removal applications in hematological oncology retain preference for density-gradient separation. Membrane filtration faces performance ceiling constraints in high-volume leukostasis cases.
Strategic Opportunities
- EU MDR clinical evidence harmonization:Strengthened apheresis equipment requirements create first-mover advantages for manufacturers with robust trial data. Parallel consultation frameworks with EMA reduce multi-regional launch sequencing friction.
- Automated disposable-to-hardware integration:Labor reduction priorities in North American hospital systems favor platforms with protocol standardization capabilities. Integrated systems command pricing premiums against standalone components.
- Adsorptive column expansion:PMDA hybrid classification pathways enable novel immunomodulation applications beyond leukocyte depletion. Japanese regulatory precedent influences Asian market entry strategies.
Industry Challenges
- Cleanroom capacity scaling:Membrane assembly requires ISO 14644-1 Class 7 environments. Qualified facility construction timelines extend 18-24 months, constraining supply response.
- Legacy system interoperability:Hospital information system integration with apheresis device data outputs demands customized middleware development. EMR compatibility certification delays installations.
- Specialized biomedical engineering talent:Extracorporeal circuit design expertise concentrates in Japanese and German industrial clusters. Recruitment competition intensifies as device portfolios expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukocytapheresis Device Market |
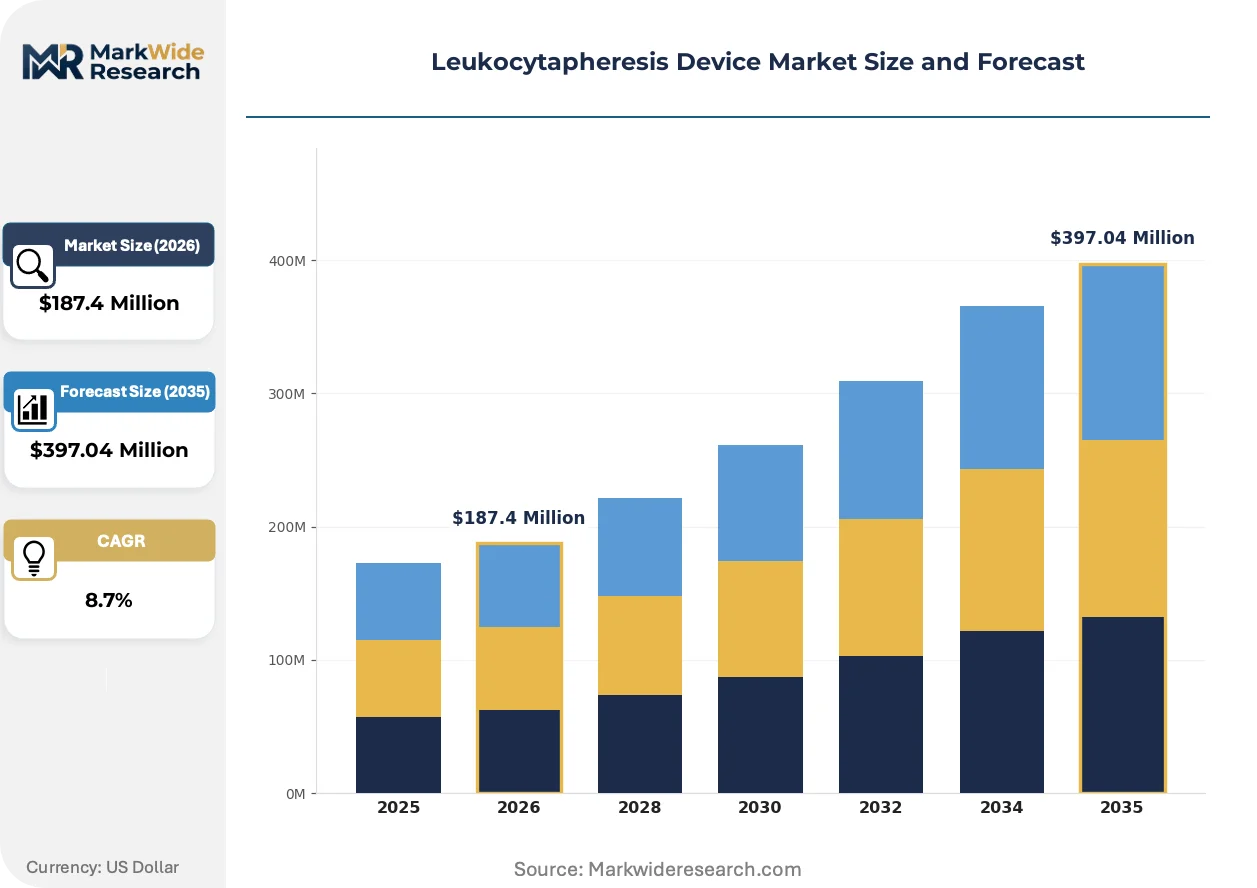
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Flow, Batch Process, Automated Systems, Manual Systems End User: Hospitals, Outpatient Clinics, Research Institutions, Blood Donation Centers Technology: Membrane Filtration, Centrifugation, Immunoadsorption, Affinity Chromatography Application: Autoimmune Disorders, Hematological Diseases, Cancer Treatment, Organ Transplantation |
| Companies Covered | Asahi Kasei Medical Co. Ltd., Haemonetics Corporation, Terumo BCT, Fresenius SE & Co. KGaA, Grifols, Macopharma, Miltenyi Biotec, B. Braun Melsungen AG, Nikkiso Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukocytapheresis Device Market Evolving Landscape
Automation and selectivity improvements are reshaping competitive positioning across membrane and centrifugation technology paths. Regulatory convergence pressures and procurement rationalization simultaneously compress margins and expand addressable procedure volumes.
Hollow-fiber membrane selectivity is consolidating autoimmune application leadership through improved leukocyte retention without platelet loss. Tertiary care centers in Japan and Germany adopt these systems for ulcerative colitis protocols at accelerated replacement cycles. The technology is consolidating supplier relationships around integrated disposable-hardware platforms that lock in recurring revenue streams.
EU MDR strengthened clinical evidence requirements are extending review timelines for apheresis equipment commercialization. Manufacturers must generate prospective trial data for CE marking where predicate device pathways previously sufficed. Hematological disease indication systems face the steepest compliance burden, compressing mid-tier competitor participation.
After-sales service unbundling is fragmenting traditional device-vendor relationships in North American hospital procurement. Third-party biomedical engineering firms now maintain centrifugation hardware while disposables flow through group purchasing organizations. This bifurcation concentrates in California and Texas health systems seeking operational expenditure flexibility over capital ownership models.
Leukocytapheresis Device Market Segmentation
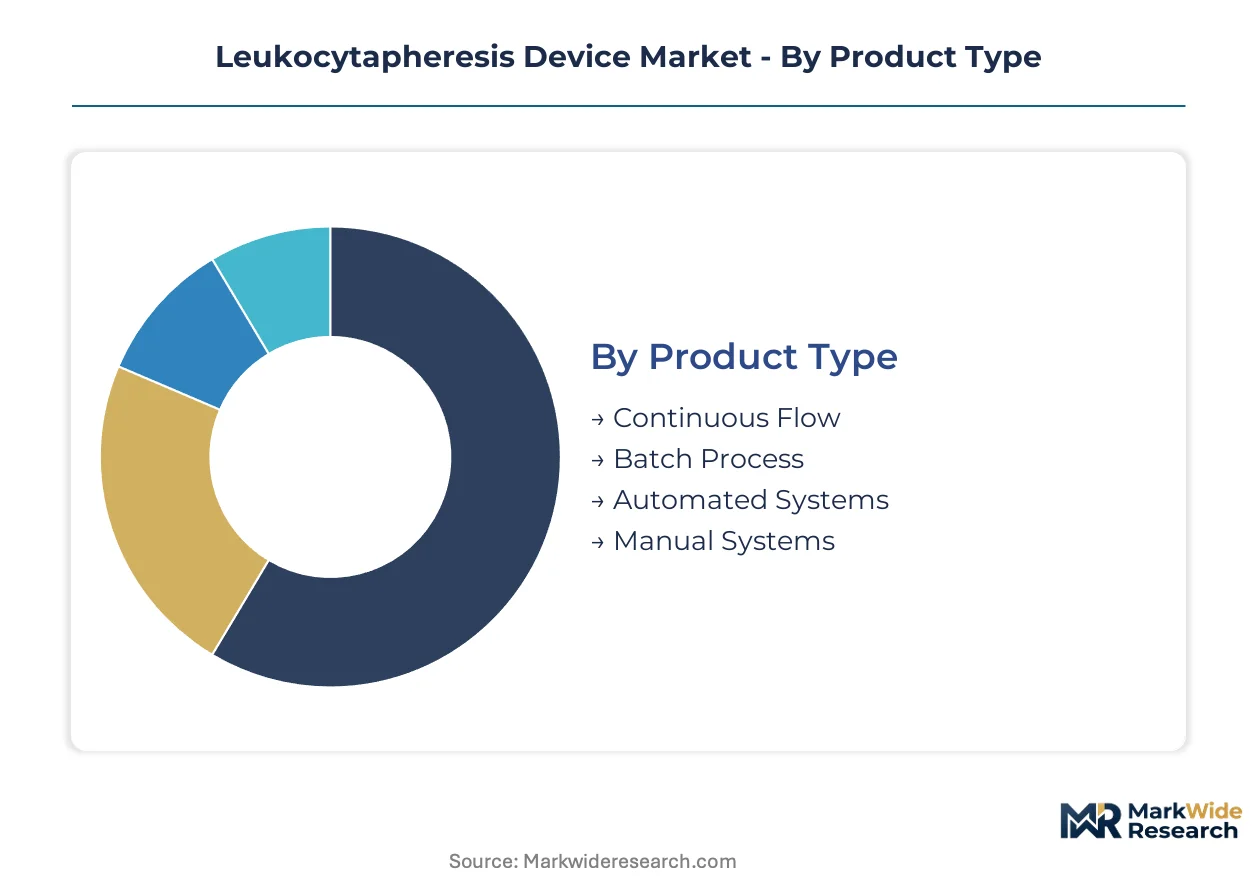
Leukocytapheresis device procurement patterns diverge sharply across clinical settings and technical specifications. Hospital systems prioritize throughput and labor efficiency, while research applications demand protocol flexibility over processing speed.
Product Type:
Supply concentration in Japanese hollow-fiber manufacturing clusters shapes device availability across all product categories.
- Continuous Flow:These systems process blood through simultaneous withdrawal and return circuits, achieving treatment cycles under 90 minutes. Japanese tertiary care centers deploy continuous flow platforms for ulcerative colitis protocols where patient throughput pressures intensify.
- Automated Systems:Integrated disposable-to-hardware platforms reduce operator intervention through pre-programmed leukocyte depletion protocols. North American hospital systems favor automated configurations as labor reduction mandates tighten across California and Texas health networks.
- Batch Process:Intermittent processing cycles suit research applications requiring sample preservation between collection phases.
- Manual Systems:Operator-dependent configurations retain niche placement in resource-constrained clinical environments.
Continuous Flow absorbs the bulk of installed capacity; Automated Systems is expanding most quickly.
End User:
Cost tier differentiation separates capital-intensive hospital deployments from flexible outpatient leasing arrangements.
- Hospitals:Integrated service contracts dominate tertiary care procurement, bundling hardware, disposables, and preventive maintenance. German university hospitals anchor European demand through autoimmune disorder treatment expansion.
- Outpatient Clinics:Leasing structures and per-procedure pricing accommodate capital constraints. Japanese specialty clinics adopt membrane filtration systems for leukostasis syndrome management where reimbursement favors ambulatory settings.
- Research Institutions:Protocol customization requirements drive preference for modular platforms with open architecture.
- Blood Donation Centers:High-volume processing needs align with centrifugation technology for bulk leukocyte removal in donor apheresis.
Hospitals retain the dominant revenue share; Outpatient Clinics is gaining share fastest.
Technology:
Application specificity determines technology selection, with autoimmune protocols favoring selectivity and hematological cases requiring bulk removal capacity.
- Membrane Filtration:Hollow-fiber configurations achieve leukocyte retention exceeding 90% while preserving platelet populations. Osaka and Tokyo manufacturing clusters concentrate supply for autoimmune indication systems.
- Centrifugation:Density-gradient separation retains primacy in leukostasis syndrome and hematological oncology protocols. Haemonetics and Terumo BCT compete on rotational speed optimization and plasma separation efficiency.
- Immunoadsorption:Adsorptive columns enable targeted cytokine removal beyond leukocyte depletion, with PMDA hybrid classification pathways accelerating Japanese approvals.
- Affinity Chromatography:Ligand-based selectivity serves research applications requiring specific cell population isolation.
Membrane Filtration commands the largest installed base; Immunoadsorption is climbing the fastest.
Application:
Volume concentration in autoimmune protocols contrasts with margin expansion in emerging transplant applications.
- Autoimmune Disorders:Ulcerative colitis and inflammatory bowel disease protocols drive recurring procedure demand. Japanese hospital systems standardize membrane filtration workflows for these indications.
- Hematological Diseases:Leukostasis syndrome in acute leukemias requires emergency leukocyte reduction. Centrifugation systems dominate this segment due to processing speed requirements in critical care settings.
- Cancer Treatment:Adoptive cell therapy preparation creates emerging demand for selective leukocyte subsets.
- Organ Transplantation:Desensitization protocols for sensitized recipients represent a nascent application with steep regulatory evidence requirements.
Autoimmune Disorders accounts for the majority of procedure volumes; Organ Transplantation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hollow-fiber membrane manufacturing concentrates in Japan's Kanto and Kansai industrial corridors, with Osaka and Tokyo prefectures anchoring global supply for leukocytapheresis device assembly. This geographic clustering shapes procurement strategies and regulatory alignment across major demand centers.
Japan
Japanese tertiary care centers drive membrane filtration adoption for ulcerative colitis protocols, with university hospitals in Tokyo and Osaka standardizing continuous flow workflows. PMDA pharmaceutical-medical device hybrid classification accelerates adsorptive column approvals for autoimmune indications. Manufacturing clusters in Tokyo and Osaka prefectures concentrate hollow-fiber production capacity, with Asahi Kasei Medical and Nikkiso anchoring regional supply chains for domestic and export markets.
United States
US hospital systems prioritize automated disposable-to-hardware platforms as labor reduction mandates tighten across California and Texas health networks. FDA 510(k) clearance pathways streamline apheresis device safety reviews, reducing commercialization timelines for membrane filtration entrants. The Boston-Cambridge biomedical corridor concentrates extracorporeal circuit design expertise, while Southern California health systems pioneer after-sales service unbundling models.
Germany
German university hospitals anchor European demand through autoimmune disorder treatment expansion, with Baden-Württemberg and Bavaria leading device procurement volumes. EU MDR strengthened clinical evidence requirements extend review timelines for apheresis equipment CE marking, compressing mid-tier competitor participation. The Stuttgart industrial region concentrates centrifugation technology development, with specialized biomedical engineering talent pools supporting hematological disease protocol optimization.
China
Chinese tertiary hospitals expand leukostasis syndrome treatment capacity as hematological oncology caseloads rise in Beijing and Shanghai medical centers. NMPA medical device classification rules govern apheresis system commercialization, with review timelines extending for novel immunoadsorption configurations. The Yangtze River Delta concentrates dialysis and blood purification device manufacturing, with domestic suppliers building membrane filtration assembly capabilities for autoimmune indication systems.
Leukocytapheresis Device Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent immunoadsorption and cell therapy preparation spaces. The vendor base stratifies across integrated platform providers, specialized membrane fabricators, and centrifugation technology houses. Three archetypes dominate: Japanese hollow-fiber membrane specialists with captive supply chains, North American integrated disposable-hardware platform vendors, and European centrifugation technology leaders. Competitive moves concentrate on automated system development and EU MDR clinical evidence generation for first-mover certification advantages.
Among Japanese membrane filtration specialists, Asahi Kasei Medical Co. Ltd. and Nikkiso Co., Ltd. exemplify the integrated supply archetype, with geographic naming indicating Kanto and Kansai regional anchoring. Haemonetics Corporation represents the North American integrated platform model, with corporate suffix indicating incorporated structure. These three occupy positions across divergent technology paths—membrane selectivity versus centrifugation bulk processing—reflecting the market's bifurcated R&D investment patterns.
| Leading Market Players |
|---|
| Asahi Kasei Medical Co. Ltd. |
| Haemonetics Corporation |
| Terumo BCT |
| Fresenius SE & Co. KGaA |
| Grifols |
| Macopharma |
| Miltenyi Biotec |
| B. Braun Melsungen AG |
| Nikkiso Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned Japanese hollow-fiber membrane specialists anchor supply-side discipline through captive cleanroom capacity in Osaka and Tokyo prefectures, translating geographic concentration into pricing power for autoimmune indication systems while North American hospital procurement unbundling erodes service-bundled premiums elsewhere.
Pricing Analysis
Warranty and preventive maintenance bundling separates integrated platform vendors from unbundled hardware competitors in North American hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 certification tier and after-sales service depth. Cost compression in standard-tier membrane filtration systems intensifies as third-party biomedical engineering firms capture maintenance revenue. Outpatient clinics exhibit highest price sensitivity due to capital constraints, while Japanese tertiary care centers accept premium positioning for PMDA-approved adsorptive column configurations.
Supply Chain Analysis
Dual-sourcing mandates from US hospital group purchasing organizations now require qualified secondary suppliers for hollow-fiber membranes beyond Asahi Kasei Medical and Nikkiso. Manufacturing draws from Japan, Germany, and emerging Chinese assembly in the Yangtze River Delta. Polysulfone resin, precision pump components, and biocompatible tubing constitute critical input dependencies. Single-source vulnerability concentrates in Osaka-Tokyo membrane production clusters. Distribution runs through integrated device-vendor direct sales for hospitals and leasing intermediaries for outpatient settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR strengthened clinical evidence requirements erect barrier-to-entry moats favoring manufacturers with pre-existing trial infrastructure and regulatory affairs scale.
For Market Incumbents: Extend certification advantage into parallel EMA-FDA consultation frameworks to compress multi-regional launch sequencing. Deepen backward integration into hollow-fiber membrane production to defend against centrifugation technology substitution in high-volume leukostasis applications. Anchor hospital information system interoperability investments to lock in integrated disposable-to-hardware platform renewals. For New Entrants and Emerging Players: Begin with organ transplantation desensitization protocols where regulatory evidence requirements have suppressed incumbent participation and pricing remains unsettled. Target Chinese tertiary hospitals expanding leukostasis syndrome capacity under NMPA medical device classification pathways. Pursue per-procedure leasing structures to bypass capital ownership barriers in North American outpatient clinics. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated system specialists with EU MDR clinical evidence packages already assembled in Germany or Japan. Long-term viability hinges on five-to-ten year capture of adoptive cell therapy preparation workflows. Monitor PMDA hybrid classification precedent expansion as inflection signal for Asian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Generation | Prospective trial investment secures CE marking priority for membrane filtration platforms ahead of predicate device pathway expiration. |
| Automated Disposable-to-Hardware Integration | Labor reduction mandates in California and Texas health networks command pricing premiums for pre-programmed leukocyte depletion protocols. |
| Hospital Information System Interoperability | EMR compatibility certification delays competitor installations and extends incumbent replacement cycle capture. |
| Adsorptive Column Expansion | PMDA hybrid classification precedent enables cytokine removal applications beyond leukocyte depletion in Japanese autoimmune protocols. |
| Cleanroom Capacity Scaling | ISO 14644-1 Class 7 facility construction in Osaka and Tokyo prefectures constrains supply response and reinforces membrane supply concentration. |
Research Methodology
Independent corroboration across primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists, combined with secondary validation from FDA 510(k) filings, PMDA approval databases, EU MDR notified body documentation, and hospital procurement records, underwrites the qualitative findings. Bottom-up procedure volume estimates and top-down device shipment analysis triangulate market sizing.
Comparable-period anchoring to historical autoimmune disorder treatment expansion and hematological oncology caseload trajectories structured the projection horizon across technology, application, and end-user segmentation dimensions. CAGRs derive from modeled procedure volume growth adjusted for device replacement cycles and automated system penetration rates. Forecast inputs incorporate PMDA hybrid classification pathway evolution and EU MDR review timeline compression.
Underlying measurement precision varies by segment; continuous flow systems and membrane filtration technology carry tighter precision than emerging immunoadsorption configurations. Forecasts reflect assumptions regarding regulatory harmonization progress and hospital labor reduction mandate intensity. Deviation in FDA breakthrough device designation alignment with EMA parallel consultation frameworks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market