
 Computer-Assisted Orthopedic Surgery Market | 2026-2036
Computer-Assisted Orthopedic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Computer-Assisted Orthopedic Surgery Market Analytics
European orthopedic device manufacturing is recalibrating around precision navigation platforms. Stryker leverages integrated robotics and digital surgery ecosystems to sustain technology leadership in joint reconstruction. Zimmer Biomet anchors its competitive stance through proprietary navigation software and instrument compatibility across hospital networks. Smith & Nephew differentiates via specialized trauma and extremities applications that occupy underserved procedural niches.
Computer-assisted orthopedic surgery encompasses intraoperative navigation, robotic positioning, and real-time imaging modalities that enable sub-millimeter accuracy in bone resection and implant placement. Optical tracking arrays, electromagnetic field generators, and fluoroscopic registration algorithms constitute core hardware layers, while proprietary software reconstructs patient-specific anatomy from preoperative CT or MRI datasets. Robotics and surgical navigation systems command the largest installed base, though computer vision modules represent the fastest-expanding technology segment as machine learning enhances anatomical recognition. Joint replacement applications generate the dominant revenue pool, while spine surgery delivers the highest per-procedure system utilization rates.
FDA 510(k) premarket notification, EU MDR technical documentation requirements, and ISO 13485 quality management standards collectively determine market access timelines and clinical evidence burdens for device manufacturers. Japan's PMDA Shonin approval pathway adds a third regulatory gate for companies targeting Asia-Pacific expansion. Stakeholders must monitor evolving software-as-a-medical-device classifications and predicate device strategies that could reshape competitive entry costs.
Market Dynamics
Navigation-guided surgical protocols are compressing the gap between preoperative planning and intraoperative execution, forcing device manufacturers to integrate software-hardware bundles that hospital systems now mandate in capital equipment tenders.
Growth Catalysts
- EU MDR technical documentation:The EU MDR conformity assessment pathway for software-as-a-medical-device is accelerating product standardization across European orthopedic device manufacturing, reducing time-to-market for validated navigation platforms.
- Aging demographics in Japan:Japan's PMDA Shonin approval pathway aligns with reimbursement structures that favor precision joint replacement procedures, expanding procedural volume in tertiary care centers.
- Machine learning modules:Computer vision algorithms trained on anatomical datasets are enhancing real-time recognition capabilities, enabling sub-millimeter accuracy in bone resection workflows.
Market Restraints
- Capital intensity of robotics systems:Multi-million dollar installed bases for robotic positioning platforms create barriers for mid-tier hospital systems, concentrating adoption among academic medical centers.
- Supply concentration in optical tracking:Infrared camera arrays and electromagnetic field generators rely on specialized sensor manufacturers concentrated in German and Japanese precision optics clusters.
- FDA 510(k) predicate device requirements:Substantial equivalence determinations for novel navigation software create clinical evidence burdens that extend regulatory timelines for algorithmic innovations.
Strategic Opportunities
- Trauma and extremities applications:Specialized navigation protocols for shoulder and ankle reconstruction occupy underserved procedural niches with lower competitive saturation than knee and hip segments.
- Spine surgery utilization:Per-procedure system utilization rates in spinal navigation exceed joint replacement applications, creating volume leverage for capital equipment amortization.
- ISO 13485 quality management:Certification alignment with international standards opens procurement pathways in Middle Eastern and Southeast Asian hospital systems expanding surgical infrastructure.
Industry Challenges
- Surgeon training pathways:Navigation and robotics proficiency requires extended proctoring periods that strain operating room throughput during adoption phases.
- Interoperability with legacy imaging:PACS integration and DICOM compliance for preoperative CT and MRI datasets creates IT infrastructure demands that delay deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer-Assisted Orthopedic Surgery Market |
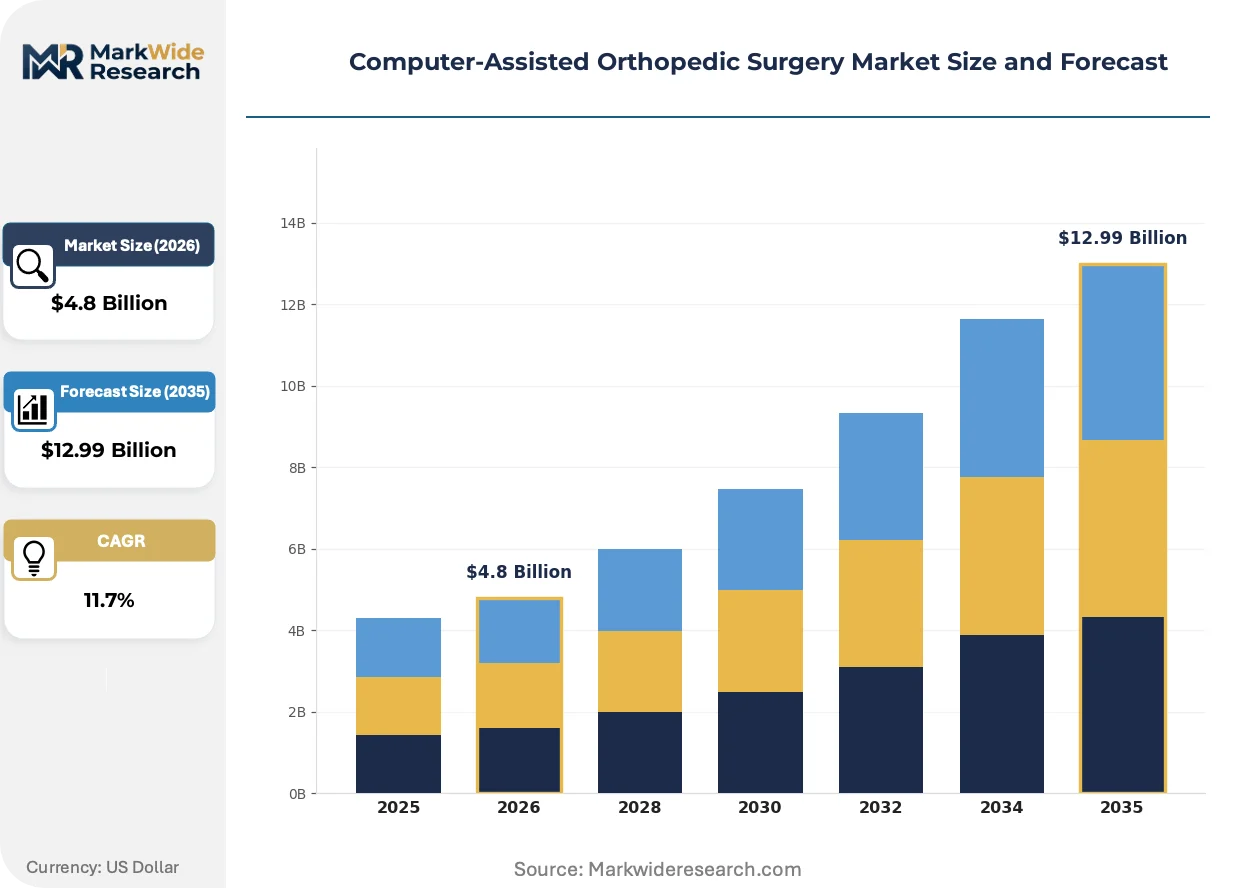
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Navigation Systems, Robotics, Imaging Solutions, Surgical Instruments Technology: Optical Navigation, Electromagnetic Navigation, Computer Vision, Image-Guided Surgery Application: Joint Replacement, Spine Surgery, Trauma Surgery, Soft Tissue Repair End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers |
| Companies Covered | Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Medtronic, NuVasive, Globus Medical, Integra LifeSciences, Brainlab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer-Assisted Orthopedic Surgery Market Evolving Landscape
Digital surgery ecosystems are collapsing the traditional boundaries between diagnostic imaging, surgical planning, and intraoperative guidance, creating integrated workflows that hospital procurement committees now evaluate as unified capital decisions rather than discrete device purchases.
Robotic positioning systems are converging with real-time optical tracking arrays to enable dynamic instrument guidance during bone resection. Academic medical centers in Germany and the United States are deploying these integrated platforms for complex revision arthroplasty cases. The technology is converging with preoperative planning software to compress operative time and reduce implant malalignment rates.
The EU MDR software-as-a-medical-device classification is redefining clinical evidence requirements for navigation algorithms that previously operated under lower regulatory thresholds. Orthopedic device manufacturers are restructuring quality management systems to address cybersecurity and post-market surveillance mandates. Spine navigation applications face the steepest compliance recalibration due to higher-risk device classifications.
Hospital value analysis committees are consolidating vendor relationships around single-source navigation-robotics contracts that bundle capital equipment, disposables, and software subscriptions. Independent community hospitals are losing procurement leverage to consolidated health systems that negotiate enterprise-wide pricing. This concentration is most visible in United States hospital networks where joint replacement bundled payment programs incentivize standardization across facility footprints.
Computer-Assisted Orthopedic Surgery Market Segmentation
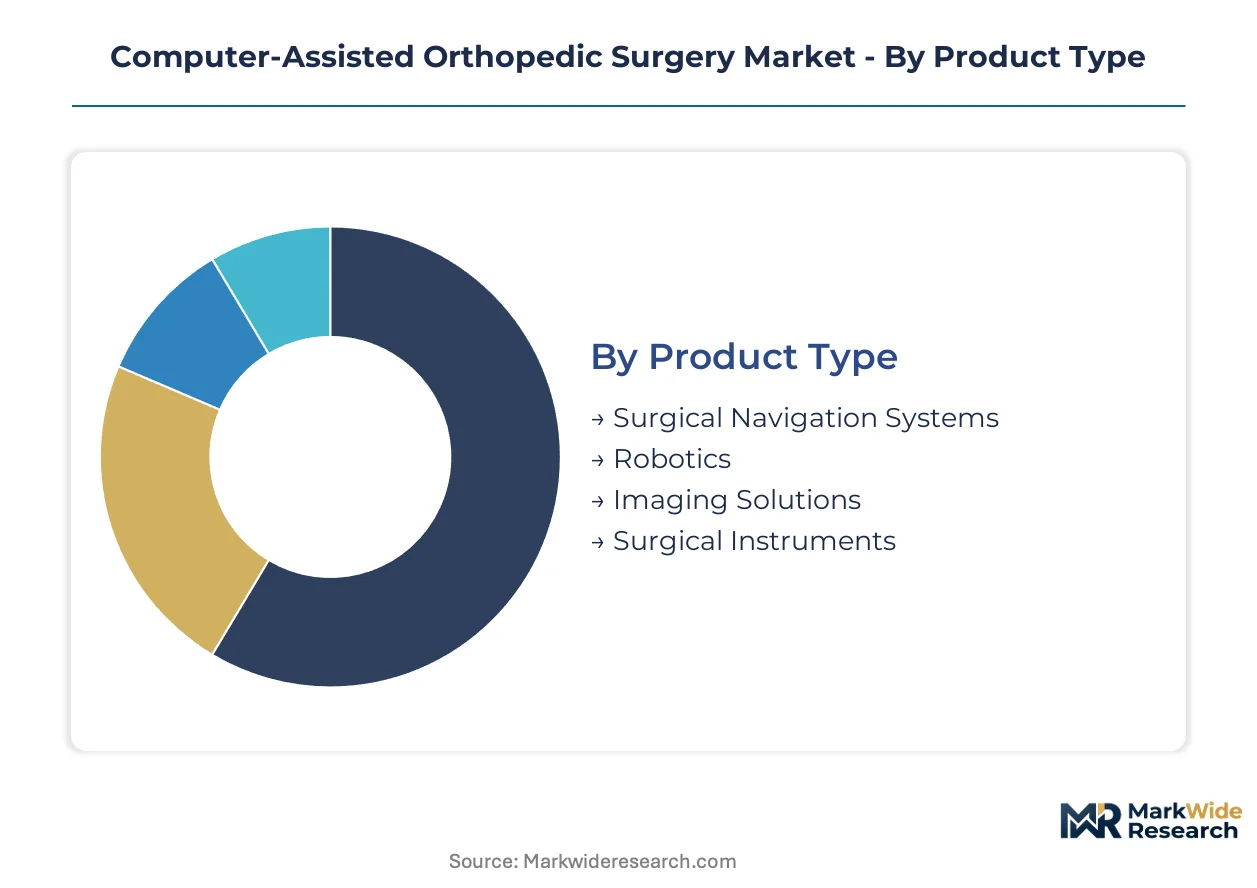
Segmentation in computer-assisted orthopedic surgery reveals how technology complexity and reimbursement structures fragment purchasing authority across hospital systems. Product configurations range from standalone navigation software to integrated robotics platforms, each carrying distinct capital intensity and training requirements.
Product Type:
Standardization dominates high-volume joint replacement workflows, while customization prevails in complex revision and trauma applications where patient anatomy varies unpredictably.
- Robotics:Motorized positioning arms execute preoperative plans with sub-millimeter precision through haptic feedback and real-time bone tracking. Academic medical centers in Germany and the United States deploy these systems for complex revision arthroplasty where manual instrumentation risks implant malalignment.
- Surgical Navigation Systems:Optical and electromagnetic tracking arrays register patient anatomy to preoperative imaging, enabling instrument guidance without robotic actuation. Mid-tier hospitals in Japan favor these platforms for their lower capital footprint and faster surgeon onboarding curves.
- Imaging Solutions:Intraoperative fluoroscopy and 3D C-arms provide real-time anatomical visualization during screw placement and resection verification.
- Surgical Instruments:Patient-specific cutting guides and tracked drill attachments extend navigation capabilities to conventional instrument sets.
Most installed capacity flows through Surgical Navigation Systems. Expansion is steepest in Robotics.
Technology:
Cost tier stratification separates premium optical arrays from budget electromagnetic alternatives, with computer vision commanding developmental premiums.
- Optical Navigation:Infrared camera arrays track reflective markers on instruments and bone segments with spatial resolution below 0.5 millimeters. German precision optics manufacturers supply the sensor hardware that underpins Stryker and Zimmer Biomet navigation platforms.
- Computer Vision:Machine learning algorithms trained on anatomical datasets enable markerless tracking through standard surgical cameras. FDA 510(k) clearance pathways for these software modules are extending as regulators evaluate algorithmic performance variability.
- Electromagnetic Navigation:Field generators create localized coordinate systems without line-of-sight constraints, suiting spine applications where instrument positioning changes frequently.
- Image-Guided Surgery:Preoperative CT and MRI registration fuses diagnostic datasets to intraoperative anatomy through proprietary reconstruction algorithms.
Optical Navigation retains the largest installed base. Computer Vision is gaining share fastest.
Application:
Volume concentration in knee and hip procedures contrasts with margin intensity in spine and trauma niches where per-case system utilization runs higher.
- Joint Replacement:Navigation-guided protocols for total knee and hip arthroplasty represent the dominant revenue pool, with bundled payment programs in United States hospital networks standardizing adoption across facility footprints. Japan's aging demographics and PMDA reimbursement alignment support procedural volume in tertiary care centers.
- Spine Surgery:Pedicle screw placement and vertebral resection demand sub-millimeter accuracy where malposition risks neurological injury. Per-procedure system utilization rates exceed joint replacement applications, creating volume leverage for capital equipment amortization.
- Trauma Surgery:Fracture reduction and intramedullary nailing benefit from real-time alignment verification in complex multi-fragment injuries.
- Soft Tissue Repair:Ligament reconstruction and tendon fixation applications remain underdeveloped relative to bony procedures.
Joint Replacement concentrates the most installed systems. Spine Surgery delivers the steepest utilization trajectory.
End User:
Customer type determines procurement complexity, with consolidated health systems negotiating enterprise contracts while independent centers face capital constraints.
- Hospitals:Academic medical centers and community hospital systems command the robotics installed base, leveraging value analysis committees to consolidate vendor relationships around bundled navigation-robotics contracts. EU MDR conformity requirements and FDA 510(k) pathways shape equipment selection criteria.
- Ambulatory Surgical Centers:Outpatient joint replacement growth in the United States is pushing navigation platform miniaturization, though capital intensity limits penetration to high-volume specialist facilities.
- Orthopedic Clinics:Private practice settings favor lower-cost navigation software and instrument rentals over capital purchases.
- Rehabilitation Centers:Postoperative alignment verification and gait analysis applications represent emerging demand for tracking technology.
Hospitals channel the most installed capacity. Ambulatory Surgical Centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision optics clusters supply infrared tracking arrays to navigation platform manufacturers, while the United States concentrates installed robotics capacity in academic medical centers. Japan's tertiary care networks standardize navigation protocols for aging patient populations.
United States
FDA 510(k) clearance pathways and bundled payment programs for joint replacement drive hospital system procurement consolidation. The agency's substantial equivalence determinations for navigation software shape algorithmic innovation timelines. Academic medical centers in Boston and the Midwest deploy integrated robotics platforms for complex revision arthroplasty.
Germany
EU MDR conformity requirements for software-as-a-medical-device accelerate quality management restructuring among orthopedic manufacturers. The KBA-relevant precision optics ecosystem in southern Germany supplies sensor hardware underpinning navigation tracking arrays. Medical technology clusters in Baden-Württemberg and Bavaria host robotics integration facilities serving European hospital networks.
Japan
PMDA Shonin approval alignment with reimbursement structures favors precision joint replacement in tertiary care centers. METI industrial policy supports domestic navigation platform development through targeted R&D incentives. Tokyo and Osaka metropolitan hospital systems represent the densest concentration of installed surgical navigation capacity in Asia-Pacific.
Switzerland
Swissmedic certification requirements for high-risk medical devices establish stringent clinical evidence standards for navigation software. The country's precision manufacturing heritage extends to optical tracking component fabrication. Zurich and Basel industrial corridors host quality management consultancies serving EU MDR transition programs.
United Kingdom
NHS England value-based procurement frameworks prioritize navigation-robotics bundles that compress operative time and reduce revision rates. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical documentation standards. London and Manchester academic hospital networks pilot computer vision modules for markerless surgical tracking.
Computer-Assisted Orthopedic Surgery Market Competitive Landscape
United States producers anchor one tier; German and Swiss specialists hold precision component supply positions. The vendor base stratifies across integrated platform developers, navigation software specialists, and optical tracking component suppliers. Three archetypes dominate: diversified orthopedic conglomerates bundling robotics with implant portfolios; pure-play navigation software vendors licensing to hospital systems; and precision optics fabricators supplying tracking hardware across OEM relationships. Competitive moves concentrate on M&A for software capabilities and strategic partnerships compressing hardware-software integration cycles.
Within the diversified orthopedic tier, Stryker and Zimmer Biomet represent integrated platform developers that bundle capital equipment with implant portfolios and disposables. Johnson & Johnson occupies a position exemplifying the medical technology conglomerate archetype, leveraging scale advantages in hospital system contracting. These three companies sit within the premium-tier vendor segment where enterprise-wide procurement negotiations consolidate vendor relationships across consolidated health system footprints.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Johnson & Johnson |
| Medtronic |
| NuVasive |
| Globus Medical |
| Integra LifeSciences |
| Brainlab |
| Others |
Value Network & Pricing Analysis
EU MDR cybersecurity mandates for software-as-a-medical-device gate qualified supply access for navigation platform manufacturers, bifurcating vendor tiers between certified premium systems and uncertified alternatives. Hospital procurement committees leverage this compliance threshold to justify enterprise-wide contracts that bundle capital equipment with multi-year service subscriptions.
Pricing Analysis
Capacity additions in German precision optics clusters are reshaping price floors for infrared tracking arrays that anchor navigation system hardware costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared robotics platforms from CE-marked navigation software and uncertified instrument attachments. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling that includes surgeon proctoring and software updates. Cost compression in mid-tier surgical navigation systems is intensifying because Japanese manufacturers are expanding electromagnetic platform production. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for optical tracking hardware and electromagnetic field generators. German precision optics manufacturers supply infrared camera arrays; Japanese sensor fabricators produce electromagnetic coils; American software developers generate navigation algorithms. Raw material dependencies include rare-earth magnets for field generators, specialized glass for optical lenses, and high-purity aluminum for robotic arm housings. Single-source vulnerability concentrates in Japanese electromagnetic sensor production. Distribution runs through OEM direct sales for robotics platforms and medical device distributors for navigation instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where hospital value analysis committees are consolidating vendor relationships around navigation-robotics bundles that deliver measurable revision rate reductions. Demand is shifting toward premium specifications that demonstrate EU MDR compliance and FDA 510(k) clearance.
For Market Incumbents: Deepen backward integration into optical tracking component fabrication to secure supply continuity against Japanese sensor concentration. Expand proprietary software development capabilities to defend margin position against pure-play navigation vendors licensing algorithmic modules. Prioritize ISO 13485 certification alignment for trauma and extremities applications where competitive saturation remains lower than joint replacement segments. For New Entrants and Emerging Players: Enter via specialized trauma navigation protocols for shoulder and ankle reconstruction that occupy underserved procedural niches with reduced competitive intensity. Target ambulatory surgical centers in the United States where outpatient joint replacement growth is compressing platform miniaturization timelines. Pursue software-only licensing models that bypass capital equipment manufacturing barriers and accelerate hospital procurement cycles. For Investors and Strategic Acquirers: Roll-up economics work for pure-play navigation software vendors because hospital procurement consolidation is fragmenting vendor relationships and creating acquisition targets with installed base leverage. Long-term viability centers on platforms demonstrating regulatory compliance across FDA, EU MDR, and PMDA pathways. Monitor PMDA Shonin approval timelines for Japanese market entry as an inflection indicator for Asia-Pacific expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways for computer vision modules are extending as regulators evaluate algorithmic performance variability. |
| CE Marking Pathway | EU MDR software-as-a-medical-device classification restructures quality management systems for cybersecurity compliance. |
| Hospital System Partnership | Value analysis committees consolidate vendor relationships around bundled navigation-robotics contracts spanning facility footprints. |
| Software Companion Development | Machine learning modules for markerless tracking represent the fastest-expanding technology segment in anatomical recognition. |
| Reimbursement Strategy | Japan's PMDA Shonin alignment with reimbursement structures favors precision joint replacement in tertiary care centers. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down robotics installation tracking forms the analytical core of this study. Primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers were combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Triangulation between demand-side capital expenditure patterns and supply-side manufacturing capacity announcements ensures cross-verified outputs.
Input-output matrix framing connects procedure volume forecasts to system utilization rates and capital equipment replacement cycles across the projection horizon. Segmentation dimensions modeled include product configuration, tracking technology, surgical application, and end-user facility type. CAGRs were derived from regression analysis against aging demographic trajectories and reimbursement alignment indicators. Industry-specific forecast inputs incorporate PMDA approval timelines and bundled payment program expansion rates.
Inputs from FDA premarket notification databases and EU MDR conformity assessment records were available through the study window; gaps in private hospital capital expenditure disclosures introduce uncertainty bands around installed base estimates. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and surgeon training adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Global Spinal Fusion Devices Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
US Orthopedic Implants Market