
 Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market | 2026-2036
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market Size, Share, and Industry Trends Forecast 2026-2036
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market Analytics
The EU Medical Device Regulation (MDR) is pivoting European procurement toward biocompatible, recyclable materials in brace fabrication. Enovis leverages its carbon-fiber molding expertise to supply hospitals with lightweight trauma braces. Bauerfeind anchors the German market through its patient-specific measurement protocols and certified orthotist networks. Össur competes on silicone-liner integration for prosthetic-orthotic hybrid systems.
Orthotic devices, splints, and orthopedic braces and supports comprise mechanically engineered external apparatuses—typically fabricated from thermoplastics, aluminum alloys, or carbon-fiber composites via vacuum-forming or CAD-CAM milling—to immobilize, align, or offload musculoskeletal structures. Their primary purpose spans post-trauma stabilization, osteoarthritis load redistribution, and post-operative limb protection during collagen remodeling phases. Foot orthoses command durable revenue streams through repeat dispensing cycles for diabetic neuropathy and plantar fasciitis patients. Thermoplastic segments attract R&D investment due to heat-moldability enabling same-day clinical customization. Rehabilitation centers represent the fastest-growing end-user channel as value-based care bundles shift joint-replacement recovery outside hospital walls.
The FDA's 510(k) framework and the EU MDR's Class I/IIa classification rules shape material traceability and clinical evidence requirements for market authorization. ISO 13485 quality management standards govern manufacturing consistency across both jurisdictions, while Health Canada's Medical Devices Bureau enforces parallel biocompatibility testing for polymer-based supports. Stakeholders must monitor evolving reimbursement coding for remote orthotic fitting and digital scan-to-manufacture workflows.
Market Dynamics
The orthotic devices market is experiencing a fundamental reconfiguration as value-based care contracts push joint-replacement recovery into outpatient rehabilitation networks, compressing traditional hospital procurement cycles and demanding same-day customization capabilities from manufacturers.
Growth Catalysts
- MDR Material Mandates:The EU Medical Device Regulation's biocompatibility requirements are accelerating R&D into recyclable thermoplastics for brace fabrication, creating competitive differentiation for compliant suppliers.
- Medicare Advantage Expansion:United States reimbursement policy now covers custom-fabricated orthoses for chronic conditions, expanding addressable volume among diabetic neuropathy and osteoarthritis patient populations.
- Carbon-Fiber Maturity:Vacuum-forming and CAD-CAM milling advances are reducing per-unit production costs for lightweight trauma braces, enabling penetration into price-sensitive clinical channels.
Market Restraints
- Aluminum Alloy Volatility:Input cost fluctuations for lightweight metal components constrain margin stability for mid-tier brace manufacturers dependent on commodity supply chains.
- 510(k) Evidence Burden:The FDA's moderate-risk pathway demands substantial clinical documentation for novel materials, extending time-to-market for innovative polymer-based supports.
- DIY Retail Substitution:Over-the-counter compression sleeves and prefabricated supports capture price-sensitive demand for minor sprains and chronic pain management.
Strategic Opportunities
- Remote Fitting Infrastructure:Digital scan-to-manufacture workflows enable direct-to-patient distribution, bypassing traditional orthotist intermediaries in dispersed rural geographies.
- Silicone-Liner Convergence:Integration of prosthetic-grade liner technology into orthopedic braces creates premium positioning for post-operative limb protection applications.
- Japan's Aging Infrastructure:METI-supported rehabilitation expansion in prefectural health systems generates demand for patient-specific measurement protocols and certified fitting networks.
Industry Challenges
- Orthotist Certification Bottlenecks:Shortages of certified fitting specialists delay custom device dispensing, particularly in markets with fragmented professional training pathways.
- ISO 13485 Compliance Costs:Quality management system audits and documentation requirements impose disproportionate overhead on small-scale manufacturers serving niche anatomical segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market |
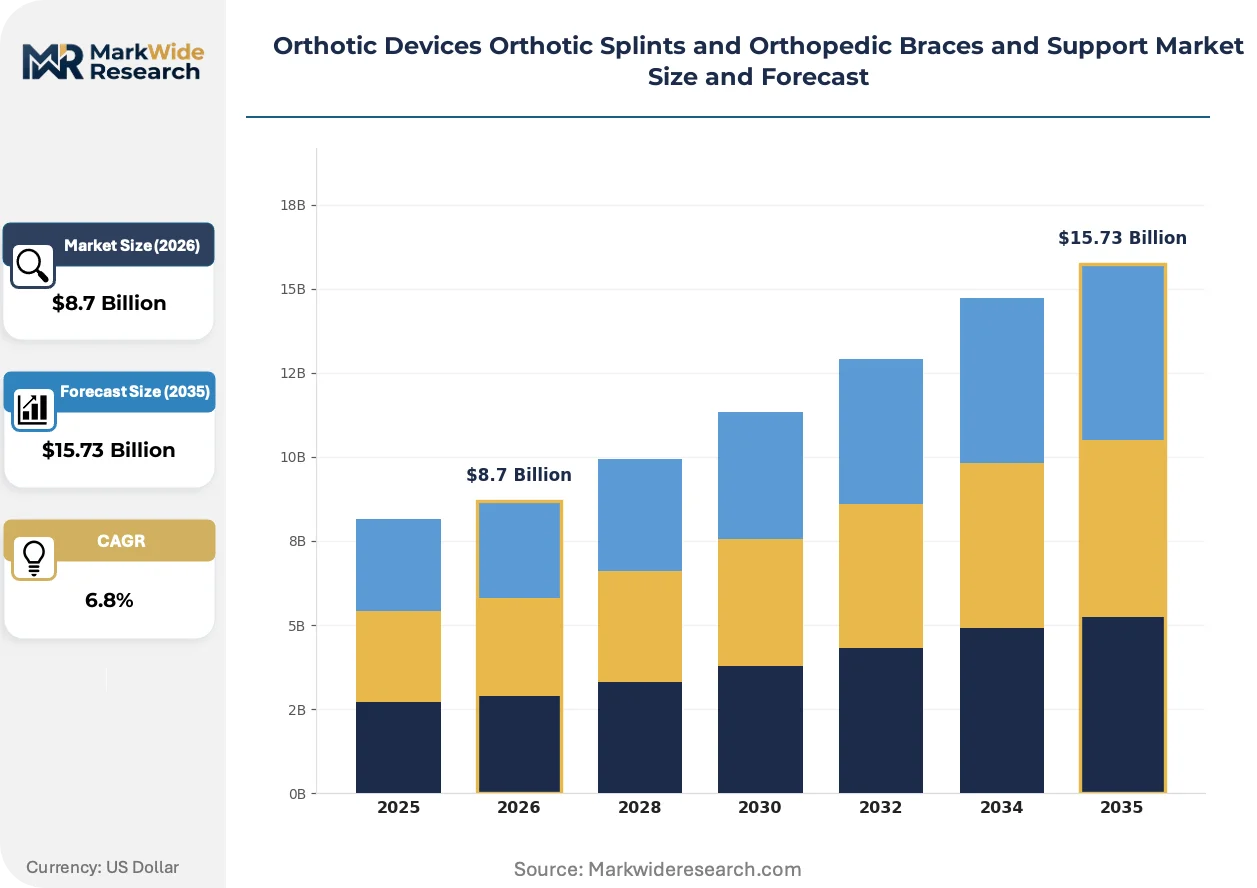
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Splints, Braces, Supports, Foot Orthoses Material: Thermoplastics, Fabrics, Composites, Metal End User: Clinics, Hospitals, Home Care, Rehabilitation Centers Application: Injury Recovery, Pain Management, Surgical Recovery, Preventive Care |
| Companies Covered | Enovis, Ottobock, Össur, Zimmer Biomet, 3M Company, Bauerfeind, DeRoyal Industries, Breg, Essity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market Evolving Landscape
Digital fabrication workflows and regulatory material mandates are converging to reshape how orthotic devices are designed, produced, and distributed across clinical and retail channels.
CAD-CAM milling technology is modularizing production economics for custom foot orthoses. Podiatry clinics and rehabilitation centers are adopting in-house digital scanning systems at accelerating rates. This distributed manufacturing capability is compressing fulfillment timelines from weeks to same-day service, enabling capture of repeat dispensing cycles for plantar fasciitis and diabetic foot management.
REACH substance restrictions are forcing reformulation of polymer-based support materials across European supply chains. Industrial consequence includes accelerated validation of bio-based thermoplastics with equivalent heat-moldability properties. German and French manufacturers are responding fastest, securing early-mover positioning for MDR-compliant brace portfolios ahead of enforcement deadlines.
Hospital procurement departments are consolidating vendor relationships under value-based care bundles for joint-replacement episodes. Rehabilitation centers and ambulatory surgery centers are displacing traditional hospital orthopedic departments as primary brace purchasers. This channel rotation is most pronounced in United States markets where Medicare bundled payment models concentrate purchasing authority with post-acute providers.
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market Segmentation
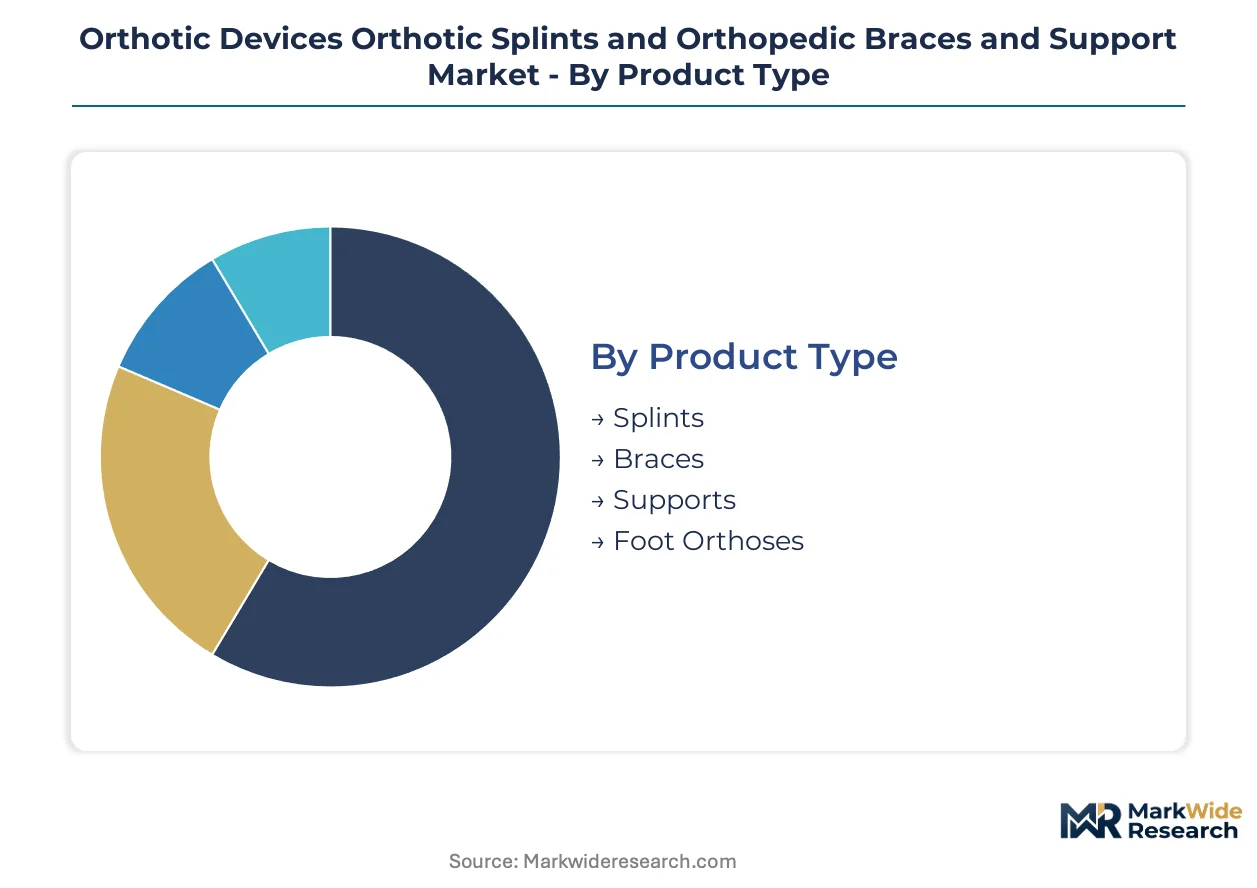
Orthotic device segmentation reflects divergent clinical requirements across acute intervention versus chronic management pathways. Material selection and distribution channel strategies must align with specific reimbursement codes and patient mobility profiles to capture value.
Product Type:
Customization intensity varies sharply across this category, from mass-produced compression supports to patient-matched carbon-fiber trauma braces requiring certified orthotist fitting.
- Foot Orthoses:CAD-CAM milled or vacuum-formed inserts addressing plantar fasciitis, diabetic neuropathy, and biomechanical misalignment. Repeat dispensing cycles in podiatry clinics and rehabilitation centers sustain revenue predictability through chronic condition management.
- Braces:Hinged or rigid structures fabricated from aluminum alloys, carbon-fiber composites, or thermoplastics for joint stabilization. Post-operative limb protection protocols in ambulatory surgery centers and hospital orthopedic departments concentrate procurement authority for trauma and osteoarthritis applications.
- Splints:Static or dynamic immobilization devices for fracture management and soft-tissue injury recovery. Emergency departments and urgent care clinics drive volume for acute trauma stabilization with prefabricated sizing options.
- Supports:Elastic or neoprene compression garments for proprioceptive feedback and mild instability management. Retail pharmacy channels and direct-to-consumer distribution capture price-sensitive demand for minor sprains and chronic pain self-management.
Leading the category by volume: Supports. Expanding most quickly: Foot Orthoses.
Material:
Cost tier stratification separates premium composite solutions from commodity metal and fabric alternatives, with thermoplastic segments attracting concentrated R&D investment for same-day clinical customization.
- Thermoplastics:Heat-moldable polymers enabling same-day fabrication and adjustment in clinical settings. REACH substance restrictions and EU MDR biocompatibility mandates are accelerating validation of recyclable, bio-based formulations across German and French manufacturing bases.
- Composites:Carbon-fiber and fiberglass-reinforced structures delivering strength-to-weight ratios critical for trauma bracing. Vacuum-forming and CAD-CAM milling advances are reducing per-unit production costs, enabling penetration into price-sensitive clinical channels.
- Metal:Aluminum and stainless-steel components for rigid structural elements in post-operative and severe trauma applications. Input cost volatility constrains margin stability for mid-tier manufacturers dependent on commodity supply chains.
- Fabrics:Elastic, neoprene, and breathable mesh materials for compression supports and soft braces. Over-the-counter retail substitution captures substantial volume for minor injury management outside reimbursed clinical pathways.
Highest margin concentration: Composites. Steepest volume expansion: Thermoplastics.
End User:
Channel maturity reflects shifting site-of-care economics, with value-based care bundles displacing traditional hospital purchasing authority toward post-acute and outpatient settings.
- Rehabilitation Centers:Outpatient facilities managing joint-replacement recovery and neuromuscular rehabilitation. Medicare bundled payment models in the United States concentrate brace procurement authority with post-acute providers, making this the fastest-expanding channel.
- Hospitals:Acute care orthopedic departments and ambulatory surgery centers for immediate post-operative stabilization. Procurement consolidation under episode-based contracts is compressing vendor relationships and demanding same-day customization capabilities.
- Clinics:Podiatry, sports medicine, and orthotist practices dispensing custom-fabricated devices. In-house digital scanning and CAD-CAM milling adoption is compressing fulfillment timelines from weeks to same-day service.
- Home Care:Direct-to-patient distribution for chronic condition management and remote rural access. Digital scan-to-manufacture workflows enable bypass of traditional orthotist intermediaries in dispersed geographies.
Capturing procurement authority fastest: Rehabilitation Centers. Maintaining highest volume: Hospitals.
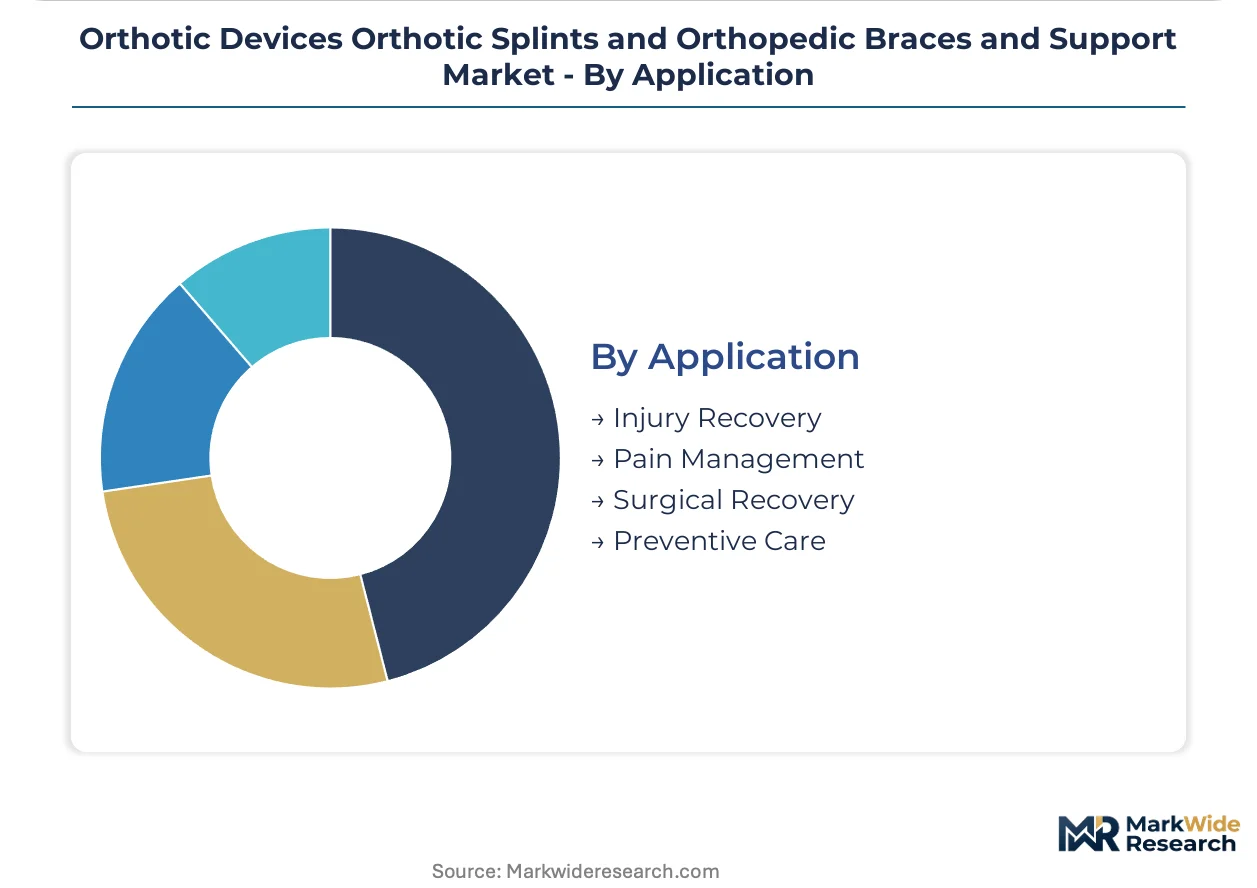
Application:
Patient acuity and reimbursement intensity determine margin structure, with surgical recovery commanding premium pricing and preventive care facing retail substitution pressure.
- Surgical Recovery:Post-operative limb protection during collagen remodeling phases following joint replacement or trauma repair. Hospital and ambulatory surgery center procurement demands biocompatible materials with documented clinical outcomes for value-based contract compliance.
- Pain Management:Chronic osteoarthritis load redistribution and neuropathic pain mitigation through custom foot orthoses and unloading braces. Medicare Advantage expansion for custom-fabricated orthoses is enlarging addressable volume among diabetic and geriatric populations in the United States.
- Injury Recovery:Acute trauma stabilization for fractures, ligament tears, and soft-tissue damage. Emergency department and urgent care dispensing favors prefabricated solutions with rapid sizing and immediate availability.
- Preventive Care:Prophylactic bracing for sports participation and occupational injury risk reduction. Over-the-counter retail channels and direct-to-consumer marketing capture substantial volume outside reimbursed clinical pathways.
Highest reimbursement intensity: Surgical Recovery. Facing greatest retail substitution: Preventive Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis medical device corridor anchors North American orthotic manufacturing, with carbon-fiber fabrication facilities serving hospital procurement networks across the Upper Midwest.
United States
Medicare Advantage plans now cover custom-fabricated orthoses for diabetic neuropathy and osteoarthritis, expanding the addressable patient base among aging populations. The FDA's 510(k) clearance pathway streamlines commercial entry for moderate-risk devices. Minneapolis-St. Paul hosts concentrated manufacturing operations supplying rehabilitation centers and ambulatory surgery centers with CAD-CAM milled foot orthoses.
Germany
Bauerfeind's patient-specific measurement protocols and certified orthotist networks anchor domestic demand for precision-fitted braces. The EU Medical Device Regulation's biocompatibility mandates accelerate R&D into recyclable thermoplastics for brace fabrication. The Stuttgart industrial region houses specialized carbon-fiber molding operations serving hospital procurement departments across Bavaria and Baden-Württemberg.
Japan
METI-supported rehabilitation expansion in prefectural health systems generates demand for certified fitting networks and patient-specific protocols. The PMDA maintains parallel biocompatibility testing requirements for polymer-based supports entering clinical channels. The Osaka-Kobe manufacturing belt concentrates production of lightweight trauma braces for post-operative limb protection.
China
NMPA regulatory harmonization with ISO 13485 standards is elevating quality management requirements for domestic manufacturers. The country's national medical device regulator enforces stricter clinical evidence documentation for novel materials. The Yangtze River Delta industrial corridor hosts vacuum-forming operations producing thermoplastic splints for domestic hospital networks and export markets.
United Kingdom
NHS procurement consolidation under value-based care bundles is compressing vendor relationships for joint-replacement recovery devices. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with retained EU MDR provisions. The Cambridge-Oxford-London golden triangle attracts digital health ventures developing remote orthotic fitting platforms.
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with orthotic divisions alongside specialized orthotics-native manufacturers. Market concentration remains moderate, with no single entity commanding dominant share across all material and application segments. Three archetypes define competitive positioning: carbon-fiber composite specialists, thermoplastic customization leaders, and integrated rehabilitation device suppliers. M&A activity targets digital scanning capabilities, while capacity expansion concentrates in FDA-registered and MDR-compliant manufacturing facilities.
Among diversified medical technology conglomerates, Zimmer Biomet and 3M Company occupy positions spanning surgical recovery and patient care portfolios. Specialized orthotics manufacturers Enovis and Össur exemplify material-driven differentiation strategies, with the former representing carbon-fiber molding expertise and the latter anchoring silicone-liner integration capabilities. German fabricator Bauerfeind sits within the patient-specific measurement tier, demonstrating how certified orthotist networks create defensive positioning in regulated European markets.
| Leading Market Players |
|---|
| Enovis |
| Ottobock |
| Össur |
| Zimmer Biomet |
| 3M Company |
| Bauerfeind |
| DeRoyal Industries |
| Breg |
| Essity |
| Others |
Value Network & Pricing Analysis
CAD-CAM milling adoption in podiatry clinics and rehabilitation centers is compressing production economics for custom foot orthoses while simultaneously dispersing manufacturing capacity away from centralized fabrication facilities. This technology shift concentrates pricing power with equipment-integrated providers capable of same-day service delivery, while fragmenting supply relationships across distributed clinical networks.
Pricing Analysis
Episode-based reimbursement bundles anchor pricing for joint-replacement recovery braces, tying device costs to total procedural outcomes rather than standalone unit transactions. Price differentiation separates FDA 510(k)-cleared devices with documented clinical evidence from uncertified alternatives, while carbon-fiber composite grades command premiums over aluminum alloy equivalents. Pricing pressure stems from Medicare Advantage expansion demanding cost-efficient custom fabrication for chronic condition management. Hospital procurement committees exhibit highest price sensitivity due to consolidated vendor negotiations under value-based contracts, whereas certified orthotist networks maintain lowest sensitivity through patient-specific fitting premiums.
Supply Chain Analysis
Carbon-fiber prepreg supply rests on Japanese and German specialty material producers, with thermoplastic resin feedstocks drawing from petrochemical complexes in the United States and Belgium. Raw material dependencies span aerospace-grade carbon fiber, medical-grade silicone for liner integration, and REACH-compliant polymer formulations. Supply chain risk centers on single-source vulnerability for high-modulus carbon fiber grades essential to trauma brace lightweighting. Distribution runs through hospital procurement departments, GPO contracts, and direct-to-patient digital platforms serving dispersed rural geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's biocompatibility mandates and clinical evidence requirements erect a cost-of-compliance barrier that favors incumbent manufacturers with established ISO 13485 quality systems and regulatory affairs infrastructure.
For Market Incumbents: Extend certified orthotist network coverage into Japan's prefectural rehabilitation systems to capture METI-supported infrastructure expansion. Consolidate vendor relationships with ambulatory surgery centers displacing traditional hospital procurement authority. Defend against DIY retail substitution by integrating digital scanning workflows that preserve clinical fitting premiums.
For New Entrants and Emerging Players: Enter via remote fitting infrastructure for dispersed rural geographies bypassing traditional orthotist intermediaries. Target home care channels for diabetic neuropathy management where Medicare Advantage reimbursement now covers custom-fabricated orthoses. Pursue go-to-market partnerships with digital health platforms developing scan-to-manufacture capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking orthotic division expansion. Long-term viability favors manufacturers with MDR-compliant manufacturing footprints and carbon-fiber molding expertise. Watch FDA 510(k) clearance timelines for novel polymer-based supports as inflection indicators for innovative material adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Certification | EU MDR biocompatibility mandates create competitive moats for validated thermoplastic suppliers ahead of enforcement deadlines. |
| Digital Scan-to-Manufacture Integration | CAD-CAM milling adoption in clinics compresses fulfillment timelines from weeks to same-day service delivery. |
| Carbon-Fiber Capacity Expansion | Vacuum-forming advances reduce per-unit costs for lightweight trauma braces penetrating price-sensitive channels. |
| Silicone-Liner Technology Convergence | Prosthetic-grade liner integration creates premium positioning for post-operative limb protection applications. |
| Reimbursement Strategy Development | Medicare Advantage coverage expansion for custom orthoses enlarges addressable volume among diabetic populations. |
Research Methodology
Independent corroboration across primary interviews with hospital purchasing committees, certified orthotists, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up demand modeling across product type, material, end user, and application segments triangulates with top-down market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span customization intensity, biocompatibility certification tier, and site-of-care channel migration. CAGRs derive from patient population epidemiology, procedure volume trajectories, and reimbursement policy evolution. Forecast inputs incorporate orthopedic procedure migration patterns and certified orthotist supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum alloy price volatility and REACH substance restriction acceleration. Assumptions reflect current regulatory enforcement trajectories and reimbursement coding stability. A small set of named triggers warrants ongoing watch: FDA 510(k) evidence burden expansion, EU MDR deadline compliance rates, and Medicare Advantage benefit design evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Vertebroplasty Needles Market