
 Knee Braces Market | 2026-2036
Knee Braces Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Braces Market Intelligence
Asset-light leasing models for durable medical equipment is narrowing the capital barrier for mid-sized orthopedic distributors. Bauerfeind leverages its German manufacturing base to sustain premium positioning across European rehabilitation networks. Enovis competes through vertical integration into polymer hinge fabrication, reducing supplier dependency. Ottobock anchors its portfolio with custom-molded unloader designs that dominate the osteoarthritis segment in Central European markets.
Knee braces are mechanical orthotic devices constructed from neoprene, nylon, or thermoplastic composites with integrated metal or carbon fiber hinges, designed to stabilize the tibiofemoral joint through controlled range-of-motion restriction or load redistribution. Their primary commercial purpose spans postoperative immobilization, ligament injury management, and degenerative joint disease progression delay. Hinged braces command the largest revenue pool due to surgical recovery protocols, while prophylactic types represent the fastest-expanding category as youth and collegiate sports programs institutionalize injury prevention mandates. Wraparound configurations attract price-sensitive segments in retail pharmacy channels, whereas functional braces for ligament stability generate premium margins through prescription-linked distribution.
The FDA's 510(k) notification process and the EU Medical Device Regulation (MDR) classification framework govern market access, with MDR's heightened clinical evidence requirements extending certification timelines for European entrants. The U.S. Centers for Medicare & Medicaid Services durable medical equipment fee schedule directly influences reimbursement-driven purchasing decisions across orthopedic clinics and rehabilitation hospitals. Stakeholders must monitor evolving sports medicine consensus guidelines from the American Academy of Orthopaedic Surgeons, as these non-binding standards increasingly determine institutional procurement specifications and payer coverage determinations.
Market Dynamics
Carbon fiber hinge fabrication is consolidating manufacturing scale among orthopedic device suppliers, compressing production timelines for hinged brace categories while raising entry barriers for polymer-dependent competitors.
Growth Catalysts
- Youth sports injury prevention mandates:Collegiate athletic programs and secondary school districts are institutionalizing prophylactic brace protocols ahead of competitive seasons, expanding institutional procurement volume.
- EU Medical Device Regulation clinical evidence pathways:MDR's heightened documentation requirements for Class I medical devices is accelerating consolidation among manufacturers with established quality management systems.
- Osteoarthritis progression management:Aging demographics in rehabilitation networks are driving unloader brace adoption as non-surgical intervention before joint replacement eligibility.
Market Restraints
- Carbon fiber composite input volatility:Aerospace and automotive demand for carbon fiber prepreg is constraining orthopedic-grade material allocation, pressuring hinge component costs.
- Reimbursement rate compression:CMS durable medical equipment fee schedule adjustments are narrowing margin pools for prescription-linked distribution channels.
- Retail pharmacy substitution:Elastic compression sleeves and basic neoprene supports are capturing price-sensitive segments outside clinical prescription pathways.
Strategic Opportunities
- Asset-light leasing models:Durable medical equipment rental platforms are emerging as alternative channels for mid-sized orthopedic distributors seeking to reduce capital deployment.
- Telehealth-integrated fitting protocols:Remote measurement technologies and 3D scanning applications are enabling custom-molded brace fulfillment without clinic-based casting appointments.
- Swissmedic-recognized quality certifications:Swiss regulatory recognition is opening premium positioning pathways for manufacturers targeting Central European rehabilitation networks.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized orthotic design expertise combining polymer science with kinematic modeling is concentrating among established European and North American manufacturers.
- 510(k) documentation timelines:FDA premarket notification preparation for novel hinge mechanisms is extending product launch schedules by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Braces Market |
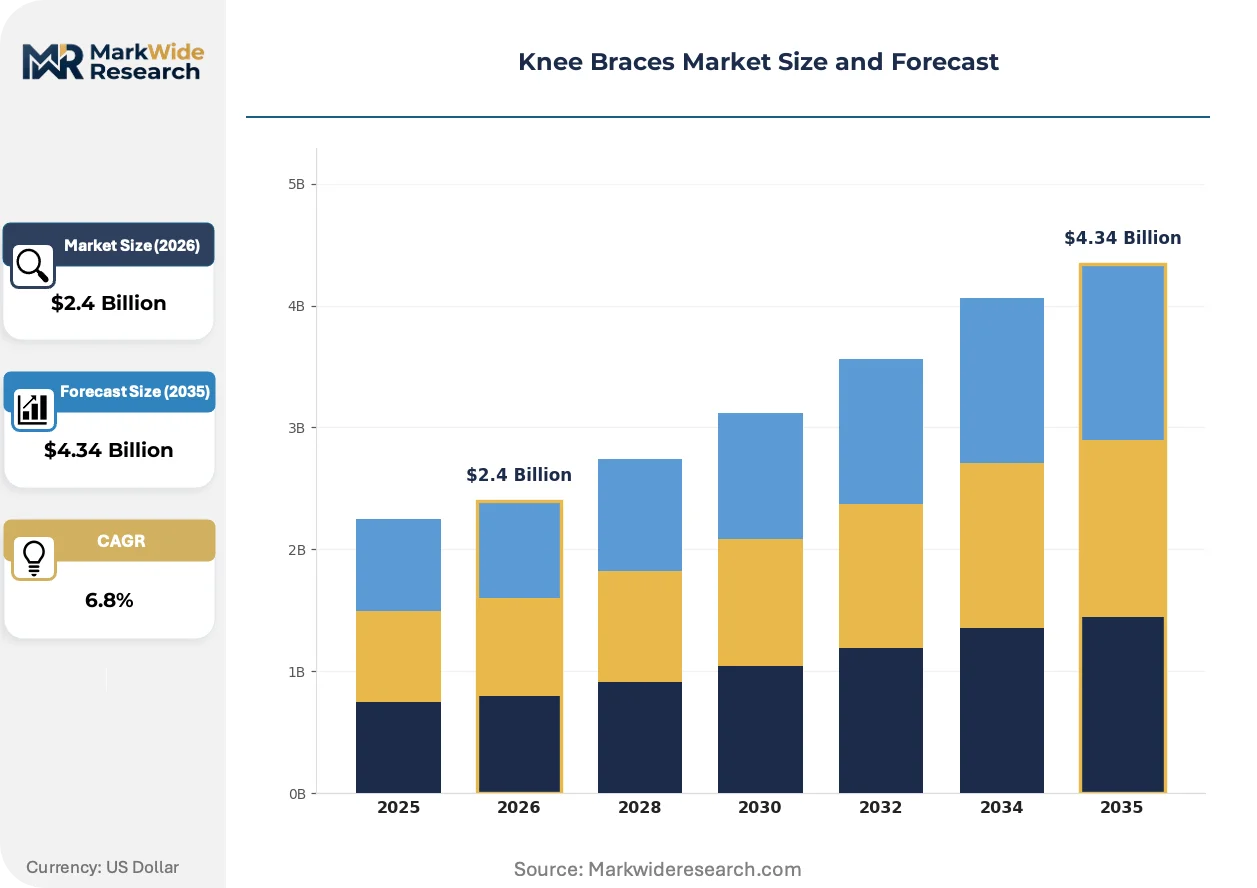
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hinged, Prophylactic, Functional, Unloader, Wraparound Material: Nylon, Neoprene, Polyester, Thermoplastic, Elastic Fabric Application: Sports Injury, Postoperative Support, Arthritis Relief, Ligament Stability End User: Orthopedic Clinics, Physical Therapy Centers, Sports Academies, Rehabilitation Hospitals |
| Companies Covered | Enovis, Ottobock, Bauerfeind, Breg, DonJoy, McDavid, Ossur, Futuro, LP Support, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Braces Market Strategic Shifts & Innovations
Digital fabrication workflows and sensor-integrated orthotics are redefining how knee braces are specified, manufactured, and monitored across postoperative and preventive care settings.
Sensor-embedded hinge mechanisms with real-time range-of-motion telemetry are virtualizing the traditional brace fitting process. Orthopedic clinics in Germany and the United States are piloting these systems for remote patient monitoring after anterior cruciate ligament reconstruction. The technology is virtualizing postoperative check-in protocols, reducing in-person physical therapy visits while generating adherence data for payer documentation.
EU MDR's strengthened post-market surveillance obligations are extending certification maintenance costs for European market participants. Manufacturers must now maintain clinical evidence portfolios across product lifecycles rather than at initial clearance. Hinged brace categories with higher risk classifications are experiencing the most pronounced compliance resource reallocation, with some suppliers narrowing European product lines to focus on core SKUs.
Direct-to-consumer configuration platforms are fragmenting traditional prescription-channel dominance. Patients with established diagnoses are self-directing toward online brace retailers offering telehealth-supported sizing, bypassing orthopedic clinic markup structures. This pattern is most visible in the United States, where high-deductible health plan enrollment has sensitized buyers to out-of-pocket cost differentials between retail and clinical procurement pathways.
Knee Braces Market Segmentation
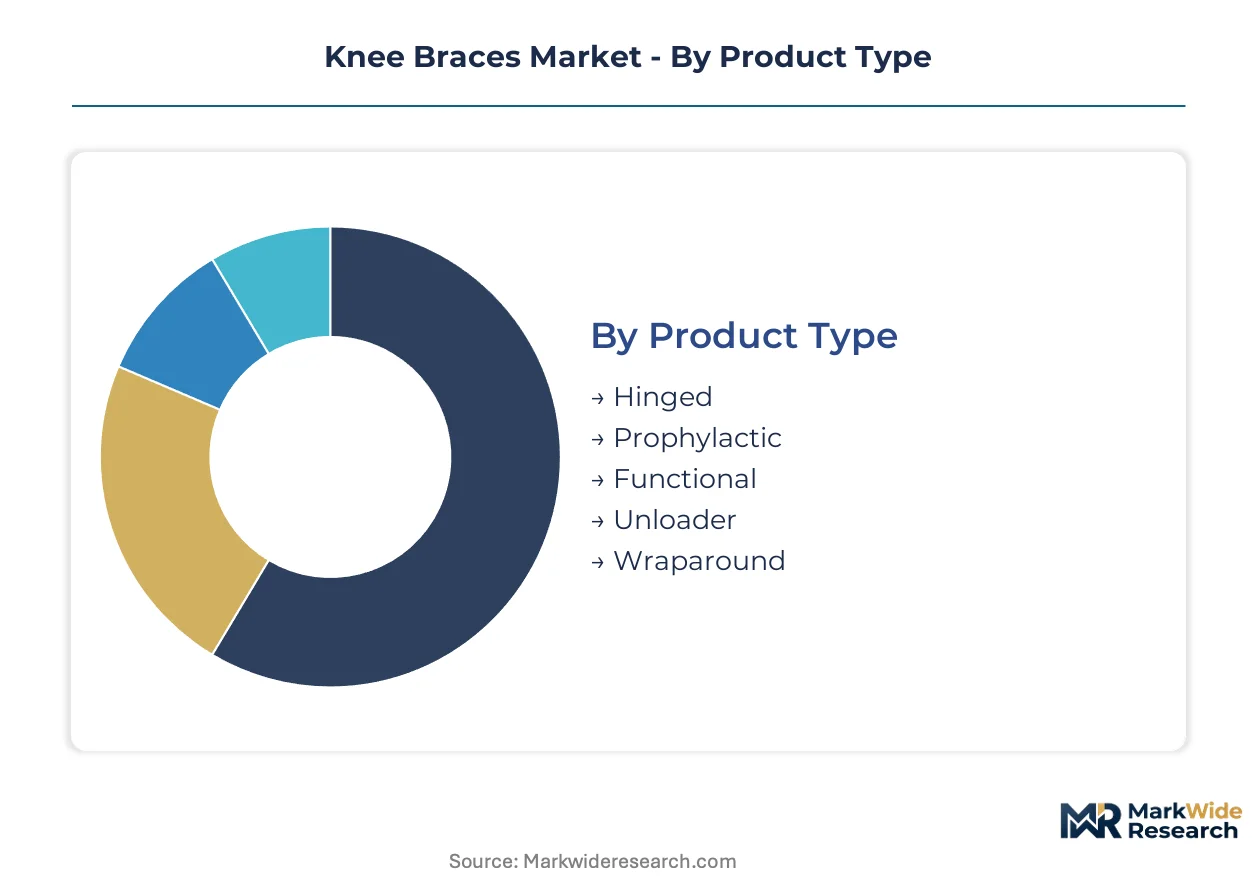
Knee brace procurement patterns diverge sharply across clinical, athletic, and retail channels, with hinge complexity and material grade determining reimbursement eligibility and price positioning. Manufacturers optimize SKU portfolios by mapping product specifications to institutional buying criteria rather than consumer preference alone.
Product Type:
Cost tier stratification separates prescription-linked therapeutic devices from retail-accessible preventive supports.
- Hinged:Carbon fiber or aluminum alloy hinge mechanisms integrated into rigid thermoplastic shells deliver calibrated range-of-motion restriction for postoperative protocols. Orthopedic clinic networks in the United States concentrate procurement volume here, driven by anterior cruciate ligament reconstruction recovery mandates and CMS durable medical equipment reimbursement codes.
- Prophylactic:Bilateral hinge designs with flexible strapping systems protect intact ligaments during high-impact athletic activity. Collegiate sports medicine programs and secondary school districts are institutionalizing seasonal distribution protocols ahead of competitive schedules, expanding institutional procurement pipelines.
- Functional:Anterior or posterior cruciate ligament instability management through adjustable hinge resistance.
- Unloader:Three-point pressure systems redistribute compressive load across the tibiofemoral joint for osteoarthritis progression delay.
- Wraparound:Velcro-closure neoprene sleeves for mild instability or proprioceptive feedback in retail pharmacy channels.
Hinged designs command the established base. The steepest expansion runs through prophylactic distribution.
Material:
Application severity dictates material selection, with moisture management and thermoformability driving specification decisions.
- Neoprene:Closed-cell synthetic rubber delivers thermal retention and compression uniformity for inflammatory joint management. Rehabilitation hospitals specify neoprene-dominant constructions for extended wear protocols, though breathability limitations restrict high-activity applications.
- Thermoplastic:Heat-moldable copolymer shells enable patient-specific contouring for postoperative immobilization and unloader mechanics. German and Swiss rehabilitation networks prioritize thermoplastic platforms for custom orthotic workflows, leveraging digital scanning integration.
- Nylon:High-tenacity woven face fabrics for abrasion resistance in athletic environments.
- Polyester:Moisture-wicking knit constructions for prolonged wear comfort.
- Elastic Fabric:Four-way stretch blends for compression sleeve categories in retail channels.
Thermoplastic constructions anchor premium positioning. Elastic fabric variants are climbing the fastest through direct-to-consumer platforms.
Application:
Customer type segmentation separates acute trauma management from chronic disease progression protocols.
- Postoperative Support:Rigid immobilization transitioning to hinged mobilization protects surgical repair sites during collagen remodeling phases. United States orthopedic surgery volumes and bundled payment incentives concentrate demand here, with prescription-channel distribution ensuring reimbursement capture.
- Ligament Stability:Anterior cruciate, posterior cruciate, medial collateral, and lateral collateral injury management through mechanical substitution or protection. Sports academies in Germany and collegiate athletic conferences in the United States drive specification intensity, with injury prevention mandates expanding prophylactic deployment.
- Sports Injury:Acute trauma management and return-to-play clearance across competitive levels.
- Arthritis Relief:Load redistribution and proprioceptive enhancement for degenerative joint disease.
Postoperative support commands the established base. Ligament stability applications are gaining share fastest through institutional sports medicine protocols.
End User:
Volume concentration varies by procurement authority, with reimbursement pathways determining channel access.
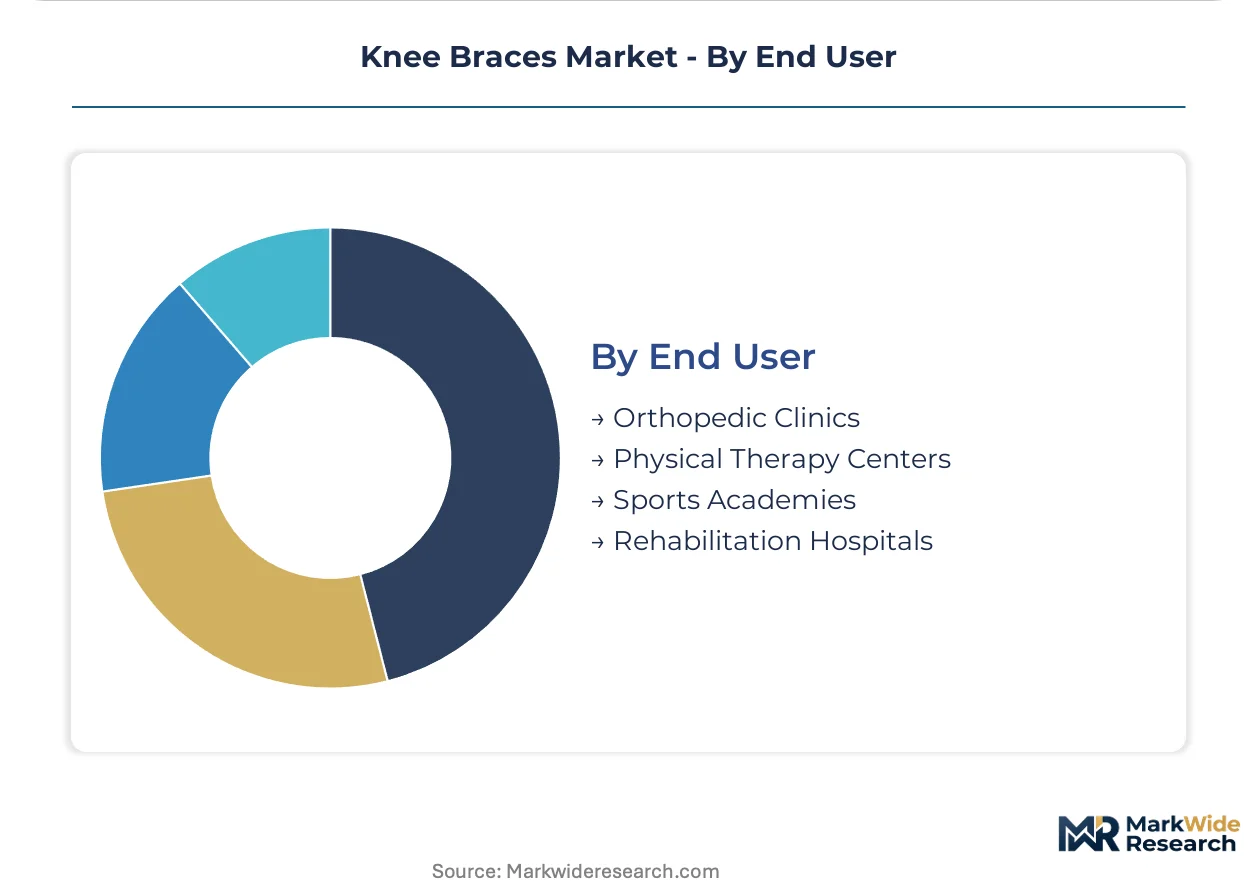
- Orthopedic Clinics:Physician-directed prescription fulfillment for postoperative and traumatic injury populations. United States clinic networks and German outpatient orthopedic centers concentrate high-margin hinged and unloader categories, leveraging direct payer contracts and durable medical equipment billing privileges.
- Sports Academies:Institutional procurement for athlete cohort protection and injury prevention standardization. NCAA Division I programs and Bundesliga youth academies are formalizing seasonal brace distribution protocols, expanding prophylactic volume outside traditional clinical channels.
- Physical Therapy Centers:Rehabilitation-phase fitting and patient education for functional progression.
- Rehabilitation Hospitals:Post-acute care protocols for complex trauma and joint replacement preparation.
Orthopedic clinics command the established base. Sports academies show the steepest expansion trajectory through preventive mandate institutionalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy divergence is fragmenting procurement pathways across major markets. CMS durable medical equipment fee schedules in the United States concentrate prescription-linked volume, while EU MDR compliance costs are reshaping European competitive positioning. Swissmedic recognition and Japanese PMDA pathways are opening premium positioning corridors for quality-certified manufacturers.
United States
Orthopedic clinic networks and NCAA Division I sports medicine programs drive hinged and prophylactic brace procurement through institutional contracts. FDA 510(k) clearance timelines for Class I medical devices shape product entry schedules, with hinge mechanism innovations requiring six-to-eighteen month documentation preparation. The Dallas-Fort Worth metroplex anchors distribution infrastructure for southwestern rehabilitation hospital networks.
Germany
Bundesliga youth academies and outpatient orthopedic centers concentrate demand for custom-molded thermoplastic constructions. EU MDR clinical evidence requirements for post-market surveillance are extending certification maintenance costs, accelerating consolidation among manufacturers with established quality management systems. The Bavarian industrial corridor around Munich hosts fabrication facilities serving Central European rehabilitation networks.
Switzerland
Swissmedic-recognized quality certifications are opening premium positioning pathways for manufacturers targeting alpine rehabilitation clinics and sports medicine institutes. The country's dual insurance system creates differentiated procurement channels between statutory and private coverage. The Zurich-Geneva corridor concentrates orthopedic device distribution for cross-border Central European supply.
Japan
PMDA medical device classification frameworks govern knee brace market access, with aging demographics driving unloader brace adoption for osteoarthritis progression management. METI industrial policy supports domestic manufacturing of polymer composite components. The Kansai region around Osaka anchors production capacity for thermoplastic shell fabrications serving East Asian export markets.
Australia
TGA medical device regulations align with EU MDR standards, streamlining certification pathways for European manufacturers entering the market. Private health insurance coverage for postoperative orthotics drives prescription-channel volume. Sydney and Melbourne metropolitan areas concentrate sports medicine clinics and rehabilitation hospitals specifying hinged brace categories for ligament injury protocols.
Knee Braces Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Orthopedic clinic networks and institutional sports medicine programs concentrate volume among manufacturers with direct payer contracts and durable medical equipment billing privileges. Three archetypes dominate: German-engineered premium fabricators, vertically integrated polymer hinge producers, and direct-to-consumer configuration platforms. Competitive moves center on M&A for quality management system acquisition and telehealth-integrated fitting protocol development.
Within the premium-engineered tier, Bauerfeind exemplifies manufacturing-base sustainability for European rehabilitation network positioning. Ottobock anchors custom-molded specialization that dominates osteoarthritis segments in Central European markets. Among vertically integrated producers, Enovis occupies a position representing captive supply of polymer hinge components that reduces supplier dependency. These three entities collectively illustrate the competitive tension between geographic manufacturing heritage and supply chain control strategies.
| Leading Market Players |
|---|
| Enovis |
| Ottobock |
| Bauerfeind |
| Breg |
| DonJoy |
| McDavid |
| Ossur |
| Futuro |
| LP Support |
| Others |
Cost & Logistics Intelligence
Carbon fiber prepreg allocation volatility from aerospace and automotive demand determines both pricing tier spreads and supply chain shape across orthopedic brace manufacturing. Manufacturers with captive polymer hinge fabrication command margin insulation, while those dependent on spot-market carbon fiber inputs face cost compression that forces portfolio narrowing toward premium therapeutic categories.
Pricing Analysis
Certification level creates the primary spread between FDA 510(k)-cleared prescription devices and retail-accessible supports. Three-tier pricing structure across premium, standard, and economy levels separates custom-molded thermoplastic unloader braces from off-the-shelf hinged designs and basic neoprene sleeves. Cost compression in the retail channel intensifies because direct-to-consumer platforms bypass clinic markup structures. Price-sensitive segments concentrate in high-deductible health plan enrollees self-directing through online retailers, while orthopedic clinics show lowest sensitivity due to CMS reimbursement capture.
Supply Chain Analysis
Extended payment terms from German and Swiss rehabilitation networks are reshaping supplier financing structures for component vendors. Manufacturing gravity centers on Germany, China, and the United States for hinge fabrication and shell molding operations. Raw material dependencies rest on carbon fiber composites from aerospace suppliers, medical-grade neoprene from Southeast Asian polymer processors, and aluminum alloys from European metallurgical facilities. Single-source vulnerability concentrates in aerospace-grade carbon fiber prepreg allocation, where orthopedic device manufacturers compete with automotive and aviation OEMs for limited supply. Distribution runs through orthopedic clinic networks, institutional sports medicine programs, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded hinge mechanisms with real-time telemetry are disrupting traditional fitting protocols, creating acquisition opportunities for manufacturers with digital fabrication capabilities and remote monitoring software.
For Market Incumbents: Build regulatory certification moats through EU MDR quality management system investments ahead of smaller competitors' compliance resource exhaustion. Acquire telehealth-integrated fitting platforms to defend against direct-to-consumer channel fragmentation. Backward integration into carbon fiber composite processing reduces aerospace demand volatility exposure. Channel control through exclusive orthopedic clinic contracts preserves prescription-linked margin pools.
For New Entrants and Emerging Players: Establish a beachhead in prophylactic brace distribution through collegiate sports medicine program partnerships, where institutional procurement protocols are still formalizing. Target secondary school districts with seasonal distribution mandates as the most penetrable segment outside established clinical channels. Deploy 3D scanning-enabled custom fitting as a go-to-market angle to bypass incumbent casting appointment infrastructure.
For Investors and Strategic Acquirers: EU MDR's heightened clinical evidence requirements reshape the acquisition landscape toward manufacturers with established post-market surveillance capabilities. Long-term viability centers on entities with digital fabrication workflows and sensor integration roadmaps. Target acquisition archetypes include quality-certified German manufacturers with Swissmedic recognition and captive hinge production. Watch FDA 510(k) clearance velocity for novel mechanism categories as the signal indicating competitive repositioning windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth-Integrated Fitting Protocol | Remote 3D scanning reduces clinic dependency and captures direct-to-consumer volume. |
| EU MDR Quality System Acquisition | Post-market surveillance capabilities accelerate certification timelines for European market entry. |
| Carbon Fiber Composite Backward Integration | Captive prepreg allocation insulates hinge production from aerospace demand competition. |
| Sensor-Embedded Hinge Development | Real-time range-of-motion telemetry enables remote patient monitoring reimbursement pathways. |
| Collegiate Sports Medicine Partnership | Institutional procurement mandates for prophylactic distribution expand non-clinical channel volume. |
Research Approach
Cross-validation between orthopedic surgeon interviews and CMS durable medical equipment claims data anchors the qualitative findings. Primary fieldwork engaged sports medicine directors, biomedical engineers at brace manufacturers, GPO contracts managers, and rehabilitation hospital procurement officers. Secondary sources encompassed FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and collegiate athletic program equipment bid records. Bottom-up unit demand modeling and top-down reimbursement flow analysis were reconciled through iterative calibration.
Calibration against historical product launch timelines and certification cycle durations refined the analytical framework. Segmentation dimensions spanned product type, material grade, application severity, and end-user procurement authority across the projection horizon. CAGRs were derived from procedure volume trajectories, sports participation rates, and reimbursement policy evolution. Forecast inputs incorporated anterior cruciate ligament reconstruction incidence patterns and osteoarthritis prevalence demographics.
Sensitivities concentrate around carbon fiber supply allocation shifts, CMS fee schedule adjustments, and EU MDR enforcement intensity variations. Forecasts reflect assumptions regarding regulatory pathway stability and institutional procurement protocol continuity. Macroeconomic contraction affecting elective procedure volumes, regulatory timeline extensions for novel hinge mechanisms, or technological substitution from regenerative medicine approaches would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Bioimpedance Devices Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Pipetting Systems Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Penile Implants Market
Medical Devices
Heating Pads Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Global Nasal Spray Market