
 Spine Devices Market | 2026-2036
Spine Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spine Devices Market Outlook
North American implant manufacturers is pivoting toward robotic-assisted delivery systems to capture premium positioning. Medtronic leverages integrated navigation platforms to sustain technology leadership across hospital networks. Stryker anchors its portfolio through specialized expandable interbody devices for minimally invasive corridors. Globus Medical differentiates via in-house manufacturing of patient-specific implants and 3D-printed titanium constructs.
Spine devices encompass implantable hardware, surgical instruments, biologics, and imaging systems designed to stabilize, decompress, or fuse spinal segments, typically manufactured from titanium alloys, PEEK polymers, or demineralized bone matrices with precision tolerances of 50-100 microns for thread engagement safety. Their primary commercial purpose is restoring spinal alignment and neural decompression in patients with degenerative, traumatic, or deformity-related pathologies. Implants and biologics command the dominant margin pool due to recurring replacement cycles and biologics' premium pricing tied to osteoinductive claims. Minimally invasive surgery technology is expanding fastest as ambulatory surgical centers demand reduced tissue disruption and shorter anesthesia exposure.
FDA 510(k) premarket notification and EU MDR conformity assessment create divergent compliance burdens that favor established manufacturers with dedicated regulatory affairs infrastructure over emerging competitors. ISO 14155 clinical investigation standards and ASTM F2077 mechanical testing protocols further elevate barriers for novel implant geometries and biologic combinations. Stakeholders must monitor reimbursement shifts toward outpatient spine procedures and the evolving clinical evidence requirements for motion-preservation technologies versus fusion-based alternatives.
Market Dynamics
Robotic-assisted surgical platforms are compressing the learning curve for minimally invasive spine procedures while simultaneously concentrating procurement authority within integrated delivery networks.
Growth Catalysts
- EU MDR conformity pathways:The Medical Device Regulation is accelerating consolidation among manufacturers with established quality management systems, creating competitive moats for compliant suppliers across European hospital networks.
- Expandable interbody cage technology:Surgeons in ambulatory surgical centers are adopting these devices for reduced tissue disruption and faster patient mobilization, driving procedural migration from inpatient settings.
- Japan's super-aging demographic:Degenerative disc disease prevalence among patients over seventy-five is expanding the addressable patient pool for motion-preservation and fusion procedures in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Titanium alloy supply concentration:Aerospace and defense demand from Chinese and Russian state buyers is constraining spot availability of Ti-6Al-4V ELI for medical-grade implant production.
- FDA 510(k) predicate device limitations:Novel geometries and biologic combinations increasingly lack suitable predicates, extending premarket notification timelines and elevating regulatory consulting costs.
- PEEK polymer substitution pressure:3D-printed titanium lattice structures with comparable radiolucency and superior osseointegration are displacing traditional polymer interbody devices in premium segments.
Strategic Opportunities
- India's tier-two hospital expansion:Corporate hospital chains in Chennai, Hyderabad, and Pune are building dedicated spine surgery units with capital equipment leasing models that lower entry barriers for advanced navigation systems.
- Biologics reimbursement tailwind:Germany's Diagnosis-Related Group recalibration for osteobiologic adjuncts is creating favorable payment conditions for demineralized bone matrix and synthetic bone graft combinations.
- Tele-proctoring convergence with haptic feedback:Real-time remote surgical guidance integrated with force-sensing instruments is enabling expert surgeons to support complex procedures at geographically dispersed facilities.
Industry Challenges
- Robotic surgery technician scarcity:Hospital systems face twelve-to-eighteen-month recruitment cycles for professionals capable of calibrating navigation platforms and troubleshooting intraoperative software anomalies.
- EU MDR technical documentation burden:Legacy implant portfolios require extensive clinical evidence generation for recertification, straining regulatory affairs bandwidth at mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spine Devices Market |
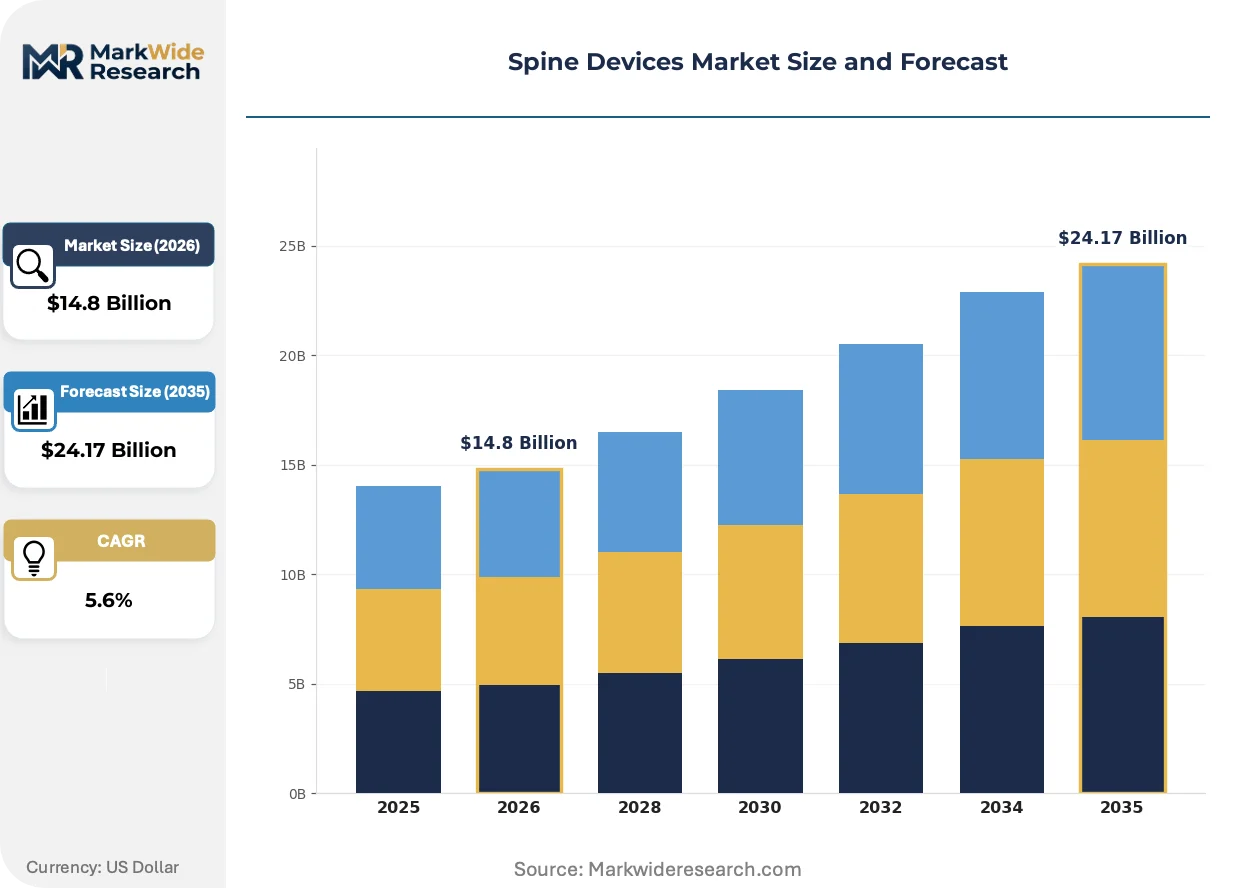
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Biologics, Imaging Devices Technology: Minimally Invasive Surgery, Robotic Surgery, Navigation Systems, Fusion Technology End User: Hospitals, Ambulatory Surgical Centers, Outpatient Facilities, Rehabilitation Centers Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson, Zimmer Biomet, Globus Medical, NuVasive, Alphatec Spine, Orthofix Holdings, RTI Surgical Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spine Devices Market Strategic Shifts
Digital surgical ecosystems are compressing the gap between preoperative planning and intraoperative execution, with artificial intelligence and augmented reality converging to reduce variability in screw placement accuracy.
Artificial intelligence-powered trajectory planning is automating the calculation of optimal pedicle screw paths based on patient-specific anatomy derived from preoperative CT datasets. Ambulatory surgical centers in Florida and Texas are adopting these systems to reduce fluoroscopy exposure and operating room time. The technology is automating the translation of radiographic data into robotic arm positioning commands, compressing the dependency on surgeon tactile feedback for corridor navigation.
EU MDR Article 117 requirements for implantable devices are mandating clinical investigation or equivalent evidence for novel biologic-device combinations. Manufacturers are restructuring product development pipelines to front-load clinical data collection, extending time-to-market for next-generation constructs. German notified bodies are experiencing backlog pressures that favor established players with dedicated regulatory affairs infrastructure over emerging competitors.
Hospital procurement committees are consolidating vendor relationships through single-source contracts for implant systems bundled with navigation capital equipment. Integrated delivery networks in California and New York are displacing traditional distributor-mediated purchasing with direct manufacturer agreements that include utilization training and outcome reporting. This concentration is most visible in academic medical centers where value-analysis committees now control eighty percent of implant selection authority.
Spine Devices Market Segmentation
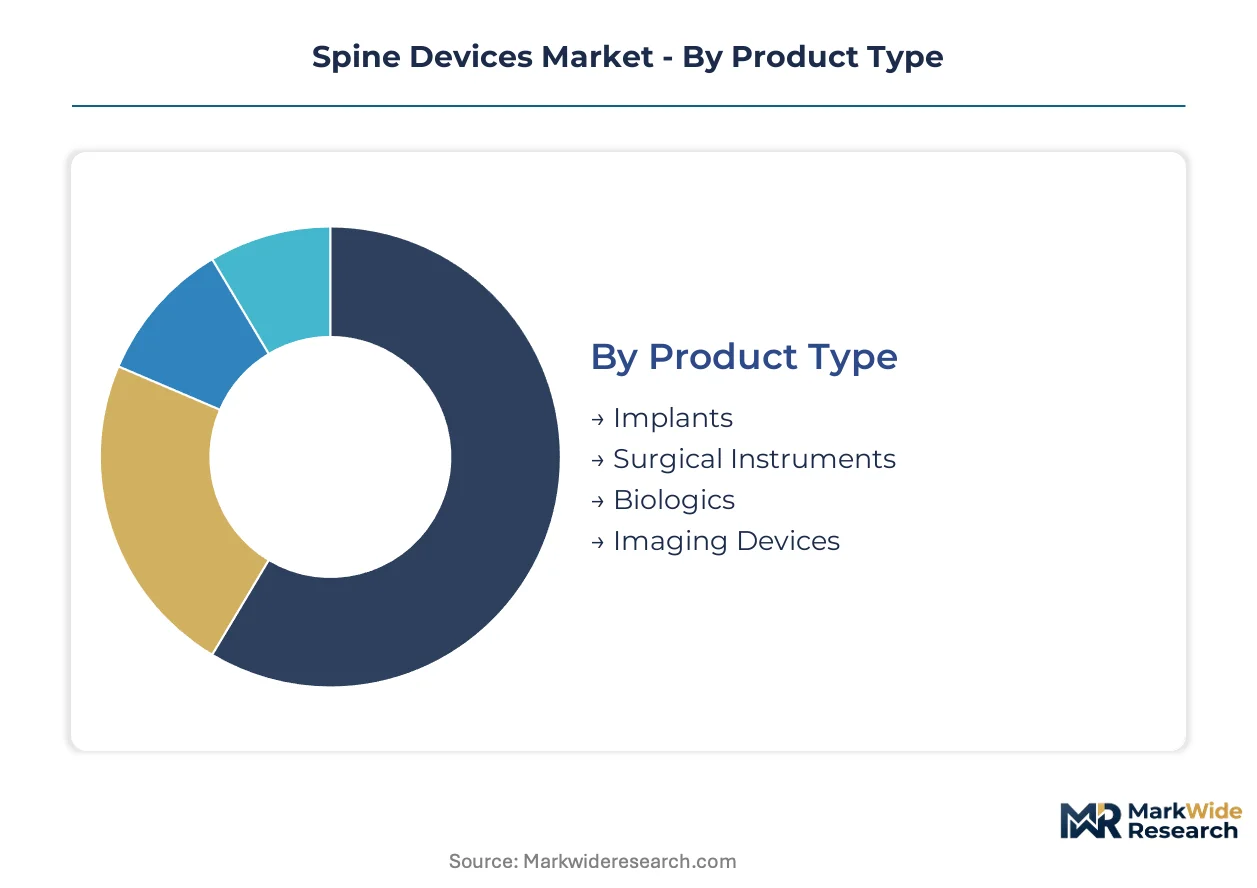
Spine device segmentation reveals how technology maturity, reimbursement pathways, and surgical site economics partition commercial opportunity. Manufacturers configure product portfolios across these axes to capture volume in high-throughput settings while defending premium positioning in complex deformity cases.
Product Type:
Titanium alloys, PEEK polymers, and demineralized bone matrices define the material specification axis across implantable hardware categories.
- Implants:Comprising pedicle screws, rods, plates, and interbody cages manufactured to 50-100 micron tolerances for thread engagement safety. Demand concentrates in United States academic medical centers where integrated delivery networks bundle implant procurement with navigation capital equipment.
- Surgical Instruments:Including retractors, drills, and insertion tools with modular designs for minimally invasive corridors. Ambulatory surgical centers in Texas and Florida are standardizing instrument sets to reduce sterilization cycle times and operating room turnover.
- Biologics:Demineralized bone matrices and synthetic bone graft substitutes with osteoinductive claims command premium pricing tied to fusion adjunct reimbursement.
- Imaging Devices:Intraoperative fluoroscopy and navigation cameras enabling real-time trajectory verification during screw placement.
Implants lead on scale; biologics lead on momentum.
Technology:
Procedure invasiveness and automation intensity separate adoption curves across surgical methodologies.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce tissue disruption and anesthesia exposure. Ambulatory surgical centers are migrating lumbar decompression and single-level fusion procedures to outpatient settings, compressing hospital inpatient volumes.
- Robotic Surgery:Arm-mounted platforms with haptic feedback and automated trajectory planning. United States hospital systems face twelve-to-eighteen-month recruitment cycles for calibration technicians, constraining deployment velocity despite capital equipment availability.
- Navigation Systems:Optical and electromagnetic tracking for instrument localization relative to preoperative CT datasets.
- Fusion Technology:Interbody cage designs and fixation constructs for spinal segment immobilization, including expandable configurations for reduced insertion profile.
Minimally invasive surgery leads on scale; robotic surgery leads on momentum.
End User:
Capital intensity and case complexity stratify procurement authority across care delivery settings.
- Hospitals:Academic medical centers and community hospitals performing complex deformity, trauma, and multilevel fusion procedures. Value-analysis committees in California and New York now control eighty percent of implant selection authority, displacing traditional surgeon-driven purchasing.
- Ambulatory Surgical Centers:Freestanding facilities in United States metropolitan clusters specializing in single-level decompression and interbody fusion. These centers demand reduced tissue disruption and shorter anesthesia exposure to enable same-day discharge.
- Outpatient Facilities:Hospital-based outpatient departments with intermediate case complexity and reimbursement positioning.
- Rehabilitation Centers:Post-acute facilities managing non-surgical spine care and recovery monitoring.
Hospitals lead on scale; ambulatory surgical centers lead on momentum.
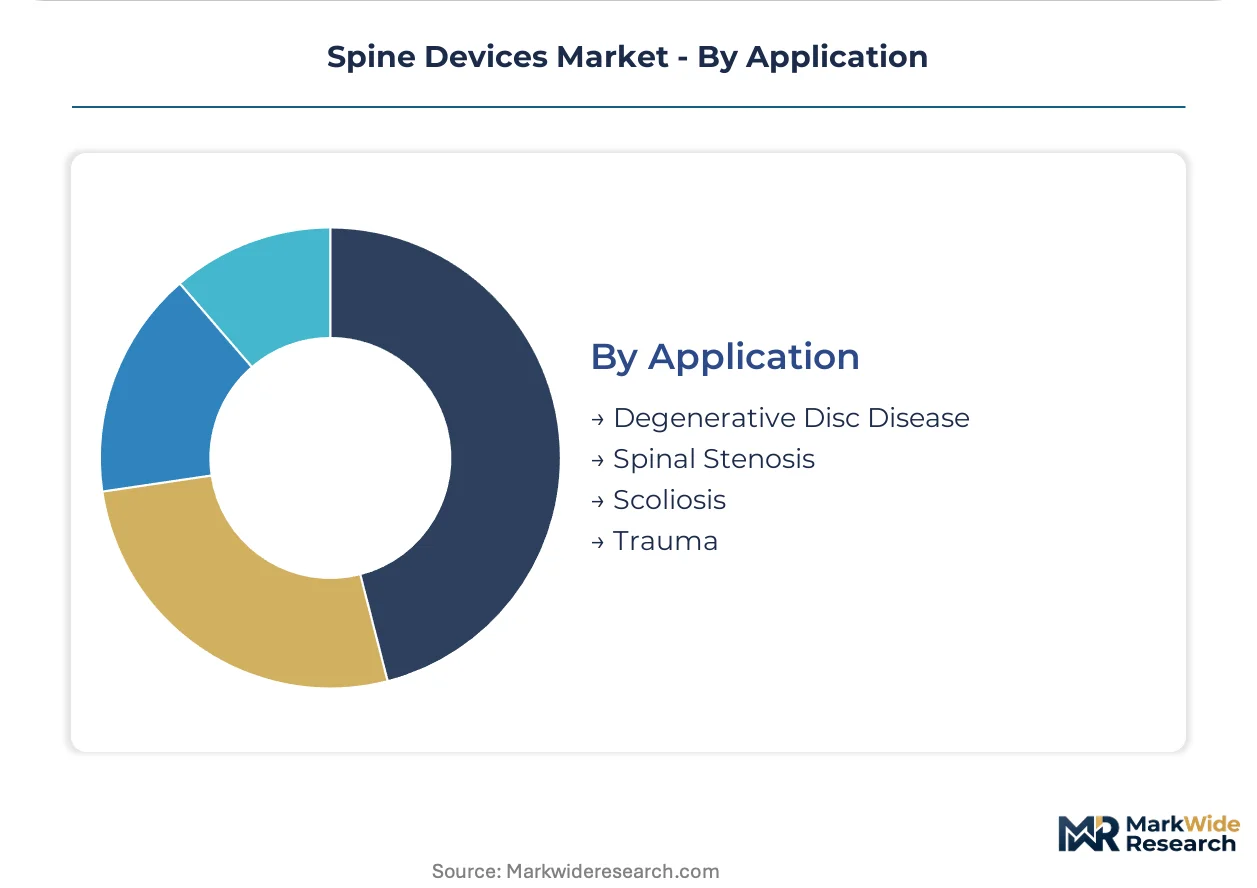
Application:
Pathology severity and patient age distribution shape procedure volume and technology selection.
- Degenerative Disc Disease:Disc space collapse and osteophyte formation in patients over fifty-five. Japan's super-aging demographic is expanding the addressable pool for motion-preservation and fusion procedures in Tokyo and Osaka metropolitan clusters.
- Spinal Stenosis:Central and foraminal canal narrowing requiring decompression with or without fusion. United States Medicare reimbursement shifts toward outpatient settings are accelerating minimally invasive corridor adoption for lumbar stenosis.
- Scoliosis:Coronal and sagittal plane deformities requiring multilevel instrumentation, typically addressed in hospital settings with robotic assistance for screw placement accuracy.
- Trauma:Fracture stabilization and spinal cord injury management with urgent surgical timelines and high implant density per case.
Degenerative disc disease leads on scale; spinal stenosis leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing spine device manufacturing capacity toward jurisdictions with streamlined quality management certification timelines. The EU MDR's clinical evidence requirements have extended recertification cycles for legacy portfolios, prompting some producers to diversify assembly operations across multiple regulatory zones.
United States
Medicare reimbursement shifts toward outpatient spine procedures are accelerating ambulatory surgical center expansion in Florida and Texas. FDA 510(k) predicate device limitations are extending premarket notification timelines for novel implant geometries. Academic medical centers in California and New York concentrate procurement authority through value-analysis committees controlling implant selection.
Germany
Diagnosis-Related Group recalibration for osteobiologic adjuncts is creating favorable payment conditions for demineralized bone matrix combinations. EU MDR Article 117 mandates clinical investigation for novel biologic-device combinations, extending development pipelines. Notified body backlogs in Berlin and Munich are favoring established manufacturers with dedicated regulatory affairs infrastructure.
Japan
Super-aging demographics are expanding the addressable patient pool for motion-preservation and fusion procedures among patients over seventy-five. PMDA consultation pathways for combination products are structuring premarket submission requirements for biologic-enhanced implants. Tokyo and Osaka metropolitan clusters concentrate specialized spine surgery units within corporate hospital chains.
India
Corporate hospital chains in Chennai, Hyderabad, and Pune are building dedicated spine surgery units with capital equipment leasing models. CDSCO medical device rules are harmonizing with IMDRF standards for quality management system certification. Tier-two hospital expansion is lowering entry barriers for advanced navigation systems through equipment financing arrangements.
China
NMPA innovative device approval pathways are accelerating market access for robotic-assisted surgical platforms with domestic clinical data. Centralized procurement reforms for high-value medical consumables are compressing implant pricing in provincial hospital networks. Yangtze River Delta manufacturing clusters are scaling titanium alloy processing capacity for medical-grade implant production.
Spine Devices Market Competitive Environment
United States producers anchor the premium-tier segment through integrated navigation platforms and robotic delivery systems; European specialists hold position via quality management infrastructure aligned with EU MDR conformity pathways. The vendor structure concentrates around diversified medical technology conglomerates with dedicated spine divisions and mid-sized specialists with focused implant portfolios. Two strategic archetypes dominate: full-spectrum platform vendors bundling capital equipment with consumable implants, and focused interbody specialists exploiting minimally invasive corridor adoption. Competitive dynamics center on M&A activity targeting robotic navigation capabilities and strategic partnerships with ambulatory surgical center networks.
Within the diversified conglomerate tier, Medtronic and Stryker occupy positions exemplifying platform-scale competitive posture. Medtronic represents the integrated navigation archetype through its hospital network penetration strategies. Stryker anchors the expandable interbody specialization vector with devices designed for minimally invasive corridors. Globus Medical sits within the patient-specific manufacturing archetype, differentiating via in-house production of 3D-printed titanium constructs.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| Alphatec Spine |
| Orthofix Holdings |
| RTI Surgical Holdings |
| Others |
Value Chain & Pricing Dynamics
Calibration technician shortages in the United States Midwest widen labor-cost spreads between premium robotic-assisted platforms and standard navigation systems. Three-tier pricing structure across premium, standard, and economy levels reflects these workforce differentials, with academic medical centers absorbing premium tiers while ambulatory surgical centers cluster in economy segments.
Pricing Analysis
Distributor margins on implant systems typically absorb fifteen to twenty-five percent of manufacturer list price before hospital procurement committees negotiate direct contracts. Price differentiation hinges on FDA 510(k) clearance tier and navigation capital equipment bundling, with integrated delivery networks commanding volume discounts unavailable to standalone facilities. Cost compression in economy-tier PEEK interbody devices intensifies as 3D-printed titanium alternatives capture premium positioning. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while academic medical centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta and India's Chennai-Pune corridor are reshaping titanium alloy sourcing for medical-grade implant production. Supply concentrates in China, Germany, and the United States for Ti-6Al-4V ELI feedstock, with aerospace demand constraining spot availability. Raw material dependencies include titanium sponge, PEEK polymer resin, and demineralized bone matrix from accredited tissue banks. Single-source vulnerability in German notified body certification creates regulatory chokepoints for European market access. Distribution runs through integrated delivery network direct contracts, displacing traditional distributor-mediated purchasing in California and New York hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spine devices market functions as a stable compounder anchored by irreversible demographic aging across developed economies. Degenerative disc disease prevalence expansion among patients over fifty-five sustains procedure volume growth independent of cyclical healthcare spending fluctuations.
For Market Incumbents: To counter robotic navigation technician scarcity constraining deployment velocity, anchor hospital network penetration through bundled capital equipment leasing with embedded training protocols. Deepen backward integration into titanium alloy processing to secure medical-grade feedstock allocation against aerospace competition. Prioritize EU MDR technical documentation investment to exploit notified body backlogs disadvantaging emerging competitors.
For New Entrants and Emerging Players: Enter via India's tier-two hospital expansion corridor, where corporate chains in Hyderabad and Pune accept equipment financing arrangements that lower navigation system entry barriers. Target spinal stenosis applications in United States ambulatory surgical centers, where Medicare reimbursement shifts accelerate minimally invasive corridor adoption. Pursue tele-proctoring partnerships with academic medical center surgeons to overcome geographic dispersion of expertise.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, targeting robotic navigation capabilities and patient-specific manufacturing infrastructure. Long-term viability rests on motion-preservation technology portfolios that address fusion-alternative demand from Japan's super-aging demographic. Watch for FDA 510(k) predicate exhaustion signals as indicators of regulatory moat widening favoring established clinical data repositories.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery networks in California consolidate eighty percent of implant selection authority through value-analysis committees. |
| CE Marking Pathway | EU MDR Article 117 mandates clinical investigation for biologic-device combinations, extending development pipelines for German notified bodies. |
| Software Companion Development | AI-powered trajectory planning automates pedicle screw path calculation from preoperative CT datasets, reducing fluoroscopy exposure. |
| Reimbursement Strategy | Germany's Diagnosis-Related Group recalibration for osteobiologic adjuncts creates favorable payment conditions for demineralized bone matrix. |
| FDA Submission | Predicate device limitations for novel geometries extend premarket notification timelines, elevating regulatory consulting costs for emerging entrants. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Segment-weighting approaches distributed value across product type, technology, end user, and application dimensions, with material specification and procedure invasiveness serving as cross-cutting stratifiers. CAGRs derived from logistic diffusion curves modeling robotic-assisted platform penetration and demographic procedure elasticity. Forecast inputs included Japan's super-aging demographic trajectories, United States ambulatory surgical center expansion rates, and EU MDR recertification cycle extensions.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-time robotic surgery utilization metrics introduce uncertainty bands around technology adoption velocity. Forecasts reflect assumptions regarding reimbursement stability and titanium alloy supply allocation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market