
 Non-Surgical Fat Reduction Market | 2026-2036
Non-Surgical Fat Reduction Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Surgical Fat Reduction Market Outlook
EU MDR is decoupling device certification from legacy CE marking timelines, forcing manufacturers to rebuild clinical evidence packages. Cutera leverages its direct sales infrastructure to sustain premium positioning across European capitals. BTL Industries anchors its growth on electromagnetic muscle stimulation paired with fat reduction protocols. AbbVie (Allergan Aesthetics) dominates the cryolipolysis segment through CoolSculpting brand recognition and physician training networks.
Non-surgical fat reduction encompasses energy-based modalities that induce adipocyte apoptosis or metabolic disruption without incision, typically operating at temperatures between -11°C and 43°C or electromagnetic frequencies of 1-30 MHz depending on mechanism. These systems serve commercial purposes by eliminating surgical risk, downtime, and anesthesia requirements while targeting localized adiposity resistant to diet and exercise. Cryolipolysis occupies the largest revenue pool given established reimbursement codes and consumer familiarity, though radiofrequency devices are capturing faster growth through combination therapies addressing skin laxity concurrent with fat reduction. Dermatology clinics command the highest margin per procedure among end-user channels, while home-use devices are expanding the addressable base despite lower per-unit economics.
FDA 510(k) pathways govern device clearance in the United States, requiring substantial equivalence demonstrations that shape R&D investment cycles and competitive entry timelines. EMA medical device regulations in Europe impose post-market surveillance obligations that elevate quality management costs for manufacturers serving both jurisdictions. Stakeholders must monitor how FDA guidance on fat reduction claims evolves relative to wellness versus medical device classification boundaries.
Market Dynamics
FDA 510(k) clearance compression is accelerating competitive entry timelines while EU MDR recertification burdens force parallel clinical investment strategies. Device manufacturers now face divergent evidence requirements across their two largest revenue jurisdictions.
Growth Catalysts
- Electromagnetic muscle stimulation pairing:Combination protocols that address both adipose tissue and muscular definition expand addressable patient pools beyond traditional body contouring candidates.
- US medical spa density:The proliferation of physician-supervised aesthetic clinics in metropolitan corridors creates localized demand concentration with minimal capital barriers for device placement.
- Radiofrequency skin laxity integration:Dual-action devices that simultaneously treat fat reduction and tissue tightening command premium positioning in dermatology clinic service menus.
Market Restraints
- EU MDR clinical evidence rebuilding:Legacy CE-marked devices face mandatory recertification with expanded post-market surveillance obligations that compress margin structures for European market participants.
- CoolSculpting brand concentration:Cryolipolysis segment dominance by a single recognized protocol creates patient preference lock-in that elevates customer acquisition costs for competing modalities.
- Home-use device substitution:Lower-cost consumer-grade radiofrequency and cryolipolysis systems capture price-sensitive segments that would otherwise seek professional treatment protocols.
Strategic Opportunities
- Indian aesthetic clinic expansion:Metro hospital chains in Mumbai and Delhi are establishing dedicated cosmetic dermatology wings with imported energy-based device portfolios.
- Male patient segment development:Abdominal contouring and submental fat protocols tailored to male adipose distribution patterns remain underpenetrated relative to female-targeted marketing.
- Post-bariatric body contouring:Massive weight loss patients present concentrated demand for skin tightening adjuncts to residual fat reduction across multiple anatomic zones.
Industry Challenges
- Biomedical engineering talent scarcity:Device manufacturers compete for specialists capable of integrating thermal modeling with tissue interaction physics for next-generation system development.
- FDA wellness claim boundary enforcement:Classification disputes between medical device and wellness product categories create regulatory uncertainty for novel mechanism introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Surgical Fat Reduction Market |
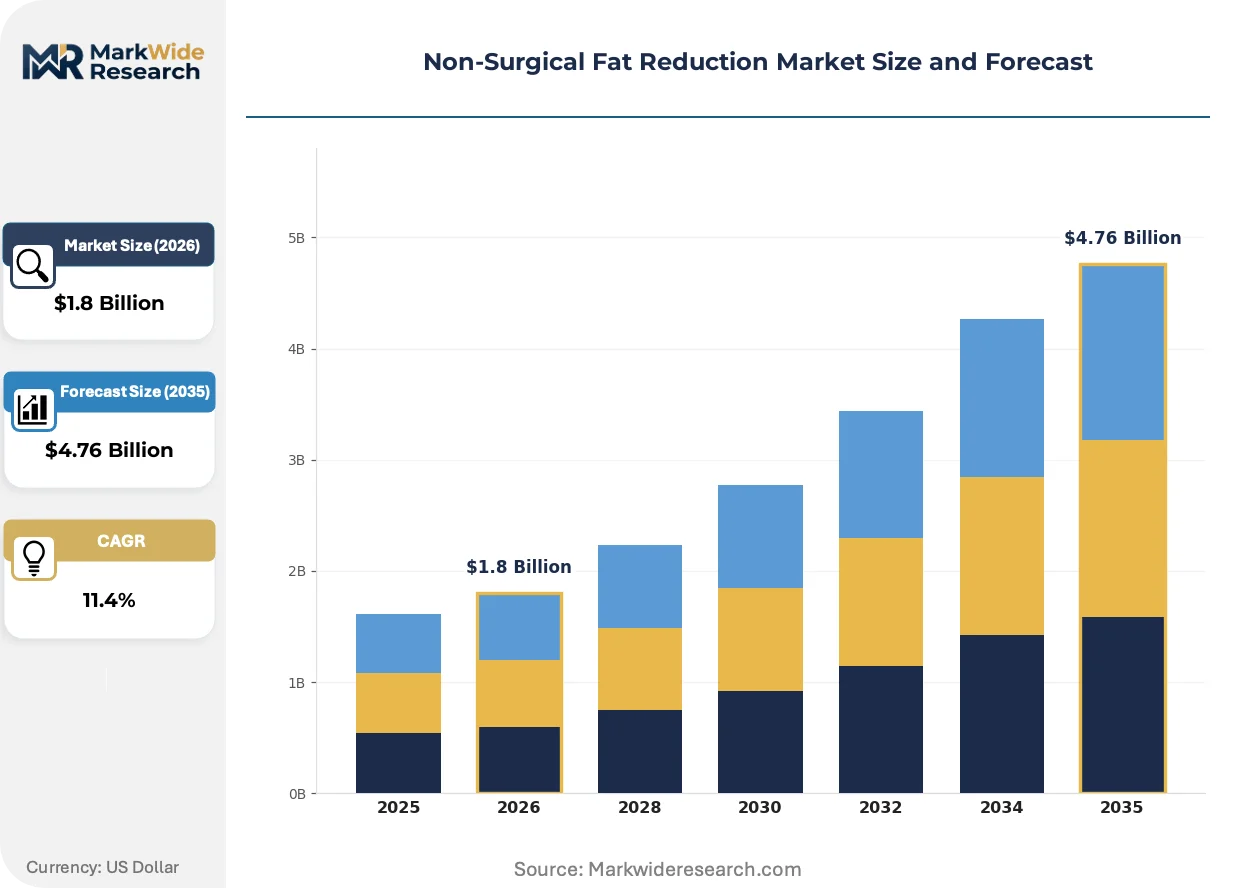
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryolipolysis, Ultrasound, Radiofrequency, Laser Therapy End User: Dermatology Clinics, Medical Spa, Fitness Centers, Home Users Technology: Cooling Technology, Vibration Technology, Pulsed Electromagnetic Field, Energy-Based Devices Application: Abdomen, Thighs, Arms, Back |
| Companies Covered | Cutera, BTL Industries, AbbVie (Allergan Aesthetics), Venus Concept, Lumenis, Cynosure, Alma Lasers, Bausch Health (Solta Medical), Candela Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Surgical Fat Reduction Market Strategic Shifts
Energy-based modalities are converging with real-time tissue monitoring systems that enable personalized treatment parameter adjustment. This integration is compressing the gap between standardized protocols and individualized outcomes.
High-intensity focused electromagnetic technology is consolidating market share in the muscle-sculpting adjacent segment. Med-spa chains in Texas and Florida are adopting these systems at replacement-cycle velocity. The technology is consolidating what were previously separate fat reduction and muscle toning revenue streams into single-procedure economics.
EU MDR post-market clinical follow-up requirements are extending surveillance obligations for cryolipolysis and radiofrequency devices already in commercial distribution. Manufacturers must now fund multi-year safety registries that were not mandated under legacy CE frameworks. German notified bodies are processing these submissions with twelve-to-eighteen-month queues that delay competitive repositioning.
Patients are compressing their decision cycles through social media before-and-after validation rather than physician consultation. Instagram and TikTok content from US-based dermatology influencers now drives appointment booking at rates that rival traditional referral channels. This shift is most pronounced in the Los Angeles and Miami metropolitan corridors where clinic marketing budgets have pivoted toward content creator partnerships.
Non-Surgical Fat Reduction Market Segmentation
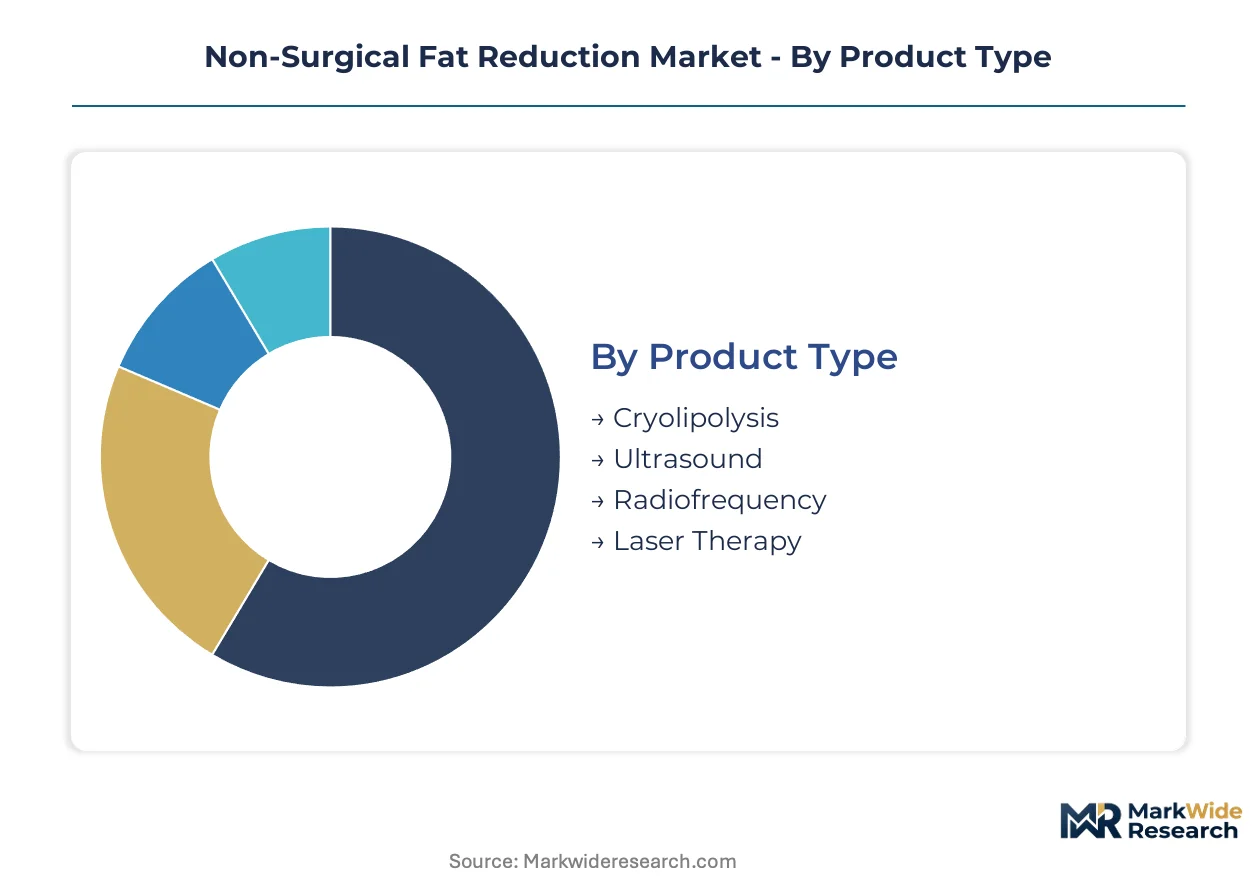
Segmentation in non-surgical fat reduction reveals how technology selection, treatment setting, and anatomical targeting shape procurement decisions across patient populations. Device manufacturers configure product portfolios around these axes to capture differential margin pools.
Product Type:
Technology specifications determine thermal range, treatment duration, and tissue interaction physics across commercial systems.
- Cryolipolysis:Controlled cooling induces adipocyte apoptosis at temperatures reaching -11°C, with established FDA clearance pathways supporting physician adoption in US dermatology networks. Demand concentrates in physician-supervised clinics where anesthesia-free protocols and minimal downtime attract patients resistant to surgical liposuction.
- Radiofrequency:Electromagnetic energy at 1-30 MHz generates thermal disruption of adipose tissue while simultaneously stimulating collagen remodeling for skin tightening. Metropolitan medical spas in Los Angeles and Miami are driving fastest adoption through combination therapy positioning that commands premium pricing over single-modality alternatives.
- Ultrasound:Focused acoustic energy mechanically disrupts fat cell membranes without thermal damage to surrounding tissue. European aesthetic clinics favor this mechanism where EU MDR surveillance requirements favor devices with extensive post-market safety data.
- Laser Therapy:Low-level laser emissions target adipocyte membrane permeability to trigger lipolysis. Home-use device manufacturers dominate this segment with lower-power systems designed for consumer self-administration.
Cryolipolysis leads on scale; radiofrequency leads on momentum.
End User:
Channel economics vary sharply across treatment settings, with capital intensity and regulatory burden shaping competitive entry.
- Dermatology Clinics:Board-certified practices command highest per-procedure margins through physician consultation requirements and medical-grade device procurement. German and Swiss clinics anchor European demand concentration for combination therapy protocols.
- Medical Spa:Physician-supervised aesthetic facilities in Texas and Florida are expanding device fleets at replacement-cycle velocity, with minimal anesthesia regulations accelerating capital deployment compared to hospital outpatient settings.
- Fitness Centers:Wellness-integrated locations in Mumbai and Delhi are piloting post-workout body contouring as membership retention tools, though per-session economics trail medical channels.
- Home Users:Consumer-grade cryolipolysis and radiofrequency devices capture price-sensitive segments through direct-to-consumer distribution, compressing addressable volume for professional treatment protocols.
Medical spa channels are expanding most quickly; dermatology clinics retain margin leadership.
Technology:
Underlying energy delivery mechanisms determine device classification, regulatory pathway, and clinical training requirements.
- Cooling Technology:Precision temperature control systems maintain adipocyte-targeting thermal profiles without epidermal injury. FDA 510(k) substantial equivalence demonstrations dominate clearance strategies for US market entry.
- Energy-Based Devices:Integrated platforms combining multiple thermal or electromagnetic modalities enable single-session treatment of concurrent adiposity and skin laxity. Japanese METI certification requirements shape development timelines for Asia-Pacific expansion.
- Pulsed Electromagnetic Field:Time-varying magnetic fields stimulate muscle contraction while inducing metabolic stress in surrounding adipose tissue. BTL Industries has anchored commercial traction through electromagnetic muscle stimulation pairing protocols.
- Vibration Technology:Mechanical oscillation disrupts adipocyte structural integrity through cavitation effects, with lower capital costs supporting penetration in emerging market aesthetic clinics.
Cooling technology leads on installed base; energy-based devices lead on R&D investment.
Application:
Anatomical targeting determines handpiece design, treatment protocol duration, and patient candidacy screening.
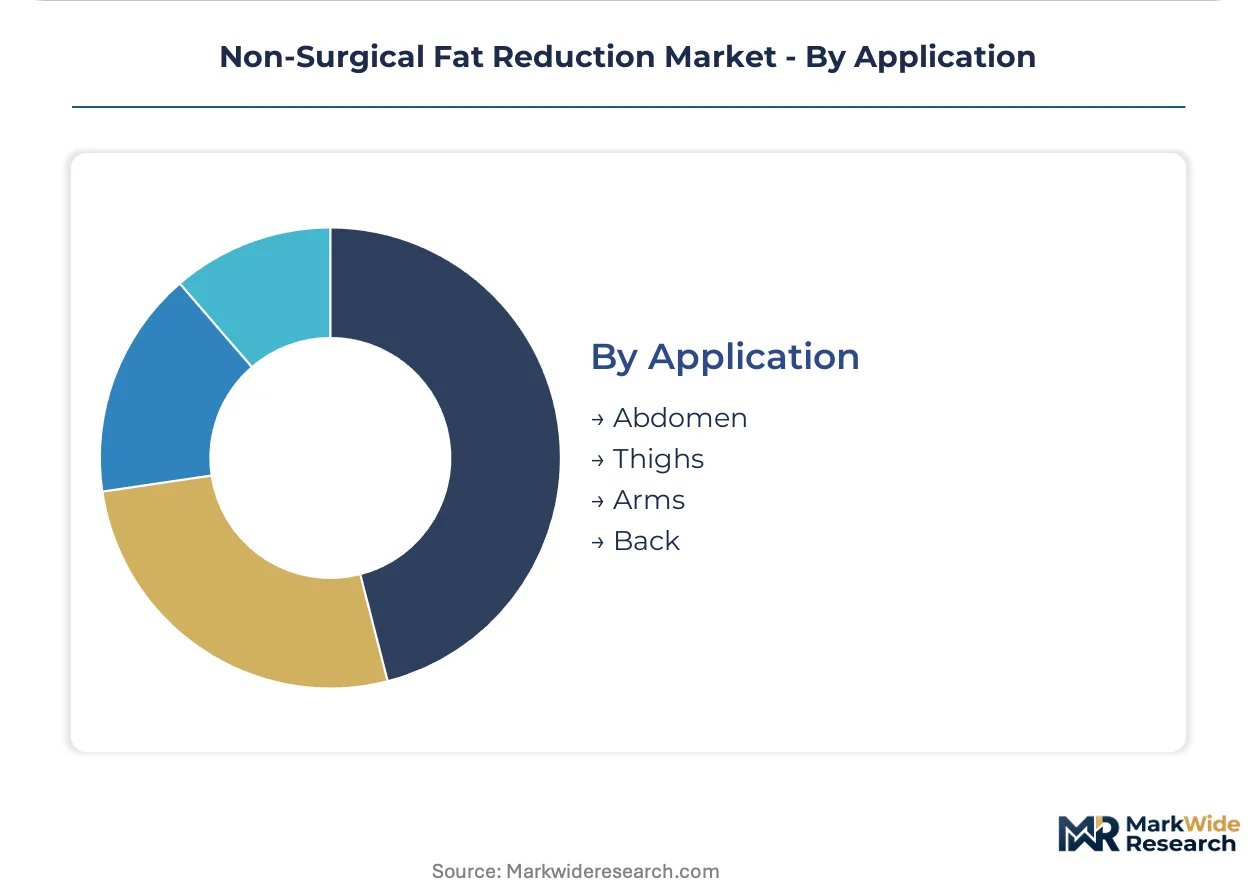
- Abdomen:Largest treatment volume reflects visceral fat accumulation patterns and visible outcome metrics that drive social media validation. Male patient segments show concentrated demand for abdominal contouring protocols.
- Thighs:Inner and outer thigh applications require specialized applicator geometry to accommodate tissue curvature. Post-bariatric patients present concentrated demand for skin tightening adjuncts in this zone.
- Arms:Upper arm adiposity protocols target demographic segments with age-related skin laxity concerns, favoring radiofrequency combination therapies.
- Back:Bra line and flank applications serve patient populations with localized adiposity resistant to exercise intervention, with treatment protocols adapted for prone positioning requirements.
Abdomen leads on procedure volume; thighs lead on expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified dermatologists and aesthetic medicine specialists cluster in metropolitan corridors across five countries that anchor device procurement and protocol adoption. These concentrations shape where manufacturers prioritize direct sales infrastructure and clinical training investments.
United States
Physician-supervised medical spas in Texas and Florida are expanding device fleets at replacement-cycle velocity, with minimal anesthesia regulations accelerating capital deployment. FDA 510(k) clearance pathways govern market entry, requiring substantial equivalence demonstrations that compress R&D investment cycles. Los Angeles and Miami metropolitan corridors concentrate demand where clinic marketing budgets have pivoted toward content creator partnerships.
Germany
Notified bodies are processing EU MDR recertification submissions with twelve-to-eighteen-month queues that delay competitive repositioning for legacy devices. German aesthetic clinics anchor European demand concentration for combination therapy protocols addressing concurrent adiposity and skin laxity. The Rhine-Ruhr and Munich metropolitan regions host the densest concentration of board-certified dermatology practices with medical-grade device procurement authority.
India
Metro hospital chains in Mumbai and Delhi are establishing dedicated cosmetic dermatology wings with imported energy-based device portfolios. CDSCO medical device regulations impose import licensing requirements that shape distribution partnerships for foreign manufacturers. The Delhi-NCR corridor concentrates affluent patient populations driving demand for non-surgical body contouring protocols.
Japan
METI certification requirements shape development timelines for Asia-Pacific expansion of combination therapy platforms. Japanese aesthetic clinics favor devices with extensive post-market safety data, aligning with conservative clinical adoption patterns. The Tokyo metropolitan area concentrates the nation's highest medical spa density and disposable aesthetic spending.
Brazil
ANVISA medical device regulations govern clearance pathways for energy-based fat reduction systems entering Latin America's largest aesthetic market. São Paulo anchors national demand concentration with specialized dermatology clinics adopting cryolipolysis and radiofrequency protocols. Brazilian patients compress decision cycles through social media validation, mirroring patterns observed in US metropolitan corridors.
Non-Surgical Fat Reduction Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a market structure that exhibits moderate consolidation around established cryolipolysis and radiofrequency platforms. The vendor base separates into three strategic archetypes: diversified medical device conglomerates with aesthetic divisions, pure-play energy-based device specialists, and emerging electromagnetic muscle stimulation entrants. Competitive dynamics center on M&A activity to acquire novel modality portfolios and strategic partnerships to accelerate geographic expansion into regulated Asian markets.
Among diversified conglomerates with aesthetic medicine divisions, AbbVie (Allergan Aesthetics) and Bausch Health (Solta Medical) occupy positions exemplifying scale-driven portfolio breadth across multiple energy-based modalities. Cutera represents the focused specialist archetype with direct sales infrastructure sustaining premium positioning across European capitals. BTL Industries anchors the electromagnetic muscle stimulation segment, demonstrating how pairing protocols can consolidate previously separate fat reduction and muscle toning revenue streams.
| Leading Market Players |
|---|
| Cutera |
| BTL Industries |
| AbbVie (Allergan Aesthetics) |
| Venus Concept |
| Lumenis |
| Cynosure |
| Alma Lasers |
| Bausch Health (Solta Medical) |
| Candela Corporation |
| Others |
Value Chain & Pricing Dynamics
Medical-grade FDA 510(k) clearance versus consumer wellness classification creates a stark bifurcation between professional clinic systems and direct-to-consumer devices, with this tier divergence manifesting in both pricing power and supply chain sourcing strategies across German notified bodies and US distribution networks.
Pricing Analysis
Bundled service protocols combining cryolipolysis with radiofrequency skin tightening command per-session premiums that unbundled single-modality treatments cannot match. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised dermatology clinics from medical spas and home-use channels. Cost compression in the consumer segment is intensifying because electromagnetic muscle stimulation entrants are flooding direct-to-consumer marketing channels. Home users exhibit highest price sensitivity, while board-certified dermatology practices demonstrate lowest elasticity due to outcome liability and reputation risk.
Supply Chain Analysis
Certification gating through FDA 510(k) substantial equivalence and EU MDR notified body queues concentrates component sourcing among established US, German, and Japanese precision manufacturers. Device assembly draws from specialized thermal control systems, electromagnetic coil arrays, and real-time tissue monitoring sensors. Single-source vulnerability persists where Japanese METI-certified subsystems anchor Asia-Pacific variant production. Distribution runs through direct sales forces for premium clinic systems and e-commerce platforms for consumer-grade alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification deadlines function as a regulatory compounder, accelerating consolidation among legacy CE-marked device holders while compressing margins for European market participants who must rebuild clinical evidence packages.
For Market Incumbents: Cement cryolipolysis segment leadership through exclusive physician training network expansion before electromagnetic muscle stimulation protocols capture abdominal contouring volume. Deepen backward integration into thermal control component manufacturing to offset supply chain bottlenecks at Japanese precision suppliers. Prioritize FDA 510(k) pathway expertise as a defensive moat against wellness-classification entrants. For New Entrants and Emerging Players: The premium-to-economy price-point gap in male-targeted abdominal contouring protocols offers white-space entry with lower customer acquisition costs than female-saturated thigh and arm segments. Target post-bariatric patient populations in US metropolitan medical spas where skin tightening adjuncts remain underserved. Pursue electromagnetic muscle stimulation pairing as the go-to-market angle to consolidate dual revenue streams. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR recertification burdens exceed smaller manufacturers' quality management system capacities. Long-term viability favors platforms with multi-modality energy delivery and software-enabled treatment personalization. Target acquisition archetypes include electromagnetic muscle stimulation specialists with METI certification progress and Indian distribution partnerships. Watch FDA guidance on wellness versus medical device classification boundaries as the signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Shortens competitive entry timelines for novel cryolipolysis applicator geometries targeting submental fat zones. |
| EU MDR Recertification Investment | Preserves German and Swiss clinic market access for legacy radiofrequency platforms facing twelve-to-eighteen-month notified body queues. |
| Electromagnetic Muscle Stimulation Pairing | Consolidates separate fat reduction and muscle toning revenue streams into single-procedure economics for Texas medical spa chains. |
| Indian Distribution Partnership | Navigates CDSCO import licensing requirements for Mumbai and Delhi metro hospital chain cosmetic dermatology wing procurement. |
| Physician Training Network Expansion | Builds preference lock-in through CoolSculpting-style protocol certification that elevates rival customer acquisition costs. |
Study Parameters
Direct dialogue with biomedical engineers, dermatology clinic procurement managers, medical spa chain operators, and FDA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, CDSCO import licensing registries, and METI certification filings. Bottom-up procedure volume estimates triangulated against top-down device shipment data from German and Japanese precision component suppliers.
Bottom-up modeling of procedure volumes by anatomical target and end-user channel converged with top-down manufacturer revenue segmentation across the projection horizon. Segmentation dimensions included technology mechanism, treatment setting capital intensity, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle velocity in US metropolitan medical spa corridors. Forecast inputs incorporated EU MDR recertification timeline delays and social media-driven patient decision cycle compression.
Caveats apply where FDA wellness claim boundary enforcement or EU MDR notified body processing backlogs could materially shift the outlook for novel modality commercialization timelines. Forecasts reflect assumptions regarding physician adoption curves and electromagnetic muscle stimulation training protocol penetration. A model refresh is warranted upon material change in FDA classification guidance or German notified body queue duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market