
 Middle East and Africa Knee Cartilage Repair Market | 2026-2036
Middle East and Africa Knee Cartilage Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Knee Cartilage Repair Market Foresight
Implantable biologic revenue is reconfiguring competitive returns across the Middle East and Africa Knee Cartilage Repair Market. Zimmer Biomet Holdings, Inc. leverages its established distribution network across Gulf state hospital systems to sustain premium positioning. Smith & Nephew plc anchors its regional presence through specialized sports medicine portfolios that dominate arthroscopic procedure suites in South African private facilities.
Middle East and Africa knee cartilage repair encompasses surgical and cell-based interventions that restore articular hyaline cartilage through autologous chondrocyte implantation, microfracture, or osteochondral grafting procedures requiring subchondral bone penetration depths of 2-4 millimeters and controlled defect preparation. These interventions primarily restore weight-bearing joint function in active patients under sixty-five years of age. Autologous chondrocyte implantation commands the highest margin pool among product types due to cell culture complexity and limited regional laboratory capacity. Arthroscopic delivery mode leads procedural volume across orthopedic clinics and hospitals, though minimally invasive approaches are gaining fastest in rehabilitation centers seeking reduced recovery protocols.
SFDA in Saudi Arabia and MOHAP in the UAE enforce medical device and biologic standards that shape product registration timelines and clinical evidence requirements for cartilage repair therapies entering these markets. South Africa's SAHPRA applies ICH-GCP aligned clinical trial standards that extend approval pathways for novel stem cell and 3D bioprinting technologies. Stakeholders must monitor evolving national health insurance reimbursement decisions across Gulf states, as coverage determinations for cell-based therapies will reshape patient access and manufacturer commercialization priorities.
Market Dynamics
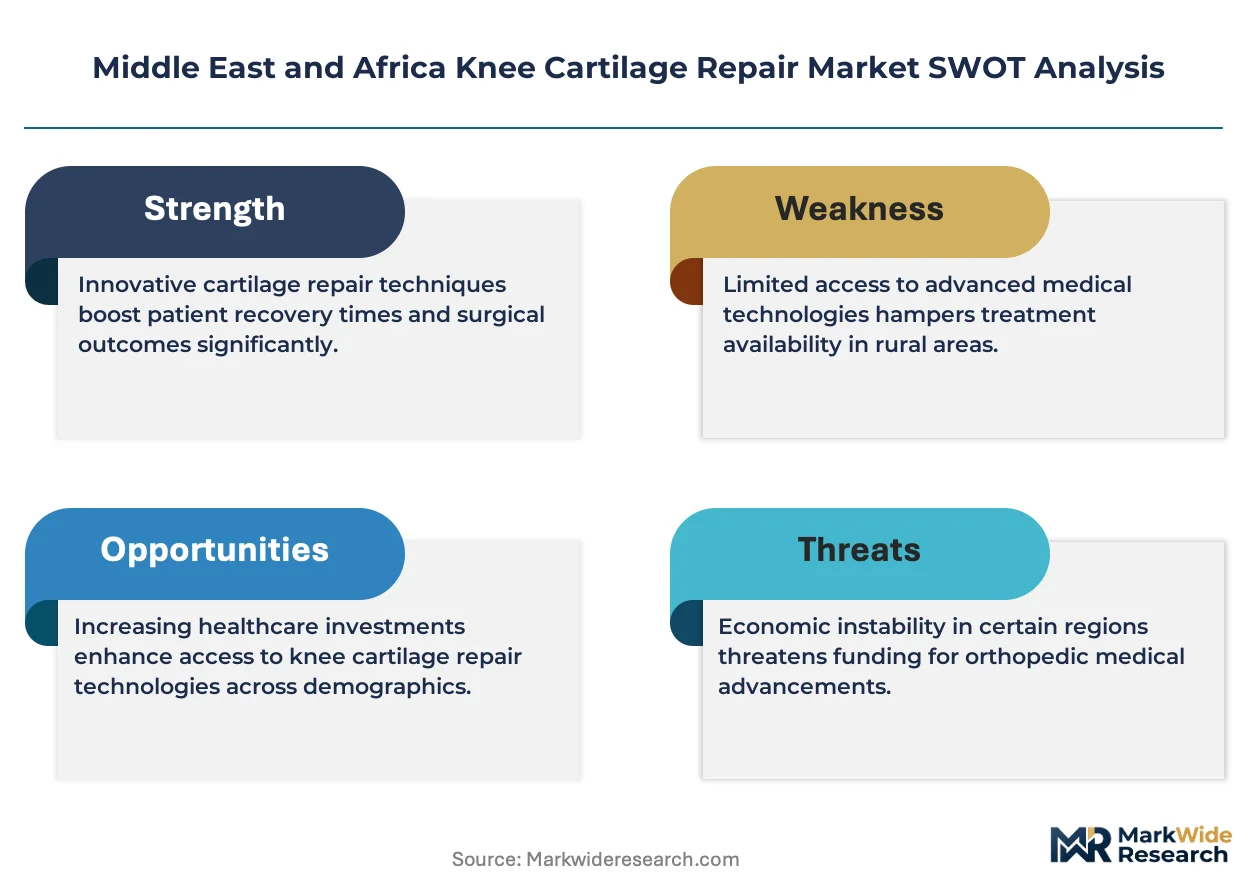
SAHPRA's tightened biologic registration requirements and the Gulf states' medical tourism infrastructure buildout are creating divergent competitive arenas across the Middle East and Africa Knee Cartilage Repair Market. Manufacturers must navigate fundamentally different approval timelines and reimbursement landscapes between South Africa's ICH-GCP aligned framework and the Gulf Cooperation Council's SFDA and MOHAP standards.
Growth Catalysts
- SFDA and MOHAP medical tourism infrastructure:The UAE and Saudi Arabia have invested in hospital systems that attract regional patients seeking advanced cartilage repair procedures, expanding addressable patient pools beyond domestic populations.
- Arthroscopic delivery mode expansion:Sports medicine clinics across South Africa are adopting minimally invasive surgical protocols that reduce recovery times and enable outpatient procedure economics.
- Autologous chondrocyte implantation capacity:Limited regional laboratory infrastructure for cell culture creates scarcity premiums that attract investment in specialized biologic manufacturing facilities.
Market Restraints
- Cell culture input cost volatility:Fetal bovine serum and specialized growth media prices fluctuate with global supply chain disruptions, compressing margins on high-complexity biologic therapies.
- Laboratory capacity concentration:Cell processing facilities cluster in Johannesburg, Cape Town, and select Gulf state capitals, creating geographic access barriers for patients in secondary cities.
- Microfracture substitution threat:Simpler bone marrow stimulation techniques retain preference among cost-constrained public health systems despite inferior long-term outcomes.
Strategic Opportunities
- Egypt and North African expansion:Underpenetrated markets with growing private healthcare investment present first-mover advantages for establishing distribution partnerships.
- 3D bioprinting convergence with stem cell platforms:Integration of scaffold technologies with autologous cell sources enables next-generation osteochondral constructs for large defect applications.
- Rehabilitation center channel development:Post-acute facilities are emerging as procedure sites for minimally invasive approaches, bypassing traditional hospital procurement.
Industry Challenges
- Cell processing technician scarcity:Qualified laboratory personnel for GMP-compliant chondrocyte expansion remain concentrated in a handful of regional training centers.
- Multi-jurisdiction registration complexity:Divergent evidence requirements between SAHPRA, SFDA, and MOHAP extend commercialization timelines and inflate regulatory affairs overhead.
- Legacy hospital integration friction:New biologic delivery systems require reconfiguration of established arthroscopic instrument workflows and surgeon training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Knee Cartilage Repair Market |
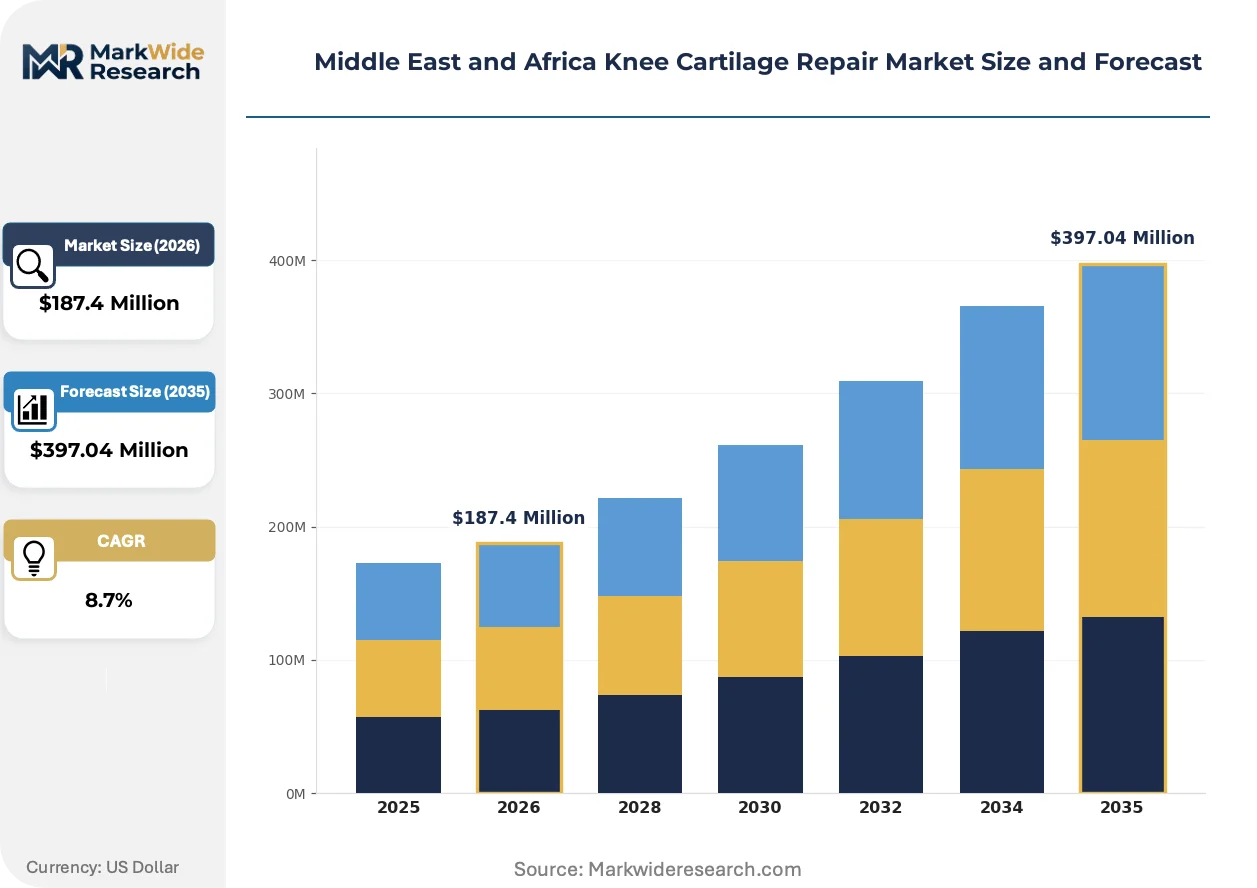
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Chondrocyte Implantation, Microfracture, Osteochondral Graft, Allograft, Synthetic Scaffolds Delivery Mode: Arthroscopic, Open Surgery, Minimally Invasive, Injections End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Sports Medicine Clinics Technology: Stem Cell Therapy, Matrix-Induced Chondrogenesis, Platelet-Rich Plasma, 3D Bioprinting |
| Companies Covered | Zimmer Biomet Holdings, Inc., Arthrex, Inc., Smith & Nephew plc, Stryker Corporation, Johnson & Johnson, DePuy Synthes, Medacta Group SA, B. Braun Melsungen, Vericel Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Knee Cartilage Repair Market Shifts & Advancements
Cell-based manufacturing advances and regulatory pathway differentiation are compressing traditional competitive moats across the Middle East and Africa Knee Cartilage Repair Market. Stakeholders must recalibrate around biologic production capabilities and jurisdiction-specific approval strategies.
Matrix-assisted autologous chondrocyte implantation is collapsing the historical gap between first-generation cell therapies and osteochondral allografts. South African private hospital groups are adopting these scaffold-enhanced platforms at accelerated rates. The technology is collapsing price premiums previously commanded by imported allograft products while improving surgical reproducibility.
SAHPRA's alignment with ICH-GCP standards is extending clinical trial timelines for novel stem cell interventions entering South Africa. Manufacturers face protracted evidence generation requirements that delay market entry relative to Gulf state pathways. Cell-based therapy developers are responding by sequencing regulatory submissions to prioritize SFDA and MOHAP approvals before engaging SAHPRA.
Medical tourism procurement models are fragmenting traditional hospital purchasing concentration in the UAE and Saudi Arabia. International patient coordinators now influence device selection through direct relationships with Gulf state specialty clinics. This channel disintermediation is most visible in Dubai's healthcare free zones where direct-to-facility distribution bypasses centralized hospital group contracts.
Middle East and Africa Knee Cartilage Repair Market Segmentation
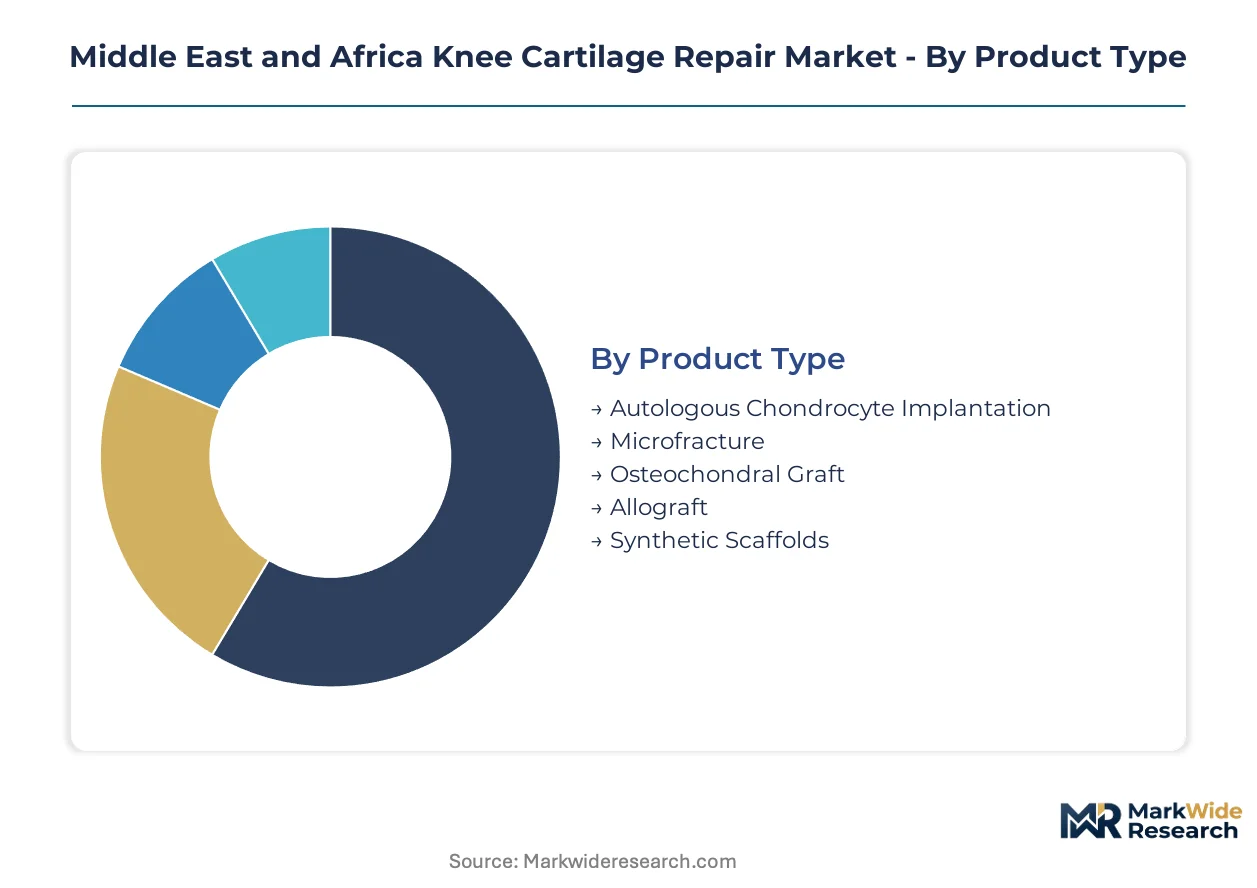
Segmentation in knee cartilage repair reveals how technology sophistication, procedural invasiveness, and care setting economics partition patient access across Middle East and Africa healthcare systems. Each dimension exposes distinct competitive arenas where regulatory requirements, reimbursement structures, and clinical training availability determine commercial viability.
Product Type:
Use cases span from simple bone marrow stimulation to multi-stage cell culture procedures requiring laboratory infrastructure investment.
- Autologous Chondrocyte Implantation:Two-stage procedure harvests patient chondrocytes for ex-vivo expansion before surgical implantation into prepared cartilage defects. Demand concentrates in Gulf state private hospitals serving medical tourism patients seeking definitive long-term outcomes, constrained by limited regional GMP cell processing capacity.
- Microfracture:Single-stage bone marrow stimulation technique creates subchondral perforations to release mesenchymal stem cells into cartilage defects. Volume dominance persists in South African public health systems and cost-sensitive North African markets where simpler instrumentation and shorter procedure times align with budget constraints.
- Osteochondral Graft:Transplantation of cylindrical bone-cartilage plugs from donor sites or allogeneic sources.
- Allograft:Cadaveric osteochondral tissue requiring specialized cold chain logistics and tissue banking infrastructure.
- Synthetic Scaffolds:Biodegradable polymer matrices supporting in-growth of native repair tissue.
Established volume favors Microfracture; emerging adoption favors Autologous Chondrocyte Implantation.
Delivery Mode:
Procedural approach selection tracks facility capital equipment availability and surgeon subspecialty training distribution.
- Arthroscopic:Endoscopic visualization through small portal incisions enables outpatient procedure economics and accelerated rehabilitation protocols. Sports medicine clinics across Johannesburg and Cape Town are equipping dedicated arthroscopy suites to capture shifting patient preference for reduced recovery timelines.
- Minimally Invasive:Mini-open approaches balance visualization with tissue preservation. Rehabilitation centers in UAE medical tourism corridors are adopting these hybrid techniques to differentiate post-acute care offerings and bypass traditional hospital procurement channels.
- Open Surgery:Full arthrotomy for complex multi-compartment defects requiring direct visualization.
- Injections:Intra-articular biologic delivery without surgical intervention, primarily for early-stage degeneration.
Arthroscopic procedures command current volume leadership; Minimally Invasive approaches are climbing the fastest as rehabilitation centers expand procedural scope.
End User:
Site-of-care dynamics fragment purchasing authority and influence technology selection through divergent reimbursement and capital allocation priorities.
- Hospitals:Acute care facilities with comprehensive orthopedic departments and inpatient rehabilitation capabilities. Gulf state hospital groups in Dubai and Riyadh anchor regional demand for cell-based therapies through medical tourism package pricing.
- Sports Medicine Clinics:Specialized outpatient facilities focused on athletic injury management. South African private clinic networks in Pretoria and Durban are expanding arthroscopic capacity to capture rugby and cricket athlete populations.
- Orthopedic Clinics:General musculoskeletal practices performing diagnostic and therapeutic procedures.
- Rehabilitation Centers:Post-acute facilities increasingly offering minimally invasive interventions.
Hospitals retain revenue concentration; Sports Medicine Clinics are gaining share fastest through targeted athlete populations and direct-pay models.
Technology:
Biologic sophistication tiers separate established clinical protocols from experimental platforms awaiting regulatory validation.
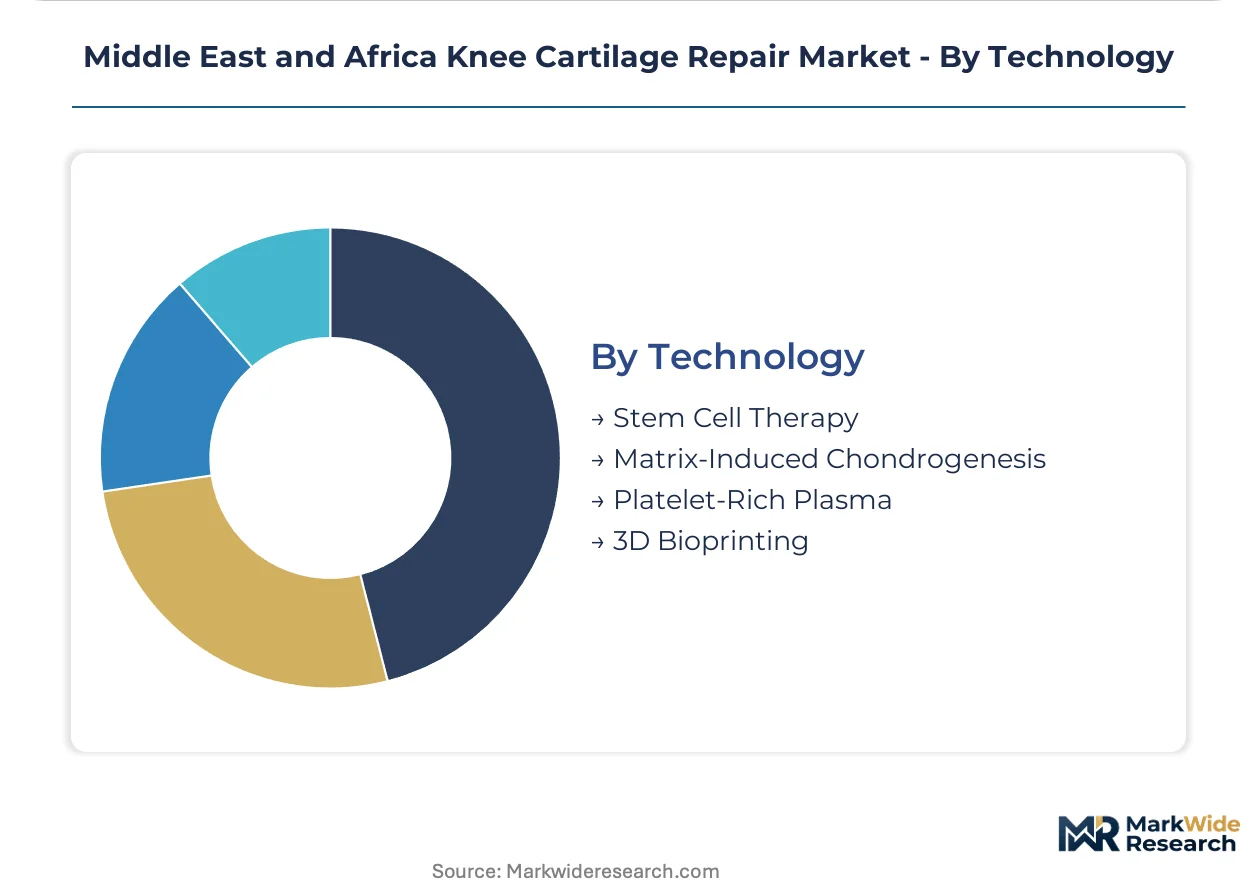
- Stem Cell Therapy:Mesenchymal stem cell applications include bone marrow aspirate concentrate and adipose-derived preparations. SAHPRA's ICH-GCP aligned trial requirements are extending South African approval timelines relative to Gulf state pathways.
- Matrix-Induced Chondrogenesis:Scaffold-assisted cell delivery improving surgical reproducibility. Private hospital groups in Johannesburg are adopting these platforms to collapse price premiums previously commanded by imported allograft alternatives.
- Platelet-Rich Plasma:Autologous blood fraction concentration for intra-articular delivery.
- 3D Bioprinting:Emerging osteochondral construct fabrication integrating patient cells with customized scaffold geometries.
Matrix-Induced Chondrogenesis anchors near-term commercial traction; 3D Bioprinting holds steepest expansion trajectory pending regulatory pathway clarification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Middle East and Africa knee cartilage repair markets. Gulf state medical tourism corridors absorb premium biologic therapies with minimal reimbursement friction, while South African public systems and North African markets remain acutely sensitive to procedure cost differentials.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi's Cleveland Clinic Abu Dhabi anchor medical tourism demand for autologous chondrocyte implantation. MOHAP enforces medical device and biologic standards that shape product registration timelines for cartilage repair therapies. Dubai's healthcare free zones enable direct-to-facility distribution models that bypass traditional hospital procurement channels.
Saudi Arabia
SFDA regulates medical device and biologic entry, with Riyadh and Jeddah hospital systems investing in cell processing infrastructure. The kingdom's Vision 2030 healthcare privatization agenda expands private hospital capacity for advanced orthopedic procedures. King Faisal Specialist Hospital in Riyadh anchors regional demand for matrix-assisted autologous chondrocyte implantation.
South Africa
SAHPRA applies ICH-GCP aligned clinical trial standards that extend approval pathways for novel stem cell technologies. Netcare and Mediclinic private hospital groups in Johannesburg and Cape Town dominate arthroscopic procedure volumes. Sports medicine clinics in Pretoria and Durban expand dedicated arthroscopy suites to capture rugby and cricket athlete populations.
Egypt
Underpenetrated private healthcare investment creates first-mover opportunities for distribution partnership establishment. The country's national pharmaceutical regulator oversees medical device registration with evolving clinical evidence requirements. Cairo and Alexandria private hospital clusters are emerging as destination sites for North African patients seeking cartilage repair procedures.
Israel
Advanced biomedical R&D infrastructure supports stem cell therapy platform development with regulatory alignment to EU MDR standards. Sheba Medical Center and Hadassah Medical Center in Tel Aviv and Jerusalem anchor clinical adoption of novel osteochondral constructs. The country's health technology assessment framework shapes reimbursement for cell-based interventions.
Middle East and Africa Knee Cartilage Repair Market Competitive Landscape
Multinational orthopedic conglomerates and specialized sports medicine players split the Middle East and Africa knee cartilage repair market through divergent channel strategies. Market structure tilts toward consolidated premium positioning in Gulf state medical tourism corridors, with fragmentation emerging in South African private clinic networks. Two archetypes dominate: diversified orthopedic giants leveraging established hospital system relationships, and sports medicine specialists capturing arthroscopic procedure volume through targeted surgeon training programs. Competitive moves center on distribution partnership expansion into underpenetrated North African markets and sequencing regulatory submissions to prioritize faster Gulf state approval pathways over protracted South African timelines.
Within the diversified orthopedic tier, Zimmer Biomet Holdings, Inc. and Stryker Corporation exemplify scale-driven positioning through Gulf state hospital system penetration. Smith & Nephew plc occupies a specialized sports medicine position, with its regional presence anchored through arthroscopic procedure suites in South African private facilities. These three companies represent contrasting strategic postures: premium biologic distribution depth versus targeted sports medicine portfolio concentration.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings, Inc. |
| Arthrex, Inc. |
| Smith & Nephew plc |
| Stryker Corporation |
| Johnson & Johnson |
| DePuy Synthes |
| Medacta Group SA |
| B. Braun Melsungen |
| Vericel Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in Gulf state cell processing facilities drives premium pricing for autologous chondrocyte implantation while compressing margins on simpler microfracture procedures across South African public systems. Laboratory utilization rates above eighty percent in Johannesburg and Dubai enable suppliers to command scarcity premiums, whereas idle arthroscopic instrument capacity in secondary cities forces discounting to maintain throughput.
Pricing Analysis
After-sales revenue from cell culture maintenance contracts and surgeon training programs drives lifetime value for biologic therapy manufacturers. Three-tier pricing structure across premium autologous chondrocyte implantation, standard matrix-assisted procedures, and economy microfracture tiers reflects GMP certification requirements and regional laboratory access. Cost compression in the economy tier intensifies because public health systems in South Africa and Egypt prioritize budget adherence over long-term outcomes. Sports medicine clinics serving medical tourism patients in Dubai and Riyadh exhibit lowest price sensitivity, while North African public hospitals demonstrate acute budget constraint responsiveness.
Supply Chain Analysis
Contract manufacturing concentration for cell culture media and scaffold materials rests with specialized biologics CMs in Germany, Switzerland, and the United States. Fetal bovine serum, collagen matrices, and polymer scaffolds feed from global suppliers subject to cold chain integrity requirements. Single-source vulnerability in cell processing equipment creates procurement risk for regional laboratory buildouts. Distribution runs through hospital group purchasing organizations in Gulf states and direct-to-facility channels in South African private clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Knee Cartilage Repair Market represents early-cycle expansion as Gulf state medical tourism infrastructure attracts regional patients seeking advanced biologic interventions unavailable in home markets.
For Market Incumbents: Harden cell processing capacity ownership in Johannesburg and Dubai to defend margin position against emerging matrix-assisted platform competitors. Secure GMP certification upgrades ahead of SAHPRA's evolving biologic standards to maintain premium tier access. Anchor hospital system relationships through exclusive surgeon training partnerships that embed workflow dependency. For New Entrants and Emerging Players: Egypt's underpenetrated private hospital sector offers first-mover distribution partnership opportunities before established players consolidate channel access. Target rehabilitation centers in UAE medical tourism corridors with minimally invasive delivery platforms that bypass traditional hospital procurement. Pursue direct-to-facility commercialization models in Dubai Healthcare City free zones to circumvent centralized contracting. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cell-based therapy manufacturing as GMP facility requirements expand. Long-term viability favors platforms with integrated laboratory and surgical delivery capabilities rather than pure-play device manufacturers. Monitor SFDA and MOHAP approval timeline convergence as signal for competitive entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Laboratory Certification | SAHPRA alignment with ICH-GCP standards extends approval timelines for uncertified entrants. |
| Medical Tourism Package Integration | Dubai and Riyadh hospital systems bundle cartilage repair with post-acute rehabilitation services. |
| Surgeon Training Academy Partnership | Sports medicine clinics in Johannesburg and Cape Town embed vendor-specific arthroscopic workflows. |
| Direct-to-Facility Distribution | Healthcare free zones enable bypass of hospital group purchasing concentration in Gulf states. |
| Matrix-Assisted Platform Launch | Scaffold-enhanced delivery collapses price premiums previously commanded by imported allograft alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital procurement managers, cell processing laboratory directors, and regulatory affairs specialists across South Africa, UAE, and Saudi Arabia and refined through secondary validation. Clinical trial registries, SAHPRA and SFDA approval databases, hospital procurement records, and GPO contract filings anchored quantitative sizing. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Demand-supply balance framing modeled patient flow through medical tourism corridors, laboratory capacity constraints, and surgeon training pipeline limitations across the projection horizon. Product type, delivery mode, end user facility type, and technology sophistication tier segmented volume and value outputs. CAGRs derived from procedure growth trajectories, pricing elasticity by payer type, and biologic therapy penetration curves. Cell culture input cost volatility and regulatory approval timeline differentials between Gulf states and South Africa informed scenario weighting.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by diversified orthopedic conglomerates or rapid stem cell platform approvals by SFDA would shift outcomes. Currency fluctuation in South African rand and Egyptian pound, plus fetal bovine serum supply disruptions, present revision triggers. Quarterly review of laboratory utilization rates, medical tourism patient origin shifts, and national health insurance reimbursement determinations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Hip Replacement Market