
 Small Molecules Contract Development and Manufacturing Organization Market | 2026-2036
Small Molecules Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Small Molecules Contract Development and Manufacturing Organization Market Insights
Commercial production revenue is reshaping margin distribution across the Small Molecules Contract Development and Manufacturing Organization value chain, pulling profitability downstream from early-stage discovery services. Lonza Group dominates high-potency API manufacturing with dedicated containment infrastructure across Swiss and US sites. WuXi AppTec leverages integrated discovery-to-commercial platforms to anchor long-term client relationships. Catalent Inc. specializes in oral solid dose technologies, occupying a defensible niche in modified-release formulations.
Small Molecules Contract Development and Manufacturing Organizations are third-party service providers that execute chemical synthesis, process development, and GMP manufacturing for low-molecular-weight pharmaceutical compounds, typically requiring reaction optimization at scales from milligram to multi-ton with purity thresholds exceeding 99.5%. These entities enable pharmaceutical and biotech companies to access specialized chemistry expertise without capital-intensive facility investments. Clinical manufacturing services command premium pricing due to batch complexity and regulatory documentation burdens, while commercial production generates volume-driven recurring revenue. Continuous flow technology adoption is accelerating as clients seek improved process safety and yield consistency for hazardous chemistries.
FDA enforces current Good Manufacturing Practice standards through facility inspections and warning letters that directly determine market access for US-bound products. EMA's revised Annex 1 guidelines on sterile manufacturing and India's CDSCO active pharmaceutical ingredient registration requirements are elevating quality compliance costs across multiple jurisdictions. China's NMPA implements domestic data requirements and on-site audits that foreign CDMOs must satisfy for commercial supply into the world's second-largest pharmaceutical market. Stakeholders must evaluate regulatory pathway convergence between FDA, EMA, and NMPA when selecting manufacturing partners for multinational trial programs.
Market Dynamics
Continuous flow chemistry is hybridizing batch manufacturing paradigms across small molecule CDMO operations, compressing cycle times for hazardous synthetic routes while FDA and EMA inspections intensify scrutiny of legacy equipment validation protocols.
Growth Catalysts
- Biotech pipeline expansion:Venture-funded biotech firms lack internal GMP infrastructure and outsource end-to-end development to capture speed-to-clinic advantages.
- EMA's Annex 1 revision:Sterile manufacturing guideline updates are forcing facility upgrades that favor specialized CDMOs with dedicated containment capabilities.
- India's PLI scheme:Production-linked incentives for active pharmaceutical ingredient manufacturing are attracting multinational sponsor programs to domestic synthesis clusters.
Market Restraints
- Specialized solvent cost volatility:Tetrahydrofuran and acetonitrile price swings squeeze margin predictability on high-volume commercial contracts.
- Swiss containment equipment dependency:Isolator and barrier technology supply concentrates among limited European vendors, extending lead times for high-potency API capacity expansion.
- China's NMPA data localization:Domestic clinical trial and manufacturing documentation requirements create regulatory friction for foreign CDMOs seeking commercial supply access.
Strategic Opportunities
- Brazil's ANVISA alignment:Emerging regulatory convergence with FDA standards creates pathway for pre-qualified CDMOs to capture Latin American commercial manufacturing.
- Oligonucleotide-small molecule conjugates:Antibody-drug conjugate platforms are pulling CDMOs into hybrid chemistry-biologics service expansion.
- Digital batch records:Cloud-based manufacturing execution systems are enabling real-time sponsor visibility and outcome-based contracting structures.
Industry Challenges
- Process analytical technology expertise gap:FDA's quality-by-design mandates require spectroscopic and chromatographic in-line monitoring capabilities that outpace available talent pools.
- Legacy ERP integration:Sponsor systems from SAP to smaller clinical platforms create data exchange friction during tech transfer phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Molecules Contract Development and Manufacturing Organization Market |
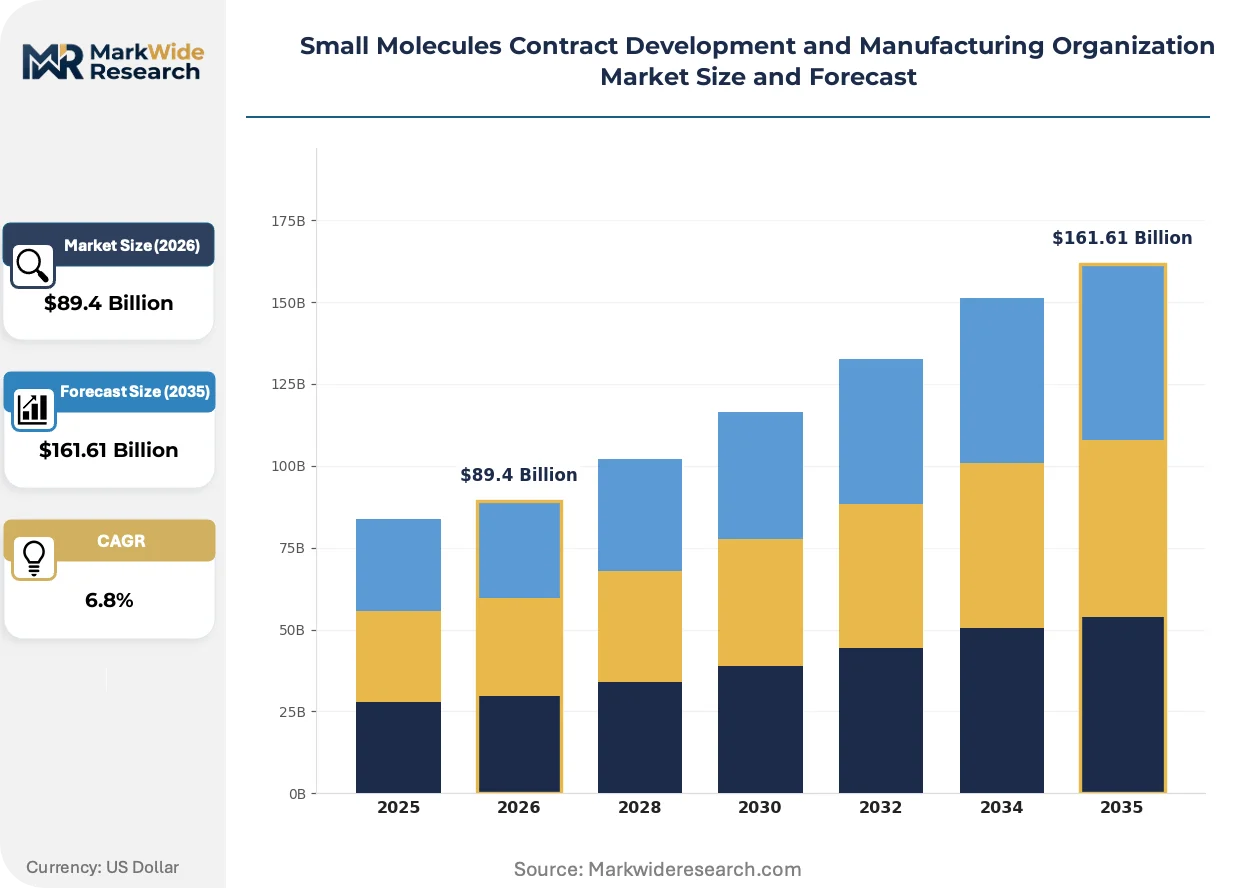
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $161.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Development, Formulation Development, Clinical Manufacturing, Commercial Production Client Type: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Research Organizations Technology: Microwave Synthesis, Continuous Flow Technology, Crystallization, Nanomaterials Application: Oncology, Cardiovascular Disorders, Infectious Diseases, Metabolic Disorders |
| Companies Covered | Cambrex Corporation, Recipharm AB, Lonza Group, Neuland Laboratories Limited, WuXi AppTec, Catalent Inc., Siegfried Holding AG, CordenPharma International, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Molecules Contract Development and Manufacturing Organization Market Trends and Innovations
Process intensification technologies are compressing footprint requirements while multiplying output per reactor volume, fundamentally altering capital efficiency calculations for new facility investments across the value chain.
Continuous flow reactor systems are hybridizing traditional batch synthesis workflows for nitration, hydrogenation, and organometallic chemistries. Mid-cap pharmaceutical sponsors are adopting these platforms for Phase II scale-up to reduce thermal hazard exposure. The technology is hybridizing project economics by collapsing development-to-commercial timelines and enabling on-demand production models that challenge conventional campaign-based capacity planning.
EMA's revised Annex 1 guidelines on sterile manufacturing are mandating barrier technology and isolator deployment for all new aseptic processing lines. CDMOs with existing containment infrastructure capture sponsor migration from facilities requiring retrofit. High-potency oncology APIs and hormone therapies face the steepest compliance cliffs, driving consolidation toward specialized European and North American sites with validated isolator suites.
Biotech procurement teams are unbundling discovery chemistry from manufacturing services, creating discrete vendor selection for medicinal chemistry versus GMP execution. This fragmentation pressures full-service CDMOs to defend integrated platform value through data package continuity and regulatory submission support. The pattern is most pronounced among Boston and San Francisco sponsor clusters where venture capital timelines compress vendor switching cycles.
Small Molecules Contract Development and Manufacturing Organization Market Segmentation
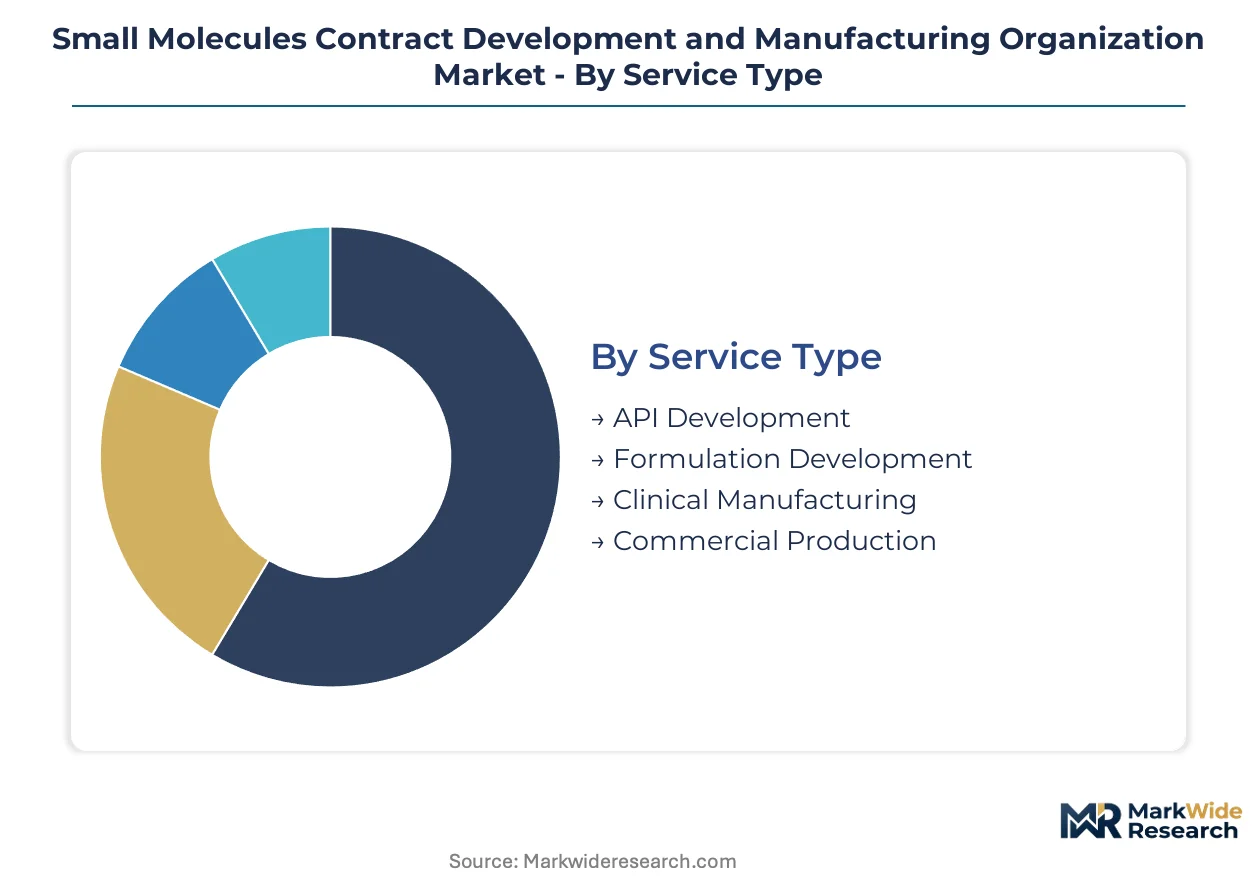
Segmentation in the Small Molecules Contract Development and Manufacturing Organization market reveals how service capabilities, client risk profiles, and therapeutic applications allocate contract value across the value chain. Understanding these dimensions enables sponsors to match outsourcing scope with vendor specialization and regulatory readiness.
Service Type:
Cost tier determines margin structure and capital intensity across the service spectrum, with early-stage activities commanding technical premiums and late-stage operations generating volume-driven recurring revenue.
- API Development:Process chemistry and route scouting for active pharmaceutical ingredients require specialized analytical infrastructure and reaction optimization expertise. Demand concentrates among Boston and Basel sponsor clusters where venture-funded biotech firms seek speed-to-clinic advantages without captive GMP investment.
- Commercial Production:Multi-ton GMP manufacturing campaigns for approved small molecule drugs operate on long-term supply agreements with stringent quality consistency requirements. Indian and Chinese synthesis clusters are capturing contract migration as FDA and EMA inspections validate their facilities for US and European commercial supply.
- Formulation Development:Oral solid dose and modified-release design services bridge API synthesis with clinical-ready dosage forms.
- Clinical Manufacturing:Phase I through Phase III batch production supports investigational new drug applications with adaptive scale-up protocols.
Commercial Production holds installed capacity. API Development is rotating up the share rankings.
Client Type:
Customer type shapes contract duration, technical complexity, and regulatory documentation burden across the outsourcing relationship lifecycle.
- Pharmaceutical Companies:Large-cap sponsors with established product portfolios outsource capacity-constrained chemistries and geographic expansion manufacturing. Internal portfolio prioritization is driving Big Pharma to divest legacy manufacturing assets and convert fixed costs to variable outsourcing spend.
- Biotech Firms:Venture-funded development-stage companies lack GMP infrastructure and require end-to-end partners from preclinical through commercialization. Cambridge and South San Francisco clusters are expanding CDMO partnerships as FDA IND timelines compress and capital efficiency mandates intensify.
- Academic Institutions:University technology transfer offices license early-stage compounds requiring kilogram-scale GMP batches for first-in-human studies.
- Research Organizations:Non-profit and government laboratories contract specialized synthesis for probe compounds and reference standards.
Pharmaceutical Companies anchor contract value. Biotech Firms are expanding most quickly as pipeline funding flows into outsourced execution.
Technology:
Technology maturity separates proven platforms from emerging capabilities that sponsors adopt for hazard mitigation and yield optimization.
- Continuous Flow Technology:Microreactor and mesofluidic systems enable precise temperature and residence time control for exothermic reactions. FDA's quality-by-design incentives are accelerating adoption for nitration and hydrogenation chemistries where thermal runaway risks dominate batch processing economics.
- Crystallization:Polymorph control and particle size engineering determine bioavailability and downstream processing efficiency for oral solid dose formulations. High-potency oncology APIs with poor aqueous solubility are concentrating demand in European sites with isolator-equipped crystallization suites.
- Microwave Synthesis:Dielectric heating accelerates reaction kinetics for rapid route scouting and library generation in discovery chemistry.
- Nanomaterials:Amorphous solid dispersions and lipid nanoparticle formulations address bioavailability challenges for BCS Class II and IV compounds.
Crystallization dominates installed capacity. Continuous Flow Technology is climbing the fastest as safety and efficiency mandates reshape process selection.
Application:
Therapeutic area concentration directs CDMO capability investment toward high-value specialized manufacturing segments with distinct regulatory and containment requirements.
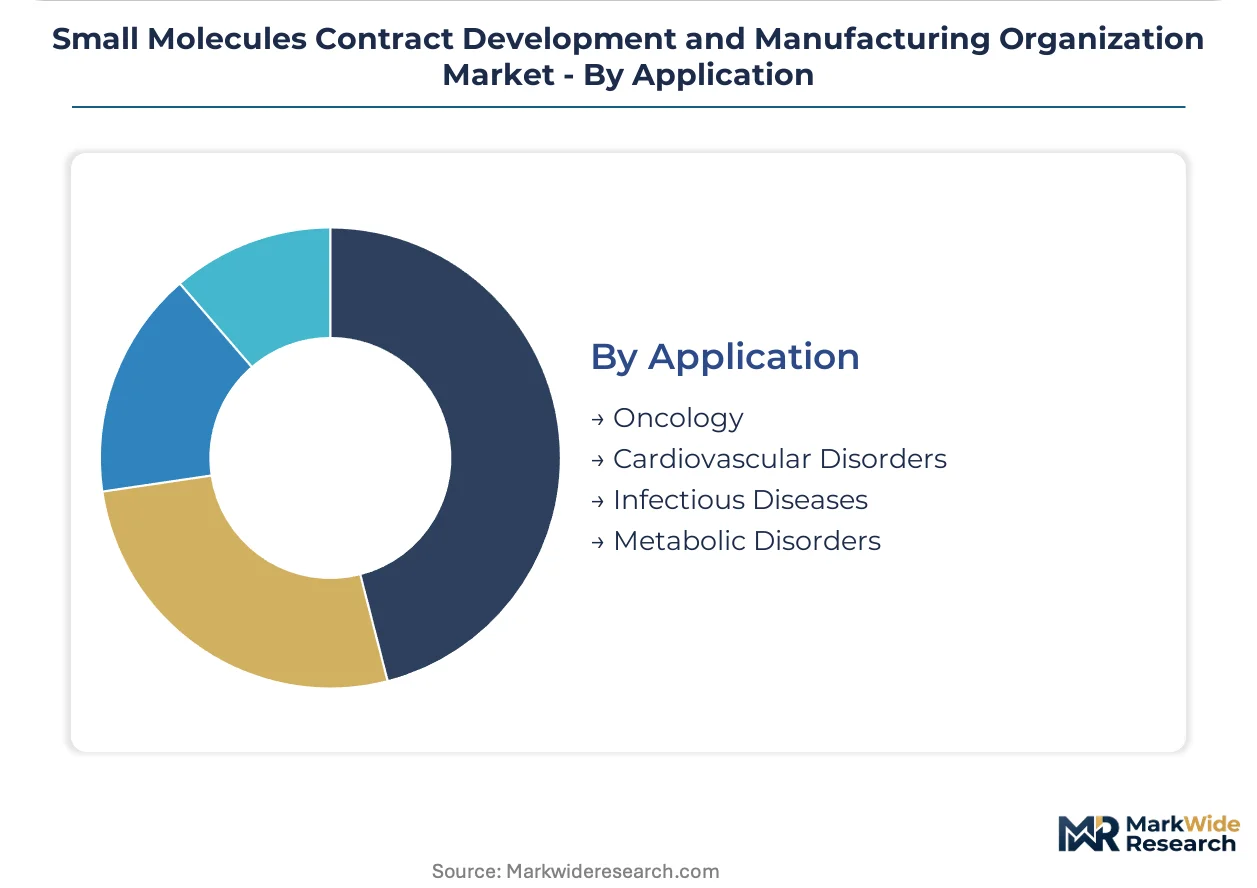
- Oncology:Cytotoxic and hormone-modulating small molecules require containment infrastructure for operator protection and environmental control. FDA's orphan drug incentives and accelerated approval pathways are expanding pipeline volumes for high-potency API synthesis across Swiss and North American specialized sites.
- Infectious Diseases:Antiviral and antibacterial manufacturing scales rapidly during pandemic preparedness and resistance-driven portfolio renewal. US government BARDA contracts and PEPFAR procurement programs are sustaining demand for large-volume antibiotic and antiretroviral API production.
- Cardiovascular Disorders:Chronic disease small molecules with established generic competition face pricing pressure that favors cost-optimized manufacturing in Asian synthesis clusters.
- Metabolic Disorders:Diabetes and obesity therapeutics require scalable processes for chronic administration populations with growing prevalence.
Oncology commands premium capacity allocation. Infectious Diseases is gaining share fastest as antimicrobial resistance programs expand government-backed manufacturing contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Western sponsors prioritize containment infrastructure and regulatory pedigree, while Asian markets emphasize cost-optimized scale and API synthesis capacity.
United States
FDA's quality-by-design mandates and accelerated approval pathways drive demand for high-potency API manufacturing with validated isolator suites. Boston and San Francisco biotech clusters outsource end-to-end development to capture speed-to-clinic advantages. Thermo Fisher Scientific anchors commercial production capacity through multi-site GMP networks serving orphan drug sponsors.
Switzerland
Swissmedic's stringent containment standards and proximity to Basel-based pharmaceutical headquarters sustain premium pricing for cytotoxic synthesis. Lonza Group operates dedicated high-potency infrastructure across Visp and Portsmouth sites. The Basel-Lucerne corridor concentrates specialized oncology API capacity serving European and US commercial supply.
India
CDSCO's active pharmaceutical ingredient registration requirements and the PLI scheme attract multinational sponsor programs to domestic synthesis clusters. Neuland Laboratories scales peptide and generic API production from Hyderabad facilities. Gujarat and Maharashtra states build large-scale chemical manufacturing parks with competitive cost structures for US and European export.
China
NMPA's domestic clinical trial data requirements and on-site audit protocols create regulatory friction for foreign CDMOs seeking commercial access. WuXi AppTec leverages integrated discovery-to-commercial platforms from Shanghai and Changzhou sites. The Yangtze River Delta concentrates process development talent serving both domestic innovators and multinational sponsors.
Germany
EMA's Annex 1 revision on sterile manufacturing drives facility upgrade demand toward CDMOs with existing barrier technology. Recipharm and Siegfried Holding occupy positions across oral solid dose and high-containment segments. The Rhine-Main and Bavarian regions maintain legacy chemical synthesis expertise alongside biologics hybrid manufacturing capabilities.
Small Molecules Contract Development and Manufacturing Organization Market Competitive Landscape
Capability concentration sits with specialized European and North American players possessing validated containment infrastructure; scale advantage sits with Asian operators building multi-ton API synthesis parks. The market structures around three tiers: integrated full-service platforms, niche technology specialists, and regional cost-optimized manufacturers. Consolidation pressure intensifies as sponsors unbundle discovery from manufacturing services, favoring CDMOs with regulatory submission continuity. Dominant competitive moves include strategic partnerships for oligonucleotide-conjugate capabilities and capacity expansion in Indian PLI-designated zones.
Within the integrated platform tier, WuXi AppTec exemplifies the discovery-to-commercial anchor model, while Lonza Group represents specialized high-potency manufacturing with Swiss and US containment infrastructure. Among formulation-focused operators, Catalent Inc. occupies a position in oral solid dose technologies. These three entities illustrate how capability depth, geographic regulatory access, and therapeutic specialization allocate competitive position across sponsor procurement decisions.
| Leading Market Players |
|---|
| Cambrex Corporation |
| Recipharm AB |
| Lonza Group |
| Neuland Laboratories Limited |
| WuXi AppTec |
| Catalent Inc. |
| Siegfried Holding AG |
| CordenPharma International |
| Thermo Fisher Scientific Inc. |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp chemical corridor shapes cost dynamics across European small molecule CDMO operations, where freight differentials between bulk API shipments and specialized high-potency containers feed directly into three-tier pricing stratification across premium isolator-certified, standard GMP, and economy generic synthesis tiers.
Pricing Analysis
Long-term offtake agreements dominate commercial manufacturing relationships, locking volume commitments across multi-year supply cycles for approved therapies. Price differentiation rests on containment certification grade and geographic regulatory pedigree, with FDA-validated Swiss and US facilities commanding substantial premiums over Indian and Chinese standard GMP operations. Cost compression in high-volume generic APIs intensifies as sponsor procurement teams unbundle discovery from manufacturing services. Biotech firms exhibit highest price sensitivity due to venture capital runway constraints, while Big Pharma prioritizes regulatory continuity over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for multinational sponsor programs seeking dual-source API security. Synthesis capacity concentrates in India, China, and Switzerland, with specialized tetrahydrofuran and acetonitrile solvent supplies drawing from German and Belgian petrochemical hubs. Single-source vulnerability in Swiss isolator equipment extends lead times for high-potency capacity expansion. Distribution runs through regional hub-and-spoke models anchored by Thermo Fisher's US network, Lonza's Swiss-US corridor, and WuXi AppTec's Yangtze River Delta cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated containment infrastructure and process analytical technology expertise constitute acute capability gaps, constraining sponsor access to compliant manufacturing partners for oncology and hormone-modulating therapies.
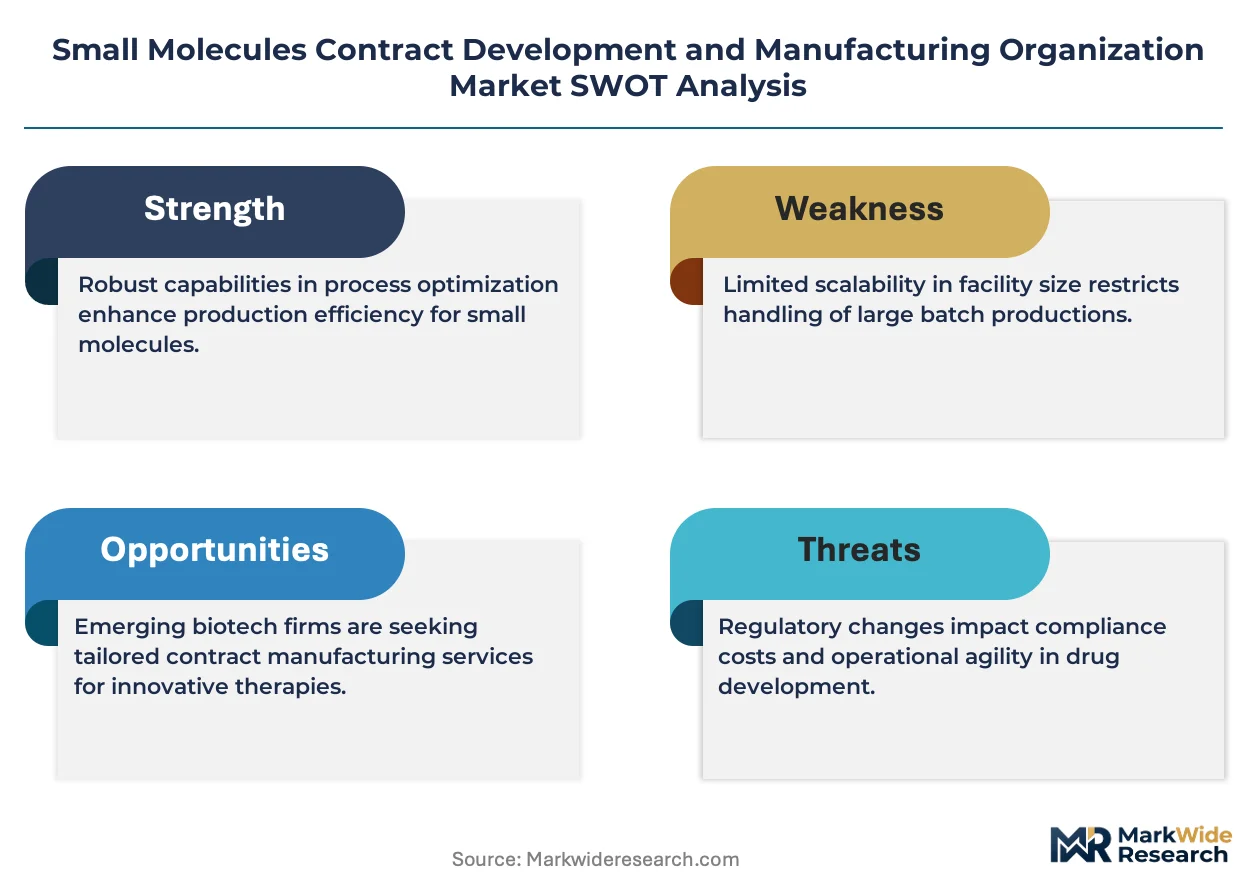
For Market Incumbents: Insulate high-potency API margins through dedicated isolator suite expansion at Swiss and US sites, countering sponsor migration toward Asian cost-optimized alternatives. Deepen backward integration into specialized solvent recovery systems to buffer tetrahydrofuran price volatility. Prioritize EMA Annex 1 compliance certification ahead of competitor retrofit timelines. For New Entrants and Emerging Players: Establish a beachhead in oligonucleotide-small molecule conjugate manufacturing, where hybrid chemistry-biologics capabilities remain underdeveloped among mid-tier CDMOs. Target Brazil's ANVISA-aligned regulatory environment for Latin American commercial manufacturing access. Lead with digital batch record platforms enabling real-time sponsor visibility as a differentiated go-to-market anchor. For Investors and Strategic Acquirers: Carve-out targets emerge from Big Pharma divestiture programs spinning legacy oral solid dose facilities as internal portfolio prioritization accelerates. Long-term viability centers on CDMOs possessing both FDA and EMA commercial supply validation with existing barrier technology infrastructure. Watch for inflection signals in India's PLI scheme utilization rates as multinational sponsor program commitments materialize.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Suite Expansion | Lonza's Swiss containment infrastructure captures EMA Annex 1-driven sponsor migration. |
| Continuous Flow Technology Deployment | WuXi AppTec's microreactor platforms reduce thermal hazard exposure for nitration chemistries. |
| PLI Zone Capacity Buildout | Neuland Laboratories scales peptide synthesis from Hyderabad's government-backed chemical parks. |
| Digital Manufacturing Execution Systems | Cloud-based batch records enable Catalent's outcome-based contracting with oral solid dose sponsors. |
| Regulatory Convergence Partnership | Brazil's ANVISA-FDA alignment creates pre-qualified CDMO access to Latin American commercial supply. |
Research Methodology
The analysis maps API development, clinical manufacturing, formulation services, and commercial production segments, each validated through drug development executives, regulatory affairs leads, quality assurance directors, and procurement managers at sponsor organizations. Primary interview findings triangulate against FDA warning letter databases, EMA inspection reports, CDSCO registration filings, ClinicalTrials.gov protocols, and customs trade data for active pharmaceutical ingredient flows. Bottom-up service line revenue estimates reconcile with top-down pharmaceutical outsourcing spend analysis.
Assumptions held fixed include current FDA quality-by-design enforcement intensity, EMA Annex 1 implementation timelines, and India's PLI scheme continuation. Variables tested across the projection horizon encompass NMPA data localization friction, Swiss containment equipment supply constraints, and continuous flow technology adoption curves. Segmentation models incorporate service type, client risk profile, therapeutic application, and technology maturity. CAGRs derive from sponsor outsourcing penetration rates and capacity utilization trends at validated facilities.
Sensitivities concentrate around regulatory inspection frequency shifts, solvent cost volatility, and sponsor unbundling of discovery from manufacturing services. Forecasts reflect documented assumptions on pipeline funding flows and geographic regulatory convergence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market