
 Global Immunosuppressant Drugs Market | 2026-2036
Global Immunosuppressant Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunosuppressant Drugs Market Foresight
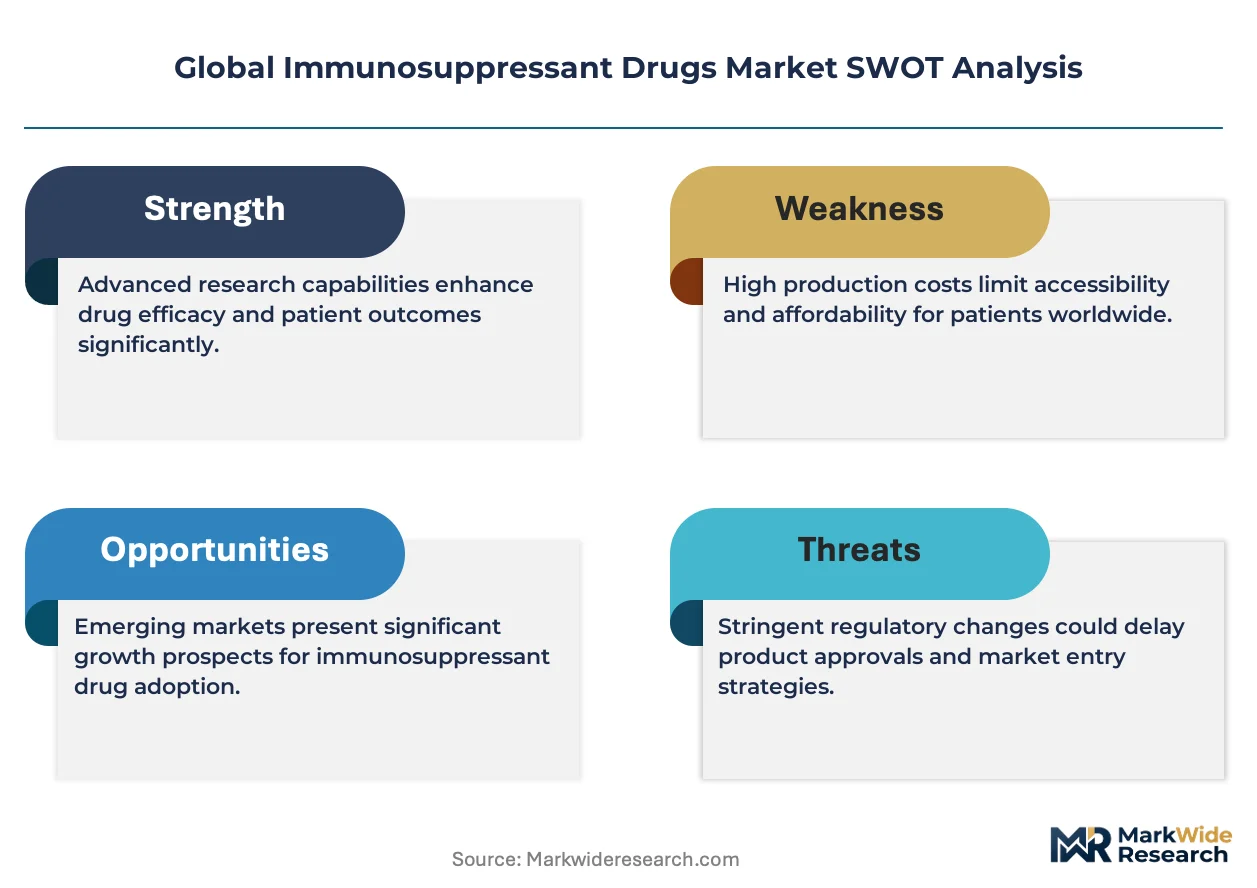
Good Manufacturing Practice certification for sterile injectable biologics is collapsing as a barrier, concentrating production among firms with validated cold-chain infrastructure. Novartis AG leverages its transplant therapy heritage to sustain leadership in calcineurin inhibitor supply. Bristol-Myers Squibb Company anchors its position through integrated biologics manufacturing. Pfizer Inc. differentiates via global distribution networks for infused immunosuppressants.
Immunosuppressant drugs are pharmacologic agents that modulate T-cell activation, cytokine signaling, or nucleotide synthesis to prevent graft rejection and autoimmune pathogenesis; formulations require precise bioavailability controls, with biologics demanding refrigerated storage between 2°C and 8°C to preserve protein integrity. Calcineurin Inhibitors occupy the largest revenue pool due to decades of transplant protocol embedding, while Biologics represent the fastest-expanding class as monoclonal antibodies displace broad-spectrum corticosteroids in lupus and inflammatory bowel disease. Organ Transplantation generates the most concentrated procurement volumes, though Autoimmune Disorders now attract the majority of new molecular entity investments.
The FDA enforces REMS and BLA pathways that extend development timelines for novel biologics, while the EMA's MDR and ATMP frameworks impose comparable compliance burdens in Europe; Japan's PMDA adds distinct pharmacovigilance requirements for post-transplant infection monitoring. These layered approval regimes privilege incumbents with established regulatory affairs capacity over emerging entrants. Stakeholders must monitor biosimilar erosion timelines and cell therapy competition to calibrate portfolio prioritization.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategies for biologics is reshaping competitive entry timelines, privileging incumbents with established regulatory affairs capacity while compressing development windows for novel monoclonal antibodies. Cold-chain infrastructure requirements are concentrating production among validated suppliers.
Growth Catalysts
- Organ Transplantation Volume:Rising kidney and liver transplant procedures in the United States, Germany, and Japan generate concentrated procurement demand for calcineurin inhibitors and induction therapies.
- EMA's ATMP Framework:Accelerated pathways for advanced therapy medicinal products in Europe shorten time-to-market for cell-based immunosuppressants, incentivizing biologics pipeline investment.
- Monoclonal Antibody Platforms:Precision targeting of cytokine signaling pathways in lupus and inflammatory bowel disease expands addressable patient populations beyond transplant centers.
Market Restraints
- Biologics Cold-Chain Costs:Refrigerated storage between 2°C and 8°C imposes capital intensity on distribution networks, elevating total cost of ownership for infused formulations.
- REMS Compliance Burden:FDA-mandated risk management programs extend development timelines and require specialized pharmacovigilance infrastructure, raising barriers for emerging entrants.
- Biosimilar Erosion Pressure:Patent expirations on legacy calcineurin inhibitors expose originator products to price compression from follow-on biologics in European tender markets.
Strategic Opportunities
- Autoimmune Disorder Expansion:Underpenetrated rheumatology and gastroenterology clinics in India and Brazil offer volume growth as monoclonal antibodies displace corticosteroids.
- Japan's PMDA Pharmacovigilance Pathways:Distinct post-transplant infection monitoring requirements create first-mover advantages for firms with integrated real-world evidence capabilities.
- Digital Therapeutics Convergence:Integration of adherence monitoring platforms with biologics dosing regimens enables outcome-based contracting with transplant centers.
Industry Challenges
- Specialized Manufacturing Talent Scarcity:Sterile injectable biologics production requires validated aseptic processing expertise that concentrates among limited contract manufacturing organizations.
- BLA Documentation Intensity:Biologics License Application submissions demand extensive CMC sections characterizing protein structure and stability, extending regulatory preparation cycles.
- Legacy System Integration:Electronic health record interoperability between transplant centers and specialty pharmacies complicates patient monitoring data capture for REMS compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunosuppressant Drugs Market |
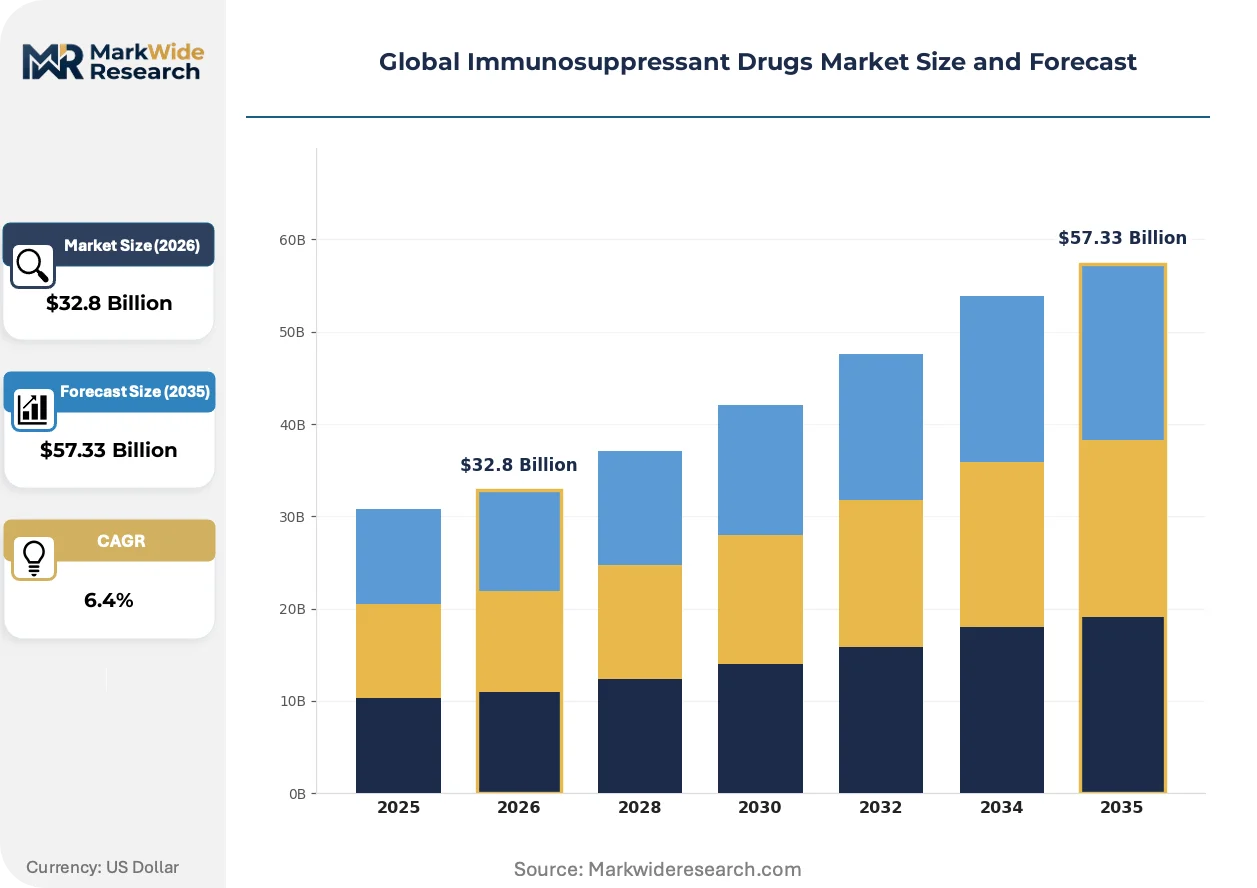
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Calcineurin Inhibitors, mTOR Inhibitors, Corticosteroids, Biologics, Antimetabolites Indication: Organ Transplantation, Autoimmune Disorders, Dermatological Conditions, Inflammatory Bowel Disease, Ophthalmic Diseases Formulation: Oral Tablets, Injectable Solutions, Topical Creams, Intravenous Infusions, Sustained Release Capsules End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Laboratories, Home Healthcare Services |
| Companies Covered | Novartis AG, Astellas Pharma, Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Pfizer Inc., Sanofi, GlaxoSmithKline plc, Johnson & Johnson, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunosuppressant Drugs Market Shifts & Advancements
Monoclonal antibody engineering is fragmenting therapeutic protocols across autoimmune indications, while regulatory frameworks accelerate differentiation between biologics and small-molecule pathways. Three developments merit particular attention.
Precision cytokine inhibition is bifurcating treatment algorithms in inflammatory bowel disease. TNF-alpha and interleukin pathway blockers enable steroid-sparing maintenance protocols. Gastroenterology practices in the United States and Germany are adopting these agents at accelerating velocity. This technology is compressing corticosteroid revenue pools while expanding biologics addressable markets.
EMA's Medical Device Regulation intersects with drug-device combination products for self-administered immunosuppressants. Pre-filled syringes and auto-injectors now require notified body certification alongside pharmaceutical approval. Subcutaneous biologics formulations targeting rheumatology patients face extended dual-track compliance timelines, prompting manufacturers to front-load device development investment.
Transplant center consolidation is altering procurement negotiation leverage. Large academic medical centers in the United States are centralizing pharmacy formulary decisions across multi-hospital systems, compressing vendor counts. This concentration is most visible in kidney transplant hubs, where integrated delivery networks now contract directly with biologics manufacturers for bundled induction and maintenance therapy protocols.
Global Immunosuppressant Drugs Market Segmentation
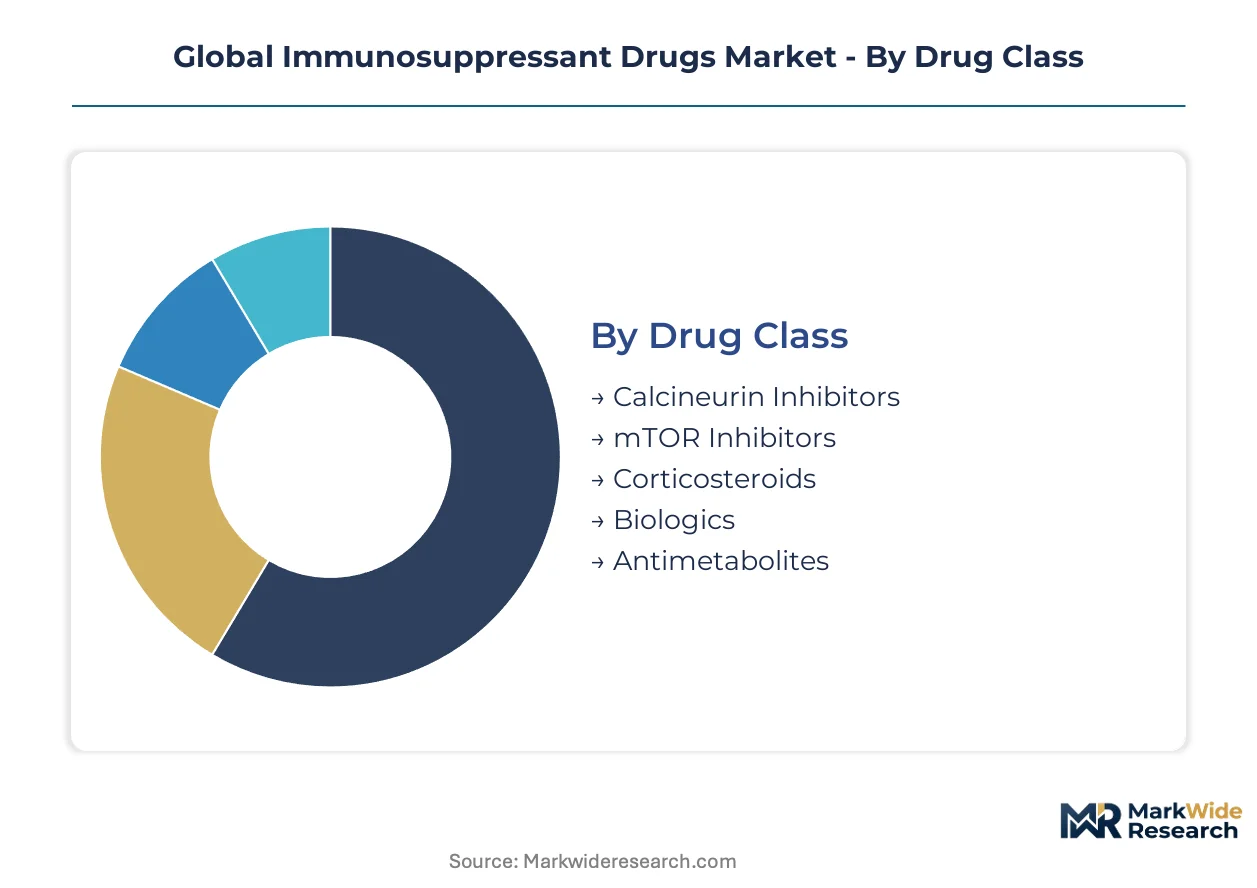
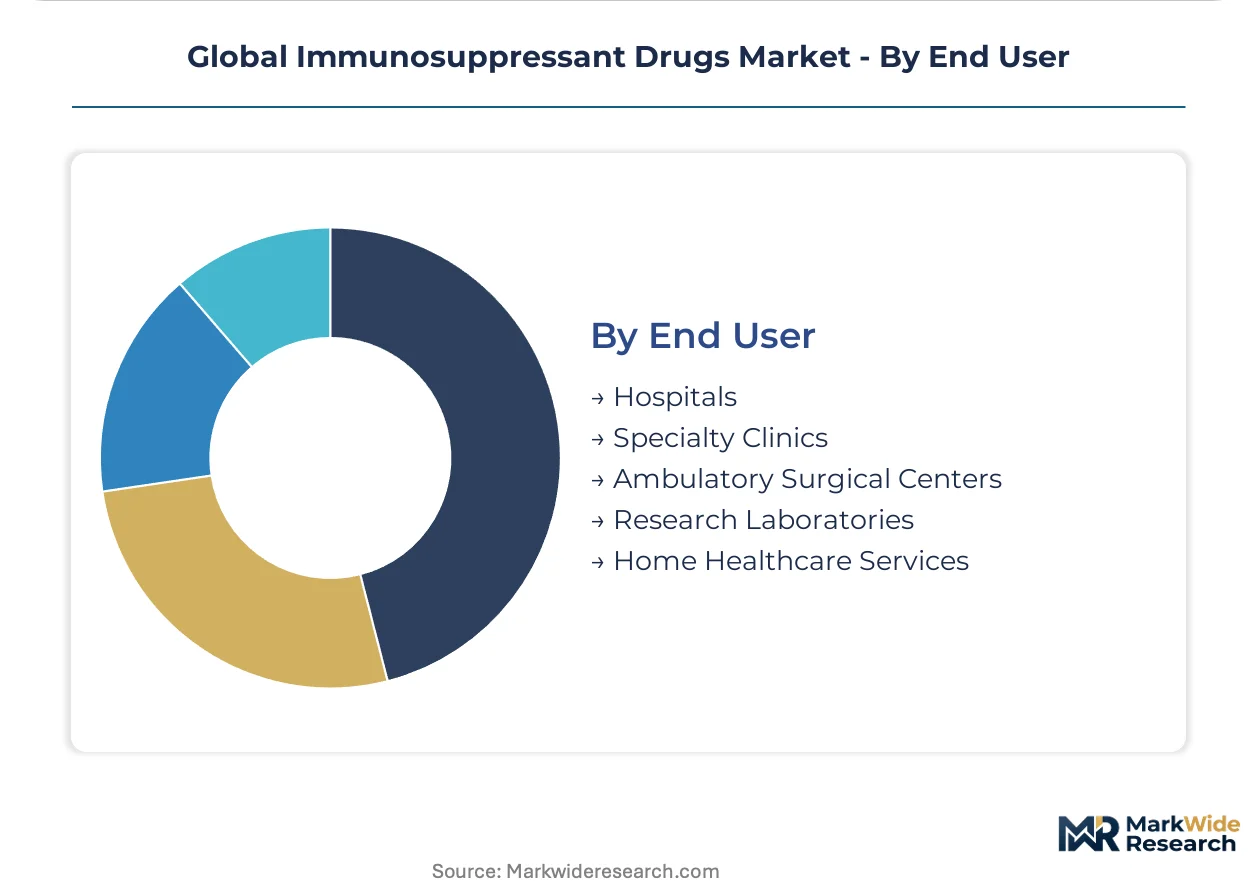
Segmentation in the immunosuppressant market reveals how procurement patterns diverge between transplant centers requiring sterile injectables and outpatient settings favoring oral maintenance therapies. Understanding these splits enables manufacturers to align cold-chain investments with formulation strategies.
Drug Class:
Geographic demand concentration varies sharply across drug classes, with calcineurin inhibitors and biologics showing distinct domestic-versus-export patterns.
- Calcineurin Inhibitors:Cyclosporine and tacrolimus formulations dominate kidney and liver transplant protocols through decades of clinical embedding. Procurement concentrates in United States academic medical centers and German university hospitals, where bundled induction-maintenance contracts lock in volume commitments.
- Biologics:Monoclonal antibodies targeting cytokine pathways require refrigerated distribution networks and carry premium positioning in lupus and inflammatory bowel disease. Japanese rheumatology clinics and United States gastroenterology practices drive adoption as steroid-sparing alternatives.
- mTOR Inhibitors:Sirolimus and everolimus serve niche protocols in calcineurin-sparing regimens and oncology combinations.
- Corticosteroids:Prednisone and methylprednisolone remain ubiquitous in induction therapy despite biologics displacement in maintenance.
- Antimetabolites:Azathioprine and mycophenolate mofetil anchor generic-heavy maintenance protocols in cost-sensitive markets.
Calcineurin inhibitors hold the largest share; momentum sits with biologics.
Indication:
Cost tier stratification separates high-acuity transplant indications from chronic autoimmune management with divergent pricing power.
- Organ Transplantation:Kidney, liver, and heart transplant programs generate concentrated procurement volumes through integrated delivery networks. United States transplant centers and Japanese surgical hubs command priority allocation from manufacturers due to protocol standardization and volume guarantees.
- Autoimmune Disorders:Rheumatoid arthritis, lupus, and vasculitis populations expand addressable markets beyond hospital settings. German rheumatology practices and United States specialty clinics are adopting biologics at accelerating velocity as corticosteroid alternatives.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis maintenance drives biologics penetration in gastroenterology.
- Dermatological Conditions:Psoriasis and atopic dermatitis support topical calcineurin inhibitor and biologics demand.
- Ophthalmic Diseases:Uveitis and transplant-related ocular complications represent niche but high-value segments.
Organ transplantation commands premium pricing; autoimmune disorders are climbing the fastest.
Formulation:
Customer type differentiation separates institutional buyers with cold-chain capability from retail-accessible outpatient prescriptions.
- Injectable Solutions:Sterile biologics requiring 2°C to 8°C storage concentrate production among validated contract manufacturers. Transplant centers in the United States and Japan contract directly for induction therapy bundles.
- Oral Tablets:Immediate-release tacrolimus and mycophenolate formulations dominate maintenance therapy in cost-sensitive markets. Indian and Brazilian outpatient pharmacies drive volume through generic substitution.
- Intravenous Infusions:Hospital-administered formulations for acute rejection episodes and induction protocols.
- Topical Creams:Dermatological applications of tacrolimus and pimecrolimus in eczema management.
- Sustained Release Capsules:Modified-release tacrolimus enabling once-daily dosing compliance in stable transplant recipients.
Injectable solutions capture the highest margins; oral tablets dominate prescription volume.
End User:
Supply concentration clusters around hospital systems with integrated specialty pharmacy capabilities versus fragmented outpatient channels.
- Hospitals:Academic medical centers and transplant hubs in the United States, Germany, and Japan consolidate formulary decisions across multi-hospital systems. These institutions negotiate direct manufacturer contracts for bundled biologics procurement.
- Specialty Clinics:Rheumatology and gastroenterology practices in urban United States markets and German metropolitan areas drive biologics adoption through physician-administered infusion centers.
- Ambulatory Surgical Centers:Outpatient transplant evaluation and pre-transplant protocols generate intermittent immunosuppressant demand.
- Research Laboratories:Cell therapy and tolerance induction protocols in university-affiliated centers.
- Home Healthcare Services:Subcutaneous biologics and oral maintenance dispensing for stable autoimmune patients.
Hospitals anchor revenue concentration; specialty clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA REMS mandates and EMA ATMP pathways are accelerating regulatory divergence across major markets, concentrating biologics production among validated cold-chain operators in the United States, Germany, and Japan while fragmenting generic penetration in emerging economies.
United States
Kidney and liver transplant volumes at academic medical centers in Boston and Houston drive concentrated procurement of calcineurin inhibitors. FDA REMS compliance requirements for monoclonal antibodies extend development timelines, privileging incumbents with established pharmacovigilance infrastructure. The Cleveland Clinic and Mayo Clinic transplant hubs negotiate direct manufacturer contracts for bundled induction therapies.
Germany
Rheumatology practices in Munich and Berlin are adopting TNF-alpha inhibitors at accelerating velocity as corticosteroid alternatives. EMA ATMP frameworks shorten time-to-market for cell-based immunosuppressants, incentivizing biologics pipeline investment. Frankfurt and Hamburg university hospitals anchor calcineurin inhibitor procurement through standardized transplant protocols.
Japan
PMDA pharmacovigilance requirements for post-transplant infection monitoring create distinct compliance burdens for biologics entrants. Tokyo and Osaka transplant centers command priority allocation from manufacturers due to protocol standardization. Japanese rheumatology clinics drive monoclonal antibody adoption in lupus management.
India
Cost-sensitive maintenance therapy markets in Mumbai and Delhi favor generic azathioprine and mycophenolate formulations. CDSCO regulatory pathways for biosimilars are compressing price points for legacy calcineurin inhibitors. Hyderabad and Ahmedabad manufacturing clusters supply oral tablet formulations across South Asian outpatient channels.
Brazil
Underpenetrated gastroenterology clinics in São Paulo and Rio de Janeiro offer volume growth for biologics as steroid-sparing alternatives. ANVISA approval timelines for infused immunosuppressants lag FDA and EMA pathways by 18-24 months. The São Paulo metropolitan area concentrates specialty pharmacy distribution for subcutaneous formulations.
Global Immunosuppressant Drugs Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs capacity and cold-chain infrastructure. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with integrated biologics manufacturing, mid-cap specialists focused on transplant therapy franchises, and emerging biosimilar producers targeting cost-sensitive markets. Strategic moves center on M&A to acquire aseptic processing expertise and capacity expansion in validated sterile injectable facilities.
Within the multinational tier, Novartis AG and Bristol-Myers Squibb Company exemplify archetypes of transplant heritage anchoring and integrated biologics manufacturing respectively. Pfizer Inc. occupies a position defined by global distribution network scale for infused formulations. These three entities represent distinct competitive vectors: calcineurin inhibitor supply continuity, monoclonal antibody platform breadth, and cold-chain logistics penetration.
| Leading Market Players |
|---|
| Novartis AG |
| Astellas Pharma |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Sanofi |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
Monoclonal antibody displacement of calcineurin inhibitors in maintenance therapy simultaneously redraws supply geography toward refrigerated biologics corridors and compresses pricing power in oral generic strongholds. This substitution dynamic privileges manufacturers with validated cold-chain infrastructure while eroding margins for legacy small-molecule producers concentrated in Indian and Brazilian outpatient channels.
Pricing Analysis
Certification level creates the primary spread between FDA-validated sterile injectables and CDSCO-registered oral generics. Three-tier pricing structure across premium biologics, standard originator small molecules, and economy generics reflects REMS compliance costs and cold-chain capital intensity. Pricing pressure stems from biosimilar erosion in European tender markets for legacy calcineurin inhibitors. Hospital systems exhibit lowest price sensitivity due to bundled procurement protocols, while retail pharmacies in emerging markets drive aggressive generic substitution.
Supply Chain Analysis
Just-in-time inventory strategies dominate biologics distribution due to protein stability constraints at 2°C to 8°C, contrasting with strategic stockpiling of oral maintenance therapies in emerging markets. Manufacturing concentrates in the United States, Germany, and Japan for sterile injectables, with India and China anchoring API production for generic formulations. Supply chains rest on mammalian cell culture capacity and specialized aseptic filling infrastructure. Single-source vulnerability concentrates in contract manufacturing organizations with validated cold-chain credentials. Distribution runs through integrated specialty pharmacy networks for infused formulations and fragmented retail channels for oral tablets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through transplant center consolidation across United States academic medical systems, compressing vendor counts and privileging manufacturers with direct contracting capabilities.
For Market Incumbents: Shield calcineurin inhibitor revenue pools through backward integration into API manufacturing and exclusive formulary partnerships with Cleveland Clinic-scale integrated delivery networks. Prioritize REMS compliance infrastructure as a defensive moat against emerging biologics entrants lacking pharmacovigilance scale. Capacity expansion in validated sterile injectable facilities preserves supply continuity advantages. For New Entrants and Emerging Players: Differentiate on subcutaneous formulation convenience for rheumatology and gastroenterology outpatient settings, where patient self-administration reduces infusion center dependency. Brazil's underpenetrated gastroenterology clinics and India's cost-sensitive rheumatology markets offer the most penetrable entry points. Pursue ANVISA and CDSCO biosimilar pathways as lower-regulatory-barrier alternatives to FDA BLA submissions. For Investors and Strategic Acquirers: EMA's ATMP framework acceleration reshapes the acquisition landscape toward cell-based immunosuppressant platforms with expedited European market access. Long-term viability centers on capabilities spanning both transplant and autoimmune indications with integrated real-world evidence generation. Target contract manufacturing organizations with validated cold-chain credentials and aseptic processing expertise. Watch FDA biosimilar interchangeability determinations as the signal indicating margin compression velocity for originator biologics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA ATMP designation accelerates European market entry for cell-based immunosuppressants. |
| Manufacturing Scale-Up | Validated sterile injectable capacity concentrates procurement leverage among cold-chain operators. |
| Licensing Agreement | Subcutaneous formulation rights unlock rheumatology clinic expansion beyond transplant centers. |
| Pipeline Diversification | Autoimmune indication expansion reduces revenue concentration in kidney transplant volumes. |
| Strategic Partnership | Integrated delivery network contracts secure bundled induction-maintenance procurement commitments. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs leads, formulary directors at transplant centers, hospital procurement managers, and payer access specialists anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation constrain estimate variance across the analysis window.
Sensitivity analysis around biosimilar erosion timelines and cell therapy competition intensity tests forecast robustness across drug class, indication, formulation, and end-user segmentation dimensions. CAGRs derive from logarithmic interpolation between base and terminal year value estimates. Modeled inputs include transplant procedure volumes by organ type, monoclonal antibody adoption curves in autoimmune indications, and regulatory approval velocity differentials across FDA, EMA, and PMDA pathways.
Material uncertainties — biosimilar interchangeability determinations, cell therapy regulatory reclassifications, and transplant center consolidation velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement stability and cold-chain infrastructure expansion. Revision becomes warranted when biosimilar market penetration in calcineurin inhibitors crosses critical formulary adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market