
 Omeprazole Market | 2026-2036
Omeprazole Market Size, Share, and Industry Trends Forecast 2026-2036
Omeprazole Market Analysis
Hospital procurement of omeprazole is broadening toward outpatient and homecare channels as payors push for reduced readmission costs. AstraZeneca leverages its original formulation heritage to sustain brand loyalty in prescription segments. Teva Pharmaceutical anchors the generic landscape through manufacturing scale across multiple dosage forms. Perrigo Company competes aggressively in private-label OTC distribution through retail pharmacy relationships.
Omeprazole is a proton pump inhibitor that irreversibly blocks the hydrogen-potassium ATPase enzyme in gastric parietal cells, suppressing acid secretion with typical bioavailability of 30-40% due to first-pass hepatic metabolism; it serves primarily to treat acid-related disorders of the upper gastrointestinal tract. Tablets dominate volume production due to stability and cost efficiency, though capsules retain preference in pediatric and geriatric compliance packaging. Injectable formulations command premium positioning in acute care settings where oral administration is contraindicated. Distribution through hospital pharmacies still captures the highest margin pools for sterile presentations, while online pharmacies are capturing script volume from chronic therapy refills.
FDA bioequivalence requirements govern generic substitution and directly determine which manufacturers qualify for first-to-file exclusivity and subsequent market access. EPA environmental standards affect active pharmaceutical ingredient waste discharge from bulk manufacturing facilities, particularly in high-volume production zones. EMA's evolving guidelines on nitrosamine impurity limits are forcing reformulation investments across European supply chains. Stakeholders must monitor regulatory divergence between FDA and EMA impurity thresholds when allocating capacity across geographic markets.
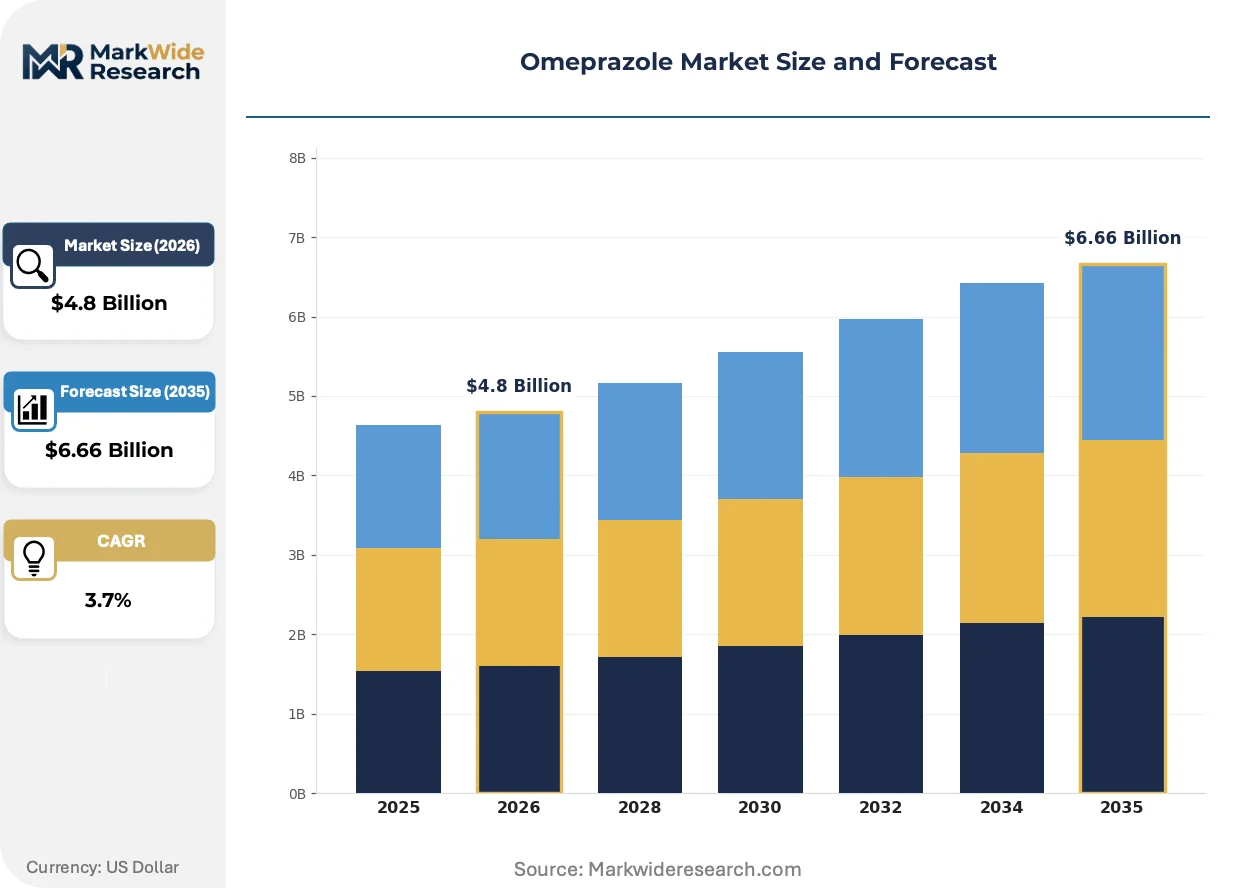
Market Dynamics
FDA bioequivalence standards for proton pump inhibitors are compressing manufacturing margins while forcing capital redeployment toward nitrosamine-compliant reformulation capacity.
Growth Catalysts
- Aging Demographics:Self-medication for gastroesophageal reflux disease expands OTC volumes in populations over 65 across the United States and Western Europe.
- REACH Compliance:ECHA substance registration requirements are consolidating European API sourcing toward certified bulk manufacturers with verified impurity controls.
- Homecare Migration:Hospital discharge protocols now mandate outpatient acid suppression therapy, extending script duration beyond acute episodes.
Market Restraints
- API Concentration:Bulk omeprazole production concentrates in high-volume zones of India and China, exposing supply chains to single-country disruption.
- Substitution Pressure:Esomeprazole and lansoprazole formulations capture switching patients through perceived efficacy advantages in refractory cases.
- First-Pass Metabolism:Omeprazole's 30-40% bioavailability limits formulation innovation compared to newer PPIs with improved pharmacokinetic profiles.
Strategic Opportunities
- Pediatric Formulations:Orally disintegrating tablets and taste-masked granules address unmet compliance needs in children aged 2-12 with erosive esophagitis.
- Online Pharmacy Integration:Chronic therapy refills through telehealth platforms bypass traditional retail pharmacy intermediaries in direct-to-patient models.
- EMA Nitrosamine Guidelines:Reformulation investments to meet tightened NDMA limits create first-mover advantages for manufacturers with validated analytical methods.
Industry Challenges
- Analytical Talent Scarcity:Nitrosamine testing protocols require mass spectrometry specialists that contract laboratories struggle to recruit at competitive rates.
- Legacy Equipment Retrofit:Existing tablet presses and coating lines demand modification to prevent cross-contamination during multi-PPI campaign manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omeprazole Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Powder Therapy Area: Gastroesophageal Reflux Disease, Peptic Ulcer Disease, Zollinger-Ellison Syndrome, Erosive Esophagitis Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Clinics End User: Hospitals, Outpatient Clinics, Homecare, Pharmacies |
| Companies Covered | AstraZeneca, Boehringer Ingelheim, Perrigo Company, Azurity Pharma, Salix Pharmaceuticals, Teva Pharmaceutical, Pfizer, Bayer AG, Cipla Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omeprazole Market Emerging Trajectories
Formulation science and distribution architecture are diverging sharply as manufacturers split investment between compliance-heavy prescription segments and margin-optimized OTC channels.
Delayed-release pellet technology is absorbing manufacturing investment as the dominant approach for protecting omeprazole from gastric acid degradation. Contract development organizations in the United States and Germany are scaling multi-particulate capacity to serve both branded and private-label clients. This absorption is compressing demand for conventional enteric-coated tablets in premium positioning while expanding accessible price tiers.
EMA's evolving nitrosamine impurity limits are forcing reformulation investments across European supply chains. Manufacturers must validate alternative synthetic routes or implement costly purification steps to meet sub-ppm thresholds for N-nitrosodimethylamine. German and Italian API facilities are prioritizing process analytical technology to demonstrate real-time impurity control during regulatory inspections.
Retail pharmacy chains are consolidating private-label purchasing through direct sourcing agreements that disintermediate traditional wholesale distributors. CVS Health and Walgreens Boots Alliance now specify formulation standards and packaging formats at contract inception rather than accepting manufacturer defaults. This concentration is most visible in the United States, where pharmacy benefit structures reward formulary placement through volume guarantees rather than clinical differentiation.
Omeprazole Market Segmentation
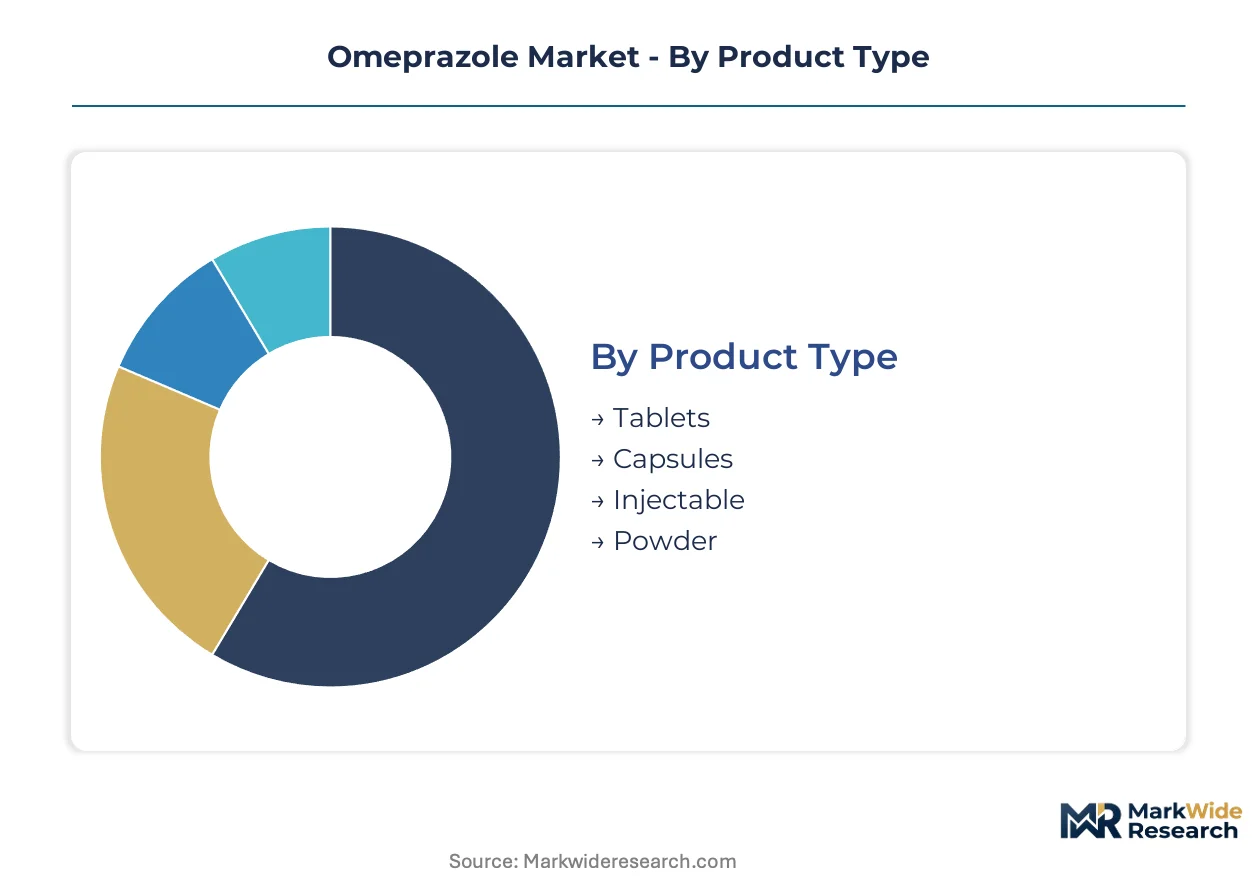
Formulation stability and route of administration dictate procurement patterns across acute and chronic care settings. Distribution channel selection hinges on reimbursement structures and patient compliance requirements rather than pure price competition.
Product Type:
Cost tier determines manufacturing investment allocation, with premium sterile presentations absorbing capital while commodity oral forms compete on scale.
- Tablets:Enteric-coated compressed formulations dominate production volumes due to stability advantages and coating-line efficiency. United States retail pharmacy chains specify delayed-release pellet specifications at contract inception, compressing margins for non-compliant manufacturers.
- Capsules:Gelatin or HPMC shells containing enteric-coated granules enable dose flexibility and pediatric compliance packaging. Western European demand concentrates in geriatric populations where swallowing difficulty drives preference for sprinkle-capable presentations.
- Injectable:Sterile lyophilized powder for IV administration commands acute care premium positioning.
- Powder:Bulk API or reconstitutable sachets serve compounding pharmacies and institutional preparation.
Volume sits with Tablets; growth tilts toward Capsules.
Therapy Area:
Application severity determines reimbursement tier and therapy duration, separating maintenance prescriptions from acute intervention protocols.
- Gastroesophageal Reflux Disease:Chronic acid suppression for erosive and non-erosive variants represents the dominant prescription volume. United States direct-to-consumer advertising sustains branded preference despite generic substitution pressure.
- Peptic Ulcer Disease:Eradication regimens combining omeprazole with antibiotics face duration compression from Helicobacter pylori resistance patterns.
- Zollinger-Ellison Syndrome:Rare gastrinoma-driven hypersecretion requires high-dose maintenance.
- Erosive Esophagitis:Mucosal healing indications with endoscopic confirmation.
Prescription volume concentrates in GERD maintenance; steepest expansion trajectory appears in erosive esophagitis diagnosis protocols.
Distribution Channel:
Customer type fragmentation separates institutional procurement with formulary constraints from direct-to-consumer accessibility.
- Hospital Pharmacies:Captive dispensing within acute care institutions with 340B pricing exposure. Margin pools concentrate in sterile injectable procurement where FDA cGMP compliance barriers limit vendor count.
- Retail Pharmacies:Chain-operated storefronts and independent dispensaries with PBM formulary integration. CVS Health and Walgreens Boots Alliance private-label consolidation disintermediates wholesale distributors.
- Online Pharmacies:Telehealth-integrated chronic therapy refills bypassing traditional intermediaries.
- Clinics:Physician-dispensed samples and short-course initiation packs.
Script volume remains with Hospital Pharmacies; share gain tilts toward Online Pharmacies.
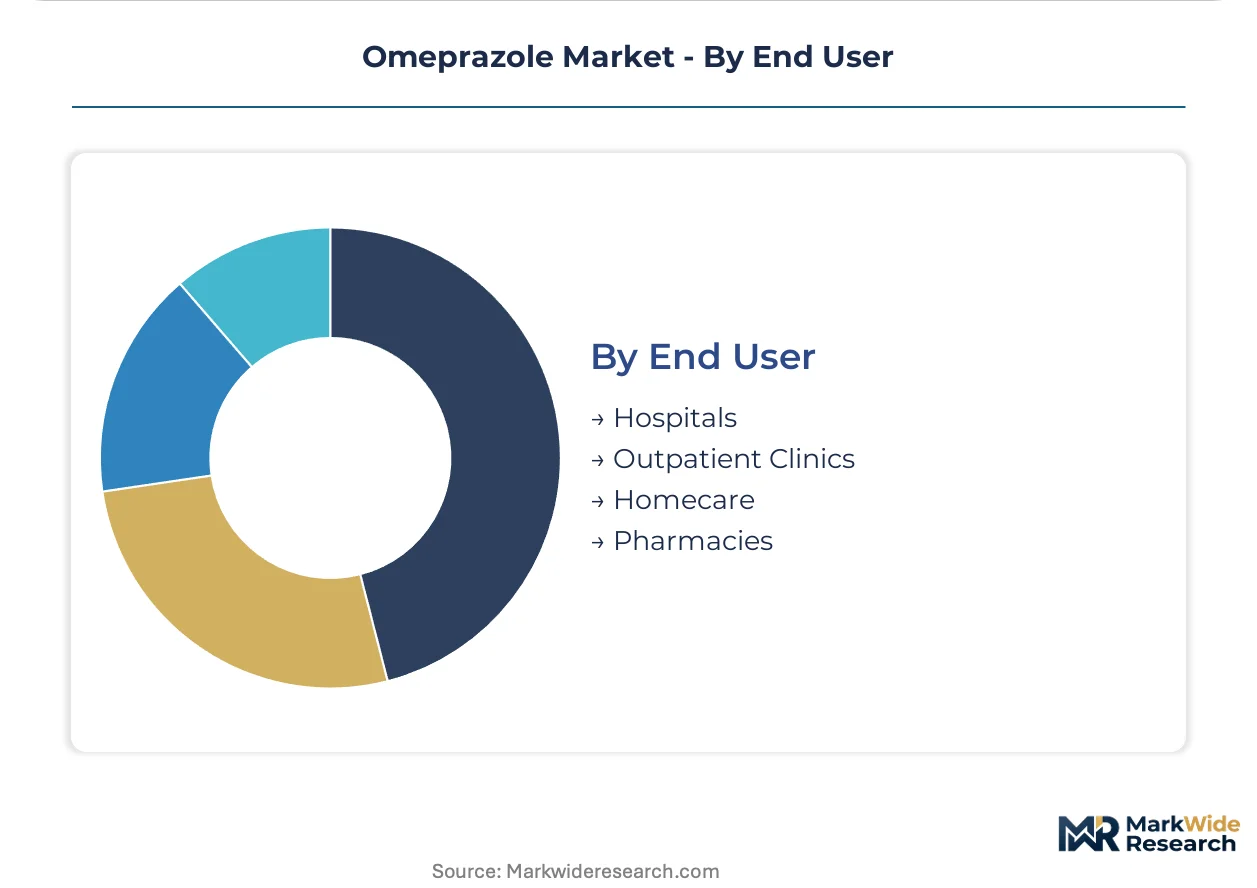
End User:
Maturity of care setting determines administration supervision requirements and adverse event liability exposure.
- Hospitals:Inpatient acid suppression for stress ulcer prophylaxis and active bleeding management. Discharge protocol mandates extend script duration into outpatient channels.
- Outpatient Clinics:Specialist-directed therapy initiation with endoscopic monitoring.
- Homecare:Post-acute oral therapy with nurse-administered injectable exceptions.
- Pharmacies:Self-selection OTC environment with pharmacist consultation requirements.
Utilization concentrates in Hospitals; patient migration accelerates fastest toward Homecare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Omeprazole API synthesis concentrates in Indian and Chinese bulk manufacturing zones, while formulation demand clusters in Western markets with aging demographics and pharmacy benefit structures that sustain chronic therapy volumes.
United States
Direct-to-consumer advertising and Medicare Part D coverage sustain branded and generic prescription volumes for GERD maintenance. FDA bioequivalence standards for proton pump inhibitors govern generic substitution eligibility and first-to-file exclusivity awards. New Jersey and North Carolina host sterile injectable manufacturing facilities serving hospital procurement networks.
Germany
REACH compliance requirements and EMA nitrosamine impurity limits are consolidating API sourcing toward certified bulk manufacturers with validated analytical controls. ECHA substance registration mandates favor established suppliers with verified impurity documentation. Frankfurt and Munich anchor formulation science clusters developing multi-particulate delayed-release technologies.
India
Domestic consumption for acid-related disorders expands with urbanization and dietary shifts, while bulk API exports supply global generic formulation networks. CDSCO manufacturing facility inspections determine export eligibility to regulated markets. Hyderabad and Ahmedabad concentrate active pharmaceutical ingredient production with integrated fermentation and chemical synthesis capabilities.
China
NMPA environmental compliance standards and dual carbon goals are reshaping bulk manufacturing investment toward lower-emission process technologies. MIIT industrial policy favors consolidated production at scale-compliant facilities. Zhejiang and Jiangsu provinces host high-volume omeprazole intermediate and API manufacturing with wastewater treatment infrastructure investments.
United Kingdom
Community pharmacy OTC self-medication for acid reflux expands as GP appointment access constraints push minor ailment management to retail channels. MHRA post-Brexit regulatory divergence from EMA creates parallel submission requirements for market access. Slough and Liverpool host distribution hubs serving retail pharmacy chain private-label sourcing.
Omeprazole Market Vendor Landscape
Top-tier vendors anchor prescription and hospital segments through formulation heritage and sterile manufacturing capabilities, while mid-tier generics and private-label specialists compete on scale and retail pharmacy relationships. The market structure separates originator-branded positions from high-volume generic substitution and OTC self-selection channels. Three archetypes dominate: legacy innovators with original formulation credibility, integrated generics manufacturers with multi-dosage form scale, and private-label distributors with retail chain consolidation leverage. Competitive moves center on nitrosamine-compliant reformulation investments and direct sourcing agreements that disintermediate wholesale distribution.
Among legacy innovators, AstraZeneca occupies a position representing original proton pump inhibitor formulation heritage, while Pfizer exemplifies diversified pharmaceutical scale spanning prescription and consumer health segments. Teva Pharmaceutical anchors the integrated generics archetype with manufacturing breadth across dosage forms. These three companies illustrate the competitive spectrum from branded prescription defense to high-volume generic supply and private-label OTC distribution.
| Leading Market Players |
|---|
| AstraZeneca |
| Boehringer Ingelheim |
| Perrigo Company |
| Azurity Pharma |
| Salix Pharmaceuticals |
| Teva Pharmaceutical |
| Pfizer |
| Bayer AG |
| Cipla Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between sterile injectable and commodity oral omeprazole manifests in both pricing power and supply chain configuration. FDA cGMP compliance for sterile manufacturing creates tiered access where validated facilities command premium positioning while non-compliant producers compete on raw material arbitrage.
Pricing Analysis
Lead-time-driven pricing separates hospital procurement contracts from spot API purchases in bulk markets. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence certification, EMA nitrosamine compliance status, and volume scale commitments. Pricing pressure stems from generic substitution acceleration as esomeprazole and lansoprazole capture switching patients. Hospital procurement committees demonstrate lowest price sensitivity due to formulary lock-in, while retail pharmacy chains negotiate aggressively on private-label OTC volumes.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled omeprazole batches remain underdeveloped, creating compliance liabilities for retail pharmacies with aging inventory. API synthesis concentrates in India, China, and selected Italian facilities with integrated fermentation capabilities. Raw material dependencies include 2-mercapto-5-methoxybenzimidazole, pyridine derivatives, and specialized enteric coating polymers. Single-country vulnerability in Indian and Chinese bulk manufacturing exposes formulation networks to disruption. Distribution runs through wholesale distributors for hospital networks and direct sourcing agreements for retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Omeprazole supply is tightening around nitrosamine-compliant reformulation capacity, with EMA-validated analytical methods propping pricing for certified manufacturers.
For Market Incumbents: Anticipate esomeprazole and lansoprazole substitution pressure by accelerating pediatric formulation development and securing direct sourcing agreements with CVS Health and Walgreens Boots Alliance. Vertical integration into multi-particulate delayed-release technology protects margin pools as retail chains consolidate purchasing power. For New Entrants and Emerging Players: Launch via telehealth-integrated online pharmacy channels to bypass entrenched retail intermediaries. Pediatric orally disintegrating tablets and taste-masked granules for children aged 2-12 represent the most penetrable white space, with compounding pharmacy partnerships offering lower regulatory barriers than FDA abbreviated new drug application pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in private-label OTC specialists with retail chain relationships and sterile injectable manufacturers with hospital formulary placement. Long-term viability hinges on nitrosamine testing infrastructure and validated analytical methods. Watch EMA-FDA regulatory divergence on impurity thresholds as the critical inflection signal for capacity allocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Nitrosamine-Compliant Reformulation Investment | EMA sub-ppm NDMA thresholds force validated alternative synthetic routes at German and Italian API facilities. |
| Pediatric Formulation Development | Orally disintegrating tablets address unmet compliance needs in children with erosive esophagitis. |
| Direct Sourcing Agreement Consolidation | CVS Health and Walgreens Boots Alliance now specify formulation standards at contract inception. |
| Multi-Particulate Capacity Expansion | Contract development organizations in the United States and Germany scale delayed-release pellet technology. |
| Telehealth Platform Integration | Chronic therapy refills bypass traditional retail pharmacy intermediaries in direct-to-patient models. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this omeprazole market assessment. Primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and API manufacturing executives combined with FDA 483 observations, EMA inspection reports, and CDSCO facility approvals. Bottom-up dosage form volume estimates triangulated against top-down therapy area spending projections from national reimbursement databases.
Data-stream reconciliation across prescription audit feeds, hospital procurement databases, and retail pharmacy chain inventory disclosures shaped the analytical framework. Segmentation dimensions modeled include formulation type, therapy severity, distribution channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of generic substitution rates, aging demographic projections, and outpatient migration patterns. Forecast inputs incorporated FDA bioequivalence approval timelines and EMA nitrosamine guideline implementation trajectories.
The model assumes a particular technology adoption path for delayed-release pellet manufacturing; alternative pathways for conventional enteric-coated tablet preservation would alter the capacity investment outlook. Forecasts reflect assumptions around regulatory harmonization stability and API sourcing concentration. Practitioners should monitor EMA-FDA impurity threshold divergence, CDSCO inspection enforcement intensity, and retail pharmacy chain consolidation velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Global BHK Rabies Vaccine Market