
 Global Hepatitis Diagnostic Test Market | 2026-2036
Global Hepatitis Diagnostic Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hepatitis Diagnostic Test Market Foresight
Aftermarket service revenue for instrument calibration and reagent supply contracts is rewriting profitability structures across the hepatitis diagnostics value chain. Danaher Corporation leverages its Beckman Coulter life sciences platform to sustain recurring consumable revenue in clinical laboratories worldwide. Abbott Laboratories anchors its position through automated immunoassay systems that dominate high-throughput blood bank screening workflows. QIAGEN N.V. specializes in molecular sample preparation technologies that extend its footprint into PCR-based hepatitis viral load monitoring.
Hepatitis diagnostic tests encompass serological and molecular assays designed to detect hepatitis A, B, C, D, and E infections through antibody, antigen, or nucleic acid identification, with sensitivity thresholds typically reaching 95% or higher for FDA-cleared immunoassays. These tests serve the dual commercial purpose of enabling clinical treatment decisions and ensuring blood supply safety through mandatory donor screening protocols. PCR assays represent the fastest-growing product category as healthcare systems shift from antibody-based screening to direct viral detection for patient management. Blood screening applications command the largest revenue share among end uses, while molecular diagnostics technology captures expanding margins as laboratories replace legacy serological methods with automated nucleic acid testing platforms.
The FDA regulates hepatitis diagnostic tests as Class II or Class III medical devices requiring premarket notification or approval, while the EMA oversees CE marking under the In Vitro Diagnostic Medical Devices Regulation across European member states. WHO prequalification standards shape market access for manufacturers seeking procurement contracts in low- and middle-income countries through United Nations agencies and global health initiatives. Stakeholders must monitor evolving regulatory convergence between FDA and EMA nucleic acid testing performance standards, as harmonization would reshape competitive barriers for molecular diagnostic platforms seeking multi-jurisdictional commercialization.
Market Dynamics
PCR-based nucleic acid testing is collapsing the traditional serology-to-molecular transition timeline as blood banks and clinical laboratories accelerate platform replacement cycles under tightening FDA and EMA performance standards.
Growth Catalysts
- WHO Prequalification Program:The WHO prequalification pathway for in vitro diagnostics is accelerating technology transfer into low-income settings through United Nations procurement contracts.
- India's National Viral Hepatitis Control Program:Public health agencies and diagnostic centers across India are scaling screening infrastructure under centralized government mandates.
- Nucleic Acid Testing Protocols:Blood banks in the United States are expanding NAT coverage under FDA guidance for donor screening safety.
Market Restraints
- Reagent Supply Concentration:Critical enzymes and primers for PCR workflows concentrate among a narrow base of specialty chemical suppliers in Germany and the United States.
- Instrument Capex Burden:Automated nucleic acid testing platforms require capital commitments that strain mid-tier clinical laboratory budgets.
- CE-IVDR Transition Friction:The European Union's In Vitro Diagnostic Medical Devices Regulation is extending certification timelines and compliance costs for molecular assay manufacturers.
Strategic Opportunities
- Point-of-Care Molecular Convergence:Miniaturized PCR and isothermal amplification technologies are opening decentralized testing in rural India and sub-Saharan Africa.
- Blood Bank Automation Retrofit:High-throughput screening facilities in the United States and Germany are replacing legacy immunoassay systems with integrated NAT-immunoassay workflows.
- Aftermarket Service Contracts:Instrument calibration and reagent supply agreements are capturing recurring revenue streams from installed base expansion.
Industry Challenges
- Molecular Diagnostics Talent Scarcity:Clinical laboratories face shortages of PCR technicians and bioinformatics specialists capable of viral load interpretation.
- Legacy System Integration Complexity:Serology-based laboratory information management systems require costly middleware upgrades to accommodate NAT data streams.
- Harmonization Timeline Uncertainty:Divergent FDA and EMA nucleic acid testing performance standards are complicating multi-jurisdictional product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hepatitis Diagnostic Test Market |
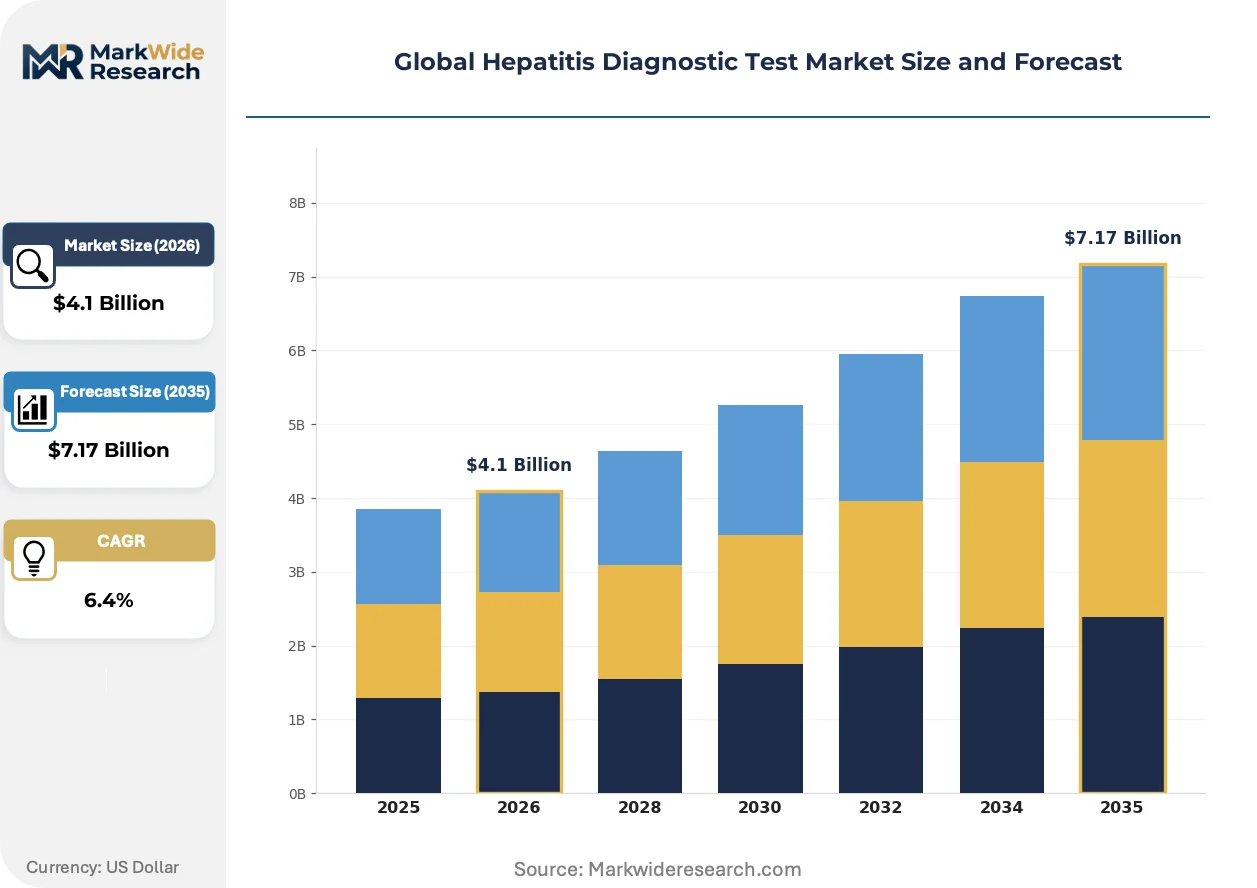
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Rapid Diagnostic Tests, PCR Assays, Western Blot, Chemiluminescence Immunoassay Application: Blood Screening, Organ Transplantation Screening, Prenatal Testing, Liver Disease Diagnosis, Epidemiological Surveillance End User: Clinical Laboratories, Blood Banks, Research Institutes, Diagnostic Centers, Public Health Agencies Technology: Immunoassay, Molecular Diagnostics, Serological Testing, Biosensor Technology, Microfluidics |
| Companies Covered | Danaher Corporation, Thermo Fisher Scientific Inc., Roche Diagnostics, QIAGEN N.V., Bio-Rad Laboratories Inc., Abbott Laboratories, bioMérieux SA, DiaSorin S.p.A., Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hepatitis Diagnostic Test Market Shifts & Advancements
Automated sample-to-answer platforms are compressing turnaround times while regulatory pressure on sensitivity thresholds intensifies platform performance requirements across major jurisdictions.
Next-generation sequencing is collapsing the cost structure for hepatitis viral genotyping and resistance profiling as reference laboratories in the United States and Germany adopt hybridization-capture workflows. Academic medical centers are replacing Sanger sequencing for outbreak investigation and treatment monitoring. The technology is collapsing the distinction between research-grade and clinical-grade viral characterization.
The FDA's nucleic acid testing guidance for donor screening is tightening analytical sensitivity requirements for hepatitis B virus detection. Blood collection organizations must validate lower limits of detection or face screening protocol restrictions. High-throughput blood banks in the United States are responding with dual-target PCR assays and automated nucleic acid extraction systems.
Consolidated procurement through national health programs is displacing fragmented hospital-level purchasing in India and Brazil. Centralized tenders for hepatitis screening reagents are concentrating supplier relationships around WHO-prequalified manufacturers. India's National Viral Hepatitis Control Program exemplifies this shift, with state diagnostic centers standardizing on approved assay menus through federal procurement frameworks.
Global Hepatitis Diagnostic Test Market Segmentation
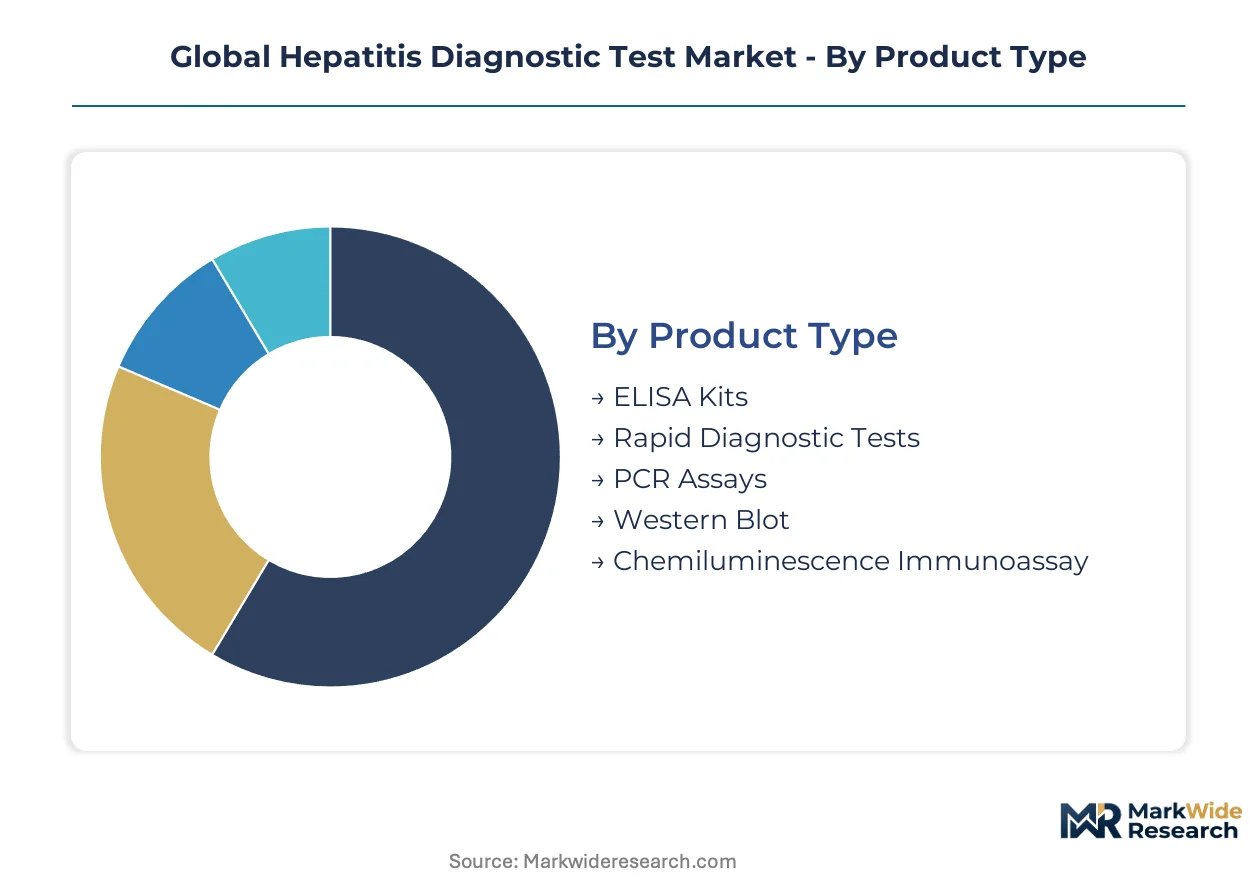
Hepatitis diagnostic test segmentation reflects a market in transition from mature serological platforms to emerging molecular technologies. Product portfolios span legacy immunoassay systems with installed base inertia and next-generation nucleic acid platforms capturing replacement cycles. Understanding segment boundaries clarifies where capital expenditure concentrates versus where consumable revenue accumulates.
Product Type:
Mature serological formats dominate installed base volume while emerging molecular platforms command replacement investment and pricing premiums.
- PCR Assays:Nucleic acid amplification platforms detect viral RNA and DNA with analytical sensitivity reaching single-digit IU/mL. Blood banks in the United States are accelerating NAT adoption under FDA donor screening guidance, displacing antibody-only workflows. Dual-target designs for hepatitis B surface antigen and core gene regions satisfy emerging regulatory stringency.
- ELISA Kits:Enzyme-linked immunosorbent assays remain the workhorse for antibody and antigen detection in resource-constrained settings. India's National Viral Hepatitis Control Program deploys standardized ELISA menus through centralized state diagnostic centers. Cost per test and minimal equipment requirements sustain relevance in high-volume screening programs.
- Rapid Diagnostic Tests:Lateral flow immunoassays enable point-of-care antibody detection without laboratory infrastructure.
- Western Blot:Confirmatory serological testing resolves indeterminate ELISA results in reference laboratory settings.
- Chemiluminescence Immunoassay:Automated high-throughput platforms integrate magnetic particle separation with signal amplification for blood bank screening.
ELISA Kits retain volume leadership; PCR Assays hold the steepest expansion curve.
Application:
Application segmentation tracks divergent regulatory intensity and reimbursement logic across clinical versus public health use cases.
- Blood Screening:Mandatory donor testing protocols command the largest revenue share through high-throughput automation and continuous reagent consumption. FDA nucleic acid testing guidance for HBV detection is tightening analytical sensitivity thresholds, forcing platform upgrades. Blood collection organizations in Germany and the United States validate lower limits of detection to maintain screening protocol authorization.
- Liver Disease Diagnosis:Patient management applications drive viral load quantification and genotyping demand in hepatology clinics. Academic medical centers adopt next-generation sequencing for resistance profiling and treatment monitoring. The technology boundary between research-grade and clinical-grade viral characterization is dissolving.
- Organ Transplantation Screening:Pre-transplant donor and recipient testing prevents hepatitis transmission in solid organ and stem cell procedures.
- Prenatal Testing:Maternal screening protocols detect hepatitis B surface antigen to guide neonatal prophylaxis decisions.
- Epidemiological Surveillance:Population-level prevalence studies and outbreak investigation rely on standardized serological and molecular assay panels.
Blood Screening captures the dominant revenue pool; Liver Disease Diagnosis is climbing the fastest as treatment monitoring extends testing frequency.
End User:
End user segmentation reveals concentration of capital investment versus decentralized volume expansion.
- Clinical Laboratories:Hospital-based and independent reference labs balance high-throughput automation with specialized molecular testing menus. Integration of nucleic acid testing data streams with legacy laboratory information management systems requires costly middleware upgrades. Talent scarcity for PCR technicians and bioinformatics specialists constrains operational expansion.
- Blood Banks:Collection organizations operate under the most stringent regulatory surveillance with continuous screening mandates. Automated sample-to-answer platforms compress turnaround times while instrument calibration and reagent supply contracts generate recurring revenue concentration.
- Diagnostic Centers:India's state-level public health infrastructure scales screening access under federal procurement frameworks.
- Public Health Agencies:National programs standardize assay menus through WHO-prequalified manufacturer relationships.
- Research Institutes:Academic centers drive adoption of next-generation sequencing for viral genotyping and resistance profiling.
Blood Banks anchor premium pricing; Diagnostic Centers in India are gaining share fastest through centralized government tenders.
Technology:
Technology segmentation maps the displacement curve from serological to molecular detection paradigms.
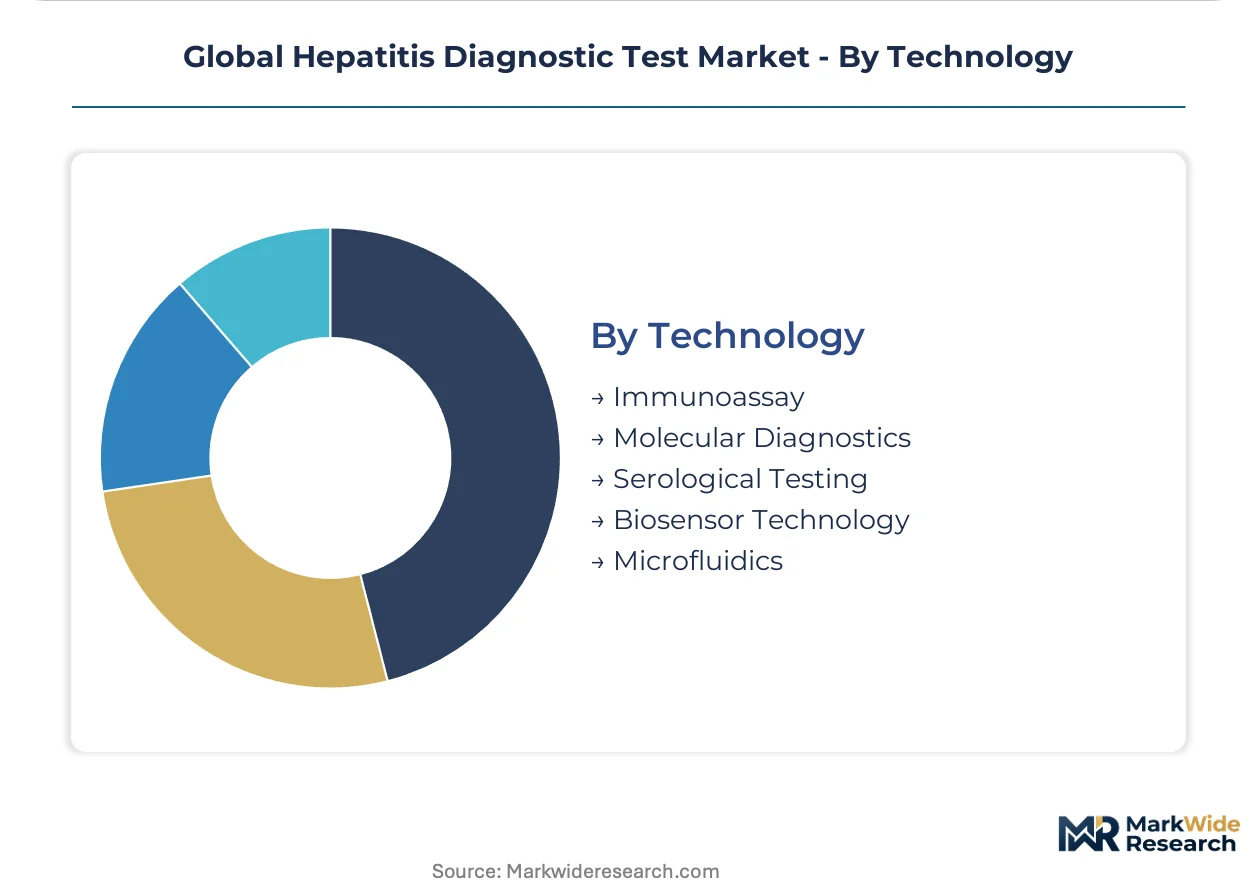
- Molecular Diagnostics:PCR and isothermal amplification platforms represent the technology layer capturing margin expansion as laboratories replace legacy methods. Miniaturized point-of-care molecular devices are opening decentralized testing in rural India and sub-Saharan Africa. WHO prequalification pathways accelerate technology transfer into low-income procurement channels.
- Immunoassay:Enzyme and chemiluminescence-based antibody and antigen detection retains massive installed base and screening protocol standardization. Automated immunoassay systems dominate high-throughput blood bank workflows in the United States and Germany.
- Serological Testing:Traditional agglutination and precipitation methods persist in resource-limited settings with minimal infrastructure.
- Biosensor Technology:Electrochemical and optical transducers enable label-free detection with reduced sample preparation requirements.
- Microfluidics:Lab-on-chip architectures integrate sample preparation, amplification, and detection for point-of-care deployment.
Immunoassay retains installed base dominance; Molecular Diagnostics is expanding most quickly through platform replacement cycles and sensitivity regulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement channels. India's state diagnostic centers negotiate bulk reagent contracts under federal tenders, while United States blood banks absorb premium instrument costs under FDA-mandated screening protocols. Germany's reference laboratories balance both pressures through hybrid automation strategies.
United States
Blood collection organizations drive demand through continuous donor screening mandates. The FDA tightens nucleic acid testing sensitivity thresholds for hepatitis B virus detection, forcing dual-target assay validation. High-throughput facilities in the Chicago and Los Angeles metropolitan areas retrofit legacy immunoassay systems with integrated NAT workflows.
Germany
Academic medical centers and blood services anchor molecular diagnostics procurement. The EMA's CE-IVDR transition extends certification timelines for assay manufacturers seeking European market access. The Rhine-Ruhr and Munich clusters concentrate reference laboratory capacity for viral genotyping and resistance profiling.
India
Centralized government tenders displace fragmented hospital purchasing under the National Viral Hepatitis Control Program. The CDSCO aligns with WHO prequalification standards to accelerate technology transfer into public health infrastructure. State diagnostic centers in Maharashtra and Karnataka scale standardized ELISA and molecular screening menus.
China
Domestic manufacturers capture volume in tier-two and tier-three city hospital networks. The NMPA strengthens nucleic acid testing performance standards for blood bank licensing. The Yangtze River Delta cluster concentrates automated platform assembly and reagent production capacity.
Brazil
Consolidated procurement through the Unified Health System concentrates supplier relationships around prequalified manufacturers. ANVISA harmonizes molecular assay registration requirements with PAHO technical specifications. São Paulo's public health laboratory network anchors regional screening capacity expansion.
Global Hepatitis Diagnostic Test Market Competitive Landscape
Capability concentration sits with molecular technology specialists; scale advantage sits with diversified life sciences conglomerates. The market structures around three tiers: integrated diagnostics platforms with global installed bases, molecular assay specialists with nucleic acid expertise, and regional reagent suppliers capturing tender-driven volume. Strategic moves center on automated platform retrofit contracts and recurring consumable revenue capture through calibration and reagent supply agreements.
Among diversified life sciences conglomerates, Danaher Corporation and Thermo Fisher Scientific occupy positions defined by instrument-installed base scale and aftermarket service penetration. Abbott Laboratories anchors the immunoassay-to-molecular convergence vector through automated screening workflows. QIAGEN N.V. exemplifies the molecular specialist archetype, with sample preparation technologies extending into PCR-based viral load monitoring applications. These three represent distinct competitive positioning strategies without overlapping core capability claims.
| Leading Market Players |
|---|
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Roche Diagnostics |
| QIAGEN N.V. |
| Bio-Rad Laboratories Inc. |
| Abbott Laboratories |
| bioMérieux SA |
| DiaSorin S.p.A. |
| Siemens Healthineers AG |
| Others |
Supply & Pricing Matrix
German specialty chemical suppliers concentrate production of Taq polymerase enzymes and synthetic primers, anchoring cost structures for PCR assay manufacturers and positioning aftermarket service contracts as the dominant margin pool across the hepatitis diagnostics value chain.
Pricing Analysis
Instrument calibration and reagent supply agreements generate lifetime value exceeding initial platform sales by ratios of three-to-one or greater. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared dual-target NAT systems from CE-IVDR transition-grade platforms and WHO-prequalified ELISA menus. Cost compression in mid-tier clinical laboratory budgets is intensifying because instrument capex requirements strain capital allocation committees. Public health agencies in India and Brazil exhibit highest price sensitivity through centralized tender mechanisms, while United States blood banks absorb premium pricing under mandatory screening protocol requirements.
Supply Chain Analysis
Contract manufacturing for molecular diagnostic platforms concentrates with specialized life sciences instrument assemblers in Germany, the United States, and Singapore. Critical enzyme production draws from fermentation facilities in Germany and the United States, while magnetic particle chemistries source from Japanese specialty materials suppliers. Single-source vulnerability in thermostable polymerase supply creates exposure to batch contamination or facility shutdown events. Distribution runs through direct field service organizations for automated platforms and third-party laboratory distributors for consumable reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across point-of-care molecular segments where miniaturized PCR and isothermal amplification technologies are creating addressable niches previously captured by centralized laboratory infrastructure.
For Market Incumbents: Pre-empt platform replacement cycles in high-throughput blood banks by accelerating dual-target assay validation ahead of FDA sensitivity threshold tightening. Secure exclusive reagent supply agreements with state diagnostic centers in India through WHO prequalification alignment. Anchor installed base expansion through integrated NAT-immunoassay workflow retrofits that raise switching costs for blood collection organizations. For New Entrants and Emerging Players: Pursue decentralized testing access in rural India and sub-Saharan Africa via miniaturized point-of-care molecular devices qualifying for WHO prequalification pathways. Target diagnostic centers excluded from centralized federal tenders in Indian states with lower screening penetration. Deploy capital-light distribution partnerships with existing laboratory supply distributors rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated nucleic acid testing platform manufacturing as dual-target assay development and FDA validation timelines extend R&D cycles. Long-term viability over the coming decade favors molecular assay specialists with captive sample preparation technology and established WHO prequalification dossiers. Acquisition target archetype: regional reagent suppliers with tender relationships in Brazil or India and underutilized manufacturing capacity. Signal to monitor: CE-IVDR certification timeline announcements from European molecular assay manufacturers as indicator of competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Target Assay Validation | FDA donor screening guidance tightening for hepatitis B virus detection mandates lower analytical sensitivity thresholds. |
| WHO Prequalification Alignment | United Nations procurement contracts accelerate technology transfer into India's National Viral Hepatitis Control Program infrastructure. |
| Point-of-Care Miniaturization | Isothermal amplification devices open decentralized testing access in rural India and sub-Saharan Africa procurement channels. |
| Aftermarket Service Expansion | Instrument calibration and reagent supply agreements capture recurring revenue from installed base growth in blood banks. |
| CE-IVDR Certification Investment | European In Vitro Diagnostic Medical Devices Regulation compliance extends market access timelines for molecular assay manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from clinical laboratory directors, blood bank technical supervisors, diagnostic center procurement managers, and molecular assay R&D leads and refined through secondary validation against FDA 510(k) filings, EMA CE marking databases, WHO prequalification listings, and hospital procurement contract awards. Bottom-up triangulation across instrument installed base estimates and reagent consumption models converged with top-down market sizing from national screening program budgets and blood collection organization expenditure disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume and value outputs through segmentation across product type, application, end user, and technology dimensions with regional regulatory cluster overlays. CAGRs were derived from weighted average growth trajectories across replacement cycle timing, screening program expansion schedules, and sensitivity regulation implementation pacing. Industry-specific forecast inputs incorporated blood bank NAT adoption curves and centralized government tender award patterns.
Sensitivities concentrate around FDA nucleic acid testing guidance revision timing, CE-IVDR certification bottleneck duration, and WHO prequalification pathway throughput capacity. Forecasts reflect documented assumptions regarding screening protocol mandate expansion and instrument replacement cycle acceleration. Quarterly review of regulatory guidance publication schedules and national tender award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Liver Function Tests Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Global Urinalysis Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
At-Home Cancer Testing Market