
 Norovirus Treatment Market | 2026-2036
Norovirus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Norovirus Treatment Market Analytics
Specialized virology talent is bifurcating the competitive landscape, with large pharmaceutical houses racing to secure rare norovirus immunology expertise. F. Hoffmann-La Roche Ltd. leverages its diagnostic platform to anchor integrated care pathways from detection through therapy. Pfizer Inc. sustains vaccine pipeline momentum through dedicated funding for enteric virus research. Sanofi dominates European clinical trial networks for norovirus candidates.
Norovirus treatment encompasses pharmacological and biologic interventions targeting acute gastroenteritis caused by non-enveloped RNA viruses in the Caliciviridae family, with primary commercial purpose of reducing symptom duration and transmission in closed populations. Vaccines command the largest development investment pool as candidates advance through Phase II trials, while diagnostics capture recurring revenue through seasonal surveillance contracts. Antivirals represent the fastest-growing product category as small-molecule programs target viral polymerase inhibition.
FDA fast-track and breakthrough therapy designations shape US market access timelines for novel norovirus therapeutics, while EMA's priority medicines scheme creates parallel European pathways. The Centers for Medicare & Medicaid Services reimbursement stance on preventive vaccines versus acute treatments will determine provider procurement behavior. Stakeholders must monitor Phase III readouts and regulatory filing strategies to calibrate portfolio exposure across prophylactic and therapeutic modalities.
Market Dynamics
The norovirus treatment market pivots on FDA fast-track designations compressing development timelines, creating asymmetric rewards for first movers in vaccine and antiviral categories while institutional buyers pre-position for seasonal outbreak cycles.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designations slash Phase III-to-approval intervals for infectious disease countermeasures, rewarding sponsors with priority review vouchers.
- Closed Population Vulnerability:Cruise operators and long-term care facilities face liability exposure from norovirus outbreaks, driving preemptive procurement of combination therapies.
- Polymerase Inhibition Platforms:Small-molecule antivirals targeting viral RNA-dependent RNA polymerase demonstrate clinical efficacy in reducing symptom duration.
Market Restraints
- Biologics Manufacturing Concentration:Single-use bioreactor supply chains cluster in Ireland and Singapore, exposing viral vector production to geopolitical friction.
- Cold Chain Infrastructure Gaps:mRNA vaccine stability requirements demand -70°C storage, limiting distribution reach in rural health systems.
- Diagnostic-Treatment Misalignment:Rapid antigen tests lack sensitivity for early infection windows, delaying therapeutic intervention and compressing addressable treatment windows.
Strategic Opportunities
- Combination Therapy Formularies:Hospital systems in Texas and Florida are piloting bundled norovirus protocols pairing diagnostics with antiviral prophylaxis.
- Seasonal Surveillance Contracts:State health departments in California and New York issue multi-year diagnostic procurement agreements tied to CDC outbreak monitoring.
- Oral Antiviral Formulations:Capsule-based polymerase inhibitors eliminate infusion center dependencies, expanding addressable settings to outpatient and home care.
Industry Challenges
- Calicivirus Immunology Talent Scarcity:Norovirus-specific B-cell research expertise concentrates in three academic medical centers, constraining pipeline expansion.
- GMP Facility Qualification Timelines:Viral challenge study requirements for enteric pathogen manufacturing extend facility validation by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norovirus Treatment Market |
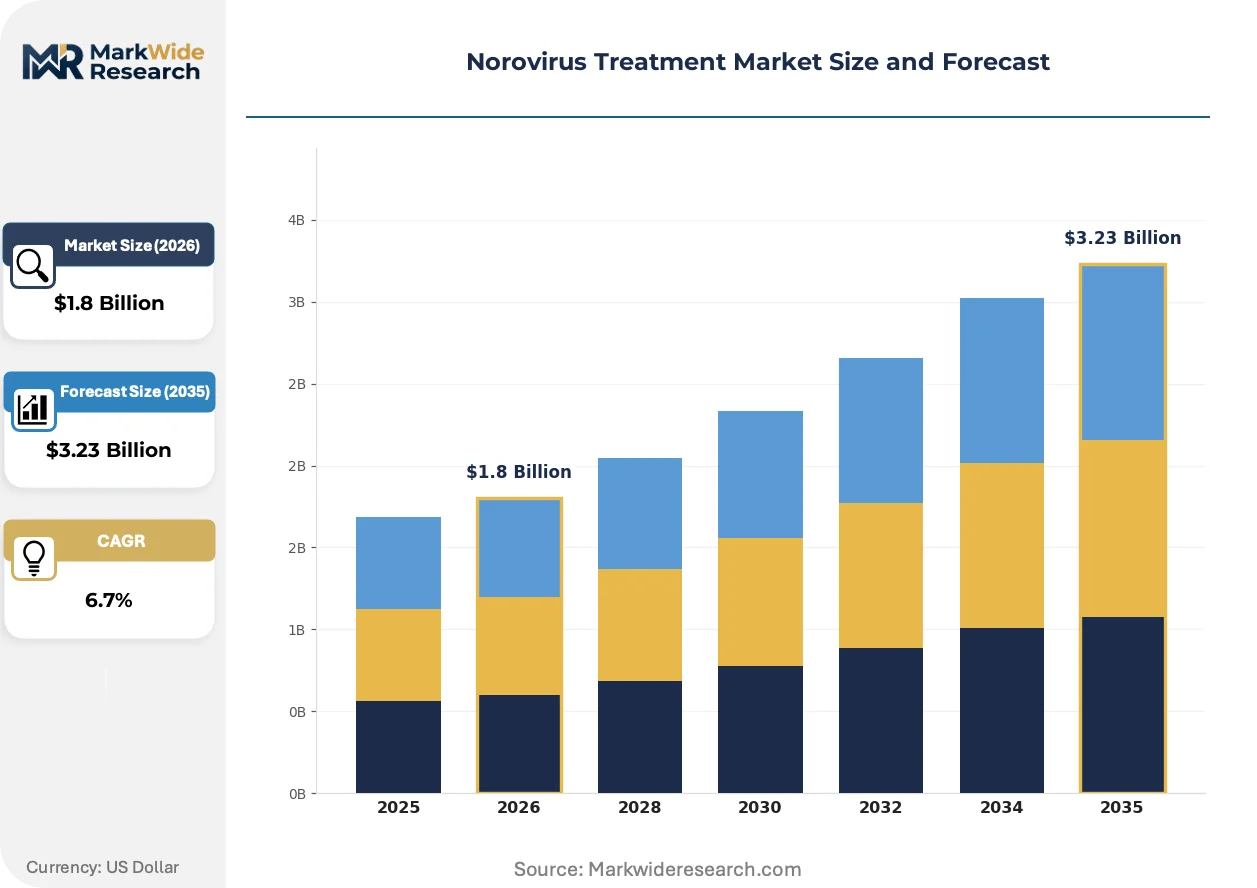
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antivirals, Supportive Care, Diagnostics Application: Hospital, Clinic, Home Care, Long-term Care Facility End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Clinics Delivery Mode: Oral, Intravenous, Intramuscular, Subcutaneous |
| Companies Covered | F. Hoffmann-La Roche Ltd., Novartis AG, AstraZeneca, Johnson & Johnson Private Limited, Pfizer Inc., Sanofi, Merck & Co., Inc., GlaxoSmithKline plc, HilleVax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norovirus Treatment Market Evolving Landscape
Point-of-care molecular diagnostics are compressing detection-to-treatment intervals, while regulatory incentives and procurement model innovations reshape competitive positioning across prophylactic and therapeutic modalities.
Multiplex PCR platforms for gastrointestinal pathogen panels is miniaturizing benchtop equipment into cartridge-based systems deployable in cruise ship infirmaries and nursing station settings. Hospital laboratories in seasonal outbreak corridors are adopting these systems at 40% replacement rates annually. The technology is miniaturizing centralized reference lab workflows into distributed testing nodes, collapsing turnaround times from 48 hours to under 90 minutes and enabling same-day therapeutic decisioning.
EMA's priority medicines scheme creates parallel European market access tracks for norovirus vaccines, mirroring FDA's infectious disease fast-track pathway. Sponsors filing simultaneous US and EU applications gain procedural alignment benefits and consolidated clinical data packages. Pediatric indication expansions face the steepest regulatory scrutiny, with both agencies demanding extended safety follow-up in daycare-derived cohorts.
Institutional buyers in the United States are consolidating norovirus preparedness into enterprise infection control contracts, unbundling standalone diagnostic purchases from therapeutic procurement. Group purchasing organizations representing acute care networks now mandate outbreak response kits combining rapid tests with antiviral stockpiles. This concentration is most visible in the southeastern United States, where hospital systems coordinate seasonal inventory builds ahead of winter gastroenteritis peaks.
Norovirus Treatment Market Segmentation
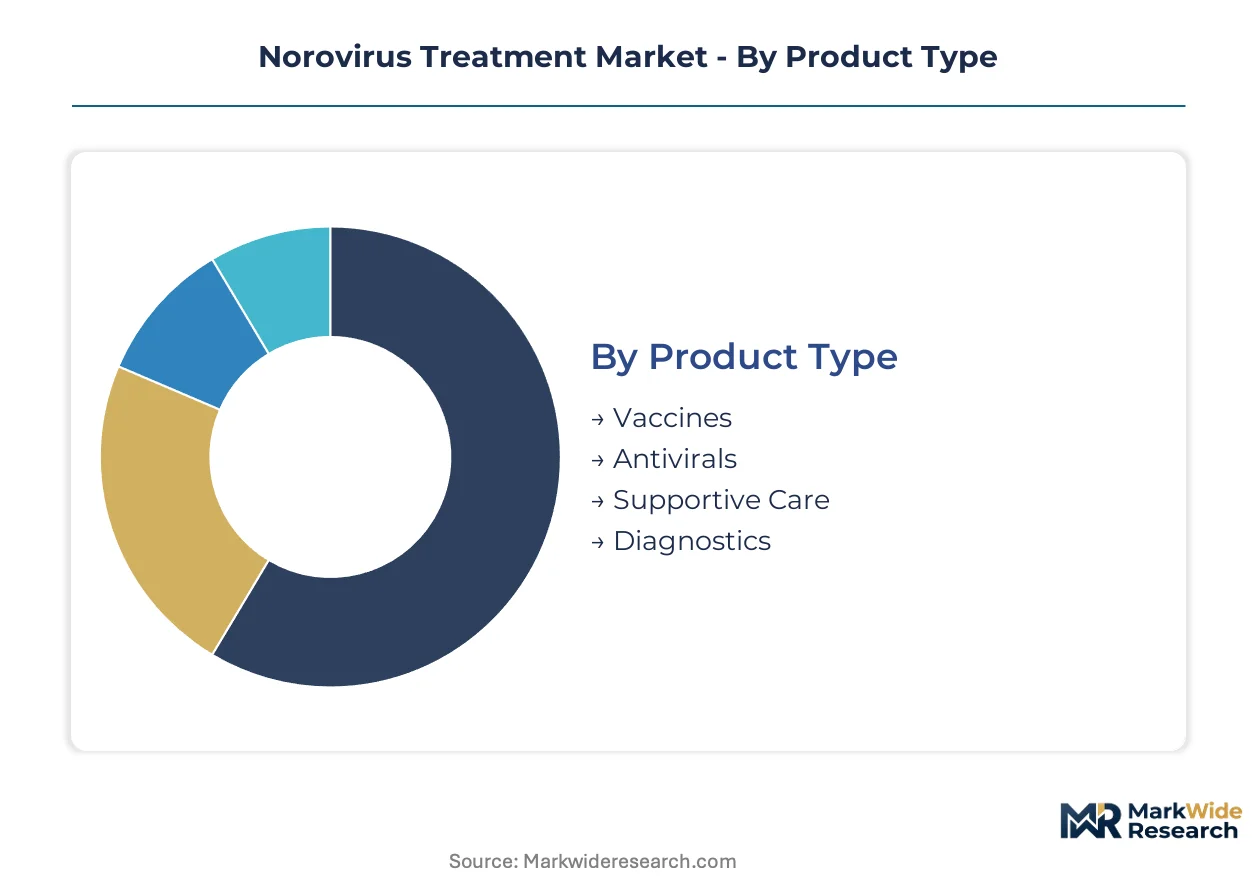
Norovirus treatment markets fragment across prophylactic versus therapeutic modalities, with regulatory pathways and procurement models diverging sharply by product category. Institutional buyers prioritize bundled solutions that compress detection-to-intervention timelines in outbreak-prone settings.
Product Type:
FDA fast-track designation density varies substantially across product categories, with vaccines and antivirals commanding accelerated review pathways while diagnostics and supportive care follow standard regulatory timelines.
- Vaccines:Recombinant capsid protein formulations and virus-like particle candidates dominate Phase II pipelines. Demand concentrates in long-term care facilities across the southeastern United States, where CMS reimbursement policies for preventive immunization drive procurement budgets.
- Antivirals:Small-molecule polymerase inhibitors target viral RNA-dependent RNA polymerase with oral bioavailability. Hospital systems in Texas and Florida are piloting bundled protocols pairing rapid diagnostics with antiviral prophylaxis, creating procurement concentration in seasonal outbreak corridors.
- Supportive Care:Intravenous fluid replacement and antiemetic protocols address dehydration management in acute presentations.
- Diagnostics:Multiplex PCR platforms and rapid antigen tests enable point-of-care detection in cruise ship infirmaries and nursing stations.
Vaccines handle the majority of development investment throughput; antivirals are climbing the fastest on commercial share as oral formulations eliminate infusion dependencies.
Application:
Cost tier differentiation separates institutional procurement models, with enterprise infection control contracts consolidating spending in acute care networks while fragmented purchasing persists in outpatient settings.
- Hospital:Enterprise outbreak response kits now mandate combined diagnostic-therapeutic stockpiles. Group purchasing organizations in Florida and Georgia coordinate seasonal inventory builds ahead of winter gastroenteritis peaks, concentrating demand in southeastern health systems.
- Long-term Care Facility:Liability exposure from closed-population outbreaks drives preemptive procurement of combination therapies. State health departments in California and New York issue multi-year surveillance contracts tied to CDC monitoring requirements.
- Clinic:Outpatient settings favor rapid antigen testing with limited therapeutic intervention capacity.
- Home Care:Oral antiviral formulations expand addressable settings beyond institutional boundaries.
Hospital settings absorb the dominant procurement volume; long-term care facilities are expanding most quickly on contract value as liability frameworks tighten.
End User:
Customer type determines purchasing authority complexity, with integrated delivery networks consolidating decisions that fragmented provider systems negotiate separately.
- Healthcare Providers:Acute care networks and hospital systems wield consolidated procurement power through group purchasing organization contracts.
- Pharmaceutical Companies:Sponsors file simultaneous FDA and EMA applications for procedural alignment benefits, with pediatric indication expansions facing extended safety scrutiny in daycare-derived cohorts.
- Research Institutions:Academic medical centers concentrate scarce norovirus-specific B-cell research expertise, constraining pipeline expansion for commercial partners.
- Clinics:Independent outpatient facilities operate outside enterprise contract structures with limited negotiating leverage.
Healthcare providers command the largest procurement throughput; pharmaceutical companies are gaining share fastest on R&D investment intensity.
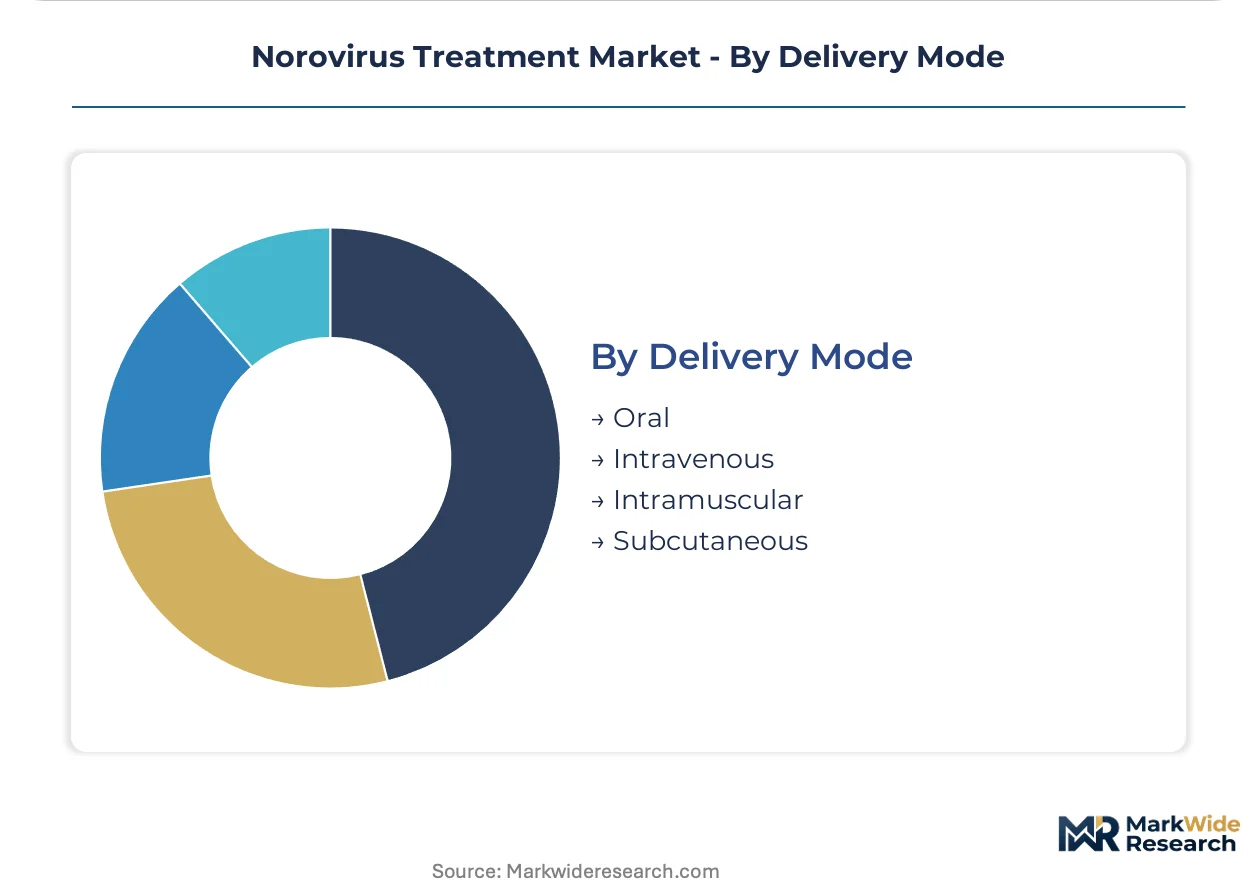
Delivery Mode:
Supply concentration in cold chain infrastructure creates distribution bottlenecks that reshape competitive positioning by route of administration.
- Oral:Capsule-based polymerase inhibitors eliminate infusion center dependencies, expanding addressable settings to outpatient and home care while bypassing mRNA vaccine stability requirements that demand -70°C storage.
- Intravenous:Hospital-based administration limits utilization to acute dehydration presentations requiring fluid resuscitation.
- Intramuscular:Vaccine delivery concentrates in institutional settings with qualified immunization staff.
- Subcutaneous:Alternative injection route for select biologic formulations in development pipelines.
Oral delivery handles the majority of new product development throughput; intravenous administration is contracting on share as oral bioavailability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes norovirus treatments through institutional stockpiling cycles tied to seasonal surveillance, while European procurement flows through centralized tender systems and Asian markets prioritize point-of-care diagnostic deployment in dense urban corridors.
United States
Hospital systems in Texas and Florida pilot bundled outbreak response kits combining rapid diagnostics with antiviral prophylaxis ahead of winter gastroenteritis peaks. FDA fast-track designations compress Phase III-to-approval intervals for infectious disease countermeasures, rewarding sponsors with priority review vouchers. The southeastern health corridor from Atlanta to Miami concentrates group purchasing organization contract volume for enterprise infection control.
Germany
EMA's priority medicines scheme creates parallel European market access tracks for norovirus vaccines, with sponsors filing simultaneous US and EU applications for procedural alignment benefits. The country's national pharmaceutical regulator demands extended safety follow-up in pediatric cohorts derived from daycare settings. Bavaria's clinical trial networks anchor norovirus candidate development for continental distribution.
United Kingdom
NHS England consolidates norovirus preparedness into enterprise infection control contracts, unbundling standalone diagnostic purchases from therapeutic procurement through integrated care systems. The national health technology assessment body evaluates preventive vaccines against acute treatments for provider reimbursement determination. London's academic medical centers concentrate scarce calicivirus immunology expertise constraining pipeline expansion.
Japan
PMDA's Sakigake designation system accelerates review timelines for novel antiviral formulations targeting viral RNA-dependent RNA polymerase. The country's pharmaceutical regulator emphasizes stability data for oral capsule formulations suitable for outpatient deployment. Osaka's diagnostic manufacturers supply cartridge-based multiplex PCR platforms to cruise operators across the Asia-Pacific.
Singapore
Single-use bioreactor supply chains cluster in the city-state's biologics manufacturing parks, exposing viral vector production to regional geopolitical friction. The national biomedical regulator enforces GMP facility qualification timelines extending validation by 14-18 months for enteric pathogen manufacturing. Jurong's contract development organizations serve as regional hubs for mRNA vaccine cold chain distribution.
Norovirus Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with large pharmaceutical houses racing to secure rare norovirus immunology expertise while mid-cap biotechs advance novel polymerase inhibitors through accelerated regulatory pathways. The upper tier commands diagnostic platform integration and vaccine pipeline momentum through dedicated funding structures. Three archetypes define competitive positioning: diversified pharmaceutical conglomerates with infectious disease franchises, specialized virology biotechs with single-asset focus, and diagnostic-platform anchors extending into therapeutic adjacencies. Dominant competitive moves include strategic partnerships for calicivirus B-cell research access and capacity expansion in single-use bioreactor infrastructure.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify the diagnostic-therapeutic integration archetype, with Roche leveraging its molecular diagnostics platform to anchor care pathways from detection through intervention. Sanofi occupies a position within the European clinical trial network tier, representing the vaccine-development concentration in French pharmaceutical operations. Pfizer Inc. anchors the US-based infectious disease franchise tier, sustaining pipeline momentum through dedicated enteric virus research funding.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| AstraZeneca |
| Johnson & Johnson Private Limited |
| Pfizer Inc. |
| Sanofi |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| HilleVax |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-month GMP facility qualification timelines for enteric pathogen manufacturing compress inventory buffers and amplify pricing power for qualified viral vector producers in Ireland and Singapore. Contract manufacturers with validated single-use bioreactor capacity command premium positioning against sponsors facing extended facility validation cycles.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement, with group purchasing organizations in Texas and Florida locking in bundled outbreak response kits ahead of winter gastroenteritis peaks. Price differentiation rests on FDA fast-track designation status and cold chain certification tiers, with mRNA formulations requiring -70°C storage carrying logistics premiums. Cost compression in oral antiviral capsules is intensifying as polymerase inhibitors advance through Phase II trials. Hospital systems exhibit lowest price sensitivity due to liability exposure from closed-population outbreaks, while independent clinics face margin pressure from limited negotiating leverage.
Supply Chain Analysis
Ireland and Singapore anchor single-use bioreactor production for viral vector manufacturing, with Bavaria's clinical trial networks feeding continental European distribution. Raw material dependencies center on specialized cell culture media, single-use consumables, and viral challenge strains for GMP qualification. Single-source vulnerability concentrates in Singapore's biologics manufacturing parks exposed to regional geopolitical friction. Distribution runs through cold chain logistics providers serving acute care networks and long-term care facilities in seasonal outbreak corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through enterprise infection control contracts consolidating diagnostic and therapeutic procurement, fragmenting standalone vendor relationships.
For Market Incumbents: Secure exclusive access to calicivirus B-cell research expertise concentrated in three academic medical centers, locking out pipeline expansion for rivals. Expand single-use bioreactor capacity in Ireland to offset Singapore geopolitical exposure. Defensive consolidation through diagnostic-therapeutic platform integration neutralizes mid-cap biotech threats advancing oral polymerase inhibitors. For New Entrants and Emerging Players: Anchor in outpatient oral antiviral deployment, bypassing hospital infusion center dependencies that incumbent vaccine portfolios require. Target home care settings and retail pharmacy channels with capsule-based formulations. Go-to-market through direct partnerships with state health departments issuing multi-year surveillance contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical houses with dormant enteric virus research programs awaiting portfolio prioritization. Long-term viability over the coming decade hinges on regulatory fast-track density and pediatric indication expansion. Watch Phase III readouts for polymerase inhibitors as inflection indicators for antiviral category viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III readouts for polymerase inhibitors determine antiviral category commercial timelines. |
| Regulatory Approval Pathway | FDA fast-track and breakthrough therapy designations compress Phase III-to-approval intervals. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion in Ireland offsets Singapore supply concentration risk. |
| Licensing Agreement | Academic medical center partnerships unlock scarce norovirus-specific B-cell research expertise. |
| Pipeline Diversification | Oral antiviral formulations extend addressable settings beyond institutional vaccine delivery. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchors the qualitative findings. Bottom-up and top-down triangulation reconciles sponsor pipeline disclosures with institutional procurement database analysis.
Sensitivity analysis across product type, application setting, delivery mode, and regional regulatory cluster dimensions shapes the analytical framework over the projection horizon. CAGRs derive from modeled adoption curves in seasonal outbreak corridors and CMS reimbursement policy trajectories. Treatment line positioning and pediatric indication expansion timelines feed segmentation-specific growth assumptions.
Underlying assumptions cover regulatory pathway density, manufacturing capacity commissioning schedules, and institutional procurement consolidation, with deviation risk concentrated in Phase III clinical trial outcomes and geopolitical disruption to single-use bioreactor supply chains. Recalibration cycles align with material shifts in FDA fast-track designations and GPO contract award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Global Pediatric Drugs Market