
 Clozapine Market | 2026-2036
Clozapine Market Size, Share, and Industry Trends Forecast 2026-2036
Clozapine Market Outlook
India's active pharmaceutical ingredient production is narrowing the cost base for generic clozapine supply. Novartis AG leverages its original formulation heritage to sustain brand recognition in regulated markets. Teva Pharmaceuticals anchors its position through vertical integration into API manufacturing. Sun Pharmaceutical Industries competes on manufacturing scale across emerging markets.
Clozapine is a tricyclic dibenzodiazepine derivative antipsychotic with high affinity for dopamine D4 and serotonin 5-HT2A receptors, requiring structured hematologic monitoring due to agranulocytosis risk. The compound serves as the gold-standard intervention for treatment-resistant schizophrenia where conventional antipsychotics fail. Tablet formulations dominate current volume, while extended-release formats capture expanding margin pools through improved adherence profiles. Hospital pharmacies control the largest distribution share, though online pharmacies are gaining traction in markets with established REMS infrastructure.
The FDA's REMS program and EMA's pharmacovigilance framework enforce mandatory blood count monitoring that shapes prescribing economics and patient access protocols. India's CDSCO and China's NMPA are tightening bioequivalence standards for generic clozapine entrants, raising compliance costs for new market participants. Stakeholders must monitor evolving REMS digitization and real-world evidence requirements that will determine competitive differentiation in regulated markets.
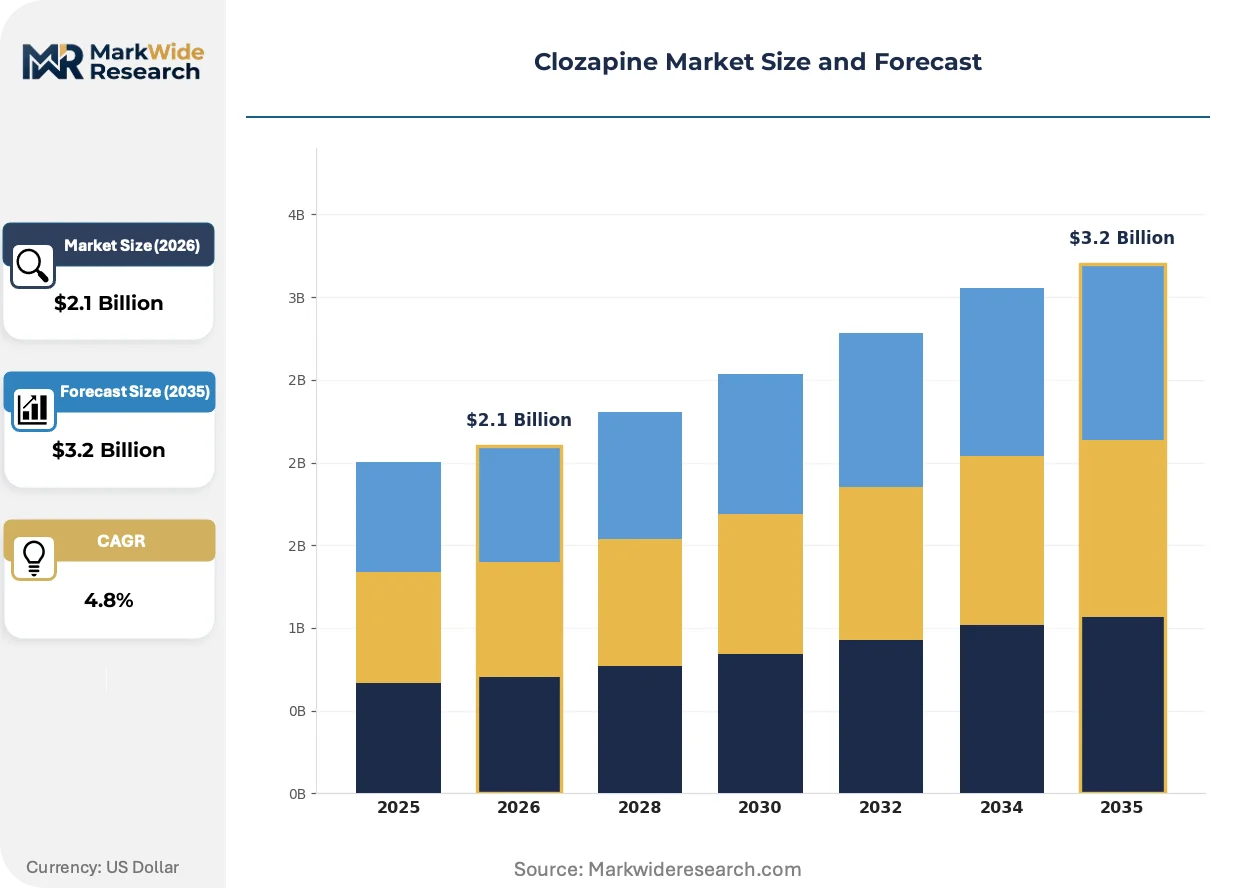
Market Dynamics
The FDA's REMS program for clozapine creates a structural moat around distribution, forcing hospital pharmacies to maintain specialized hematologic monitoring infrastructure that smaller retail channels cannot replicate.
Growth Catalysts
- Treatment-resistant schizophrenia protocols:Psychiatric institutions in the United States are embedding clozapine earlier in therapeutic algorithms after two failed antipsychotic trials.
- EMA pharmacovigilance harmonization:Standardized blood monitoring frameworks across European member states are reducing prescriber hesitation and expanding addressable patient pools.
- API manufacturing scale-up:Indian pharmaceutical clusters are achieving cost efficiencies in dibenzodiazepine synthesis that compress generic pricing floors.
Market Restraints
- Agranulocytosis surveillance burden:Weekly then biweekly neutrophil count requirements impose labor costs that deter outpatient clinic adoption.
- Single-source API concentration:Active pharmaceutical ingredient production clusters heavily in Gujarat and Hyderabad, exposing supply chains to localized disruption risks.
- Metabolic side-effect profiles:Weight gain and diabetes liabilities drive psychiatrists toward newer antipsychotics with cleaner safety signals.
Strategic Opportunities
- Digital REMS infrastructure:Cloud-based hematologic reporting systems are streamlining patient enrollment and reducing pharmacy administrative overhead.
- Extended-release formulation penetration:Once-daily dosing technologies are improving adherence among outpatient populations previously managed on immediate-release tablets.
- Brazilian psychiatric reform:ANVISA is expanding community-based mental health protocols that could replicate US clozapine utilization patterns.
Industry Challenges
- Specialized pharmacy workforce scarcity:REMS-certified pharmacists require training in neutropenia risk counseling that generalist retail staff lack.
- Legacy EHR integration friction:Hospital information systems struggle to automate REMS blood count reporting into existing clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clozapine Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Oral Solution, Injectable, Extended Release End User: Hospitals, Clinics, Homecare, Community Centers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Wholesalers Application: Schizophrenia, Bipolar Disorder, Treatment-Resistant Depression, Neurological Disorders |
| Companies Covered | Novartis AG, Mylan, Teva Pharmaceuticals, Jazz Pharmaceuticals, Sun Pharmaceutical Industries, Aurobindo Pharma, Hikma Pharmaceuticals, Intas Pharmaceuticals, Mayne Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clozapine Market Strategic Shifts
Digital health infrastructure is compressing the administrative burden of clozapine therapy, while formulation science and regulatory harmonization are reshaping competitive access patterns across psychiatric care settings.
Extended-release clozapine formulations are migrating from immediate-release tablets in outpatient settings where adherence failures previously triggered hospitalization. Community mental health centers in the United States are adopting these technologies to reduce relapse-driven readmissions. The shift is compressing margin structures for generic immediate-release manufacturers while creating pricing power for differentiated delivery platforms.
EMA's centralized pharmacovigilance database is harmonizing adverse event reporting standards across European psychiatric institutions. This standardization reduces prescriber uncertainty about cross-border patient transfers and blood monitoring continuity. Southern European markets with historically fragmented mental health systems are responding fastest, accelerating clozapine initiation rates in Spain and Italy.
Hospital pharmacy consolidation is concentrating clozapine dispensing into specialized psychiatric networks with dedicated REMS compliance infrastructure. Independent retail pharmacies are ceding this therapy class to institutional channels with embedded hematology laboratories. The behavioral shift is most visible in US metropolitan markets where health system vertical integration has advanced furthest.
Clozapine Market Segmentation
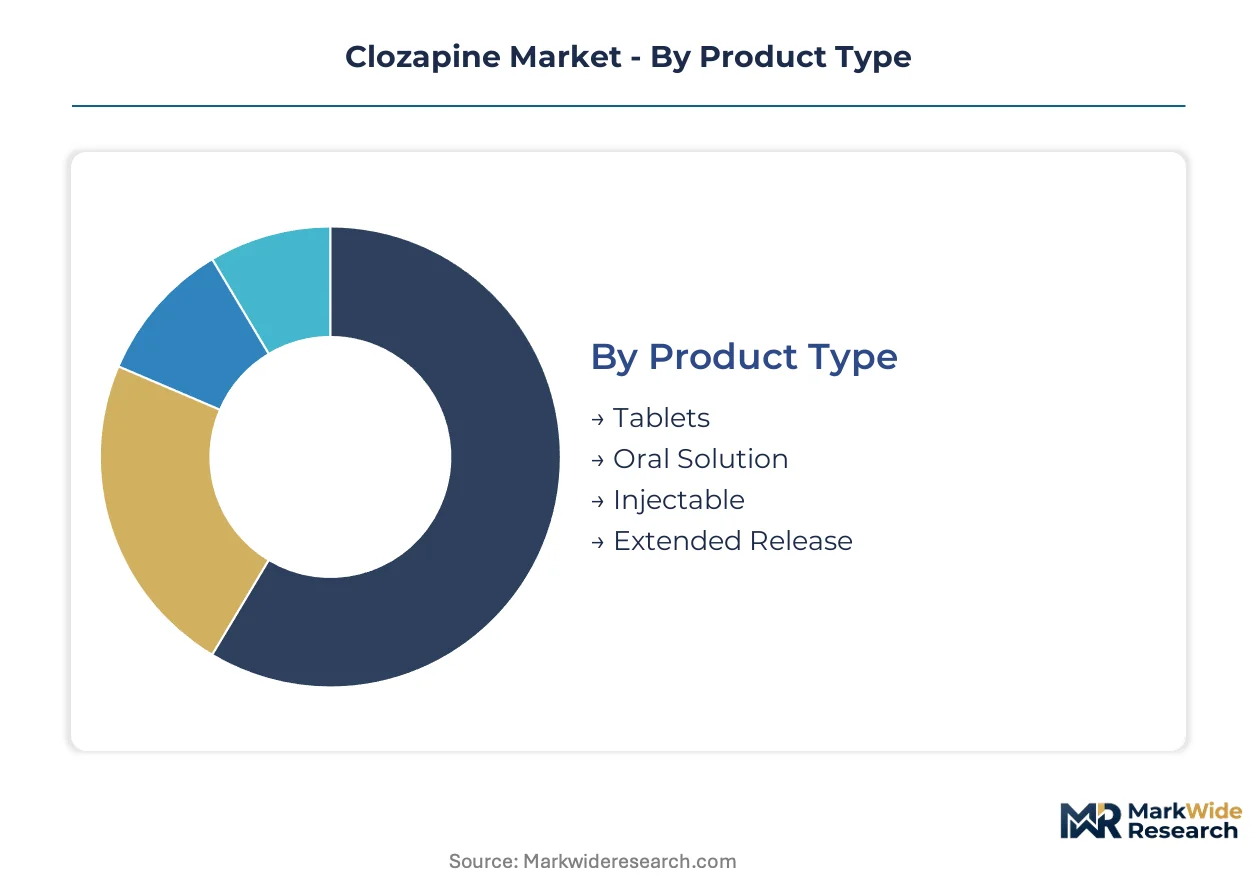
Clozapine's REMS-mandated blood monitoring creates divergent segment economics, with hospital channels capturing high-touch patients while extended-release formulations reshape outpatient economics. Segmentation strategy must account for the therapy's specialized distribution infrastructure and the metabolic side-effect profiles that drive formulation preferences.
Product Type:
Immediate-release formats turn over fastest through hospital discharge protocols, while extended-release technologies command longer prescription cycles through improved adherence profiles.
- Tablets:Standard immediate-release dibenzodiaepine formulations with established bioequivalence pathways dominate current volume. Hospital pharmacies in the United States anchor procurement for treatment-resistant schizophrenia protocols where weekly blood draws are already embedded in clinical workflows.
- Extended Release:Once-daily polymer-matrix or osmotic pump technologies reduce plasma fluctuation and improve outpatient adherence. Community mental health centers in metropolitan markets are adopting these formats to reduce relapse-driven readmissions among patients previously lost to follow-up.
- Oral Solution:Liquid formulations serve dysphagia patients and acute agitation scenarios requiring rapid titration.
- Injectable:Depot formulations remain limited by REMS complexity and hematologic monitoring logistics for long-acting injectable programs.
Tablets anchor the volume base while Extended Release gains share at the steepest rate.
End User:
Cost tiers separate institutional settings with embedded laboratories from community channels struggling to absorb REMS compliance overhead.
- Hospitals:Academic medical centers and psychiatric institutions with on-site hematology infrastructure control the largest patient share. FDA REMS requirements align naturally with inpatient monitoring capabilities, making hospitals the default initiation setting for treatment-resistant schizophrenia protocols.
- Clinics:Outpatient psychiatric practices with REMS certification are expanding clozapine maintenance therapy as digital reporting tools reduce administrative burden. These settings capture patients stabilized after hospital initiation.
- Homecare:Mobile phlebotomy services and telepsychiatry platforms are enabling REMS compliance for homebound patients with severe mental illness.
- Community Centers:Federally qualified health centers in the United States are piloting clozapine programs with centralized laboratory partnerships.
Hospitals retain the highest patient concentration while Clinics expand most quickly as digital infrastructure matures.
Distribution Channel:
Supply concentration favors institutional channels with captive REMS infrastructure over fragmented retail networks.
- Hospital Pharmacies:Embedded within psychiatric networks with dedicated neutropenia monitoring protocols, these channels control the majority of clozapine dispensing. Vertical integration with health system laboratories creates compliance efficiencies that independent retailers cannot replicate.
- Retail Pharmacies:Chain pharmacies with specialized psychiatric certification programs are capturing stable maintenance patients in markets with established REMS digitization.
- Online Pharmacies:Mail-order channels with centralized REMS reporting capabilities are gaining traction for refill prescriptions in states with interoperable laboratory networks.
- Wholesalers:Specialty distributors with cold-chain and controlled-substance expertise serve as intermediaries for institutional procurement.
Hospital Pharmacies dominate current volume while Online Pharmacies show the steepest expansion trajectory as remote monitoring technologies mature.
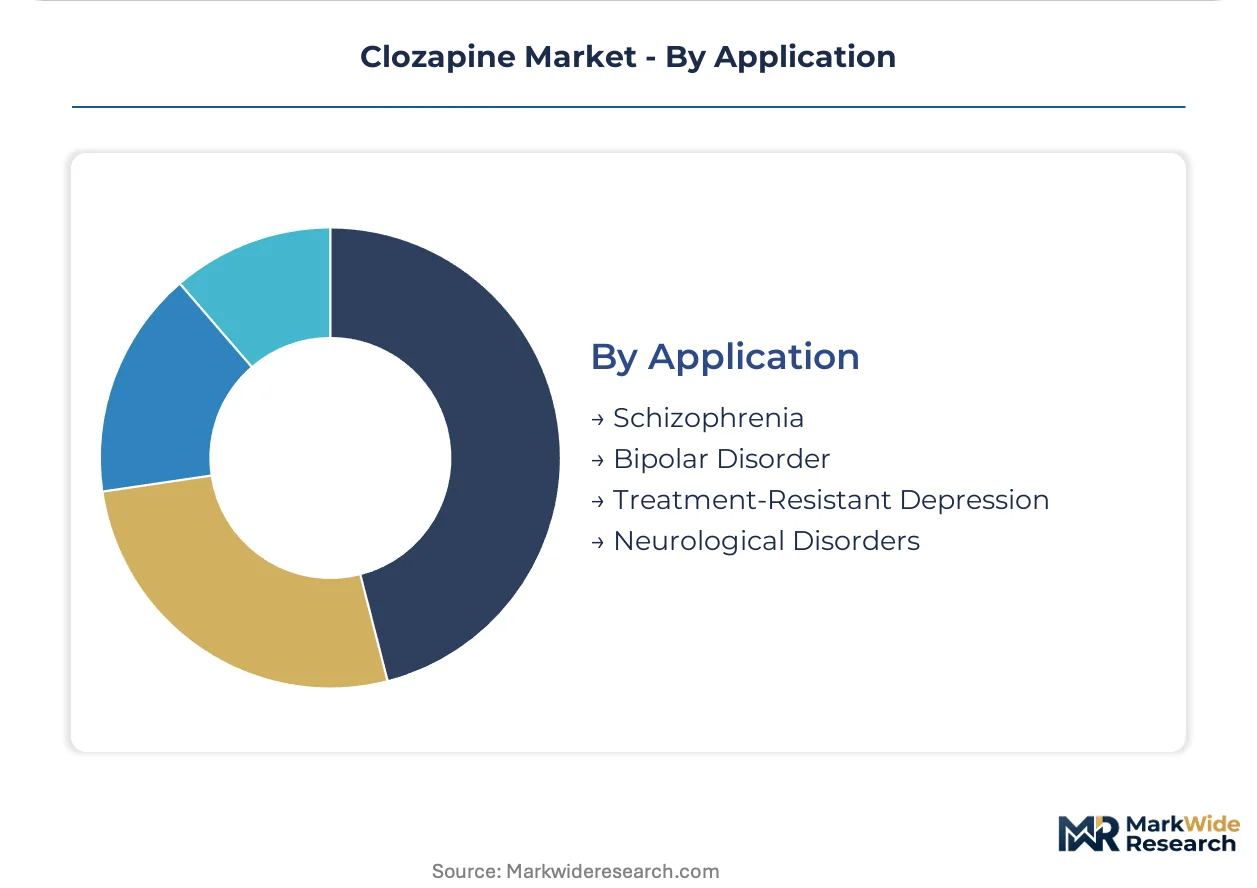
Application:
Maturity curves separate schizophrenia's established protocols from emerging indications where evidence generation continues.
- Schizophrenia:Treatment-resistant protocols after two failed antipsychotic trials represent the core approved indication. Psychiatric institutions in the United States embed clozapine earlier in therapeutic algorithms, expanding the addressable patient pool.
- Treatment-Resistant Depression:Augmentation strategies for major depressive disorder failing multiple antidepressant classes are gaining prescriber attention through real-world evidence accumulation.
- Bipolar Disorder:Manic and mixed episode management represents an off-label use with limited formal evidence but significant clinical experimentation.
- Neurological Disorders:Parkinson's disease psychosis and Lewy body dementia applications face heightened mortality warnings that constrain utilization.
Schizophrenia anchors the volume base while Treatment-Resistant Depression climbs the fastest as augmentation protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis for clozapine concentrates in western Indian pharmaceutical clusters, with formulation and distribution networks extending across North America, Europe, and Asia-Pacific psychiatric care systems. Regulatory divergence on hematologic monitoring protocols shapes patient access patterns in each jurisdiction.
United States
Academic medical centers in Massachusetts and California anchor treatment-resistant schizophrenia protocols that embed clozapine earlier in therapeutic algorithms. The FDA's REMS program mandates weekly-to-biweekly neutrophil surveillance that channels dispensing through hospital pharmacies with embedded laboratories. Specialized psychiatric networks in the Northeast Corridor have achieved the highest per-capita clozapine initiation rates through integrated health system infrastructure.
Germany
University psychiatric hospitals in Bavaria and North Rhine-Westphalia drive clozapine utilization through standardized treatment-resistant protocols. The Federal Institute for Drugs and Medical Devices enforces pharmacovigilance reporting that aligns with EMA centralized databases, reducing prescriber uncertainty about cross-border patient transfers. Manufacturing clusters in Baden-Württemberg supply active pharmaceutical ingredients to generic formulation facilities across the European Union.
India
CDSCO tightening of bioequivalence standards for generic clozapine entrants is raising compliance costs for new market participants in Gujarat and Hyderabad API production zones. Domestic psychiatric institutions in Maharashtra and Karnataka are expanding clozapine access through government-funded mental health programs. Export-oriented formulation manufacturers in Telangana supply regulated markets in North America and Europe.
United Kingdom
NHS England's Mental Health Services Dataset tracks clozapine prescribing patterns across NHS Trusts in London and the Midlands, enabling outcome-based protocol refinement. The Medicines and Healthcare products Regulatory Agency maintains vigilance on agranulocytosis reporting through the Yellow Card scheme. Specialized psychiatric pharmacy services in Greater Manchester and the West Midlands have pioneered digital REMS infrastructure for outpatient monitoring.
Brazil
ANVISA expansion of community-based mental health protocols is replicating US clozapine utilization patterns in São Paulo and Rio de Janeiro metropolitan areas. Psychiatric reform legislation mandates clozapine availability through the Unified Health System for treatment-resistant schizophrenia patients. Manufacturing partnerships between Indian API suppliers and Brazilian formulation facilities are compressing import dependency for critical antipsychotic supply.
Clozapine Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API supply and generic formulation. The clozapine market structures around three tiers: originator heritage players with brand recognition in regulated markets, vertically integrated generic manufacturers with captive API production, and regional formulation specialists competing on cost in emerging economies. Consolidation pressures favor scale-driven players capable of absorbing REMS compliance infrastructure investments. Strategic moves center on backward integration into dibenzodiazepine synthesis and digital health partnerships for remote hematologic monitoring.
Within the originator heritage tier, Novartis AG anchors brand positioning through its original formulation legacy. Among vertically integrated generic manufacturers, Teva Pharmaceuticals and Sun Pharmaceutical Industries exemplify scale-driven competitive positioning. These three entities represent the dominant archetypes shaping procurement dynamics across hospital pharmacy networks in the United States and European psychiatric institutions.
| Leading Market Players |
|---|
| Novartis AG |
| Mylan |
| Teva Pharmaceuticals |
| Jazz Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Aurobindo Pharma |
| Hikma Pharmaceuticals |
| Intas Pharmaceuticals |
| Mayne Pharma |
| Others |
Value Chain & Pricing Dynamics
Single-source API concentration in Gujarat and Hyderabad exposes clozapine supply chains to localized disruption risks that simultaneously compress generic pricing floors and force buyers toward institutional channels with captive REMS infrastructure. This dependency structure creates pricing tier spreads between vertically integrated manufacturers and formulation specialists while channeling procurement through hospital pharmacies with embedded hematology laboratories.
Pricing Analysis
The FDA's REMS program dictates the pricing tier structure across the clozapine market, separating originator heritage products from generic immediate-release tablets and extended-release formulations. Price differentiation rests on certification grade for REMS compliance infrastructure and manufacturing scale for API synthesis. Cost compression in immediate-release generics is intensifying because Indian pharmaceutical clusters are achieving dibenzodiazepine synthesis efficiencies. Hospital pharmacies with captive laboratory networks exhibit the lowest price sensitivity, while independent retail channels struggle to absorb REMS administrative overhead.
Supply Chain Analysis
Export-control restrictions on pharmaceutical manufacturing equipment limit technology transfer to emerging formulation facilities, constraining supply expansion outside established Indian and European production zones. Active pharmaceutical ingredient synthesis concentrates in India, Germany, and Switzerland, drawing from dibenzodiazepine precursors and specialized polymer-matrix components for extended-release technologies. Single-source vulnerability runs through Gujarat-based API manufacturers exposed to regional environmental regulatory enforcement. Distribution runs through specialty wholesalers with controlled-substance expertise serving hospital pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clozapine incumbents face substitution pressure from newer antipsychotics with cleaner metabolic safety profiles that psychiatrists increasingly favor for treatment-resistant patients outside strict protocol settings.
For Market Incumbents: Insulate formulation portfolios by securing captive dibenzodiazepine API supply through backward integration into Indian manufacturing clusters. Deepen REMS compliance infrastructure investments to maintain hospital pharmacy channel control against retail competitors. The metabolic side-effect liability of clozapine represents the core substitution threat requiring adherence-improving extended-release R&D focus. For New Entrants and Emerging Players: Build out digital REMS reporting capabilities to capture outpatient clinic expansion as telepsychiatry platforms reduce administrative burden for community mental health centers. Brazil's psychiatric reform legislation offers the most penetrable geography for generic formulation entry through ANVISA-mandated Unified Health System availability. Target government procurement contracts with centralized laboratory partnership models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive API production and established regulatory filing pathways. Long-term viability hinges on REMS digitization partnerships and real-world evidence generation capabilities for treatment-resistant depression augmentation protocols. Watch EMA pharmacovigilance harmonization progress across Southern European member states as the inflection signal for cross-border patient pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Digital Infrastructure Partnership | Cloud-based hematologic reporting reduces pharmacy administrative overhead for FDA compliance. |
| Extended-Release Formulation Development | Once-daily dosing technologies improve outpatient adherence and reduce relapse-driven hospitalizations. |
| API Manufacturing Scale-Up | Indian pharmaceutical clusters achieve dibenzodiazepine synthesis cost efficiencies for generic supply. |
| Brazilian Market Entry | ANVISA community mental health protocols replicate US utilization patterns through government procurement. |
| Real-World Evidence Generation | Treatment-resistant depression augmentation protocols expand addressable patient pools beyond schizophrenia. |
Study Parameters
Operator-level perspectives from psychiatric pharmacy directors, REMS program administrators, hospital procurement managers, and generic formulation executives anchored the qualitative base for this study. Primary fieldwork combined with secondary validation through FDA REMS documentation, EMA pharmacovigilance databases, CDSCO bioequivalence filings, and Indian pharmaceutical export records. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation cross-checked segmentation outputs across dosage forms and distribution channels.
Scenario-bracketing around regulatory enforcement intensity and API supply disruption probability framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, distribution channel, and application indication. CAGRs were derived from treatment-resistant protocol penetration curves and generic substitution elasticity parameters. Forecast inputs incorporated REMS digitization adoption rates and extended-release formulation share migration patterns.
Stress conditions across agranulocytosis surveillance burden escalation, single-source API supply interruption, and metabolic side-effect liability litigation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory harmonization progress and psychiatric workforce training capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Gastric Cancer Drugs Market