
 Calcium Channel Blocker Market | 2026-2036
Calcium Channel Blocker Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Channel Blocker Market Intelligence
The integration of pharmacogenomic data into treatment protocols is rewriting the clinical application of calcium channel blockers. This shift favors companies with strong R&D pipelines in precision medicine. Pfizer leverages its extensive clinical trial data to identify patient subgroups responsive to specific agents. Novartis competes through its focus on novel combination therapies, while Bayer anchors its position with established, high-volume products.
Calcium channel blockers are medications that inhibit the influx of calcium ions into vascular smooth muscle cells and cardiac myocytes. They primarily target L-type voltage-gated calcium channels, leading to vasodilation and reduced cardiac workload. Dihydropyridines constitute the largest product type segment due to their potent vasodilatory effects and broad clinical use. The hypertension therapy area dominates volume, representing the primary indication for this drug class.
Market access is governed by stringent clinical trial and drug approval processes mandated by bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These regulations enforce rigorous standards for drug safety, efficacy, and manufacturing, directly influencing R&D timelines and costs. Navigating the divergent reimbursement policies and pharmacovigilance requirements across key markets remains a central strategic challenge for manufacturers.
Market Dynamics
The increasing prevalence of chronic hypertension and aging populations worldwide serves as the central structural force. This demographic pressure necessitates development of extended-release formulations that improve patient adherence and support long-term, cost-effective disease management strategies for health systems.
Growth Catalysts
- Aging Demographics:An expanding elderly population in countries like Japan and Germany increases the patient base for chronic conditions like hypertension, a primary indication for calcium channel blockers.
- Extended-Release Formulations:The development of once-daily dosing regimens improves patient compliance and therapeutic consistency, making these drugs more attractive for long-term management of cardiovascular diseases.
- Public Health Initiatives:National health programs, such as China's NMPA-overseen efforts to control cardiovascular disease, are expanding access to essential medicines and driving prescription volumes.
Market Restraints
- Therapeutic Substitution:Competition from other antihypertensive drug classes, particularly Angiotensin-Converting Enzyme (ACE) inhibitors and Angiotensin II Receptor Blockers (ARBs), limits market share expansion.
- Generic Erosion:The expiration of patents for key dihydropyridine drugs results in intense price competition from generic manufacturers, compressing margins for branded products.
- Regulatory Scrutiny:Strict pharmacovigilance requirements mandated by regulators like the EMA and PMDA for monitoring long-term side effects increase post-market surveillance costs for manufacturers.
Strategic Opportunities
- Pharmacogenomic Integration:Developing diagnostic tools to identify patient genotypes that respond best to specific calcium channel blockers offers a path to personalized medicine and premium positioning.
- Combination Therapies:Creating fixed-dose combinations with other antihypertensive agents, such as diuretics or ARBs, can improve efficacy and patient convenience, opening new product lines.
- Emerging Markets:Expanding distribution networks in Latin American countries like Brazil and Mexico, where cardiovascular disease prevalence is rising, presents significant volume growth potential.
Industry Challenges
- API Supply Chain Vulnerability:Concentration of active pharmaceutical ingredient (API) manufacturing in specific regions, notably China and India, creates significant risk of supply chain disruptions and price volatility.
- Divergent Reimbursement Policies:Manufacturers face complexity in securing favorable reimbursement status from disparate payers like the US Centers for Medicare & Medicaid Services (CMS) and national bodies in the EU.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Channel Blocker Market |
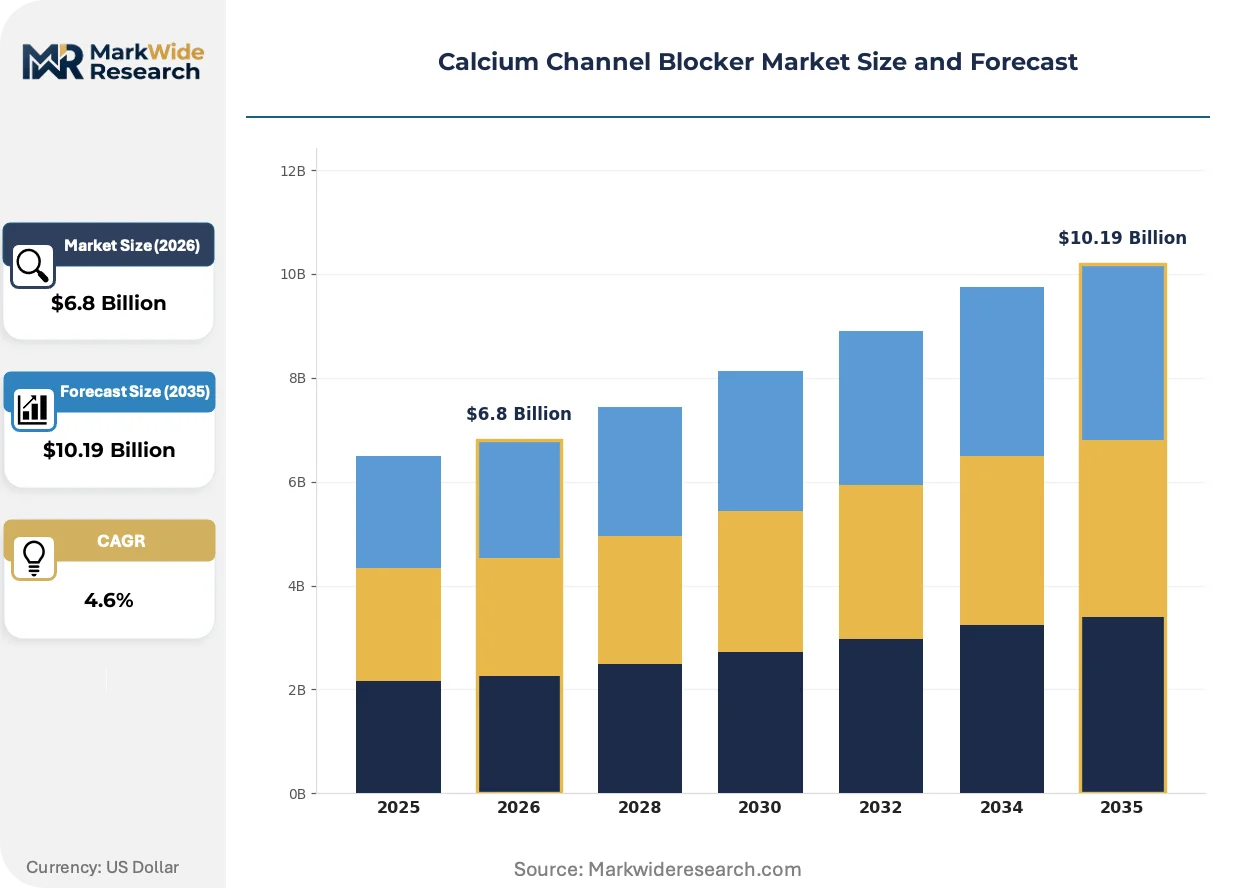
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dihydropyridines, Phenylalkylamines, Benzothiazepines, Others Therapy Area: Hypertension, Angina, Arrhythmia, Raynaud's Phenomenon End User: Hospitals, Specialty Clinics, Ambulatory Care Centers, Diagnostic Laboratories Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Pfizer, Novartis, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Viatris, GlaxoSmithKline, Bayer, AstraZeneca, Bausch Health Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Channel Blocker Market Strategic Shifts & Innovations
The convergence of clinical data analytics and pharmacology is redefining treatment paradigms for cardiovascular disease. This shift prioritizes patient-specific outcomes and drives innovation in drug formulation and delivery mechanisms beyond simple efficacy.
In-silico modeling uses computational algorithms to simulate the interaction of calcium channel blockers with biological targets in virtual patient populations. R&D divisions are adopting these platforms to predict drug efficacy and adverse effects early in development. This digital-first approach is virtualizing parts of preclinical trial design, compressing timelines and reducing financial risk.
A significant regulatory evolution is the acceptance of Real-World Evidence (RWE) by agencies like the US FDA and EMA for post-approval studies. This shift compels drugmakers to systematically analyze data from electronic health records to validate long-term drug performance. The hypertension therapy segment is most impacted, as RWE is used to confirm the sustained safety and efficacy of widely prescribed agents.
Purchasing decisions are increasingly guided by value-based care principles, shifting focus from unit price to total cost of care. This model disrupts traditional procurement by rewarding therapies that improve patient adherence and reduce long-term complication rates. This shift is most evident in large hospital networks in the United States, which prioritize drugs with strong health-economic outcomes data.
Calcium Channel Blocker Market Segmentation
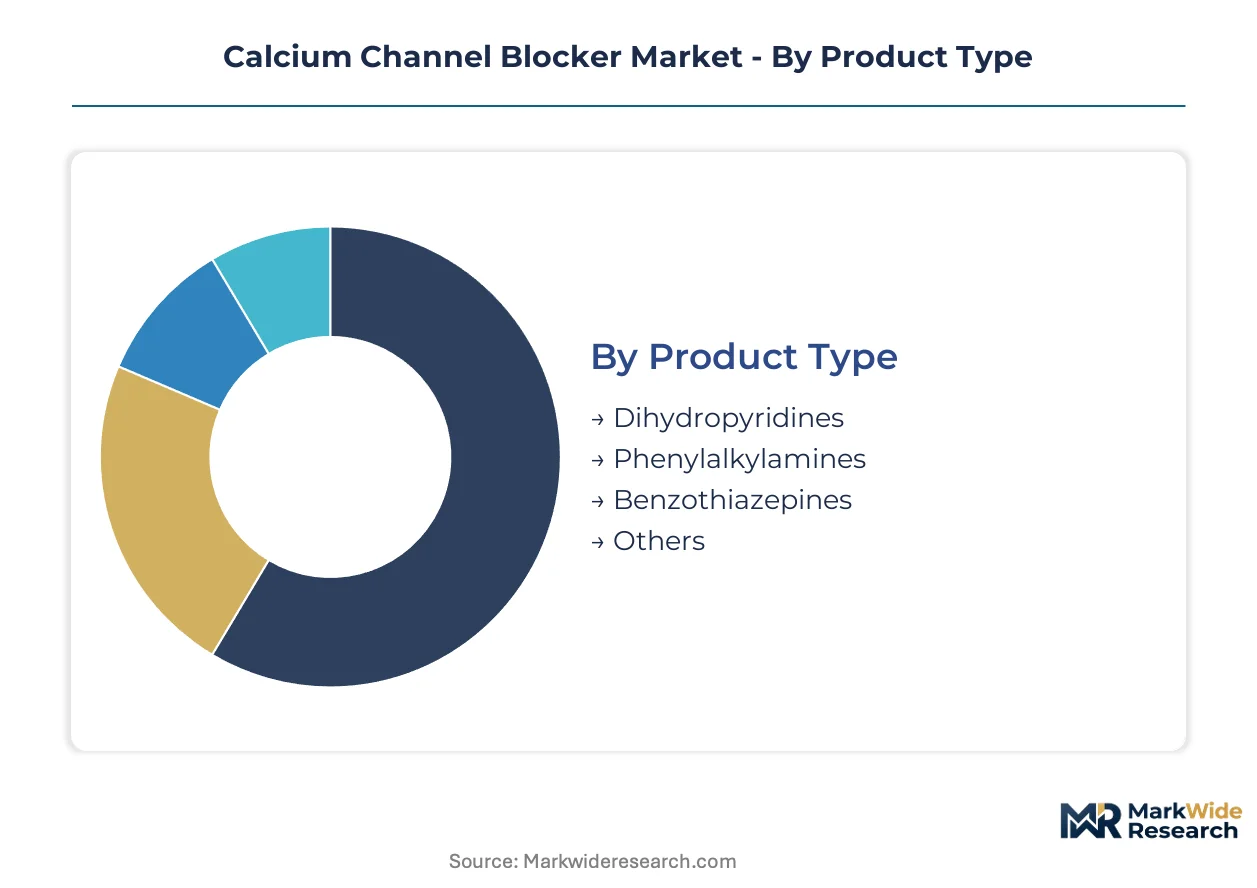
Understanding the segmentation within the Calcium Channel Blocker Market is crucial for identifying distinct demand patterns and strategic growth avenues. This granular analysis reveals how different product types, therapy areas, end-users, and distribution channels contribute to the overall market landscape.
Product Type:
The after-sales-service intensity for calcium channel blockers varies significantly by product type, reflecting differing patient monitoring requirements and therapeutic complexities.
- Dihydropyridines:This class primarily acts on vascular smooth muscle, leading to potent vasodilation without significantly affecting cardiac contractility or conduction. Demand concentrates in China and India, driven by the escalating prevalence of hypertension and the widespread adoption of these agents as first-line therapy.
- Phenylalkylamines:These agents exert their effects on both cardiac and vascular smooth muscle, reducing heart rate and contractility while also causing vasodilation. Germany and Japan show sustained demand, supported by an aging demographic prone to both hypertension and cardiac arrhythmias.
- Benzothiazepines:This group offers an intermediate profile, influencing both cardiac and vascular tissues, often used for hypertension and angina.
- Others:This category includes newer or less common calcium channel blocker formulations and experimental compounds under development.
Dihydropyridines holds the largest share; momentum sits with Phenylalkylamines.
Therapy Area:
The application profile for calcium channel blockers defines distinct patient populations and treatment protocols, influencing prescription volumes across therapeutic areas.
- Hypertension:This segment involves the long-term management of high blood pressure, where calcium channel blockers reduce vascular resistance and cardiac workload. The United States and European Union countries lead demand due to established guidelines favoring these drugs for blood pressure control.
- Angina:Calcium channel blockers alleviate chest pain by improving blood flow to the heart muscle and reducing cardiac oxygen demand. Patient populations in Brazil and Mexico represent significant volume, where cardiovascular disease incidence is rising.
- Arrhythmia:Certain calcium channel blockers regulate abnormal heart rhythms, particularly supraventricular tachycardias.
- Raynaud's Phenomenon:This condition involves spasms of blood vessels, and calcium channel blockers help improve blood flow to affected extremities.
Hypertension remains the dominant therapy area; Angina is expanding most quickly.
End User:
Customer type segmentation for calcium channel blockers highlights the diverse healthcare settings where these medications are administered and dispensed.
- Hospitals:These facilities serve as primary points of care for acute cardiovascular events and initial diagnosis, driving significant procurement volumes. Demand from hospital formularies in France and Italy remains strong for both emergency and sustained treatment.
- Specialty Clinics:Focused on cardiology and hypertension management, these clinics provide ongoing patient care and prescription refills. The United Kingdom and Canada show consistent demand from specialized outpatient settings.
- Ambulatory Care Centers:These centers offer outpatient services, including routine check-ups and chronic disease management, contributing to prescription volumes.
- Diagnostic Laboratories:These facilities conduct tests crucial for diagnosing cardiovascular conditions that necessitate calcium channel blocker therapy.
Hospitals represent the primary end-user segment; Specialty Clinics show significant growth.
Distribution Channel:
Supply concentration patterns within the distribution channel dictate the reach and accessibility of calcium channel blockers to various patient demographics.
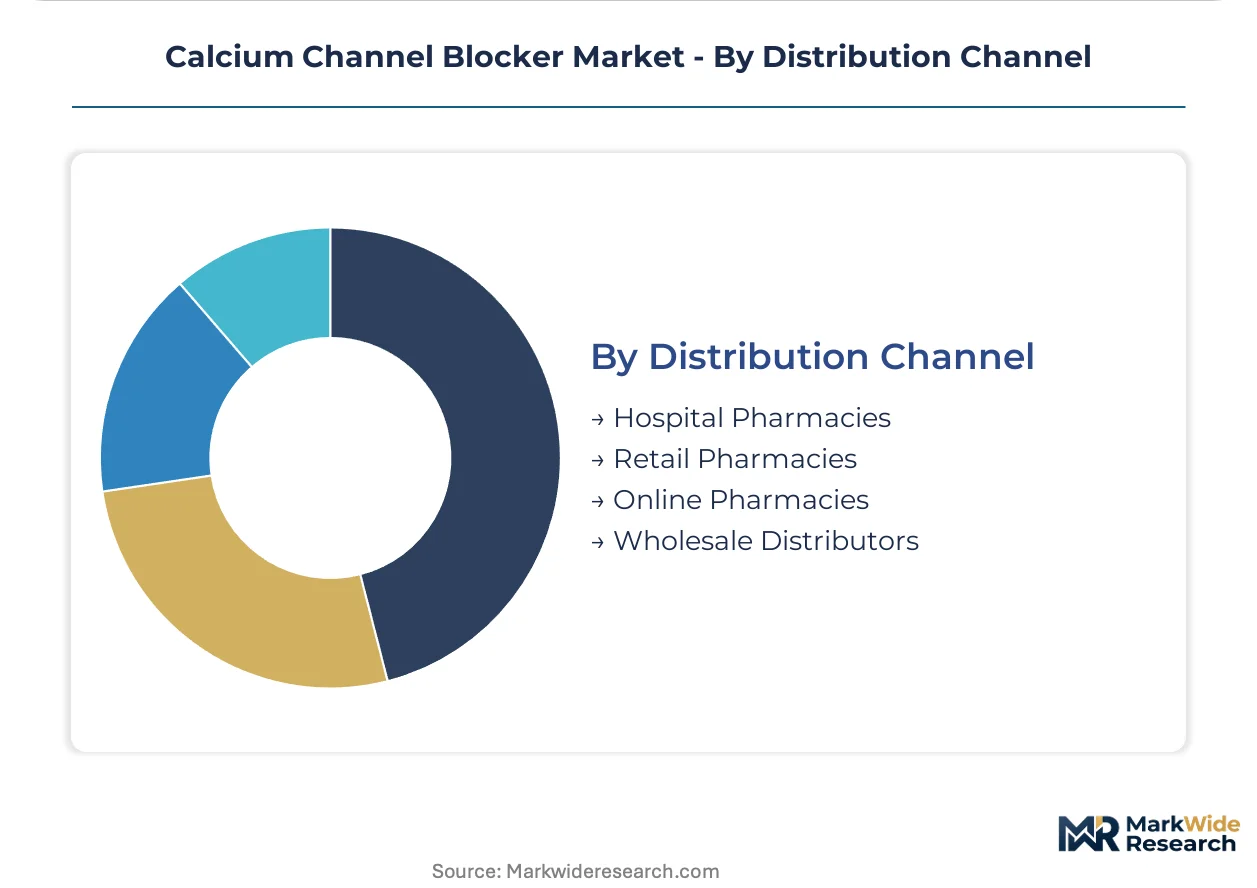
- Retail Pharmacies:These pharmacies provide direct access to prescribed medications for the general public, forming the largest point of patient dispensation. The extensive network of retail pharmacies in the United States and Germany ensures broad availability of these drugs.
- Wholesale Distributors:These entities manage the large-scale logistics and supply of pharmaceutical products from manufacturers to various healthcare providers and pharmacies. Their operations are critical for market penetration in diverse geographies, including Australia and South Korea.
- Hospital Pharmacies:Integrated within hospital systems, these pharmacies manage drug supply for inpatient and outpatient services.
- Online Pharmacies:These digital platforms offer convenience and home delivery, particularly for chronic medication refills.
Retail Pharmacies account for the largest direct patient access; Online Pharmacies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global distribution of calcium channel blockers from manufacturing hubs in India and China to key consumer markets underpins regional growth. Patient demographics and established healthcare systems drive demand across diverse geographies. Regulatory frameworks and reimbursement policies significantly influence market access and adoption rates in each region.
China
An aging population and rising prevalence of cardiovascular conditions drive strong demand for calcium channel blockers in China. The NMPA oversees national health programs aimed at controlling cardiovascular disease, expanding access to essential medicines. Major pharmaceutical manufacturing and distribution centers in the Yangtze River Delta support this extensive market.
United States
The United States leads demand for calcium channel blockers due to established guidelines for hypertension management. US FDA approval processes and CMS reimbursement policies shape market access for these drugs. Large hospital networks across major metropolitan areas prioritize therapies with strong health-economic outcomes data.
Germany
Germany shows sustained demand for phenylalkylamines and other calcium channel blockers, supported by an aging demographic prone to hypertension and cardiac arrhythmias. The European Medicines Agency (EMA) enforces rigorous standards for drug safety and efficacy. Pharmaceutical research and development hubs in cities like Munich continue to innovate within the cardiovascular therapeutic area.
Japan
An expanding elderly population in Japan increases the patient base for chronic conditions like hypertension. The PMDA mandates strict pharmacovigilance requirements for monitoring long-term side effects of prescribed medications. Advanced healthcare infrastructure in Tokyo and other major cities ensures consistent demand and distribution.
India
Demand for dihydropyridines concentrates in India, driven by the escalating prevalence of hypertension and widespread adoption of these agents. The CDSCO regulates drug approval and manufacturing standards within the country. Active pharmaceutical ingredient (API) manufacturing clusters in Hyderabad and Gujarat support domestic and export markets.
Calcium Channel Blocker Market Key Industry Players
Channel-controlling players compete with product-specialist players across the calcium channel blocker market. The industry exhibits a tiered structure, with established pharmaceutical giants holding significant market share. Strategic archetypes include precision medicine innovators, combination therapy specialists, and established product leaders. Portfolio diversification and leveraging extensive clinical trial data represent dominant competitive moves.
Within the precision medicine innovation archetype, Pfizer leverages its extensive clinical trial data to identify patient subgroups responsive to specific agents. Novartis competes through its focus on novel combination therapies, enhancing efficacy and patient convenience. Bayer anchors its position with established, high-volume products, maintaining a significant presence in the market.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Viatris |
| GlaxoSmithKline |
| Bayer |
| AstraZeneca |
| Bausch Health Company |
| Others |
Cost & Logistics Intelligence
The Suez Canal's freight cost dynamics significantly influence the supply concentration of active pharmaceutical ingredients, directly impacting downstream price differentiation for calcium channel blockers. This interaction between concentrated supply and logistics costs shapes market pricing.
Pricing Analysis
The pricing gap between branded extended-release formulations and generic dihydropyridines remains substantial. Value-based pricing models increasingly reward novel combination therapies with improved patient outcomes. Price differentiation drivers include formulation complexity and extensive clinical trial data supporting enhanced efficacy. Pricing pressure stems from intense generic erosion in mature segments, impacting branded product margins. Public health systems in the European Union demonstrate higher price sensitivity compared to private hospital networks in the United States.
Supply Chain Analysis
Extended payment terms from major pharmaceutical manufacturers to API suppliers in India and China are a key financing mechanism. Geographic supply concentration for active pharmaceutical ingredients centers in India and China. Raw material dependencies include specialized chemical intermediates and excipients. The API supply chain vulnerability, particularly from single-source suppliers, represents a significant structural risk. Distribution runs through a network of wholesale distributors supplying retail pharmacies and hospital systems globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Calcium Channel Blocker Market is at a platform-economics inflection, driven by the integration of pharmacogenomic data into treatment protocols. This shift prioritizes patient-specific outcomes within cardiovascular care ecosystems.
For Market Incumbents:Entrench existing market share by investing in next-generation extended-release formulations, leveraging established clinical trial data. Diversify product portfolios with novel combination therapies to counter therapeutic substitution from ACE inhibitors. Strengthen channel control through strategic partnerships with large hospital networks, mitigating generic erosion.
For New Entrants and Emerging Players:Geographic underpenetration in emerging markets, particularly Latin America, offers significant white-space opportunities. Target the angina therapy area with cost-effective dihydropyridine formulations adapted for local prevalence. A direct-to-physician marketing approach, emphasizing accessibility and affordability, can drive initial prescription volumes.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core cardiovascular assets. Long-term viability for this market depends on sustained innovation in precision medicine and combination therapies over the next decade. The signal to watch is the regulatory approval of the first pharmacogenomically guided calcium channel blocker.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates approval for novel formulations, establishing a competitive edge in patient outcomes. |
| Pipeline Diversification | Mitigates reliance on single drug classes, broadening therapeutic options for clinicians. |
| Manufacturing Scale-Up | Ensures cost-efficient production of high-volume generic and branded products for global supply. |
| Strategic Partnership | Leverages distribution networks in emerging markets, expanding market access and patient reach. |
| Pharmacogenomic Integration | Drives personalized medicine, improving treatment efficacy for specific patient subgroups. |
Research Approach
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration. This involved combining primary interviews with industry stakeholders and secondary validation from sources like FDA filings, EMA submissions, and ClinicalTrials.gov. Both bottom-up and top-down triangulation methods ensured data consistency and accuracy.
The analytical framework employed a scenario-bracketing approach across the analysis window, modeling various market evolution pathways. Segmentation dimensions included product type, therapy area, end-user, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected adoption rates. Key forecast inputs included disease prevalence rates and patent expiration schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by generic manufacturers or novel therapeutic developers would shift outcomes. Forecasts reflect assumptions documented through extensive primary and secondary research. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Global Immunosuppressant Drugs Market