
 DNA Probes - Based Diagnostics Market | 2026-2036
DNA Probes - Based Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Probes - Based Diagnostics Market Outlook
Reagent subscription models for probe-based assay panels is shifting how diagnostic manufacturers monetize molecular testing. F. Hoffmann-La Roche Ltd. leverages its installed base of cobas instruments to lock in recurring consumable revenue. QIAGEN N.V. anchors its growth in sample-to-insight workflows that bundle extraction reagents with probe content. Thermo Fisher Scientific Inc. competes through scale in oligonucleotide synthesis, controlling cost structures for custom probe production.
DNA probes are single-stranded nucleic acid sequences, typically 15-50 nucleotides in length, designed to hybridize with complementary target sequences through Watson-Crick base pairing; they function as detection elements in molecular assays that identify specific genetic variants, pathogens, or chromosomal abnormalities with high specificity. Fluorescent probes and TaqMan probes dominate clinical revenue due to their integration into real-time PCR workflows, while microarrays retain importance in research settings where multiplexing thousands of targets justifies higher per-run costs. Oncology applications command premium positioning because companion diagnostic requirements tie probe content to therapy selection, creating stickier customer relationships than infectious disease screening.
The FDA regulates nucleic acid-based diagnostics as in vitro diagnostics under 21 CFR Part 820 quality system requirements, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for probe-based oncology tests in Europe. China's NMPA has accelerated review pathways for innovative molecular diagnostics, reshaping where companies prioritize registration investments. Stakeholders must monitor how regulatory divergence between these jurisdictions affects probe design standardization and kit modification costs.
Market Dynamics
The consolidation of hospital procurement around integrated molecular diagnostics platforms is compressing vendor margins while locking in multi-year consumable commitments from reference laboratories.
Growth Catalysts
- Oncology companion diagnostic mandates:FDA requirements tying probe-based tests to targeted therapy approvals create captive demand from pharmaceutical sponsors seeking co-development partnerships with diagnostic manufacturers.
- China's NMPA accelerated review pathways:Streamlined registration for innovative molecular diagnostics is redirecting R&D investment toward Shanghai and Beijing bioclusters.
- CRISPR-enhanced probe specificity:Guide RNA integration with fluorescent detection chemistry is reducing false-positive rates in infectious disease screening below 0.1% thresholds.
Market Restraints
- Oligonucleotide synthesis cost volatility:Phosphoramidite monomer supply concentrates in German and Japanese chemical manufacturers, exposing probe producers to input price swings.
- EMA IVDR clinical evidence requirements:Stricter performance validation for oncology probe kits extends European registration timelines by 18-24 months versus pre-2022 standards.
- Next-generation sequencing substitution:Amplicon-based NGS panels are capturing multiplex testing volumes previously served by discrete probe assays in research settings.
Strategic Opportunities
- Point-of-care molecular testing in India:CDSCO regulatory harmonization with WHO prequalification standards opens decentralized diagnostic deployment in tier-2 and tier-3 cities.
- Pharmacogenomic probe panels:CYP450 and TPMT variant detection is expanding from academic medical centers into community hospital formularies.
- Cloud-connected reagent inventory systems:IoT-enabled consumable monitoring creates subscription stickiness by automating probe replenishment before stockouts occur.
Industry Challenges
- Bioinformatics specialist scarcity:Probe design optimization requires hybrid molecular biology and computational expertise that outpaces current training pipeline output.
- Laboratory Information System integration:Middleware compatibility gaps between proprietary instrument software and hospital EMR platforms delay test menu expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Probes - Based Diagnostics Market |
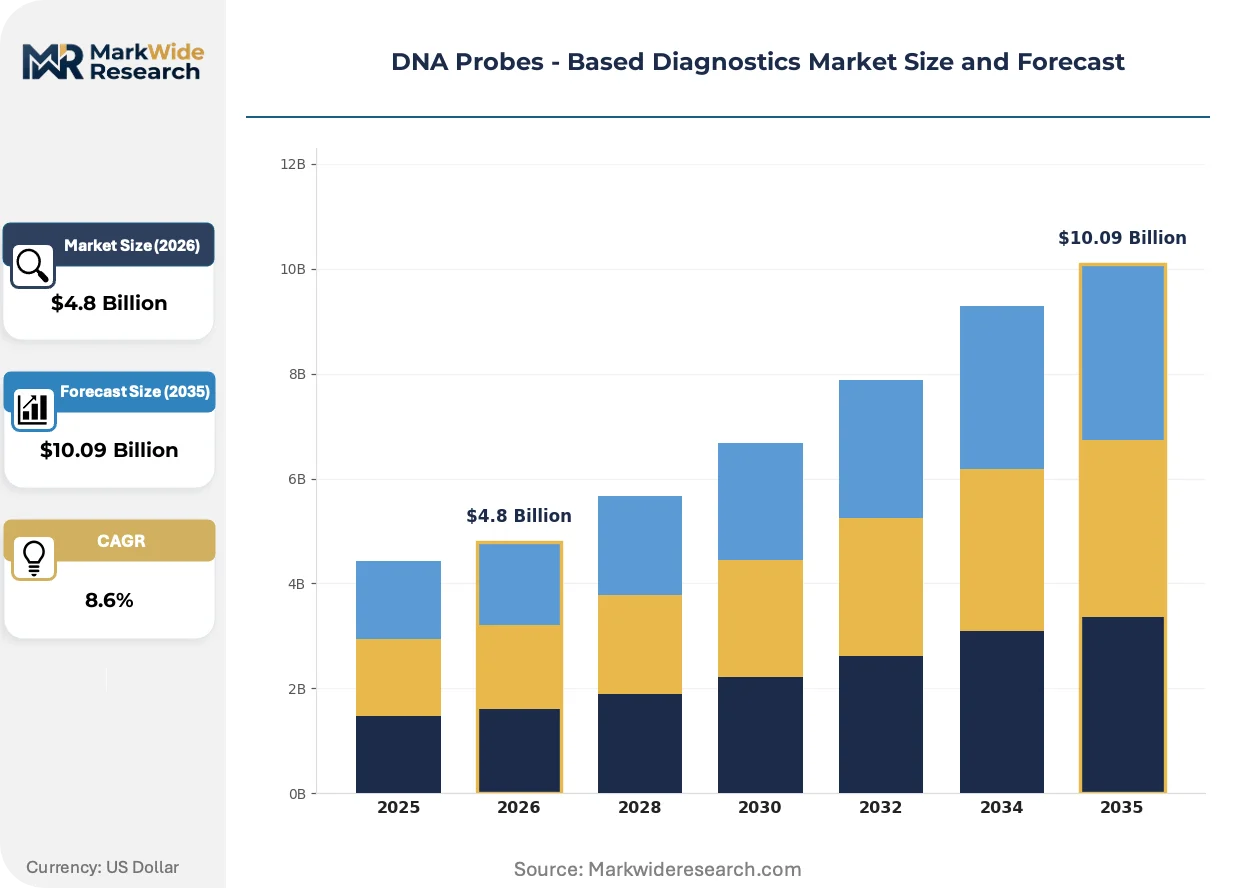
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarrays, Fluorescent Probes, TaqMan Probes, LNA Probes Technology: Polymerase Chain Reaction, In Situ Hybridization, Sequencing, Gel Electrophoresis Application: Genetic Testing, Oncology, Infectious Diseases, Prenatal Testing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Academic Centers |
| Companies Covered | F. Hoffmann-La Roche Ltd., Abbott Molecular, QIAGEN N.V., Thermo Fisher Scientific Inc., Siemens Healthineers, Beckman Coulter Inc., Becton, Dickinson and Company, bioMérieux, GE Healthcare Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Probes - Based Diagnostics Market Strategic Shifts
Digital PCR workflows are fragmenting the installed base of real-time PCR instruments while forcing incumbent vendors to defend reagent revenue through locked chemistry agreements.
Locked nucleic acid chemistry is expanding into clinical probe design by improving thermal stability and mismatch discrimination. Oncology reference laboratories in the United States are adopting LNA-modified probes for circulating tumor DNA detection at allele frequencies below 0.5%. This chemistry shift is expanding into minimal residual disease monitoring applications previously dominated by NGS methods.
The FDA's ongoing nucleic acid-based test modernization is compressing validation study timelines for breakthrough-designated companion diagnostics. Sponsors now submit prospective clinical trial data through the Pre-Cert program rather than traditional 510(k) pathways. Oncology probe manufacturers with FDA breakthrough status are capturing priority review slots that accelerate time-to-revenue by 8-12 months versus standard submissions.
Hospital system procurement offices are consolidating molecular diagnostics contracts under single-source agreements that bundle instruments, reagents, and service. Independent reference laboratories in Germany and China are responding by forming purchasing cooperatives to maintain negotiating leverage against multinational vendors. This buyer concentration is most visible in Bavaria and Guangdong province, where provincial health authorities have mandated centralized tendering for all nucleic acid testing platforms.
DNA Probes - Based Diagnostics Market Segmentation
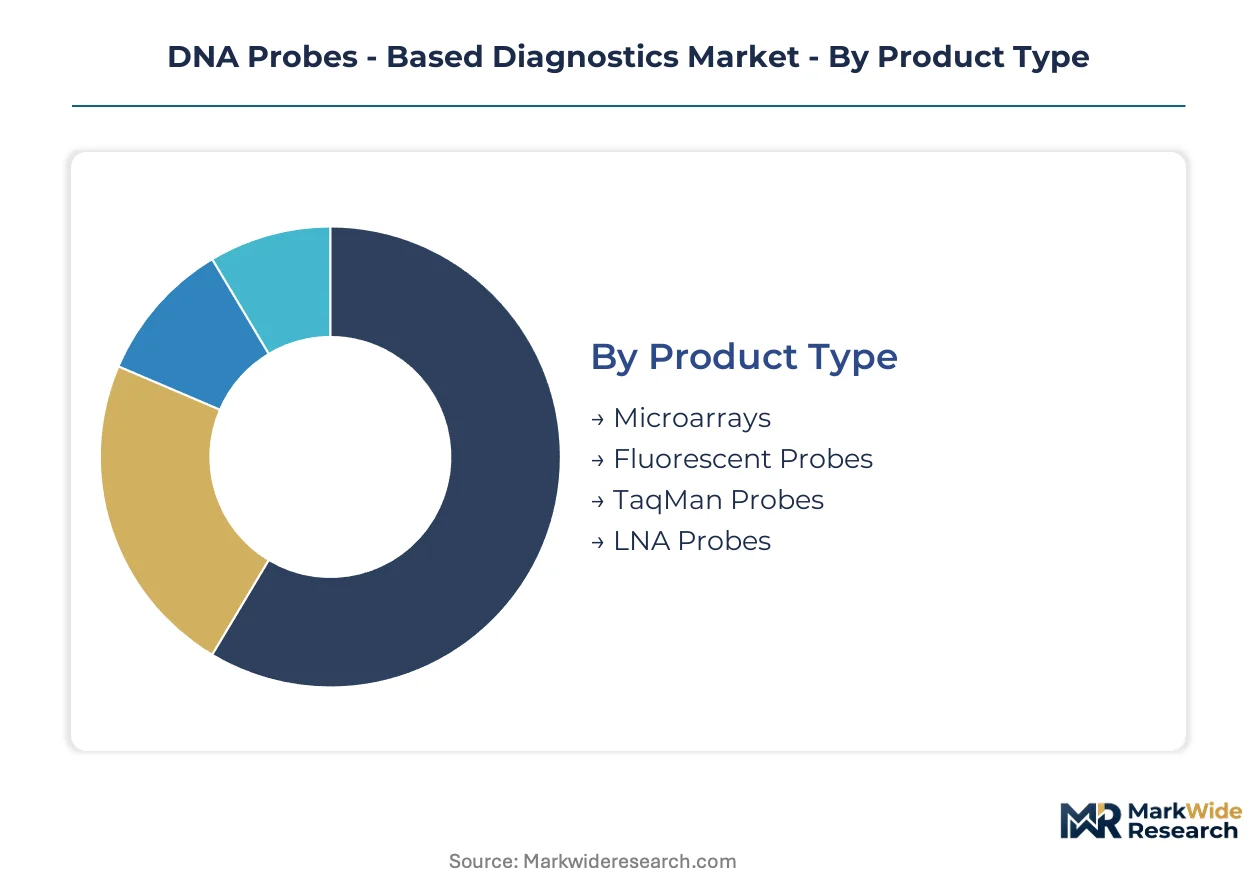
Probe chemistry selection directly determines assay sensitivity thresholds and regulatory validation burden. Segmentation reveals where capital deployment concentrates across synthesis platforms, detection modalities, and care settings.
Product Type:
Capital intensity peaks with microarray manufacturing, where photolithographic mask sets and cleanroom infrastructure demand eight-figure upfront commitments before first commercial batch release.
- Microarrays:Silicon or glass substrates carry thousands of immobilized probe sequences for parallel target interrogation. Demand clusters in pharmacogenomic screening programs at academic medical centers in Germany and the United States, where batch processing of 50,000+ variants justifies per-run costs exceeding $2,000.
- Fluorescent Probes:Synthetic oligonucleotides conjugated to fluorophores enable real-time signal generation upon target hybridization. Oncology reference laboratories in Shanghai and Boston are standardizing on FAM and HEX dye configurations for circulating tumor DNA panels, driven by companion diagnostic co-development contracts with pharmaceutical sponsors.
- TaqMan Probes:Dual-labeled hydrolysis probes with 5' reporter and 3' quencher moieties integrate into quantitative PCR workflows. Infectious disease screening programs at hospital systems in Guangdong province represent the largest procurement volume.
- LNA Probes:Locked nucleic acid modifications enhance thermal stability and single-base mismatch discrimination. Minimal residual disease monitoring applications in Bavarian oncology centers are adopting this chemistry for allele frequency detection below 0.5%.
Most installed capacity flows through Fluorescent Probes. Expansion is steepest in LNA Probes.
Technology:
Platform selection hinges on throughput requirements and staff technical proficiency, with sequencing workflows demanding specialized bioinformatics support that constrains deployment to tertiary care settings.
- Polymerase Chain Reaction:Thermal cycling amplification of target sequences with probe-based detection remains the dominant clinical modality. Community hospital laboratories in the United States and China prioritize real-time PCR instruments for their 90-minute turnaround times and minimal hands-on requirements.
- In Situ Hybridization:Tissue-section probe hybridization with chromogenic or fluorescent readout enables morphological context preservation. Anatomic pathology departments at German university hospitals drive demand for HER2 and ALK break-apart probe kits.
- Sequencing:Next-generation and Sanger methods incorporate probe-based target enrichment or primer extension chemistries. Research institutions in Beijing and Boston represent the primary customer base for hybridization capture panels.
- Gel Electrophoresis:Size-based separation of probe-amplicon complexes persists in low-resource settings and educational contexts. Diagnostic laboratories in tier-2 Indian cities maintain legacy workflows for infectious disease confirmation.
Polymerase Chain Reaction carries the largest instrument installed base. Sequencing platforms are gaining share fastest in oncology applications.
Application:
Revenue concentration skews toward oncology, where probe content ties directly to therapy selection and commands premium pricing through companion diagnostic mandates.
- Oncology:Probe panels detect somatic mutations, gene amplifications, and chromosomal translocations to guide targeted therapy selection. FDA breakthrough-designated tests for EGFR, BRAF, and PIK3CA variants concentrate demand at United States reference laboratories with pharmaceutical co-development agreements.
- Infectious Diseases:Pathogen-specific probe assays identify viral, bacterial, and fungal nucleic acids in clinical specimens. China's NMPA accelerated review pathways have expanded tuberculosis and HPV screening volumes in Shanghai and Beijing municipal health systems.
- Genetic Testing:Germline variant detection for hereditary conditions employs probe-based carrier screening and diagnostic panels. Academic centers in Germany and the United States process the highest volumes for cystic fibrosis and spinal muscular atrophy testing.
- Prenatal Testing:Cell-free fetal DNA analysis and chromosomal microarrays utilize probe content for aneuploidy detection. Hospital systems in Guangdong province have centralized non-invasive prenatal testing procurement under provincial tendering frameworks.
Oncology commands the highest average revenue per test. Infectious Diseases represents the highest test volume segment.
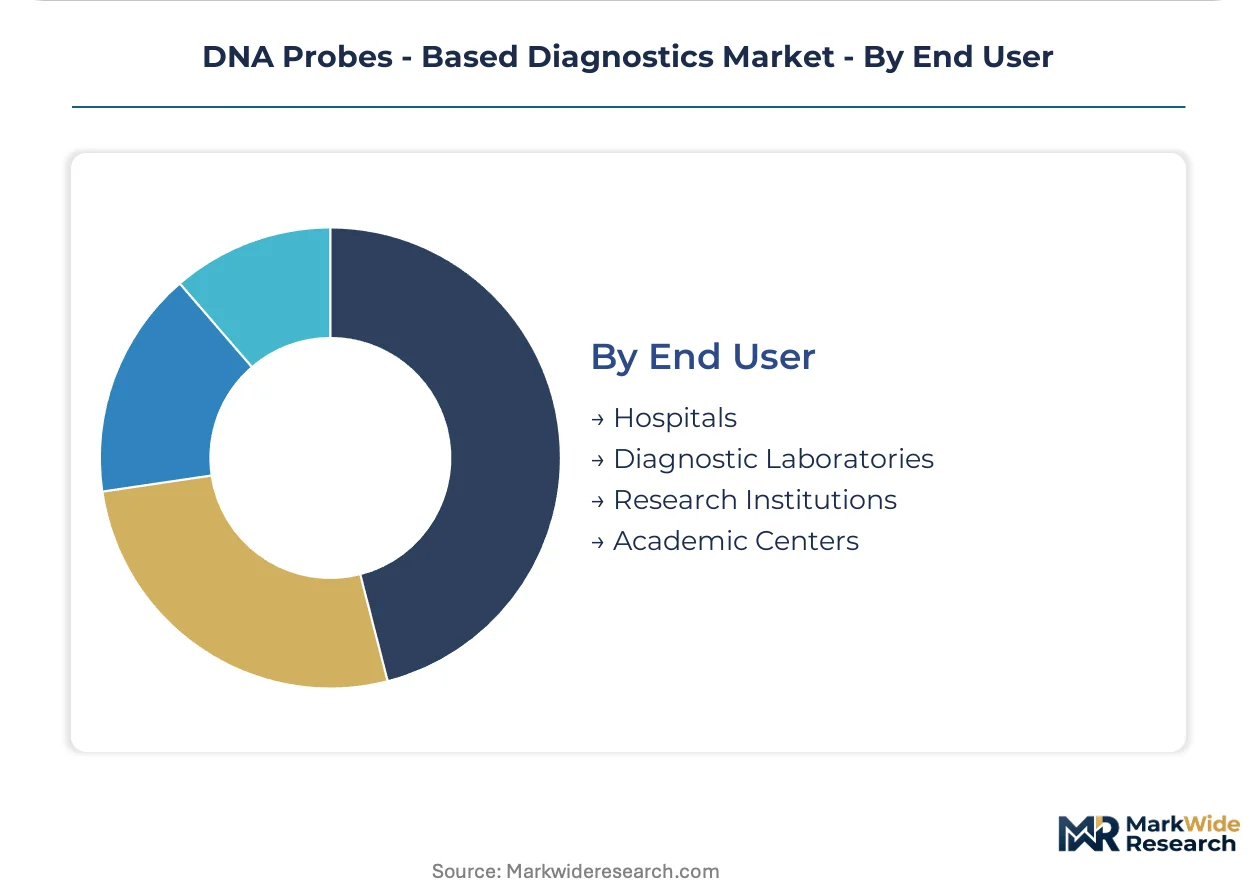
End User:
Procurement authority consolidation is reshaping vendor relationships, with hospital system central offices displacing individual laboratory purchasing autonomy.
- Diagnostic Laboratories:Independent and hospital-affiliated reference labs process high-complexity molecular testing for outpatient and inpatient ordering. Bavarian laboratory cooperatives negotiate multi-year reagent contracts with pooled purchasing leverage.
- Hospitals:In-house molecular diagnostics laboratories support emergency department and oncology service line needs. United States health systems with 10+ hospital campuses are consolidating instrument platforms under single-source agreements.
- Research Institutions:Basic and translational science applications demand custom probe synthesis and flexible assay configurations. Beijing and Shanghai bioclusters account for the fastest-growing procurement of synthetic biology probe libraries.
- Academic Centers:Teaching hospitals with affiliated medical schools balance clinical service and research missions. German university hospitals in Heidelberg and Munich maintain dual-track procurement for validated clinical assays and investigational probe sets.
Diagnostic Laboratories process the highest absolute probe consumption. Hospitals are consolidating procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands higher per-test revenue than China, yet Chinese municipal health systems process substantially larger screening volumes for infectious disease applications.
United States
Oncology reference laboratories and pharmaceutical co-development partnerships drive probe-based diagnostic consumption. FDA breakthrough-designated companion diagnostics for EGFR and BRAF variants accelerate validation timelines through the Pre-Cert program. Hospital systems across Texas and California consolidate molecular diagnostics procurement under single-source agreements spanning instruments, reagents, and service.
Germany
Academic medical centers in Heidelberg and Munich maintain dual-track procurement for validated clinical assays and investigational probe sets. EMA In Vitro Diagnostic Regulation imposes stricter clinical evidence standards that extend oncology probe kit registration timelines. Bavarian laboratory cooperatives negotiate multi-year reagent contracts with pooled purchasing leverage against multinational vendors.
China
Shanghai and Beijing municipal health systems expand tuberculosis and HPV screening volumes through NMPA accelerated review pathways. Streamlined registration for innovative molecular diagnostics redirects R&D investment toward Yangtze River Delta bioclusters. Provincial health authorities in Guangdong mandate centralized tendering for all nucleic acid testing platforms.
India
CDSCO regulatory harmonization with WHO prequalification standards enables decentralized diagnostic deployment in tier-2 and tier-3 cities. Tier-2 diagnostic laboratories maintain legacy gel electrophoresis workflows for infectious disease confirmation. Hyderabad and Bangalore bioclusters attract investment in cloud-connected reagent inventory systems for probe replenishment automation.
DNA Probes - Based Diagnostics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing multi-year consumable commitments while independent probe suppliers serve research flexibility needs. Market structure tilts toward consolidation around installed instrument bases, yet fragmentation persists in custom synthesis and specialty chemistry niches. Three archetypes dominate: multinational conglomerates with diagnostic divisions, pure-play molecular diagnostics specialists, and oligonucleotide synthesis service providers. Competitive dynamics center on locked chemistry agreements that defend reagent revenue and purchasing cooperative formation that restores buyer leverage.
Among diversified healthcare conglomerates, F. Hoffmann-La Roche Ltd., Siemens Healthineers, and GE Healthcare Life Sciences occupy positions that span instrumentation, consumables, and service contracts. These entities exemplify platform-centric strategies where instrument placement secures recurring probe revenue. Pure-play molecular diagnostics specialists including QIAGEN N.V., bioMérieux, and Abbott Molecular represent archetypes focused on sample-to-insight workflow integration. Thermo Fisher Scientific Inc. anchors the scale-driven synthesis tier, with Beckman Coulter Inc. and Becton, Dickinson and Company sitting within clinical automation ecosystems that bundle probe content with liquid handling infrastructure.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Abbott Molecular |
| QIAGEN N.V. |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers |
| Beckman Coulter Inc. |
| Becton, Dickinson and Company |
| bioMérieux |
| GE Healthcare Life Sciences |
| Others |
Value Chain & Pricing Dynamics
Specialized oligonucleotide chemists concentrated in Bavaria and the Yangtze River Delta create labor-cost differentials that widen pricing-tier spreads between premium LNA-modified probes and standard fluorescent chemistries.
Pricing Analysis
Capacity additions in Chinese phosphoramidite manufacturing are reshaping price floors for standard probe synthesis while premium LNA-modified probes retain pricing power through chemistry patents held by European suppliers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and customization depth. Price differentiation hinges on FDA breakthrough designation status and vertical integration into oligonucleotide synthesis. Reference laboratories in Guangdong province exhibit highest price sensitivity due to centralized provincial tendering, while pharmaceutical co-development partners in Boston and Shanghai show lowest sensitivity.
Supply Chain Analysis
Specialized workforce availability in German chemical manufacturing clusters and Chinese bioclusters anchors probe production geography. Phosphoramidite monomer supply concentrates in Germany, Japan, and China; fluorophore conjugation chemistry draws from Swiss and American specialty chemical producers. Single-source vulnerability in phosphoramidite precursor supply exposes probe manufacturers to input disruption. Distribution runs through direct instrument-locked reagent agreements with hospital systems and reference laboratory cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's NMPA accelerated review pathways and Europe's EMA IVDR extended validation timelines, with registration cost differentials redirecting R&D investment toward Shanghai and Beijing.
For Market Incumbents: Anchor installed instrument bases through locked chemistry agreements that defend consumable revenue against digital PCR substitution. Prioritize backward integration into phosphoramidite synthesis to insulate margin structures from German and Japanese chemical supplier pricing power. Expand cloud-connected reagent inventory systems to automate probe replenishment and deepen subscription stickiness. For New Entrants and Emerging Players: CRISPR-enhanced probe specificity offers a technology-first wedge into infectious disease screening applications where false-positive reduction commands premium positioning. Target point-of-care molecular testing in India's tier-2 and tier-3 cities where CDSCO regulatory harmonization with WHO standards lowers entry barriers. Pursue pharmacogenomic probe panel partnerships with community hospital formularies seeking CYP450 and TPMT variant detection capabilities. For Investors and Strategic Acquirers: Platform-centric diagnostic conglomerates are the most active acquirer in this space, seeking consumable revenue streams to offset instrument placement costs. Five-to-ten year viability favors targets with FDA breakthrough-designated companion diagnostics and pharmaceutical co-development pipelines. Watch for NMPA registration queue priority shifts as signal of Chinese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Locked Chemistry Agreement Expansion | Defends reagent revenue against digital PCR instrument substitution in United States hospital systems. |
| Phosphoramidite Synthesis Backward Integration | Reduces exposure to German and Japanese chemical supplier price volatility for probe manufacturers. |
| Cloud-Connected Reagent Inventory Deployment | Automates probe replenishment before stockouts occur in Bavarian laboratory cooperatives. |
| NMPA Accelerated Review Pathway Utilization | Compresses registration timelines for innovative molecular diagnostics in Shanghai municipal health systems. |
| Pharmaceutical Co-Development Partnership | Captures companion diagnostic mandates tied to EGFR and BRAF targeted therapy approvals. |
Study Parameters
Multiple input streams — primary interviews with diagnostic laboratory directors, regulatory affairs specialists, and hospital procurement managers; secondary validation through FDA 510(k) filings, EMA IVDR submission databases, and NMPA registration records; plus trade data on phosphoramidite imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by probe chemistry type, detection technology platform, clinical application area, and end-user procurement authority level. CAGRs were derived from instrument installed base expansion rates and consumable pull-through assumptions, incorporating companion diagnostic approval velocity and NMPA queue priority shifts as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA IVDR evidentiary requirement evolution and phosphoramidite supply concentration risk. Forecasts reflect documented assumptions on regulatory pathway efficiency and reagent subscription model adoption. Material deviation in FDA Pre-Cert program expansion or Chinese provincial tendering centralization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
D-Dimer Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market