
 Antimetabolite Drugs Market | 2026-2036
Antimetabolite Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antimetabolite Drugs Market Outlook
Project finance tied to hospital system expansion is narrowing the competitive field for antimetabolite suppliers, as smaller manufacturers lack the balance-sheet depth to underwrite long-term supply contracts with consolidated purchasing networks. F. Hoffmann-La Roche AG anchors its position through captive biologics manufacturing and deep oncology franchise integration. Pfizer Inc. leverages global distribution infrastructure to sustain volume leadership across intravenous and oral delivery formats. Novartis AG competes through specialized positioning in transplant immunosuppression and targeted cancer therapy combinations.
Antimetabolite drugs are structural analogs of natural metabolites that disrupt nucleic acid synthesis by inhibiting key enzymes in folate, pyrimidine, or purine metabolic pathways, typically formulated as injectable solutions or oral tablets with stringent sterility and stability requirements. Their primary commercial purpose centers on interrupting rapid cell division in malignant tissues and modulating immune responses in graft rejection or autoimmune conditions. The cancer treatment application dominates current revenue pools, while autoimmune disorders represents the fastest-growing segment as rheumatology practices expand off-label and approved uses of methotrexate and azathioprine. Intravenous delivery mode commands premium pricing due to hospital administration requirements, though oral formulations are gaining share in maintenance therapy settings where homecare and clinic channels reduce total cost of care.
FDA oncology center review standards, EMA centralized marketing authorization procedures, and WHO essential medicines list inclusion criteria collectively shape product development priorities and market access trajectories for antimetabolite portfolios. These frameworks determine clinical trial endpoints, manufacturing quality benchmarks, and reimbursement eligibility across jurisdictions, directly influencing which molecules achieve commercial scale. Stakeholders must monitor evolving biosimilar substitution policies and reference pricing mechanisms, as these regulatory instruments will determine whether originator manufacturers retain pricing power or cede margin to lower-cost alternatives in hospital and clinic procurement.
Market Dynamics
Hospital purchasing consolidation is compressing supplier margins for antimetabolite manufacturers, as integrated delivery networks leverage multi-year volume commitments to extract price concessions that smaller producers cannot match.
Growth Catalysts
- FDA Accelerated Approval:Compressed review timelines for oncology therapies enable faster commercialization of novel antimetabolite entities, reducing time-to-revenue for developers targeting unmet cancer indications.
- Homecare Infusion:Expansion of ambulatory chemotherapy administration shifts patient volumes from inpatient to outpatient settings, extending maintenance therapy durations and prescription refill frequencies for oral formulations.
- Autoimmune Protocol Expansion:Rheumatology practices are broadening methotrexate and azathioprine prescribing for lupus and psoriatic arthritis, creating volume growth outside traditional oncology revenue pools.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for purine analogs clusters in specific Asian manufacturing zones, exposing formulators to single-source disruption risks and geopolitical trade friction.
- Reimbursement Compression:Medicare's hospital outpatient prospective payment system bundles antimetabolite costs into procedure-based rates, limiting separate drug pricing flexibility for infused therapies.
- Biosimilar Substitution:EMA reference pricing mechanisms and US interchangeable biosimilar designations threaten originator pricing power for folate antagonists nearing patent expiry.
Strategic Opportunities
- India Oncology Infrastructure:CDSCO streamlined approval pathways and government-funded cancer hospital expansion create accessible volume for cost-optimized oral antimetabolite portfolios.
- Companion Diagnostic Pairing:Pharmacogenomic testing integration enables targeted thiopurine dosing based on TPMT enzyme activity, differentiating premium formulations through personalized therapy positioning.
- Specialty Pharmacy Networks:Direct distribution through limited-distribution specialty pharmacies bypasses traditional wholesale markups and captures patient adherence data for manufacturer risk-sharing contracts.
Industry Challenges
- Sterile Manufacturing Capacity:Injectable antimetabolite production requires EU GMP Annex 1 compliant aseptic filling lines, and qualified facility scarcity extends lead times for commercial batch release.
- Cold Chain Integrity:Temperature excursions during last-mile distribution to infusion centers degrade product stability, necessitating validated packaging investments that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimetabolite Drugs Market |
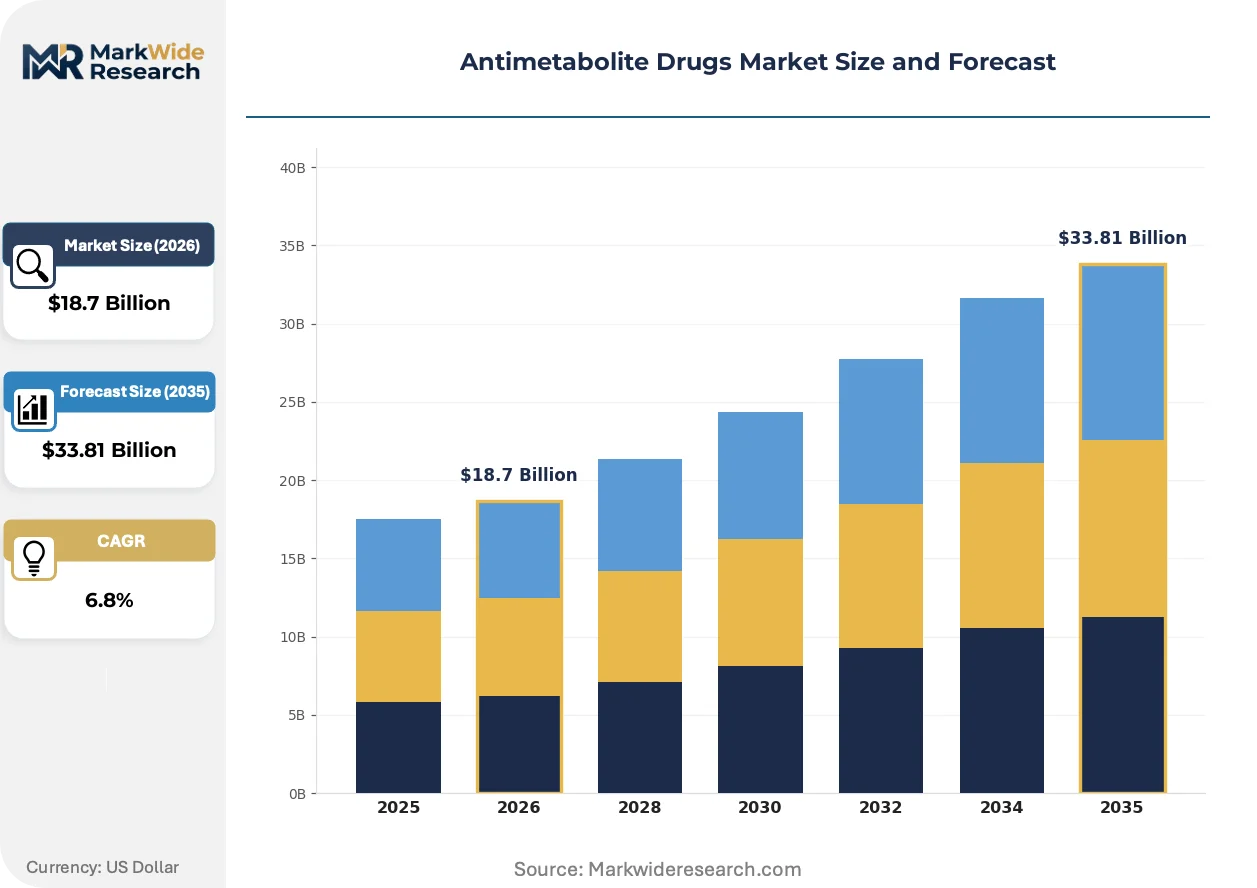
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cytarabine, Gemcitabine, Azathioprine, Methotrexate Application: Cancer Treatment, Autoimmune Disorders, Organ Transplantation, Rheumatoid Arthritis Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Homecare, Healthcare Organizations |
| Companies Covered | F. Hoffmann-La Roche AG, Pfizer Inc., Novartis AG, Bristol-Myers Squibb, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Sanofi S.A., Amgen Inc., AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimetabolite Drugs Market Strategic Shifts
Antimetabolite development is pivoting toward precision-delivery mechanisms that minimize off-target toxicity while preserving cytotoxic efficacy against rapidly dividing malignant cells.
Antibody-drug conjugates incorporating tubulin-binding or DNA-alkylating payloads are migrating from early-phase hematologic indications into solid tumor protocols, with breast and lung cancer centers adopting these constructs as second-line alternatives to conventional antimetabolite monotherapy. This migration is compressing market share for standalone pyrimidine analogs in metastatic settings where combination regimens demonstrate superior progression-free survival.
EMA's updated Good Manufacturing Practice Annex 1 requirements for sterile medicinal products mandate continuous environmental monitoring and barrier technology upgrades, forcing contract manufacturers to retool filling operations or exit the cytotoxic injectables segment entirely. Facilities serving European hospital networks are prioritizing isolator-based aseptic processing to maintain supply eligibility under the revised quality framework.
Oncology procurement directors are consolidating antimetabolite purchasing through group purchasing organizations that negotiate sole-source or dual-source agreements, displacing fragmented multi-vendor sourcing that previously characterized hospital pharmacy operations. This concentration is most visible in United States integrated delivery networks spanning multiple states, where formulary standardization across member hospitals reduces therapeutic substitution variability.
Antimetabolite Drugs Market Segmentation
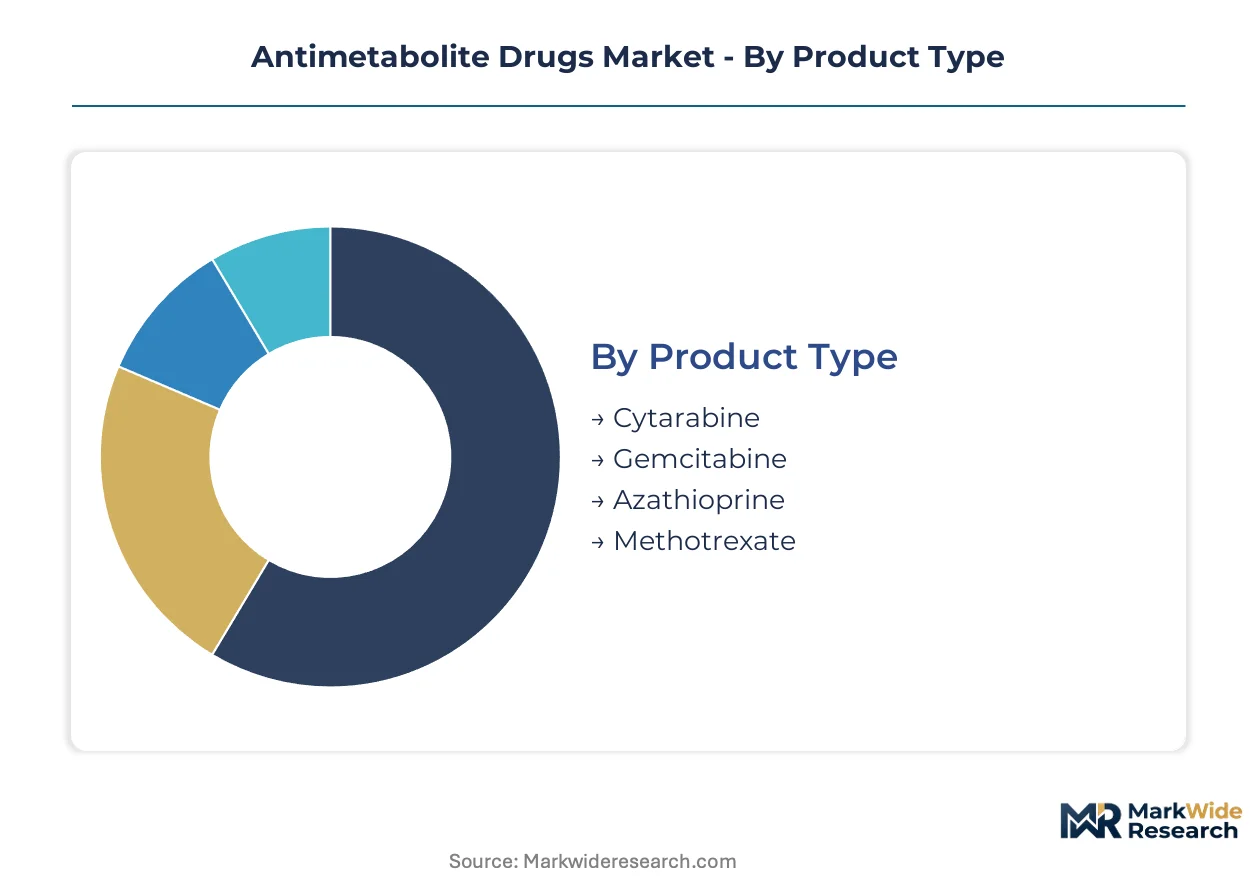
Antimetabolite drug segmentation reveals distinct procurement cycles and margin profiles across molecular categories, with hospital formularies prioritizing molecules by patent status and generic availability. Understanding these segment dynamics enables suppliers to align manufacturing capacity with demand velocity and reimbursement trajectories.
Product Type:
Cytarabine and gemcitabine turn inventory fastest in acute leukemia protocols where treatment cycles compress to 7-10 days, while azathioprine and methotrexate sit on pharmacy shelves for months in chronic maintenance settings.
- Cytarabine:Pyrimidine nucleoside analog with rapid cellular uptake kinetics and short plasma half-life requiring frequent dosing. Demand concentrates in United States academic medical centers running induction protocols for acute myeloid leukemia, constrained by API manufacturing bottlenecks in Asian supply zones.
- Gemcitabine:Deoxycytidine analog with extended intracellular retention and broader solid tumor applicability. United States community oncology practices favor this agent for pancreatic and non-small cell lung cancer regimens, driving volume through Medicare Part B reimbursement pathways.
- Azathioprine:Purine analog prodrug converted to 6-mercaptopurine for immunosuppression in transplant maintenance.
- Methotrexate:Folate antagonist with established rheumatology off-label use and pediatric leukemia protocols.
Cytarabine anchors the volume base while gemcitabine gains share at the steepest rate as solid tumor indications expand.
Application:
Cost tier stratification separates high-price oncology indications from lower-margin immunology uses, with organ transplantation occupying a mid-tier reimbursement position.
- Cancer Treatment:Cytotoxic protocols targeting rapid cell division in hematologic and solid malignancies. United States hospital outpatient departments command premium pricing for infused regimens, though bundled payment models compress per-dose margins.
- Autoimmune Disorders:Off-label and approved uses in lupus, psoriasis, and inflammatory bowel disease. Rheumatology practices in Germany and France drive volume growth as EMA guidelines broaden methotrexate first-line positioning.
- Organ Transplantation:Chronic immunosuppression to prevent graft rejection in kidney and liver transplants.
- Rheumatoid Arthritis:Specific autoimmune indication with established biologic sequencing protocols.
Cancer treatment anchors the volume base while autoimmune disorders climb the fastest as rheumatology prescribing expands.
Delivery Mode:
Margin structure inverts between hospital-administered parenterals and patient-managed orals, with subcutaneous formats capturing adherence premiums in homecare settings.
- Intravenous:Infused formulations requiring aseptic compounding and oncology nursing supervision. United States infusion centers bill under Medicare's hospital outpatient prospective payment system, embedding drug costs into procedure-based rates.
- Oral:Tablet and capsule formats enabling home administration and extended maintenance therapy. Specialty pharmacy networks in the United States capture patient adherence data through direct distribution, bypassing traditional wholesale markups.
- Subcutaneous:Self-injectable presentations for methotrexate in rheumatoid arthritis.
- Intramuscular:Depot formulations with extended release kinetics for transplant immunosuppression.
Intravenous anchors the volume base while oral climbs the fastest as homecare channels expand.
End User:
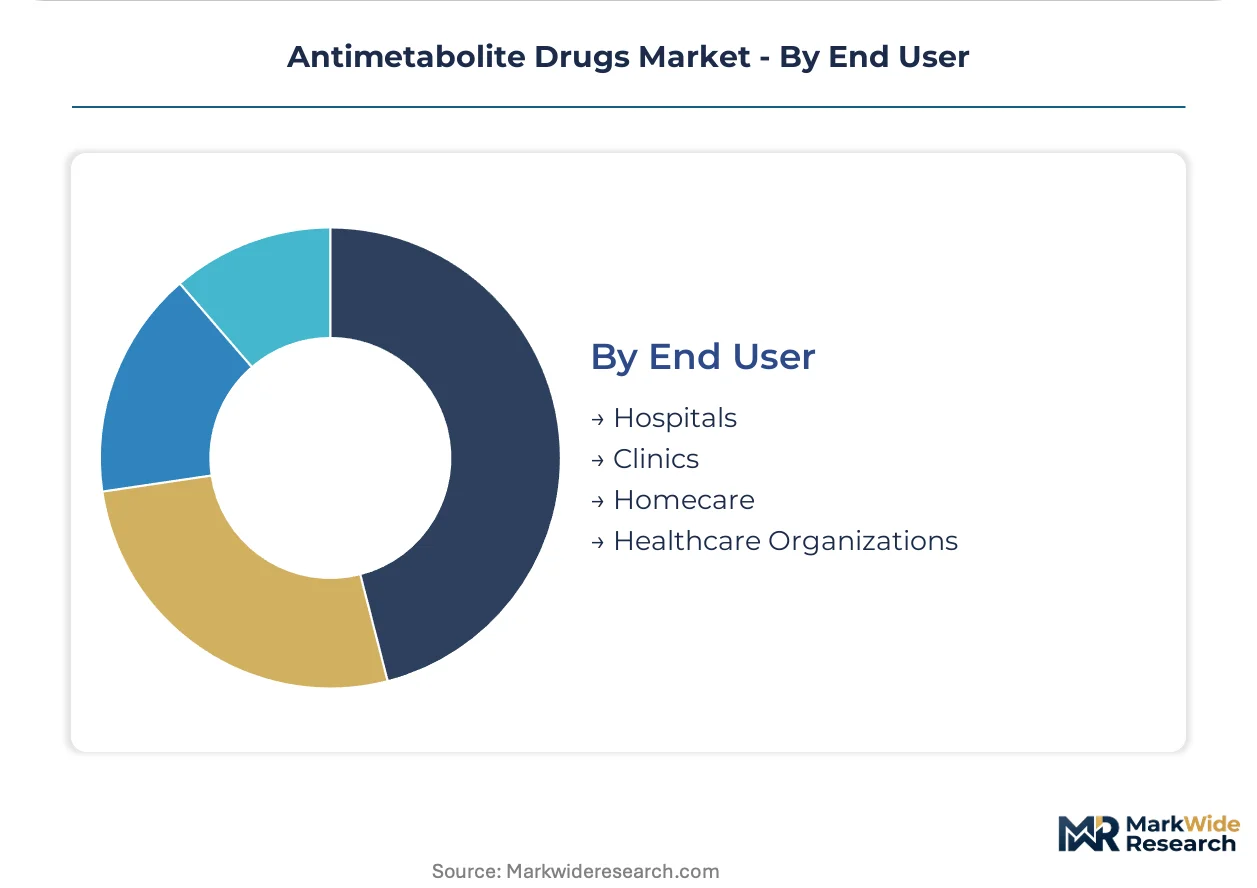
Customer concentration shapes contract terms, with consolidated United States hospital systems extracting volume discounts that fragment the supplier base.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees standardizing formularies across multi-state member facilities. United States group purchasing organizations negotiate sole-source agreements that displace fragmented multi-vendor sourcing.
- Clinics:Ambulatory oncology and rheumatology practices with lower inventory carrying costs and faster generic substitution.
- Homecare:Infusion nursing services and specialty pharmacy direct-to-patient distribution.
- Healthcare Organizations:Accountable care organizations and managed care entities with population-based contracting.
Hospitals anchor the volume base while homecare climbs the fastest as ambulatory administration expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in antimetabolite drugs tilt toward net imports in high-consumption markets while API manufacturing concentrates in select Asian supply zones. Finished formulation trade runs through specialized cold-chain logistics networks serving hospital procurement systems.
United States
Medicare Part B reimbursement drives infused antimetabolite procurement through hospital outpatient departments, with bundled payment models embedding drug costs into procedure rates. FDA accelerated approval pathways compress development timelines for novel oncology entities. The Texas Medical Center in Houston anchors clinical trial enrollment for acute leukemia protocols using cytarabine-based induction regimens.
Germany
EMA centralized marketing authorization procedures enable simultaneous market access across EU member states for new molecular entities. Reference pricing mechanisms for folate antagonists threaten originator margins as interchangeable biosimilars gain formulary acceptance. The Rhine-Main biopharma cluster around Frankfurt hosts sterile manufacturing facilities supplying EU hospital networks with EU GMP Annex 1 compliant injectables.
Japan
PMDA oncology review standards emphasize progression-free survival endpoints that favor combination regimens incorporating antimetabolite backbones. National health insurance reimbursement lists determine hospital formulary placement with biennial price revisions. The Kanto region surrounding Tokyo concentrates academic medical center demand for gemcitabine in pancreatic cancer protocols.
India
CDSCO streamlined approval pathways and government-funded cancer hospital expansion create accessible volume for cost-optimized oral portfolios. PLI scheme incentives for active pharmaceutical ingredient manufacturing aim to reduce import dependence for purine analogs. The Hyderabad-Visakhapatnam corridor hosts contract manufacturing organizations producing cytarabine API for export to regulated markets.
Switzerland
Swissmedic marketing authorization procedures align with EMA standards while permitting earlier access for innovative therapies through temporary authorization schemes. The country's pharmaceutical value chain concentrates on high-margin biologics and specialty generics rather than commodity antimetabolites. The Basel biotech cluster focuses on antibody-drug conjugate development that displaces standalone antimetabolite use in metastatic settings.
Antimetabolite Drugs Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API manufacturing and sterile formulation. The supplier base stratifies between multinational oncology franchises with captive biologics manufacturing and regional formulators dependent on outsourced active pharmaceutical ingredients. Three archetypes dominate: integrated pharmaceutical conglomerates with global distribution infrastructure, mid-scale generic specialists focused on cost-optimized oral portfolios, and contract development and manufacturing organizations serving sterile injectable demand. Competitive moves center on backward integration into API supply and specialty pharmacy network partnerships that bypass traditional wholesale channels.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche AG, Pfizer Inc., and Novartis AG exemplify divergent strategic positioning. Roche anchors its presence through deep oncology franchise integration and captive biologics manufacturing capabilities. Pfizer occupies a scale-driven position leveraging global distribution infrastructure across intravenous and oral delivery formats. Novartis sits within specialized immunology and targeted therapy combinations, particularly in transplant maintenance protocols. These three entities represent distinct competitive vectors rather than direct substitution, with each emphasizing different molecular categories and clinical settings.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Pfizer Inc. |
| Novartis AG |
| Bristol-Myers Squibb |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Amgen Inc. |
| AstraZeneca plc |
| Others |
Value Chain & Pricing Dynamics
EU GMP Annex 1 compliant aseptic filling undercapacity across the Rhine-Main biopharma cluster is forcing formulators to bid up slot premiums, compressing margins for oral portfolios while concentrating pricing power among isolator-equipped contract manufacturers serving hospital networks.
Pricing Analysis
Hospital purchasing consolidation anchors three-tier pricing structure across premium, standard, and economy levels in infused antimetabolites, with FDA accelerated approval status and EU GMP certification grade driving differentiation. Originators with companion diagnostic pairings command premium positioning against interchangeable biosimilars facing EMA reference pricing pressure. Cost compression in standard-tier folate antagonists is intensifying because Medicare bundled payment models embed drug costs into procedure-based rates. Community oncology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical efficacy over per-dose economics.
Supply Chain Analysis
Upstream pyrimidine and purine analog API production draws from India, China, and select European manufacturing zones, with the Hyderabad-Visakhapatnam corridor hosting cytarabine active pharmaceutical ingredient output for regulated export markets. Key inputs include nucleoside precursors, folate derivatives, and sterile filtration membranes. Single-source vulnerability in Asian API manufacturing exposes formulators to geopolitical trade friction and customs delays. Distribution runs through validated cold-chain logistics networks serving consolidated hospital group purchasing organizations and specialty pharmacy direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimetabolite drug development sits in early-cycle expansion as rheumatology practices broaden methotrexate and azathioprine prescribing for lupus and psoriatic arthritis, extending addressable volume beyond traditional oncology revenue pools.
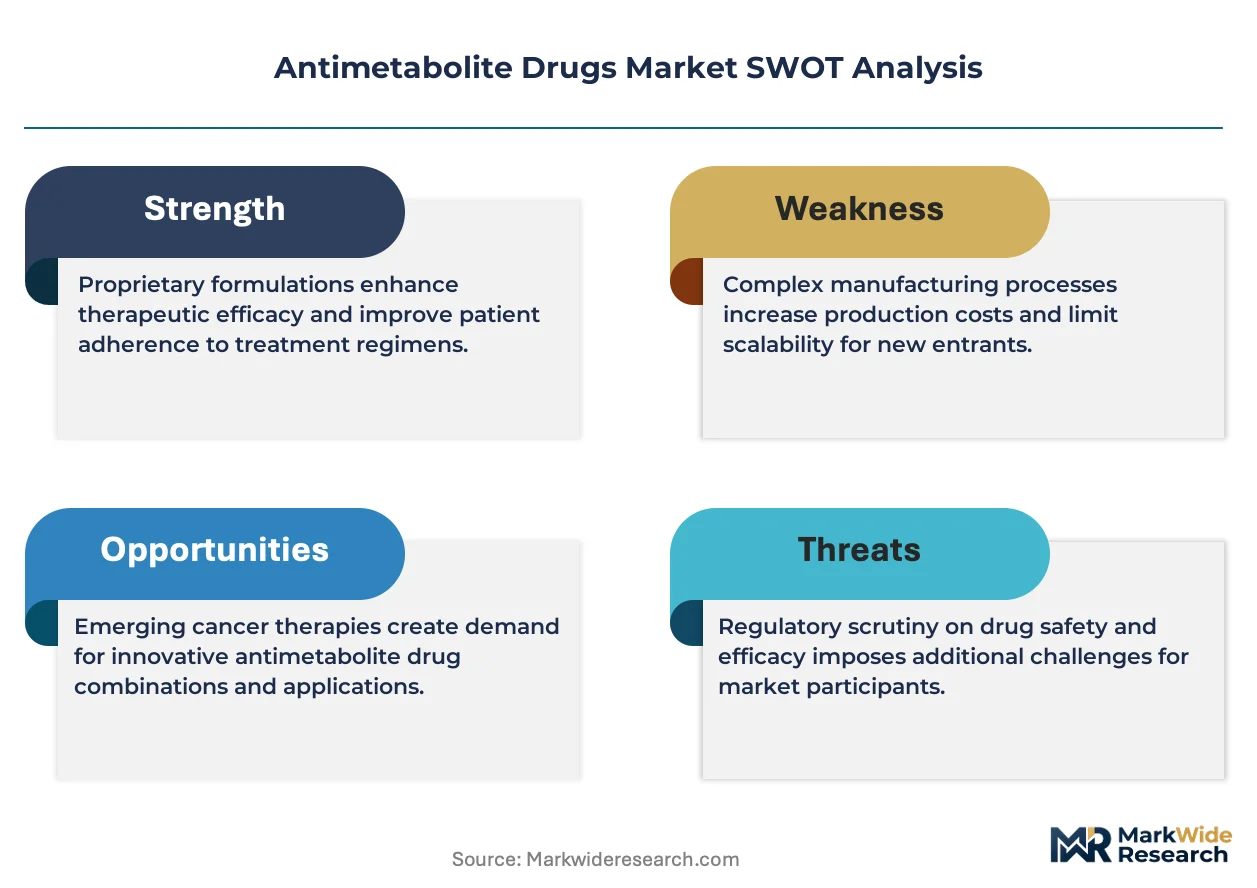
For Market Incumbents: Harden sterile manufacturing capacity positions through EU GMP Annex 1 isolator upgrades or exclusive contract manufacturing partnerships, defending against biosimilar substitution threats in folate antagonists nearing patent expiry while deepening oncology franchise integration through companion diagnostic pairings. For New Entrants and Emerging Players: Pursue CDSCO streamlined approval pathways for cost-optimized oral portfolios targeting India's government-funded cancer hospital expansion, with specialty pharmacy network partnerships offering the most penetrable go-to-market angle for bypassing traditional wholesale markups and capturing adherence data. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterile injectable manufacturing as barrier technology upgrades and continuous environmental monitoring mandates reshape facility economics, favoring long-term positions in contract development and manufacturing organizations with qualified aseptic filling lines and established hospital network contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | TPMT pharmacogenomic testing differentiation enables premium thiopurine dosing protocols in academic medical centers. |
| Specialty Pharmacy Network Partnership | Direct distribution bypasses wholesale markups while capturing patient adherence data for risk-sharing contracts. |
| EU GMP Annex 1 Compliance Investment | Isolator-based aseptic processing maintains supply eligibility under EMA revised sterile manufacturing frameworks. |
| India CDSCO Regulatory Pathway | Streamlined approvals unlock government-funded cancer hospital volume for cost-optimized oral portfolios. |
| Homecare Infusion Channel Expansion | Ambulatory chemotherapy administration extends maintenance therapy durations and prescription refill frequencies. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with oncology franchise directors, hospital formulary managers, regulatory affairs leads, and specialty pharmacy network operators; combined with secondary validation against FDA accelerated approval filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov enrollment data, and Medicare Part B reimbursement schedules. Bottom-up demand modeling across molecular categories and administration routes triangulated with top-down market sizing.
Forecast inputs span treatment line positioning, dosage form segmentation, regional regulatory cluster dynamics, and patient population eligibility criteria across the analysis window. CAGRs derive from fitted growth curves incorporating oncology protocol adoption rates, rheumatology prescribing expansion, and biosimilar penetration assumptions. Sterile manufacturing capacity utilization and API supply concentration patterns inform supply-side constraints.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, EMA reference pricing implementation, or Asian API trade flows would shift the trajectory. Cross-checking against hospital procurement database benchmarks and GPO contract award disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Postmenopausal Vaginal Atrophy Drugs Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Veterinary Pain Management Drugs Market