
 Erdosteine Market | 2026-2036
Erdosteine Market Size, Share, and Industry Trends Forecast 2026-2036
Erdosteine Market Analysis
REACH compliance is expanding the cost-of-entry calculus for erdosteine manufacturers serving European patients. Hikma Pharmaceuticals leverages its vertically integrated API-to-dosage capabilities to sustain cost advantages across regulated markets. Hanmi Pharmaceuticals anchors its position through specialized respiratory R&D pipelines. Recipharm AB competes as a contract development and manufacturing organization with dedicated facilities for mucolytic production.
Erdosteine is a thiol derivative with a molecular structure featuring four sulfur atoms, manufactured through condensation of cysteine with glyceraldehyde followed by cyclization, primarily functioning as a mucolytic agent that breaks disulfide bonds in mucus glycoproteins to reduce viscosity in chronic respiratory conditions. Tablets dominate prescription volumes in hospital and retail pharmacy channels where physician preference favors fixed-dose oral administration. Syrups capture expanding share in pediatric and geriatric home healthcare segments where swallowing difficulties drive formulation flexibility. Mucolytic therapy applications lead clinical utilization while cough management represents the fastest-growing indication as prescribers seek alternatives to opioid-based suppressants.
EMA marketing authorization requirements and FDA active pharmaceutical ingredient inspection protocols shape quality benchmarks for cross-border erdosteine trade. India's CDSCO and China's NMPA impose additional bioequivalence standards on generic entrants that filter substandard suppliers from tender participation. Stakeholders must monitor evolving pharmacovigilance reporting obligations and real-world evidence requirements that will determine which manufacturers retain formulary access across priority markets.
Market Dynamics
EMA's tightened pharmacovigilance requirements for mucolytic APIs are forcing manufacturers to restructure quality management systems around real-world evidence collection. This regulatory pivot favors API-to-dosage integrators with captive analytical capabilities over pure-play suppliers dependent on contract laboratories.
Growth Catalysts
- REACH compliance expansion:ECHA's updated substance evaluation protocols are filtering substandard API manufacturers from European tender participation, concentrating volume among qualified suppliers with dedicated respiratory production lines.
- COPD prevalence in Mediterranean markets:Italy's aging patient population sustains prescription volumes for fixed-dose erdosteine tablets through hospital formulary contracts.
- Thiol chemistry process optimization:Advances in cysteine condensation and cyclization reactions are reducing batch-to-batch variability in sulfur-containing mucolytic synthesis.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in India and China create geographic vulnerability for European formulators dependent on long-haul import routes.
- Substitution threat from carbocysteine:Alternative mucolytic agents with established reimbursement codes in France and Germany compete for physician prescribing preference in chronic bronchitis management.
- REACH registration cost burden:ECHA's tonnage-based fee structure and extended safety data requirements impose fixed cost barriers that disproportionately affect low-volume specialty API entrants.
Strategic Opportunities
- Pediatric syrup formulation expansion:Swallowing difficulties in geriatric home healthcare segments create demand for liquid dosage alternatives to standard tablets.
- CDSCO bioequivalence pathway:India's tightened generic approval standards present first-mover advantage for manufacturers with pre-validated analytical methods and local clinical trial infrastructure.
- Real-world evidence integration:EMA's evolving post-authorization study requirements reward sponsors with existing patient registry relationships and pharmacovigilance databases.
Industry Challenges
- Analytical method transfer complexity:Cross-border technology transfers for sulfur-specific assay validation face timeline compression as regulatory filing deadlines tighten.
- Multinational inspection coordination:Synchronized FDA and EMA site visits require dedicated quality assurance staffing that strains mid-cap API manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erdosteine Market |
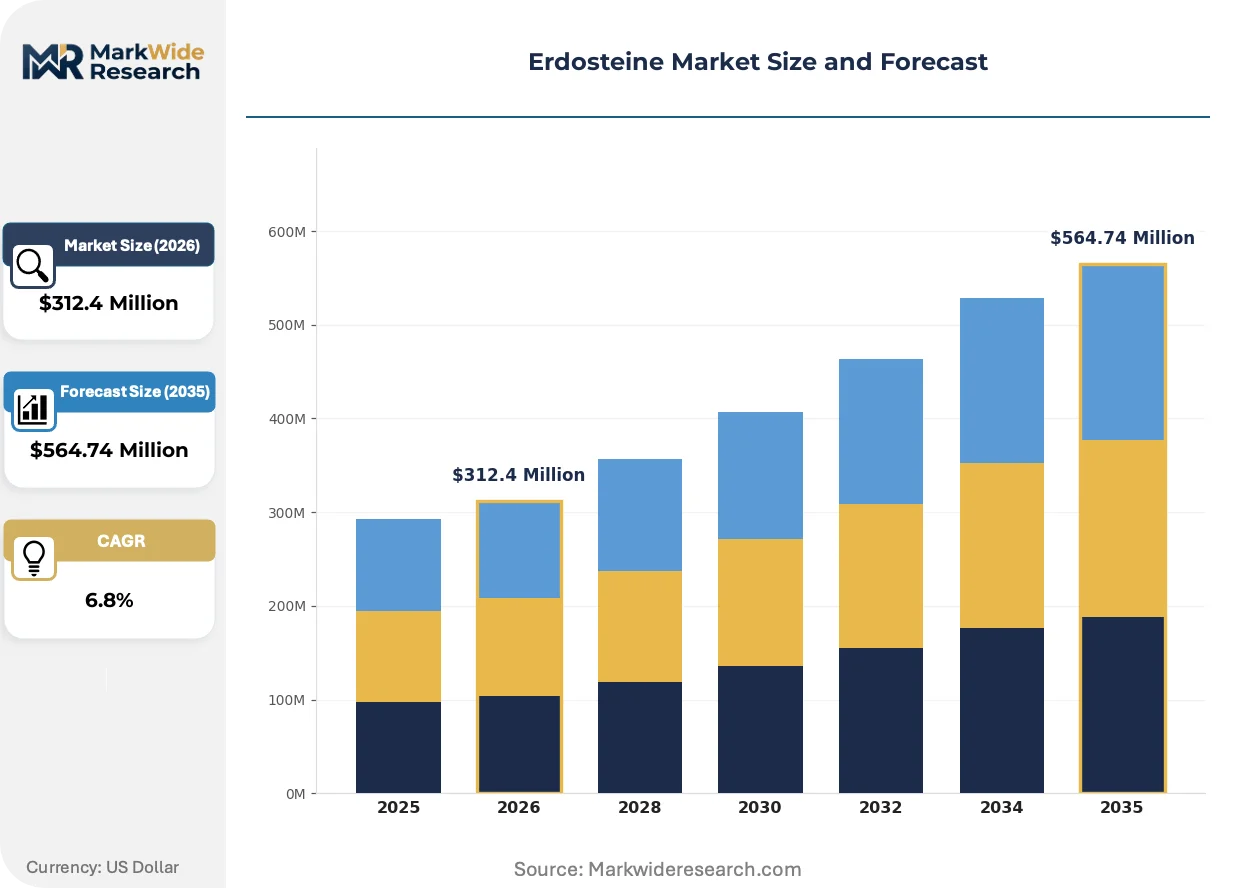
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Syrups, Granules End User: Hospitals, Clinics, Home Healthcare, Retail Pharmacies Application: Chronic Obstructive Pulmonary Disease, Respiratory Infections, Mucolytic Therapy, Cough Management Distribution Channel: Direct Sales, Online Pharmacies, Wholesalers, Distributors |
| Companies Covered | Hikma Pharmaceuticals, Hanmi Pharmaceuticals, Recipharm AB, Edmond Pharma, Berchemia Healthcare, Delta Finochem Pvt. Ltd., Shandong Luoxin Pharmaceutical Group Stock Co., Ltd., Zhejiang Kangle Pharmaceutical, Alitair Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erdosteine Market Emerging Trajectories
Continuous manufacturing technologies are displacing batch processing in thiol derivative synthesis, compressing production cycles while tightening impurity profiles. This shift demands reconfigured facility layouts and real-time release testing capabilities that alter capital deployment patterns across the supply base.
Process analytical technology is integrating in-line spectroscopic monitoring into cysteine condensation reactions, enabling immediate deviation correction during cyclization. Italian formulators with hospital contract manufacturing relationships are adopting these systems fastest, driven by EMA's emphasis on parametric release for respiratory APIs. The technology is integrating quality assurance directly into production workflows, reducing traditional quarantine inventory buffers.
REACH authorization timelines for sulfur-containing substances are extending pre-market preparation phases, forcing manufacturers to front-load toxicology investment. ECHA's substance evaluation criteria now require enhanced respiratory sensitization data that previously fell outside standard mucolytic registration packages. European API suppliers are responding by consolidating dossier preparation functions and establishing dedicated regulatory science units.
Hospital procurement consolidation is compressing supplier rosters for fixed-dose respiratory therapies, concentrating volume among manufacturers with integrated formulation and packaging capabilities. Italian regional health authorities are unbundling tender awards by dosage form, favoring suppliers with dual tablet and syrup production lines. This pattern is most visible in Lombardy and Veneto, where centralized purchasing for chronic disease management programs has eliminated single-product vendors from qualified supplier lists.
Erdosteine Market Segmentation
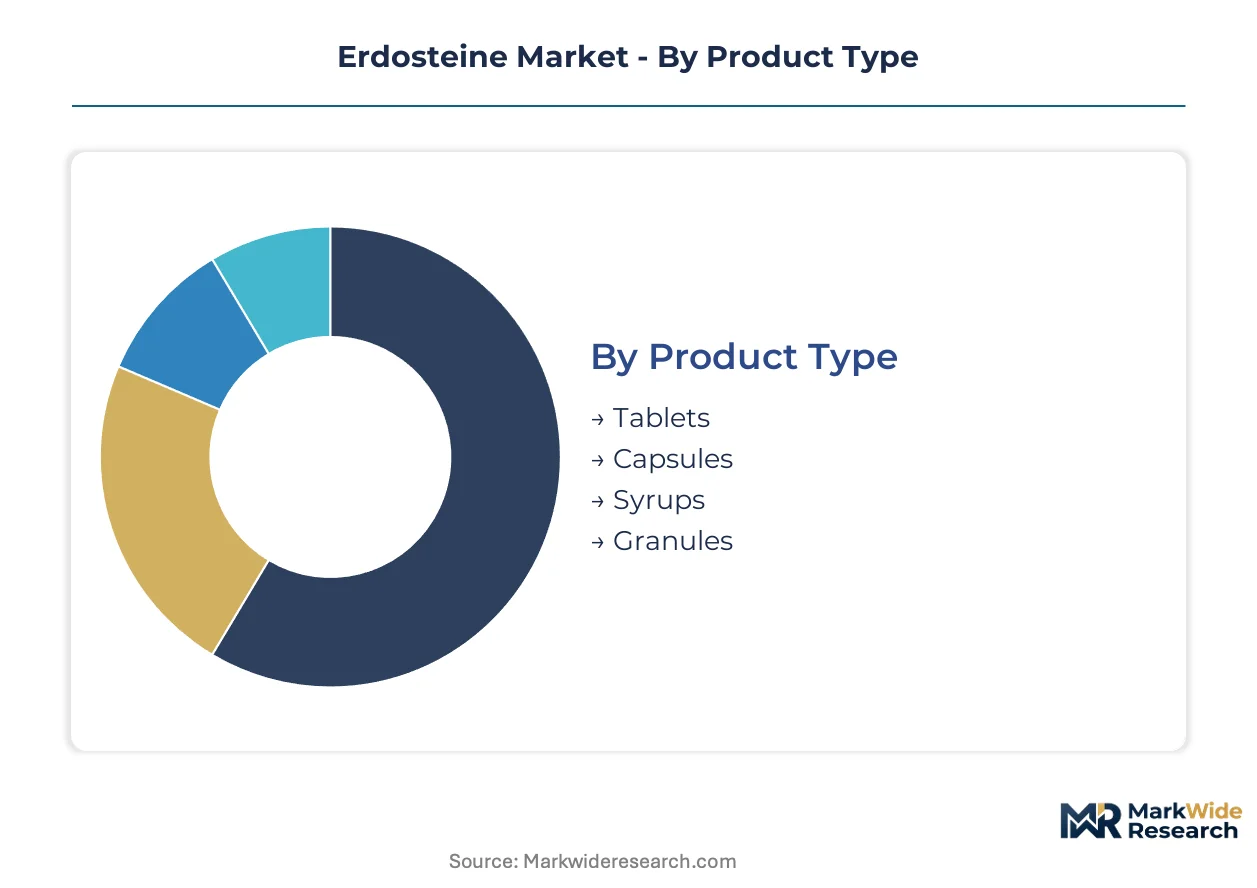
Erdosteine's formulation diversity creates distinct competitive arenas where manufacturing capabilities and regulatory positioning determine segment-specific access. Hospital procurement consolidation and home healthcare expansion are reshaping volume flows across dosage forms and channels.
Product Type:
Tablet formulations retain formulary dominance as physicians prioritize fixed-dose reliability in chronic respiratory management, while liquid alternatives capture upgrade demand from aging populations with swallowing limitations.
- Tablets:Compressed solid dosage forms containing erdosteine as the active pharmaceutical ingredient with standard excipient matrices. Hospital formulary contracts in Italy and Spain sustain prescription volumes where EMA marketing authorization requirements favor established solid oral manufacturers. Batch-to-batch consistency in thiol content drives supplier selection for chronic obstructive pulmonary disease maintenance therapy.
- Syrups:Aqueous liquid formulations with viscosity-adjusted rheology for pediatric and geriatric administration. Home healthcare segments in Mediterranean markets drive demand as family caregivers seek alternatives to tablet crushing. EMA's parametric release emphasis rewards manufacturers with in-line spectroscopic monitoring during liquid fill operations.
- Capsules:Gelatin or HPMC shell enclosures containing erdosteine powder or granules. Retail pharmacy channels in markets with pharmacist compounding traditions favor this format for dose flexibility.
- Granules:Free-flowing particulate preparations for reconstitution prior to administration. Pediatric specialists in hospital settings prescribe this format for precise weight-based dosing.
Tablets sit at the top of the volume ranking, with syrups climbing the fastest.
End User:
Cost tier stratification separates acute intervention settings from maintenance therapy environments, with reimbursement codes and procurement mechanisms diverging sharply across institutional and retail channels.
- Hospitals:Acute care institutions with centralized pharmacy operations and formulary committees. Italian regional health authorities consolidate tender awards for respiratory therapeutics, concentrating volume among suppliers with dedicated mucolytic production lines. EMA pharmacovigilance requirements for post-authorization studies shape long-term contract terms.
- Home Healthcare:Community-based chronic disease management programs and family caregiver settings. Mediterranean aging demographics sustain demand for liquid formulations where swallowing difficulties limit tablet adherence. Reimbursement pathway complexity varies across national health systems.
- Clinics:Outpatient respiratory specialist practices with direct prescribing authority. Pulmonologist preference for fixed-dose tablets drives prescription patterns in chronic bronchitis management.
- Retail Pharmacies:Community dispensaries with patient counseling obligations and generic substitution protocols. CDSCO bioequivalence standards in India filter substandard generic entrants from tender participation.
Hospitals command the largest prescription share, with home healthcare expanding most quickly.
Application:
Maturity gradients separate well-established mucolytic indications from emerging cough management protocols where prescribers seek alternatives to opioid-based suppressants.
- Mucolytic Therapy:Primary indication targeting disulfide bond reduction in mucus glycoproteins to decrease respiratory secretion viscosity. Standard-of-care status in chronic obstructive pulmonary disease maintenance protocols across European markets. REACH compliance for sulfur-containing APIs concentrates supply among qualified manufacturers with dedicated respiratory production lines.
- Cough Management:Emerging application as prescribers reduce opioid-based suppressant prescriptions. Italian and Spanish physicians lead adoption in geriatric populations where sedation risk limits alternative options. EMA's tightened pharmacovigilance requirements favor sponsors with existing patient registry infrastructure.
- Chronic Obstructive Pulmonary Disease:Long-term maintenance therapy for progressive airflow limitation. Hospital formulary contracts in Mediterranean markets sustain volume for fixed-dose tablet presentations.
- Respiratory Infections:Adjunctive therapy during acute bacterial or viral lower respiratory tract infections. Prescription patterns vary with seasonal influenza and pneumonia epidemiology.
Mucolytic therapy holds the established volume base, with cough management gaining share fastest.
Distribution Channel:
Supply concentration in API production clusters shapes channel vulnerability, with geographic distance from Indian and Chinese manufacturers influencing inventory strategies across European formulators.
- Wholesalers:Regional pharmaceutical distributors with cold chain capabilities and batch traceability systems. Italian and Spanish hospital procurement consolidation drives volume through selected national wholesalers with EMA-compliant quality agreements.
- Direct Sales:Manufacturer-to-institution contracts bypassing intermediary distribution layers. Large hospital networks in Lombardy and Veneto negotiate directly with API-to-dosage integrators for respiratory therapeutics.
- Distributors:International traders with cross-border licensing and import authorization expertise. Long-haul routes from Indian API clusters create geographic vulnerability for European formulators dependent on maritime freight.
- Online Pharmacies:Digital dispensaries with prescription verification protocols and patient delivery logistics. Regulatory frameworks for remote pharmacy practice vary across European member states.
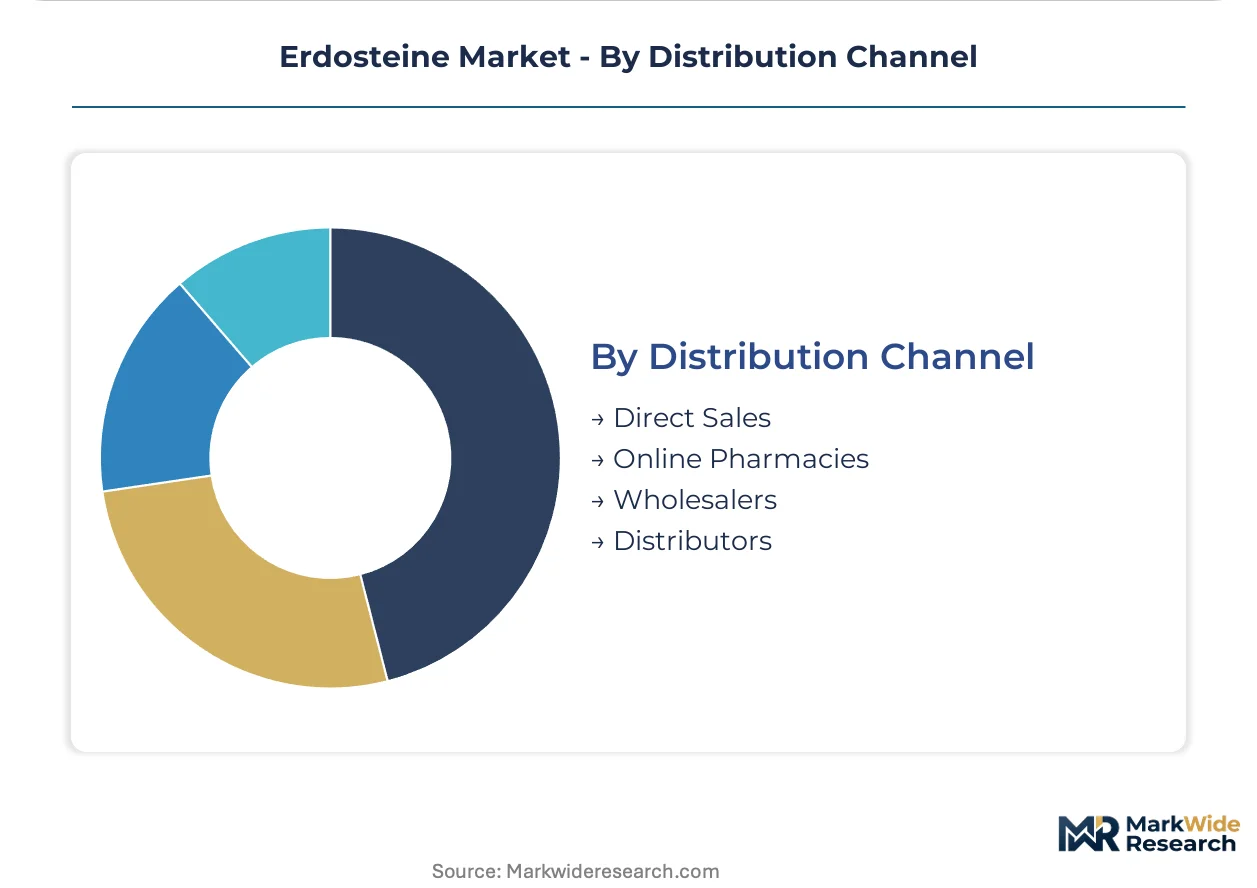
Wholesalers maintain the highest throughput position, with direct sales climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Erdosteine synthesis originated in Italian pharmaceutical laboratories during the 1980s, establishing Lombardy as the foundational production cluster before manufacturing capabilities dispersed across Mediterranean and Asian markets.
Italy
Chronic obstructive pulmonary disease prevalence among aging populations sustains prescription volumes for fixed-dose erdosteine tablets through hospital formulary contracts. EMA marketing authorization requirements favor established solid oral manufacturers with dedicated respiratory production lines. Lombardy and Veneto regional health authorities consolidate tender awards, eliminating single-product vendors from qualified supplier lists.
Spain
Geriatric home healthcare expansion drives demand for liquid syrup formulations where swallowing difficulties limit tablet adherence. EMA's parametric release emphasis rewards manufacturers with in-line spectroscopic monitoring during liquid fill operations. Catalonia and Madrid hospital networks negotiate directly with API-to-dosage integrators for respiratory therapeutics procurement.
China
NMPA bioequivalence standards on generic entrants filter substandard suppliers from tender participation, concentrating volume among qualified manufacturers. Cysteine condensation and cyclization reaction advances reduce batch-to-batch variability in sulfur-containing mucolytic synthesis. Shandong and Zhejiang provinces host active pharmaceutical ingredient production clusters serving European formulator import demand.
India
CDSCO tightened generic approval standards present first-mover advantage for manufacturers with pre-validated analytical methods and local clinical trial infrastructure. Long-haul maritime freight routes from Indian API clusters create geographic vulnerability for European formulators dependent on just-in-time inventory. Maharashtra and Gujarat pharmaceutical manufacturing zones specialize in thiol derivative export production.
Germany
Alternative mucolytic agents with established reimbursement codes compete for physician prescribing preference in chronic bronchitis management. ECHA's tonnage-based fee structure and extended safety data requirements impose fixed cost barriers affecting low-volume specialty API entrants. North Rhine-Westphalia chemical production corridors integrate REACH compliance into sulfur-containing substance manufacturing protocols.
Erdosteine Market Vendor Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive API-to-dosage capabilities. Market concentration favors manufacturers with dedicated respiratory production lines and established EMA marketing authorizations over pure-play API suppliers dependent on contract formulation relationships. Three archetypes dominate: integrated multinational pharmaceuticals, specialized respiratory CDMOs, and regional generic formulators with backward integration into thiol chemistry. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure hospital formulary contracts and regional tender awards.
Among vertically integrated multinationals, Hikma Pharmaceuticals and Hanmi Pharmaceuticals anchor the premium tier with established regulatory dossiers across European and Asian markets. Recipharm AB occupies a distinct position as a contract development and manufacturing organization with dedicated mucolytic production facilities. These three exemplify the capability spectrum required for sustained formulary access amid tightening pharmacovigilance and REACH compliance obligations.
| Leading Market Players |
|---|
| Hikma Pharmaceuticals |
| Hanmi Pharmaceuticals |
| Recipharm AB |
| Edmond Pharma |
| Berchemia Healthcare |
| Delta Finochem Pvt. Ltd. |
| Shandong Luoxin Pharmaceutical Group Stock Co., Ltd. |
| Zhejiang Kangle Pharmaceutical |
| Alitair Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Italian regional health authority tender unbundling by dosage form is forcing API-to-dosage integrators to maintain dual tablet-syrup production lines or face exclusion from qualified supplier lists, compressing margins for single-format manufacturers while rewarding versatile producers with formulary pricing power.
Pricing Analysis
Bundle-unbundle service splits separate API suppliers with captive formulation capabilities from pure-play manufacturers dependent on tolling relationships. Three-tier pricing structure across EMA-authorized, REACH-registered, and non-European suppliers reflects regulatory compliance grade and batch-to-batch thiol consistency. Pricing pressure stems from hospital procurement consolidation in Lombardy and Veneto, where direct manufacturer contracts bypass traditional wholesale markups. Generic formulators in India exhibit highest price sensitivity due to CDSCO bioequivalence investment requirements, while Italian hospital networks demonstrate lowest sensitivity where clinical preference overrides cost considerations.
Supply Chain Analysis
Dual-sourcing mandates from European formulators now require qualified backup suppliers for cysteine-derived APIs, extending qualification timelines and locking in incumbent relationships. Production gravity centers on India, China, and Italy, with Shandong and Zhejiang provinces hosting condensation-cyclization clusters and Maharashtra-Gujarat zones specializing in thiol derivative export. Raw material dependencies span pharmaceutical-grade cysteine, glyceraldehyde precursors, and sulfur reagents with specified oxidation profiles. Single-source vulnerability runs through maritime freight chokepoints connecting Indian API clusters to Mediterranean formulators. Distribution runs through national wholesalers with EMA-compliant quality agreements in Italy and Spain, supplemented by direct sales to consolidated hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH registration cost burdens in Europe create margin capture opportunities for manufacturers with pre-validated Indian clinical trial infrastructure and EMA-authorized Italian production assets.
For Market Incumbents: Anchor formulary position through backward integration into cysteine condensation chemistry and parametric release capabilities, defending against carbocysteine substitution threats in German and French reimbursement markets. Prioritize dual tablet-syrup production line investments to meet Italian regional health authority tender unbundling requirements. EMA pharmacovigilance database relationships represent the critical lever for post-authorization study compliance. For New Entrants and Emerging Players: Enter via CDSCO bioequivalence pathway in India, where tightened standards filter substandard competitors and create first-mover advantage for sponsors with local analytical infrastructure. Pediatric syrup formulations for Mediterranean home healthcare segments offer the most penetrable white space, given geriatric swallowing difficulties and family caregiver demand. Go-to-market angle should emphasize EMA parametric release readiness and real-world evidence collection capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap API-to-dosage integrators possessing captive thiol chemistry expertise and established EMA marketing authorizations across multiple dosage forms. Long-term viability hinges on regulatory moat sustainability over a 5-10 year window as REACH authorization timelines extend and hospital procurement consolidation accelerates. Signal to watch: Italian regional health authority tender award unbundling patterns and the elimination rate of single-product vendors from qualified supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thiol Chemistry | Captive cysteine condensation capabilities reduce batch variability and REACH compliance costs for European tender participation. |
| Dual Dosage Form Capacity Expansion | Parallel tablet and syrup production lines satisfy Italian regional health authority unbundled procurement requirements. |
| EMA Parametric Release Implementation | In-line spectroscopic monitoring during cyclization reactions accelerates release timelines and reduces quarantine inventory. |
| Real-World Evidence Infrastructure Buildout | Patient registry relationships and pharmacovigilance databases satisfy tightened post-authorization study obligations. |
| CDSCO Bioequivalence Pre-Validation | Pre-established analytical methods and local clinical trial infrastructure capture first-mover advantage in Indian generic approvals. |
Methodological Framework
Multiple input streams — regulatory dossier analysis, supply chain mapping, and procurement pattern assessment — were reconciled through bottom-up and top-down triangulation. Primary interviews with respiratory drug development executives, EMA regulatory affairs leads, Italian hospital formulary directors, and CDSCO compliance officers were cross-validated against secondary sources including EMA marketing authorization databases, REACH registration filings, CDSCO generic approval records, and Italian regional health authority tender documentation.
Data-stream reconciliation across volume and value dimensions employed segmentation modeling by dosage form, application indication, end-user channel, and regional regulatory cluster. CAGRs were derived through trend extrapolation and market sizing validation across the analysis window. Forecast inputs incorporated COPD epidemiology trajectories, REACH authorization timeline projections, and hospital procurement consolidation patterns in Mediterranean markets.
Inputs from EMA and CDSCO regulatory databases were available through the study window; gaps in real-time tender award data from Italian regional health authorities introduce uncertainty bands around market share allocations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market