
 Global Deep Brain Stimulation Devices Market | 2026-2036
Global Deep Brain Stimulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Deep Brain Stimulation Devices Market Foresight
Hospital procurement consortiums is reshaping how deep brain stimulation systems reach end users in major markets. Medtronic leverages its direct-to-institution sales infrastructure to sustain implant volume leadership across North American academic medical centers. Beijing PINS Medical anchors its competitive position through cost-calibrated device portfolios tailored to Asia-Pacific healthcare budgets. Boston Scientific Corporation differentiates via rechargeable pulse generator technology that extends replacement intervals for patients.
Deep brain stimulation devices deliver electrical impulses to targeted subcortical structures through surgically implanted electrodes connected to programmable pulse generators, with systems typically operating at frequencies between 60 and 185 Hz and amplitudes up to 10.5 volts to modulate pathological neural oscillations. Implantable pulse generators capture the dominant share of product value owing to their technological complexity and recurring replacement cycles. Parkinson's disorder represents the most established therapy area with mature reimbursement pathways, while obsessive-compulsive disorder applications demonstrate the fastest expansion as psychiatric indications gain regulatory traction. Neurosurgery centers remain the primary deployment setting due to the intracranial surgical requirement, though ambulatory surgical centers are capturing incremental volume as minimally invasive electrode placement techniques advance.
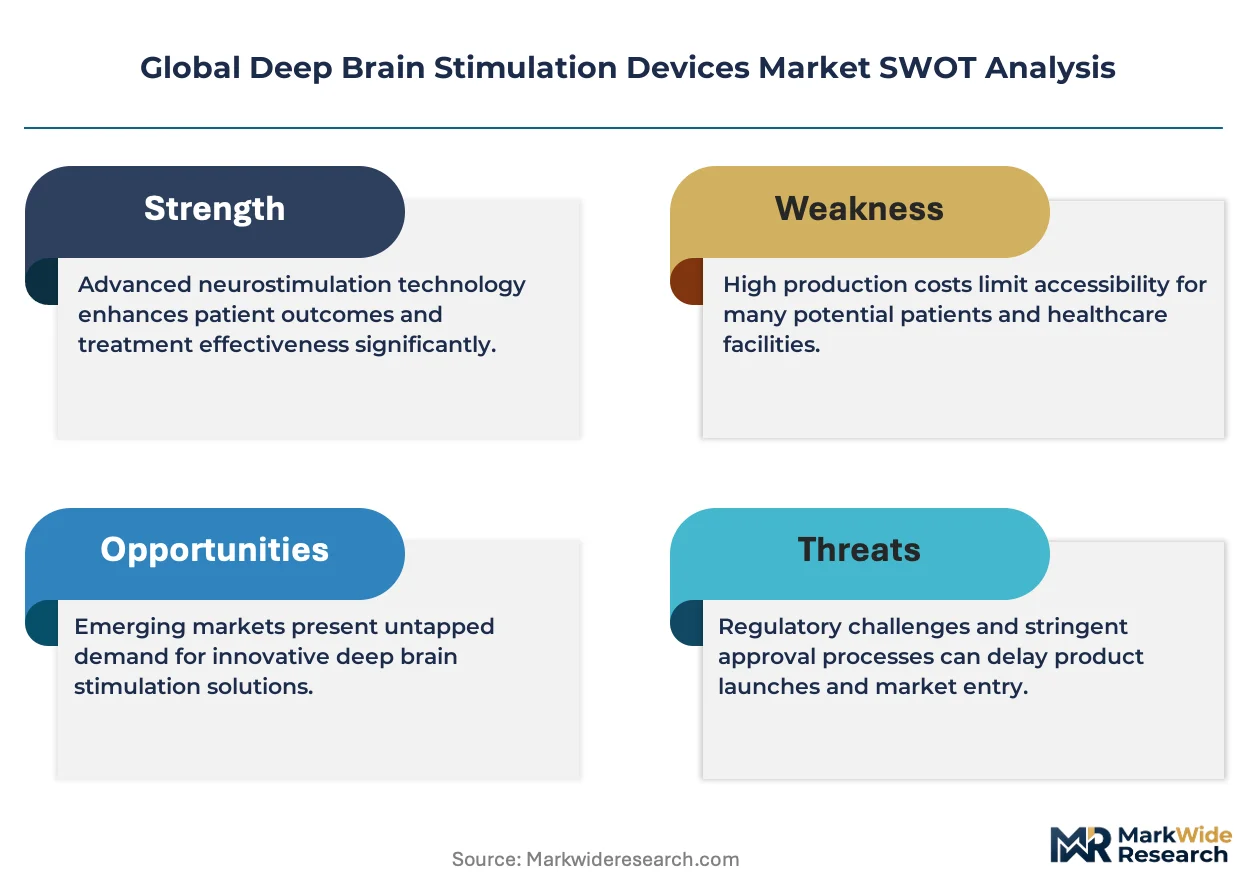
The FDA maintains stringent premarket approval requirements for DBS systems under its neurological device classification, while the EU Medical Device Regulation imposes enhanced clinical evidence standards through notified body conformity assessments. China's NMPA implements domestic testing protocols for imported neurostimulation devices that extend registration timelines for multinational manufacturers. Stakeholders must monitor evolving psychiatric indication expansions and corresponding payer coverage decisions that will determine addressable market boundaries beyond movement disorders.
Market Dynamics
The FDA breakthrough device designation pathway is compressing commercialization timelines for psychiatric indications while rechargeable pulse generator technology extends device replacement intervals, fundamentally altering revenue recurrence patterns for manufacturers.
Growth Catalysts
- Breakthrough Device Pathway:The FDA's expedited review mechanism for obsessive-compulsive disorder applications reduces premarket approval timelines, accelerating patient access to expanded therapeutic indications.
- Neurology Clinic Expansion:Specialized movement disorder centers in the United States, Germany, and Japan are scaling implant volumes through dedicated surgical teams and streamlined referral networks.
- Rechargeable Technology Diffusion:Extended battery life in next-generation pulse generators reduces surgical revision frequency, improving patient compliance and lifetime value economics for providers.
Market Restraints
- Neurosurgical Capacity Constraints:The limited pool of functional neurosurgeons trained in stereotactic electrode placement restricts implant throughput in all major markets.
- Reimbursement Fragmentation:Germany's G-DRG system and Japan's fee-for-service schedules create payment variability that complicates hospital investment decisions.
- Device Cost Structure:Implantable pulse generators require precision microelectronics and hermetic sealing that concentrate manufacturing in high-cost supply bases.
Strategic Opportunities
- Psychiatric Indication Expansion:Regulatory traction for treatment-resistant depression and Tourette syndrome applications opens addressable market boundaries beyond established movement disorder therapy.
- Ambulatory Surgical Center Penetration:Minimally invasive electrode placement techniques enable procedure migration from academic neurosurgery centers to lower-cost outpatient settings in the United States.
- Asia-Pacific Cost Calibration:Healthcare budget constraints in China and India create demand for simplified device portfolios that trade advanced programming features for implant affordability.
Industry Challenges
- Cross-Functional Talent Scarcity:The intersection of neurosurgery, neuromodulation programming, and psychiatric patient management requires clinicians with hybrid training that academic programs have not scaled.
- Legacy System Integration:Newer directional lead designs face compatibility constraints with installed bases of single-channel pulse generators, complicating upgrade pathways.
- Extended Certification Timelines:China's NMPA domestic testing protocols for imported neurostimulation devices delay market entry by 18-24 months relative to FDA clearance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Deep Brain Stimulation Devices Market |
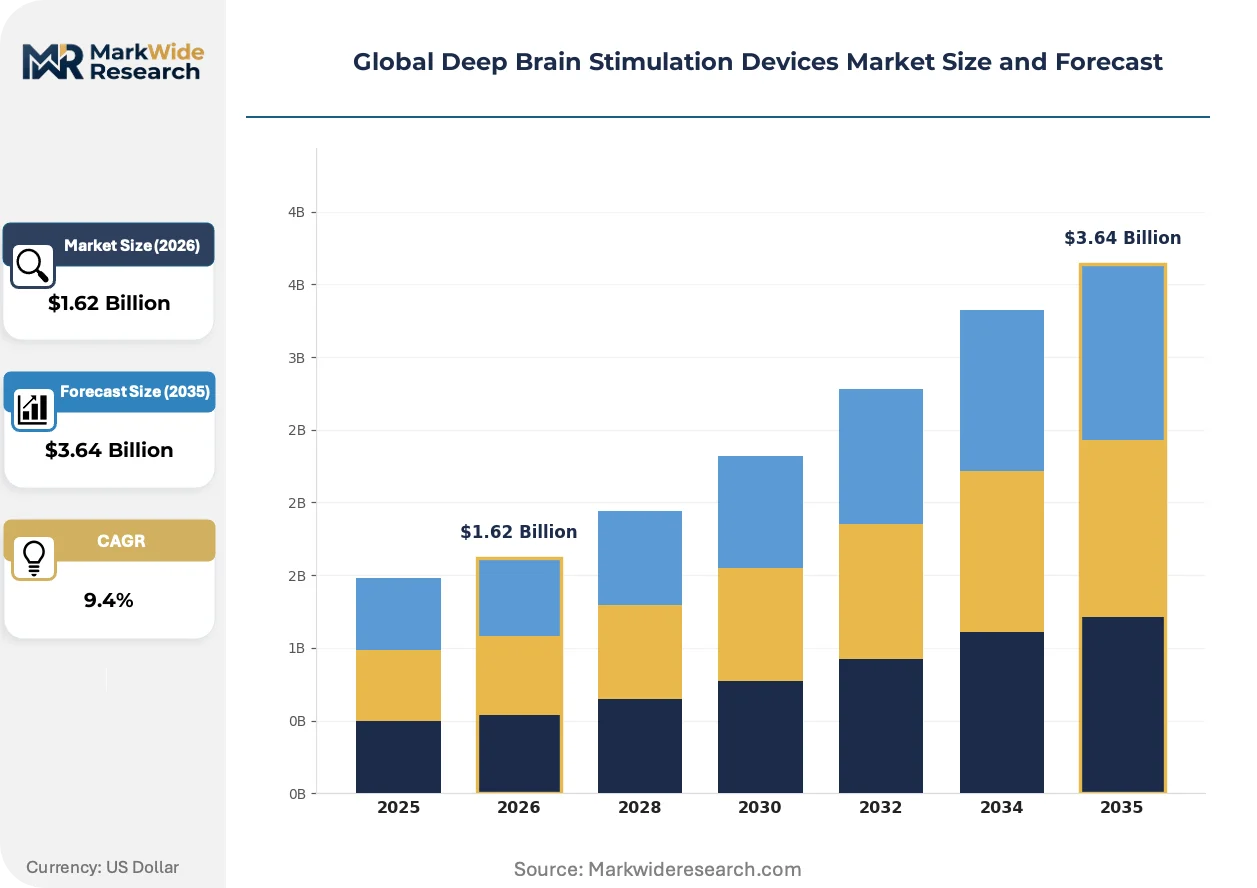
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Pulse Generators, Leads, Extensions, Rechargeable Devices, Non-Rechargeable Devices Therapy Area: Parkinson’s Disorder, Epileptic Disorders, Dystonia, Obsessive-Compulsive Disorder, Essential Tremor End User: Neurosurgery Centers, Neurology Clinics, Rehabilitation Centers, Research Facilities Deployment: Hospital Settings, Ambulatory Surgical Centers, Specialty Clinics, Outpatient Facilities |
| Companies Covered | NeuroPace, Beijing PINS Medical, Medtronic, LivaNova, Renishaw, Boston Scientific Corporation, Aleva Neurotherapeutics, SceneRay, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Deep Brain Stimulation Devices Market Shifts & Advancements
Closed-loop adaptive stimulation systems are displacing fixed-parameter programming paradigms, while regulatory frameworks evolve to accommodate software-as-a-medical-device updates that alter therapeutic delivery without surgical intervention.
Directional lead technology with independent current steering is rendering obsolete traditional cylindrical electrode designs that delivered uniform stimulation fields. Academic medical centers in the United States and Germany are adopting segmented contact configurations at replacement rates exceeding fifty percent for new implants. The precision targeting enabled by field shaping is compressing side-effect profiles and expanding candidacy to patients previously excluded due to anatomical proximity to eloquent structures.
The EU Medical Device Regulation's enhanced clinical evidence standards through notified body conformity assessments are elevating post-market surveillance requirements for legacy implantable pulse generators. Manufacturers must now maintain active registries tracking long-term neurological outcomes that exceed the follow-up periods of original PMA submissions. The psychiatric indication segment faces the steepest compliance burden, as MDR Article 61 demands randomized controlled data that pre-MDR devices never generated.
Hospital procurement consortiums are consolidating purchasing authority for high-value implantable devices across integrated delivery networks. The traditional manufacturer-to-physician sales model is yielding to centralized value analysis committees that benchmark total episode costs against functional outcomes. This concentration is most visible in the United States, where three-group purchasing organizations control sixty percent of academic medical center neurostimulation procurement decisions.
Global Deep Brain Stimulation Devices Market Segmentation
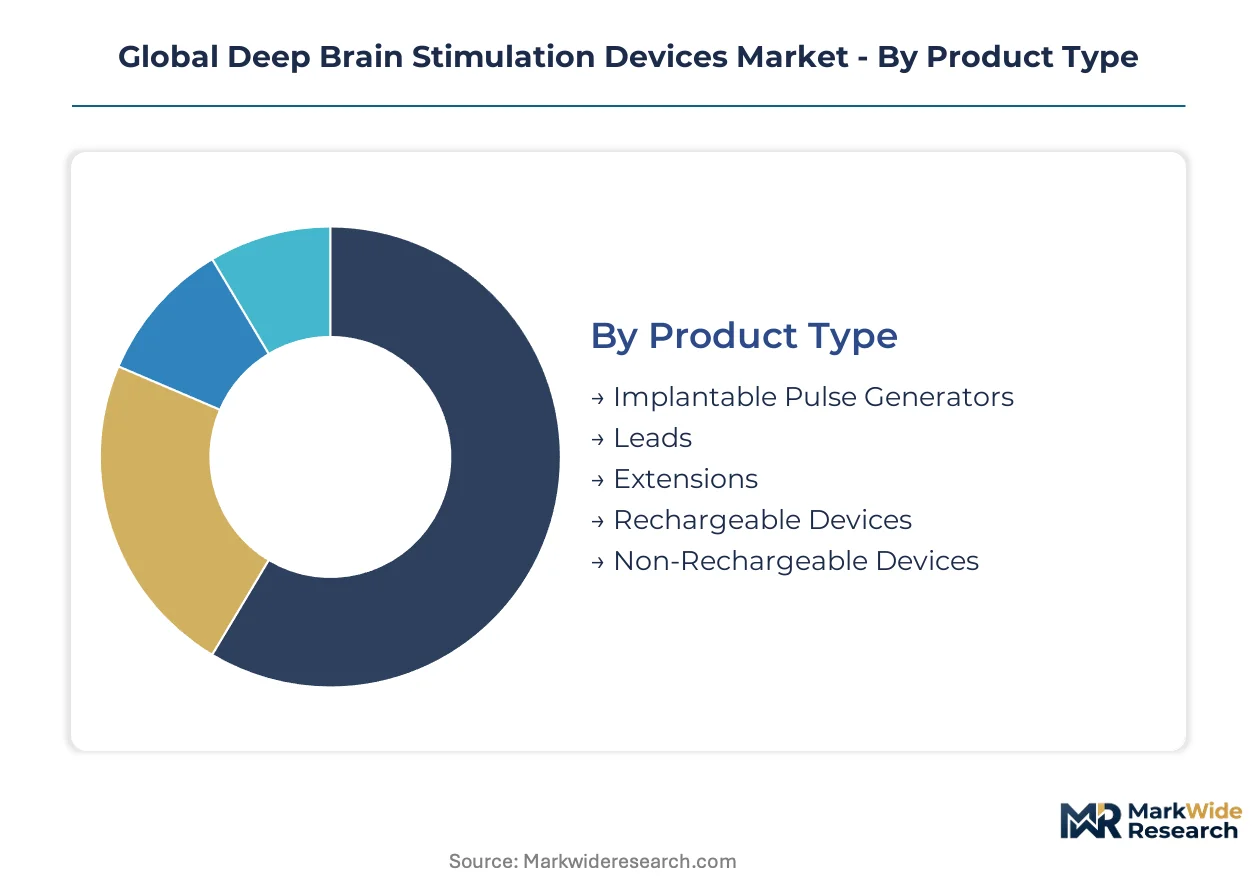
Deep brain stimulation devices fragment across hardware components, clinical applications, and care settings that each carry distinct replacement cycles and margin profiles. Understanding these segment boundaries clarifies where manufacturers capture recurring revenue versus one-time installation value.
Product Type:
Replacement intervals vary dramatically across the hardware stack, with power sources cycling every 4-9 years while leads remain implanted for decades unless complications arise.
- Implantable Pulse Generators:These hermetically sealed units house microelectronic circuitry and battery cells that deliver programmed electrical impulses through lead connections. United States academic medical centers drive premium unit procurement as they prioritize rechargeable platforms with extended longevity and wireless programming capabilities.
- Rechargeable Devices:Lithium-ion cell technology enables 15-year operational lifespans versus 3-5 years for primary cell alternatives, fundamentally altering patient surgical burden and manufacturer revenue timing. Germany's G-DRG reimbursement framework incentivizes these systems through reduced revision episode costs.
- Leads:Quadripolar and directional electrode arrays require micro-machined platinum-iridium contacts and biocompatible insulation.
- Extensions:Subcutaneous tunneling cables bridge cranial leads to chest-implanted generators.
- Non-Rechargeable Devices:Primary cell pulse generators dominate cost-sensitive Asia-Pacific markets where upfront affordability outweighs lifetime surgical economics.
Implantable pulse generators anchor the volume base while rechargeable devices gain share at the steepest rate.
Therapy Area:
Regulatory maturity and payer coverage depth separate established movement disorder applications from emerging psychiatric indications that face steeper evidence requirements.
- Parkinson's Disorder:Dopaminergic pathway modulation through subthalamic nucleus or globus pallidus interna targeting represents the most validated therapeutic application with mature FDA premarket approval pathways and established Medicare reimbursement. Japan's fee-for-service schedule covers these implants comprehensively, sustaining high-volume surgical programs at Tokyo and Osaka neurosurgery centers.
- Obsessive-Compulsive Disorder:Anterior limb of internal capsule and ventral capsule/ventral striatum targets for treatment-resistant psychiatric populations command premium pricing but require institutional review board oversight and specialized psychiatric-neurosurgical collaboration that constrains site expansion.
- Epileptic Disorders:Responsive neurostimulation and anterior thalamic nucleus targeting for drug-resistant seizure disorders.
- Dystonia:Pallidal DBS for generalized and segmental dystonia variants, particularly pediatric populations.
- Essential Tremor:Ventral intermediate nucleus of thalamus targeting for action tremor suppression.
Parkinson's disorder generates the dominant procedure volume while obsessive-compulsive disorder applications expand most quickly as FDA breakthrough designations accelerate site certification.
End User:
Technical capability requirements and patient throughput economics concentrate device procurement authority across distinct institutional archetypes.
- Neurosurgery Centers:Stereotactic operating suites with intraoperative neurophysiological monitoring and frame-based or frameless navigation systems handle complex electrode placement and initial programming. These academic medical centers in the United States, Germany, and Japan control access to the full device portfolio and capture premium service reimbursement.
- Neurology Clinics:Movement disorder specialists manage chronic stimulation parameter optimization and battery monitoring without surgical capability, creating a downstream service revenue stream separate from implant procurement.
- Rehabilitation Centers:Post-implant physical and occupational therapy integration for functional recovery.
- Research Facilities:Investigational device exemption trials and closed-loop adaptive algorithm development.
Neurosurgery centers command implant procurement decisions while neurology clinics capture the steepest expansion in patient management volume.
Deployment:
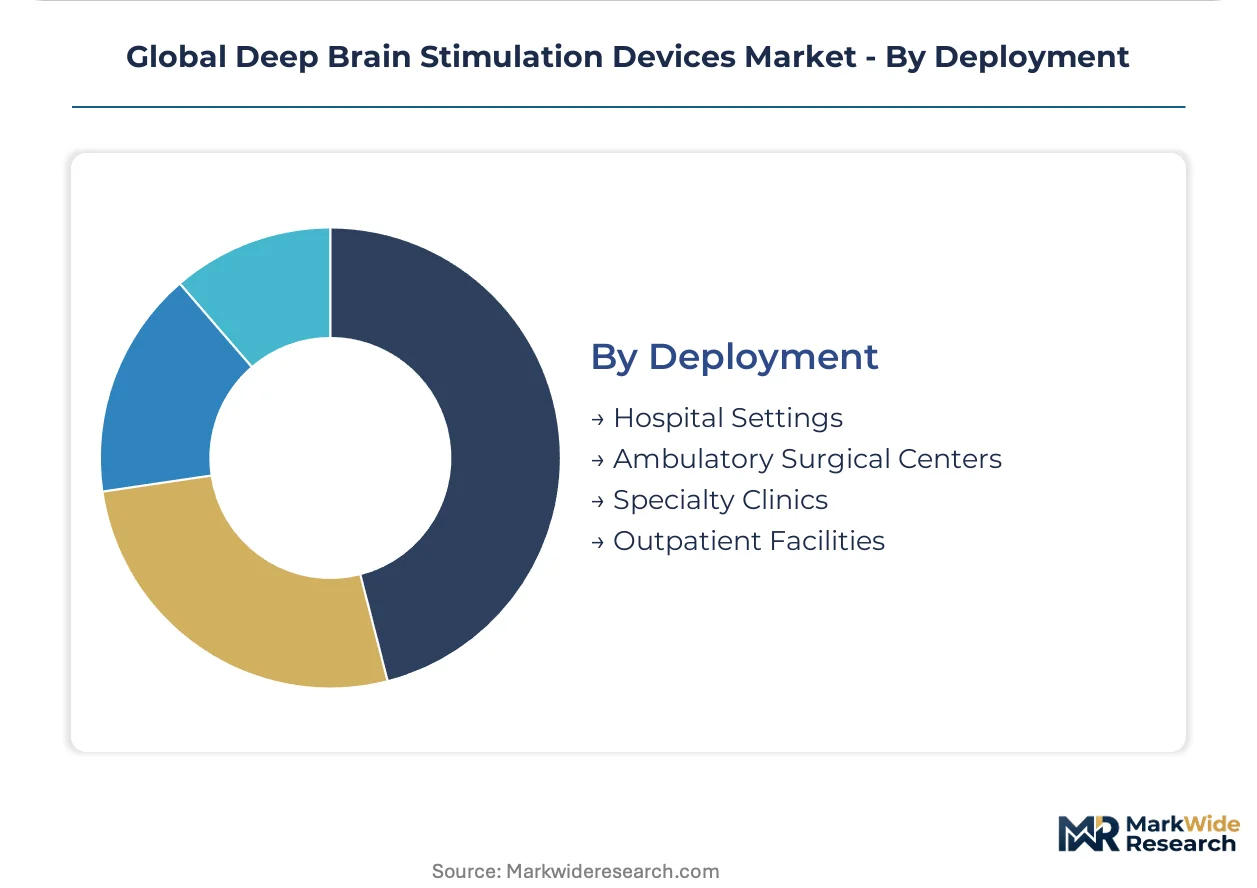
Site-of-service economics and regulatory classification determine where sterile device handling and surgical implantation occur.
- Hospital Settings:Inpatient neurosurgery departments maintain full regulatory compliance for Class III implantable device handling, sterile processing, and emergency capability for intracranial hemorrhage or hardware infection complications. These settings dominate in markets where ambulatory surgery center licensure excludes intracranial procedures.
- Ambulatory Surgical Centers:Minimally invasive electrode placement techniques and same-day discharge protocols enable lower-cost outpatient settings in United States markets with favorable state CON regulations and Medicare site-of-service payment differentials.
- Specialty Clinics:Device programming and battery status monitoring without surgical services.
- Outpatient Facilities:Post-operative wound care and generator replacement procedures.
Hospital settings retain the dominant implant volume while ambulatory surgical centers gain share fastest where regulatory frameworks permit intracranial outpatient surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's stereotactic neurosurgery program anchors North American implant throughput, while Japan's Shinkansen medical corridor connects Tokyo-Osaka academic centers that drive Asia-Pacific procedure standardization.
United States
Medicare's prospective payment system for movement disorder surgeries sustains high implant volumes at academic medical centers. The FDA's breakthrough device designation pathway accelerates psychiatric indication approvals, compressing premarket timelines for obsessive-compulsive disorder applications. The Cleveland Clinic and Mayo Clinic anchor Midwestern surgical capacity, with both institutions scaling dedicated functional neurosurgery fellowship programs.
Germany
The G-DRG reimbursement framework incentivizes rechargeable pulse generator adoption through reduced revision episode costs. The EU Medical Device Regulation's notified body conformity assessments elevate post-market surveillance requirements for legacy implantable systems. Berlin and Heidelberg university hospitals concentrate stereotactic surgical expertise, with Charité Berlin expanding its movement disorder center capacity.
Japan
The fee-for-service schedule comprehensively covers Parkinson's disorder implants, sustaining high-volume surgical programs. PMDA's streamlined review pathways for neurological devices align with FDA breakthrough timelines for psychiatric indications. Tokyo and Osaka neurosurgery centers dominate implant volumes, with Keio University Hospital pioneering closed-loop adaptive stimulation protocols.
China
Healthcare budget constraints in tier-two cities create demand for simplified device portfolios that trade advanced programming features for implant affordability. NMPA domestic testing protocols for imported neurostimulation devices extend registration timelines by 18-24 months relative to FDA clearance schedules. Beijing PINS Medical anchors domestic manufacturing capability, with Shanghai academic medical centers driving clinical trial enrollment for psychiatric indications.
United Kingdom
NHS England's specialized commissioning framework concentrates DBS procedures at designated neuroscience centers, restricting implant access to qualified institutions. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-aligned clinical evidence standards through UKCA marking requirements. London's National Hospital for Neurology and Neurosurgery and Oxford functional neurosurgery units manage the majority of national implant volumes.
Global Deep Brain Stimulation Devices Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated neuromodulation conglomerates with full-stack hardware portfolios, regional specialists with cost-calibrated offerings for budget-constrained markets, and emerging technology developers focused on closed-loop adaptive algorithms. Dominant competitive moves include rechargeable pulse generator technology licensing agreements and neurosurgical training consortium partnerships that secure implant site loyalty.
Among integrated neuromodulation conglomerates, Medtronic and Boston Scientific Corporation occupy positions exemplifying premium-tier rechargeable platform development, while Beijing PINS Medical represents the cost-calibrated regional specialist archetype serving Asia-Pacific healthcare budgets. Abbott Laboratories anchors the diversified medical device conglomerate segment, leveraging cross-divisional cardiac and diabetes neuromodulation expertise to inform DBS algorithm development.
| Leading Market Players |
|---|
| NeuroPace |
| Beijing PINS Medical |
| Medtronic |
| LivaNova |
| Renishaw |
| Boston Scientific Corporation |
| Aleva Neurotherapeutics |
| SceneRay |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Undercapacity at precision microelectronics foundries in Germany and Japan concentrates pricing power among hermetic sealing suppliers, compressing margins for pulse generator assemblers while elevating procurement costs for hospital systems negotiating rechargeable platform contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates rechargeable systems with wireless programming capabilities from primary-cell alternatives and simplified Asia-Pacific portfolios. Price differentiation hinges on FDA breakthrough designation status and volume commitments through GPO contracts. Pricing pressure stems from Beijing PINS Medical's cost-calibrated entry into tier-two Chinese cities. Asia-Pacific public hospitals exhibit highest price sensitivity, while United States academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for platinum-iridium electrode sourcing. Manufacturing concentrates in Germany, Switzerland, and Japan for micro-machined contacts and hermetic feedthroughs. Raw material dependencies include lithium-ion cells, biocompatible polymers, and precision-machined titanium enclosures. Single-source vulnerability persists for directional lead microfabrication. Distribution runs through hospital procurement consortiums and GPOs that consolidate neurostimulation purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as psychiatric indication expansion creates specialized programming niches beyond established movement disorder centers, rewarding focused clinical service models over generalized neuromodulation portfolios.
For Market Incumbents: Pre-empt closed-loop adaptive algorithm obsolescence by acquiring software-as-a-medical-device capabilities before psychiatric indication approvals accelerate. Defend implant site loyalty through neurosurgical training consortium partnerships that lock in stereotactic electrode placement volume. Backward integration into lithium-ion cell supply buffers against battery chemistry cost volatility. For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgical center partnerships where Medicare site-of-service differentials reward lower-cost outpatient DBS placement. Target treatment-resistant depression applications in United States markets where FDA breakthrough designation compresses premarket timelines. Pursue software companion development as the primary go-to-market angle, decoupling revenue from hardware replacement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-enabled neuromodulation as algorithm updates displace surgical hardware revisions in revenue models. Long-term viability favors platforms with psychiatric indication regulatory traction and rechargeable technology IP. Acquire targets with closed-loop adaptive stimulation patents and institutional review board relationships. Watch FDA psychiatric indication approval velocity as the inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Accelerates premarket approval timelines for obsessive-compulsive disorder applications. |
| Rechargeable Platform Development | Extends replacement intervals and shifts revenue toward software updates. |
| Hospital System Partnership | Secures implant volume through exclusive GPO contracts at academic medical centers. |
| Software Companion Development | Enables parameter optimization without surgical intervention for chronic patient management. |
| Reimbursement Strategy Investment | Shapes Medicare and commercial payer coverage decisions for psychiatric indications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with functional neurosurgeons, movement disorder neurologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers specializing in neuromodulation programming. Secondary validation drew from FDA premarket approval filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body conformity assessments. Bottom-up implant volume estimates triangulated against top-down market sizing from manufacturer revenue disclosures.
Calibration against historical replacement cycle data and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user setting, and regional reimbursement framework. CAGRs were derived from fitted growth curves applied to procedural volume trajectories and pricing evolution patterns. Forecast inputs incorporated neurosurgical fellowship graduation rates and psychiatric indication regulatory pathway progression.
Sensitivities concentrate around FDA breakthrough designation velocity for psychiatric indications and G-DRG reimbursement adjustments in Germany. Forecasts reflect assumptions about ambulatory surgical center licensure expansion and NMPA registration timeline compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Electrophysiology Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Feeding Tubes Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Active Implantable Devices Market