
 Ion Channel Modulators Market | 2026-2036
Ion Channel Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Ion Channel Modulators Market Analytics
China is tilting toward domestic ion channel R&D capacity with new biotech parks in Shanghai and Suzhou. Pfizer Inc. leverages its established cardiovascular franchise to anchor blockbuster-scale calcium channel programs. GlaxoSmithKline sustains one of the industry's deepest pain-management pipelines through sustained R&D intensity in sodium channel blockers. Evotec AG differentiates via automated patch-clamp platforms that compress target validation timelines for partner biotechs.
Ion channel modulators comprise synthetic and biologic compounds that selectively bind to transmembrane pore-forming proteins to alter ion flux, with functional parameters including half-maximal inhibitory concentration thresholds in the nanomolar range and state-dependent binding kinetics. These molecules serve primary commercial purpose across neurological, cardiovascular, and pain therapeutics where precise electrical signaling control determines clinical outcomes. Blockers occupy the largest revenue pool given entrenched antiarrhythmic and antiepileptic franchises, while activators represent the fastest-expanding category as gene-therapy-linked optogenetics and small-molecule approaches open new target classes. Injectable delivery commands premium pricing in hospital settings, yet oral formulations dominate prescription volume through patient adherence advantages in chronic neurological and cardiovascular indications.
FDA orphan drug designations and EMA PRIME eligibility reshape demand by compressing regulatory review timelines for rare-channelopathy indications. China's NMPA accelerated approval pathways for innovative chemical drugs further expand market access for domestic developers. REACH compliance in Europe and evolving EPA environmental assessments for manufacturing effluent impose formulation and process constraints that elevate compliance costs. Stakeholders must monitor how CRISPR-enabled channelopathy models and AI-driven structure-based design reshape which target classes attract capital allocation versus which mature mechanisms face generic displacement.
Market Dynamics
AI-driven structure-based design is compressing target validation timelines for novel ion channel modulators, while CRISPR-enabled channelopathy models reshape which therapeutic mechanisms attract capital allocation versus face generic displacement.
Growth Catalysts
- FDA Orphan Drug Designations:These accelerate clinical trial timelines for rare-channelopathy indications, reducing regulatory burden for developers pursuing novel sodium and calcium channel targets.
- Gene-therapy-linked optogenetics:This emerging platform is opening new activator target classes previously inaccessible to small-molecule approaches, expanding addressable indications.
- Shanghai biotech parks:China's NMPA accelerated approval pathways for innovative chemical drugs are expanding market access for domestic developers with captive R&D infrastructure.
Market Restraints
- REACH compliance costs:ECHA environmental assessments for manufacturing effluent impose formulation constraints that elevate process development expenses for European production.
- Automated patch-clamp platform concentration:Contract research access concentrates among limited specialized providers, creating bottleneck risk for target validation timelines.
- Biologic substitute threat:Monoclonal antibody approaches for pain management are displacing small-molecule sodium channel blockers in certain refractory indications.
Strategic Opportunities
- EMA PRIME eligibility:This regulatory pathway compresses review timelines for priority medicines, creating first-mover advantage for developers with breakthrough channelopathy therapies.
- AI-structure convergence with cryo-EM:Combining machine learning with high-resolution protein imaging is enabling rational design against previously intractable channel conformations.
- Suzhou manufacturing corridor:Underpenetrated domestic production capacity offers cost-advantaged supply for Asia-Pacific distribution networks.
Industry Challenges
- Electrophysiology talent scarcity:Skilled patch-clamp operators and ion channel pharmacologists remain concentrated among established academic centers and contract research organizations.
- State-dependent binding assay complexity:Validating kinetic parameters across multiple channel conformations extends preclinical characterization timelines.
- Legacy cardiovascular franchise integration:Repurposing antiarrhythmic discovery infrastructure for neurological indications requires substantial assay reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ion Channel Modulators Market |
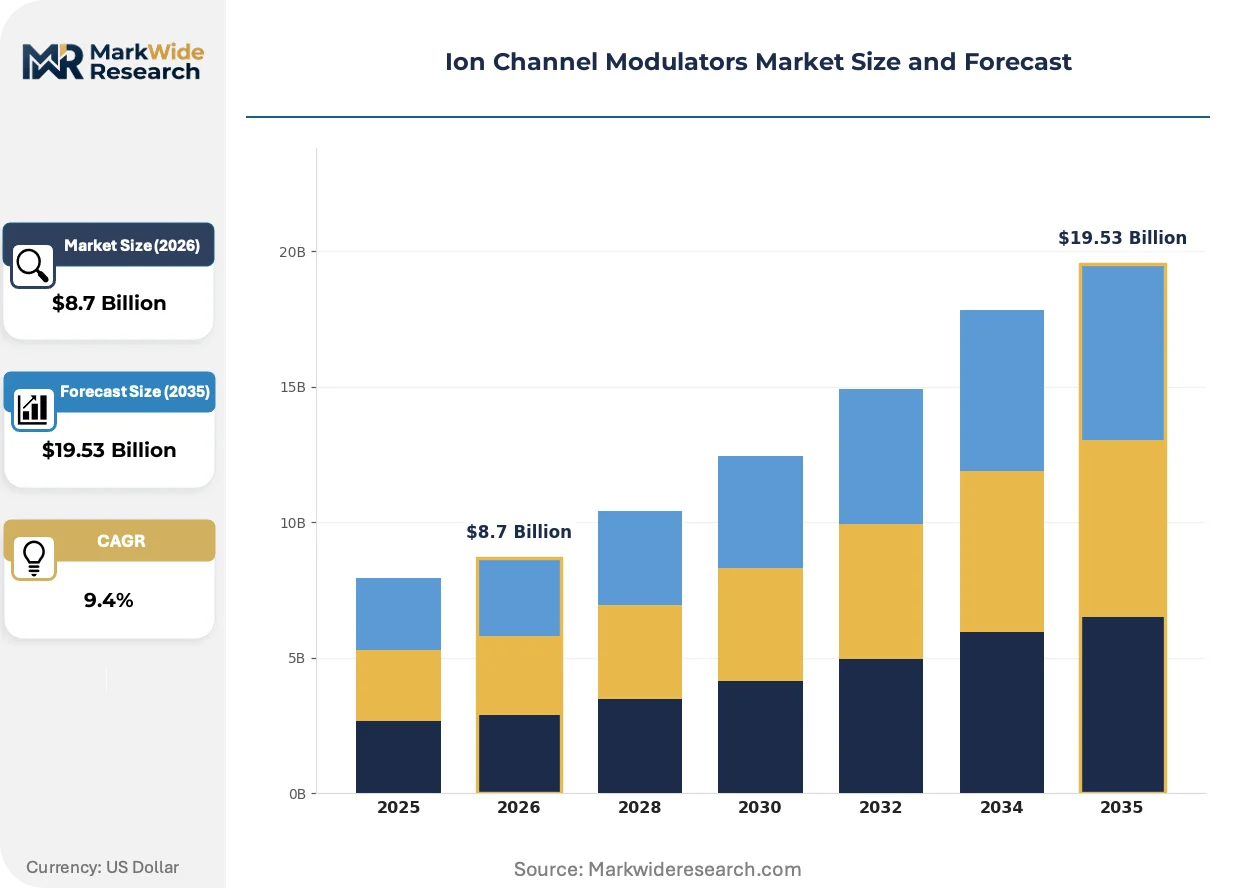
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blockers, Agonists, Inhibitors, Activators Application: Neurological Disorders, Cardiovascular Diseases, Pain Management, Muscle Disorders Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Research Institutions, Pharmaceuticals, Biotechnology Companies |
| Companies Covered | GlaxoSmithKline, Merck, Pfizer Inc., Cellectricon AB, Evotec AG, AstraZeneca, Sanofi, Nanion Technologies GmbH, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ion Channel Modulators Market Evolving Landscape
Computational platforms are displacing empirical screening as the primary engine of ion channel drug discovery, compressing the interval between target identification and lead optimization while elevating the importance of structural biology partnerships.
Automated patch-clamp technology is virtualizing the electrophysiology workflow that once required manual operator intervention. Mid-cap biotechs and large pharmaceutical discovery units are adopting these platforms at accelerating pace, reducing per-compound assay costs by an order of magnitude. This virtualization is compressing target validation timelines from months to weeks, enabling parallel screening of state-dependent binding kinetics that manual methods cannot achieve.
REACH authorization requirements under ECHA jurisdiction are reshaping manufacturing process design for European supply. The industrial consequence extends beyond compliance documentation to fundamental reformulation decisions, as effluent toxicity thresholds constrain solvent selection and synthetic route architecture. Small-molecule activator programs face disproportionate impact given their typically more complex multi-step syntheses and higher solvent intensity.
Hospital procurement committees are consolidating vendor relationships for injectable ion channel modulators, displacing fragmented purchasing across individual therapeutic areas. This concentration favors suppliers with broad neurological and cardiovascular portfolios capable of meeting formulary bundling requirements. The shift is most visible in United States academic medical centers, where centralized pharmacy and therapeutics committees now negotiate system-wide contracts spanning sodium channel blockers, calcium channel antagonists, and potassium channel activators.
Ion Channel Modulators Market Segmentation
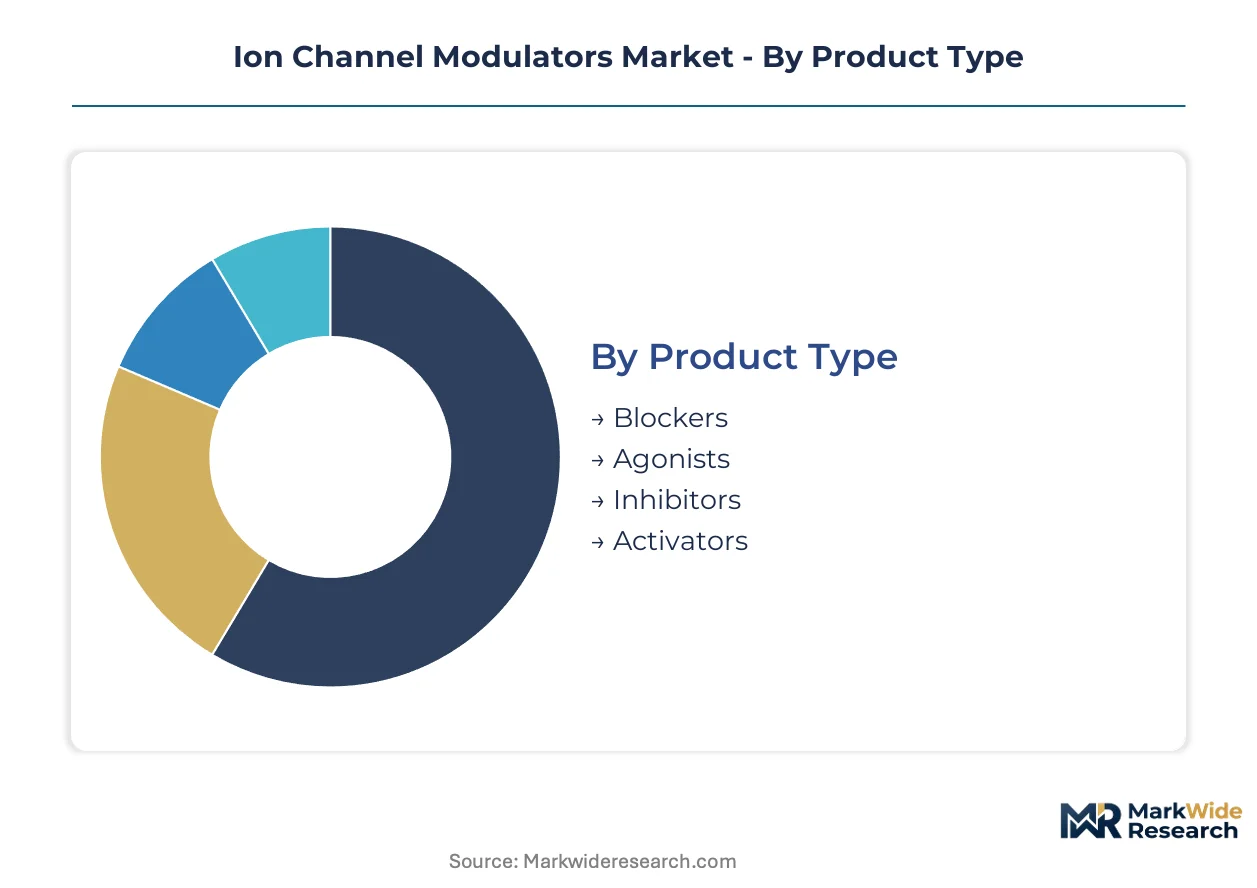
Ion channel modulators span heterogeneous molecular mechanisms and therapeutic contexts that reshape how developers allocate R&D capital. Segment-level demand patterns determine which formulation strategies and target indications attract partnership investment versus generic substitution risk.
Product Type:
Functional mechanism dictates clinical utility across electrical signaling disorders, with each modality commanding distinct development timelines and regulatory pathways.
- Blockers:These compounds occlude pore-forming domains to suppress aberrant ion flux, with established sodium and calcium channel franchises dominating antiarrhythmic and antiepileptic prescribing. Demand concentrates in United States hospital formularies where entrenched cardiovascular protocols sustain volume.
- Activators:Small-molecule and optogenetic approaches that enhance channel opening kinetics are expanding addressable indications into loss-of-function channelopathies. Gene-therapy-linked platforms in Boston and San Francisco biotech clusters are accelerating preclinical translation.
- Agonists:Ligand-gated channel potentiators serve niche nicotinic and GABA receptor applications in smoking cessation and anesthesia.
- Inhibitors:Allosteric modulators that reduce channel opening probability without complete blockade offer improved therapeutic indices for chronic neurological dosing.
The dominant share belongs to Blockers, while Activators is closing the gap fastest.
Application:
Clinical indication determines reimbursement intensity and prescriber specialization requirements for commercial deployment.
- Neurological Disorders:Epilepsy, migraine, and ataxia indications drive precision medicine approaches targeting specific channelopathy genotypes. FDA orphan drug designations for rare sodium channel mutations are compressing development timelines in this cluster.
- Pain Management:Sodium channel blockers face displacement pressure from biologic alternatives, yet novel state-dependent binding kinetics are preserving differentiated positioning for refractory neuropathic populations.
- Cardiovascular Diseases:Antiarrhythmic and antihypertensive franchises sustain mature revenue pools with limited novel target expansion.
- Muscle Disorders:Myotonic and periodic paralysis channelopathies represent emerging addressable populations with unmet need.
Neurological Disorders commands the largest development pipeline, with Pain Management experiencing the steepest competitive pressure from alternative modalities.
Delivery Mode:
Route of administration shapes manufacturing complexity, pricing power, and patient adherence profiles across acute versus chronic indications.
- Oral:Tablet and capsule formulations dominate prescription volume through outpatient adherence advantages in chronic neurological and cardiovascular maintenance therapy.
- Injectable:Intravenous and subcutaneous delivery commands premium pricing in hospital settings where rapid onset and controlled titration determine clinical outcomes.
- Transdermal:Patch-based delivery offers steady-state pharmacokinetics for pain management with reduced first-pass metabolism.
- Inhalation:Pulmonary delivery remains exploratory for acute bronchospasm and potential CNS indications requiring rapid blood-brain barrier penetration.
Oral formulations generate the highest prescription counts, though Injectable delivery captures superior per-dose economics in institutional settings.
End User:
Customer type determines procurement scale, technical specification requirements, and relationship dynamics for supplier positioning.
- Hospitals:Academic medical centers and health systems consolidate vendor relationships through centralized pharmacy and therapeutics committees, favoring suppliers with broad portfolio breadth across neurological and cardiovascular categories.
- Pharmaceuticals:Large-cap developers leverage established cardiovascular franchises to anchor blockbuster-scale calcium channel programs with integrated discovery and commercial infrastructure.
- Biotechnology Companies:Mid-cap specialists partner with automated patch-clamp platform providers to compress target validation timelines for novel mechanisms.
- Research Institutions:Academic electrophysiology laboratories concentrate skilled patch-clamp operators and channel pharmacologists, creating talent scarcity for commercial recruitment.
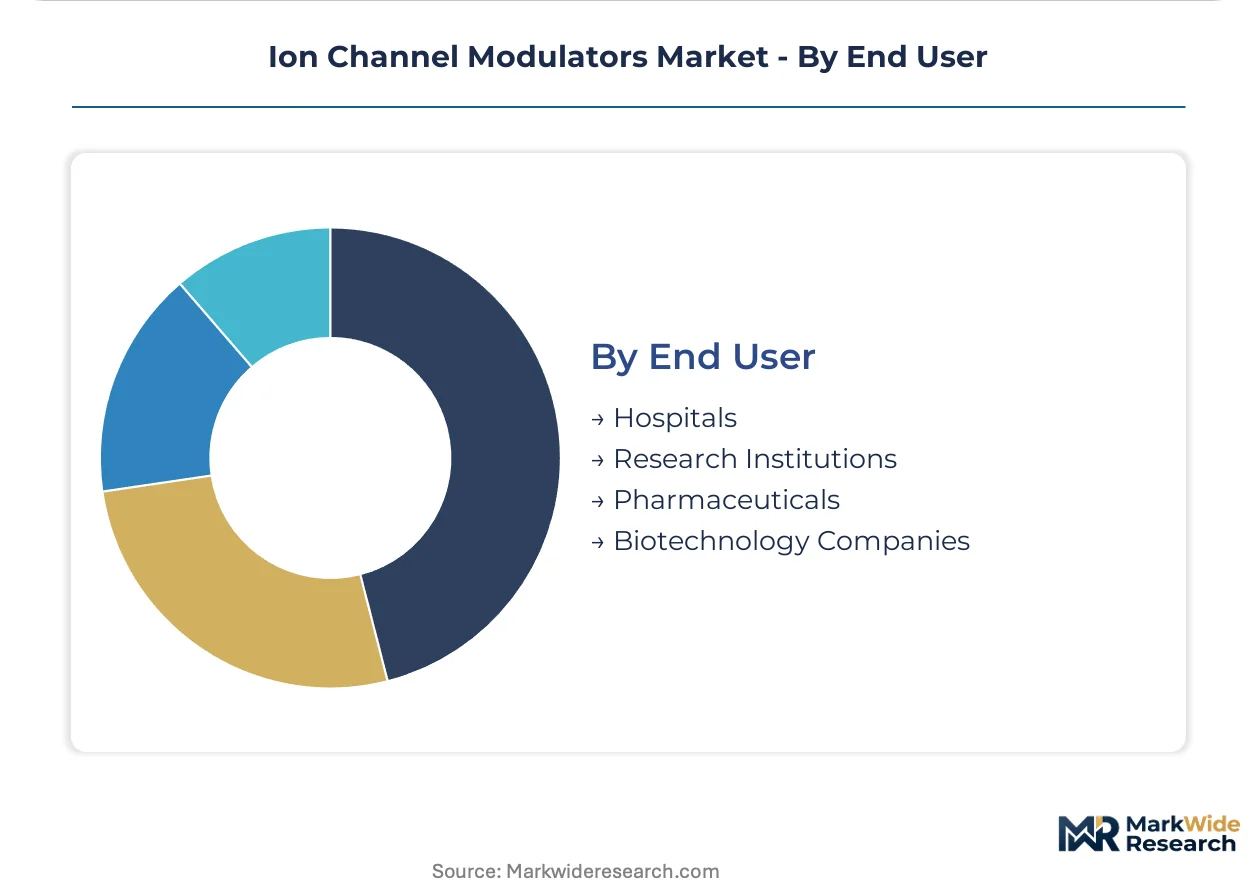
Hospitals represent the largest procurement volume, while Biotechnology Companies are expanding their share fastest through platform specialization and partnership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotech clusters in Boston and San Francisco anchor United States supply, while Shanghai and Suzhou parks tilt Chinese capacity toward domestic R&D. Regulatory pathways in both markets compress development timelines for rare-channelopathy indications.
United States
FDA orphan drug designations accelerate clinical trial timelines for sodium and calcium channel targets targeting rare neurological channelopathies. The agency's breakthrough therapy pathway further compresses review schedules for first-in-class modulators. Boston and San Francisco biotech clusters concentrate gene-therapy-linked optogenetics platforms that open new activator target classes.
China
NMPA accelerated approval pathways for innovative chemical drugs expand market access for domestic developers with captive R&D infrastructure. The regulator's priority review vouchers reward rare disease indications including channelopathy therapies. Shanghai and Suzhou biotech parks house automated patch-clamp platform partnerships that compress target validation timelines for mid-cap specialists.
Germany
ECHA REACH compliance requirements reshape manufacturing process design for European supply, elevating formulation constraints on solvent selection. EMA PRIME eligibility compresses review timelines for priority medicines including breakthrough channelopathy therapies. Frankfurt and Munich pharmaceutical corridors sustain deep electrophysiology talent pools concentrated among established academic centers.
Switzerland
Swissmedic's streamlined authorization procedures attract developers seeking rapid European market entry for precision neurological therapies. The country's dual-track regulatory system accommodates both centralized EMA and national pathways. Basel and Zurich pharmaceutical hubs anchor cardiovascular franchise infrastructure repurposable for ion channel discovery programs.
Japan
PMDA's sakigake designation system accelerates approval timelines for innovative ion channel modulators addressing unmet neurological need. METI's healthcare technology subsidies support domestic adoption of automated electrophysiology platforms. Tokyo and Osaka academic medical centers consolidate vendor relationships for injectable modulators through centralized pharmacy committees.
Ion Channel Modulators Market Competitive Landscape
Big-pharma cardiovascular franchises and mid-cap electrophysiology specialists split the market between blockbuster-scale calcium channel programs and platform-enabled target validation services. Consolidation concentrates among legacy antiarrhythmic developers, while fragmentation persists in the automated patch-clamp contract research tier. Two strategic archetypes dominate: diversified pharmaceutical conglomerates leveraging established discovery infrastructure, and technology-platform specialists compressing preclinical timelines through instrumentation partnerships. Competitive moves center on assay virtualization partnerships and biotech cluster co-location for talent access.
Within the diversified-pharmaceutical tier, Pfizer Inc. and GlaxoSmithKline occupy positions anchored by cardiovascular franchise depth, while Evotec AG exemplifies the platform-specialist archetype through automated patch-clamp partnerships that serve partner biotech discovery timelines. These three entities represent the strategic spectrum from integrated blockbuster development to outsourced target validation services.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Merck |
| Pfizer Inc. |
| Cellectricon AB |
| Evotec AG |
| AstraZeneca |
| Sanofi |
| Nanion Technologies GmbH |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
The Shanghai-Suzhou pharmaceutical corridor's freight cost dynamics amplify supply concentration effects for ion channel modulators, compressing margins for European developers while enabling price differentiation between captive manufacturing and contract synthesis tiers.
Pricing Analysis
REACH authorization dictates the pricing tier structure across European supply, separating certified green-chemistry formulations from standard synthetic routes. Three-tier pricing structure across premium, standard, and economy levels reflects ECHA compliance burden, volume scale, and after-sales technical support bundling. Cost compression in the standard tier is intensifying because contract manufacturers compete on NMPA-aligned specifications for Asia-Pacific export. Hospital procurement committees exhibit lowest price sensitivity given formulary bundling requirements, while mid-cap biotechs sourcing for preclinical programs show highest elasticity.
Supply Chain Analysis
Export-control restrictions on high-throughput electrophysiology instrumentation limit flows from Germany and Switzerland to Chinese biotech parks, fragmenting equipment access. Active pharmaceutical ingredient production draws from India, China, and Germany, with automated patch-clamp consumables anchored in Sweden and Germany. Single-source vulnerability concentrates in specialized ion channel cell line providers. Distribution runs through regional distributor networks serving hospital systems and direct partnerships with academic medical center pharmacy committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ion channel modulators market functions as a defensive-moat arena where regulatory entrenchment through orphan drug exclusivity creates durable pricing power for first movers in rare channelopathy indications.
For Market Incumbents: Harden cardiovascular franchise infrastructure against biologic displacement by deepening state-dependent binding assay capabilities and securing exclusive automated patch-clamp platform partnerships. Expand captive manufacturing footprint in Suzhou to capture NMPA accelerated approval pathway advantages. Prioritize EMA PRIME eligibility investment to compress review timelines for breakthrough neurological modulators. For New Entrants and Emerging Players: Build out gene-therapy-linked optogenetics capabilities in Boston or San Francisco clusters to access activator target classes inaccessible to small-molecule incumbents. Target loss-of-function sodium channelopathies with FDA orphan drug designation potential as the most penetrable indication white space. Pursue platform partnership structures with Evotec AG or equivalent automated electrophysiology providers to compress target validation timelines versus internal build. For Investors and Strategic Acquirers: Carve-out targets emerge from large-pharma pain management franchises facing biologic substitution pressure, where sodium channel blocker assets trade at discount to neurological repositioning potential. Five-to-ten year viability hinges on CRISPR channelopathy model integration and AI-structure convergence capabilities. Monitor FDA breakthrough therapy designation velocity for novel calcium channel targets as the critical inflection signal for capital reallocation toward activator mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Patch-Clamp Platform Partnership | Evotec AG's instrumentation partnerships compress target validation timelines from months to weeks for partner biotechs. |
| EMA PRIME Eligibility Pursuit | Priority medicine status compresses review timelines for breakthrough channelopathy therapies seeking European market entry. |
| Orphan Drug Designation Acquisition | FDA exclusivity incentives accelerate clinical trial timelines for rare sodium and calcium channel mutation indications. |
| Green Chemistry Reformulation Investment | REACH-compliant solvent selection reduces ECHA environmental assessment risk for European manufacturing supply. |
| Gene-Therapy Optogenetics Platform Buildout | Boston and San Francisco biotech clusters anchor preclinical translation for previously inaccessible activator target classes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the ion channel modulator value chain, including drug development executives at large-pharma cardiovascular franchises, regulatory affairs leads navigating FDA orphan drug pathways, hospital pharmacy and therapeutics committee directors, and automated patch-clamp platform engineers. Secondary validation drew from FDA filings, EMA PRIME eligibility decisions, ClinicalTrials.gov channelopathy trial registrations, and NMPA accelerated approval pathway announcements. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated against disclosed partnership structures and platform licensing terms.
Calibration against historical orphan drug approval timelines and gene-therapy optogenetics investment flows anchored the analytical framework across the analysis window. Segmentation dimensions included functional mechanism, clinical indication, delivery mode, and regional regulatory cluster. CAGRs were derived from indication-level penetration curves and pricing power erosion assumptions. Forecast inputs incorporated automated patch-clamp adoption rates and CRISPR channelopathy model translation velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene-therapy platform specialists or AI-driven structure-based design entrants would shift outcomes. Material shifts in FDA breakthrough therapy designation criteria or ECHA REACH effluent toxicity thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Methylphenidate Hydrochloride Market