
 Antidiarrhoeal Market | 2026-2036
Antidiarrhoeal Market Size, Share, and Industry Trends Forecast 2026-2036
Antidiarrhoeal Market Insights
Pharmacovigilance expertise is redrawing competitive boundaries in antidiarrhoeal development, as post-market safety monitoring becomes a prerequisite for OTC status upgrades. GlaxoSmithKline leverages its regulatory science infrastructure to sustain leadership across multiple therapy areas. Johnson & Johnson anchors its position through brand strength in consumer health channels. Perrigo Company specializes in private-label manufacturing, competing aggressively on cost and distribution scale.
Antidiarrhoeals comprise pharmacological agents that modulate intestinal motility, fluid secretion, or microbial balance, with formulations typically containing active concentrations between 2 mg and 262 mg depending on mechanism. These agents serve to restore gastrointestinal function across acute infectious episodes, chronic functional disorders, and drug-induced diarrhoea. Loperamide dominates the product type landscape due to its mu-opioid receptor selectivity and established OTC status, while bismuth subsalicylate captures significant share through dual antibacterial and antisecretory action. Liquid suspension formats are gaining traction fastest among paediatric and geriatric populations where swallowing compliance limits tablet uptake.
FDA bioequivalence requirements and EMA OTC switch pathways govern market access for reformulated antidiarrhoeals, with WHO prequalification standards additionally shaping procurement in low-income settings. The EU F-Gas Regulation and REACH chemical safety protocols influence excipient selection and manufacturing location decisions for European supply. Stakeholders must monitor evolving pharmacovigilance mandates and paediatric indication expansions as the primary vectors of portfolio repositioning.
Market Dynamics
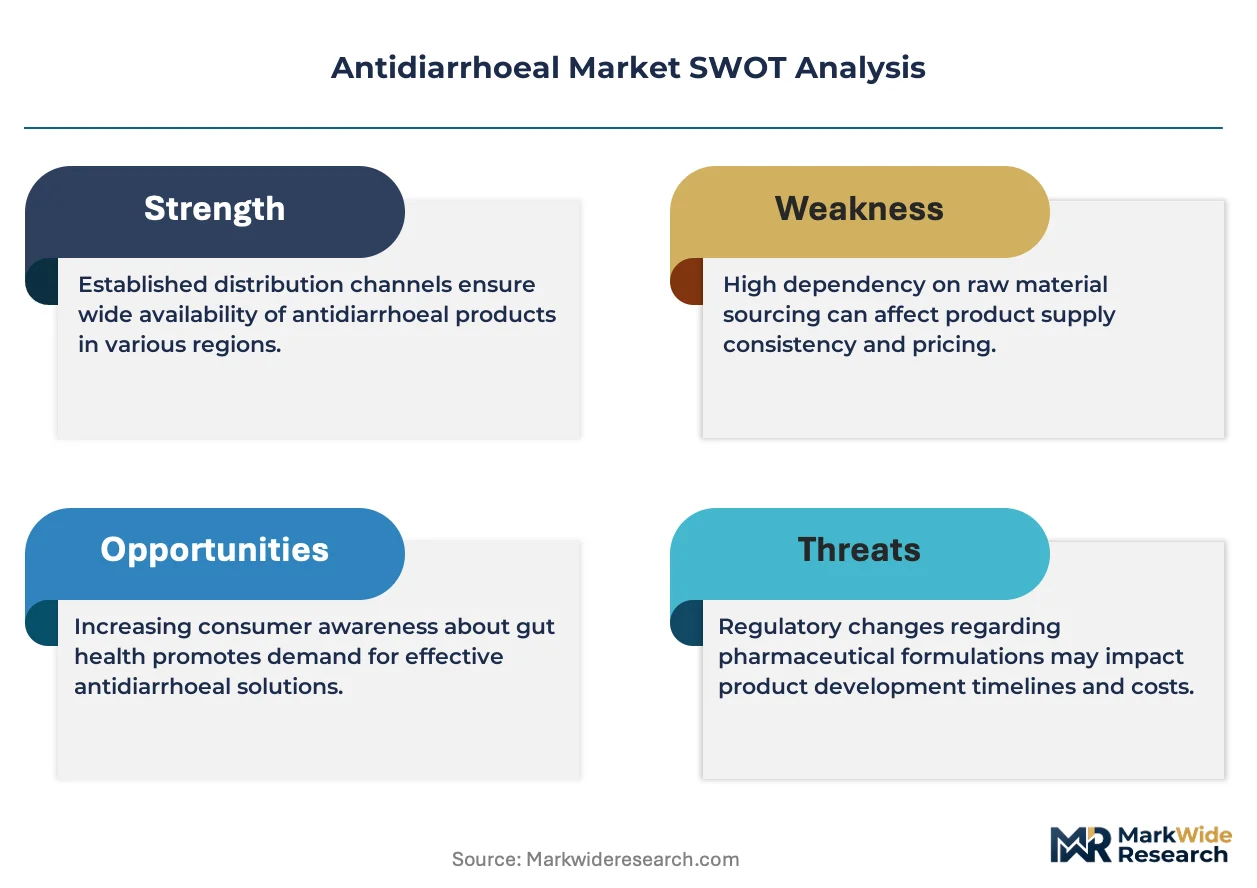
FDA and EMA pharmacovigilance mandates for OTC switches are restructuring competitive entry barriers, forcing developers to build post-market surveillance infrastructure before commercialization rather than retrofitting compliance retroactively.
Growth Catalysts
- OTC Switch Pathways:FDA bioequivalence standards for prescription-to-OTC transitions are accelerating portfolio expansions. Manufacturers who pre-invest in clinical safety databases capture first-mover positioning in self-medication segments.
- India:Pharmacy network densification in tier-2 and tier-3 cities is expanding addressable populations. CDSCO streamlined approval processes for fixed-dose combinations are shortening time-to-market for reformulated antidiarrhoeals.
- Liquid Suspension Manufacturing:Pediatric and geriatric formulation capabilities are differentiating contract manufacturers. Facilities with aseptic filling lines for unit-dose sachets command premium capacity allocations from multinational marketers.
Market Restraints
- API Concentration:Loperamide hydrochloride active pharmaceutical ingredient production concentrates in Chinese and Indian chemical clusters. Single-source dependencies create vulnerability to environmental compliance shutdowns and export restriction volatility.
- Excipient Cost Volatility:Bismuth subsalicylate supply faces price pressure from mining concentration in Peru and Bolivia. Currency fluctuation and export quota regimes transmit directly into formulation cost structures.
- Substitution Threat:Probiotic interventions for acute infectious diarrhoea are capturing physician preference in European and North American markets. EMA guidance on microbiome therapeutics is legitimating competitive displacement at the point of prescription.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization with FDA standards is reducing duplicative clinical requirements. Self-medication culture expansion in São Paulo and Rio de Janeiro pharmacy chains creates whitespace for premium-positioned brands.
- Telehealth Integration:Remote diagnostic platforms are embedding antidiarrhoeal recommendations into algorithmic treatment protocols. Partnerships with digital health providers enable direct-to-patient fulfillment bypassing traditional wholesale channels.
- WHO Prequalification:Procurement eligibility for UN agency and government tenders in sub-Saharan Africa and South Asia requires manufacturing audit compliance. Early investment in prequalification opens institutional volume streams insulated from retail competition.
Industry Challenges
- Paediatric Trial Design:Ethical constraints on placebo-controlled studies in dehydrated children complicate indication expansion. Regulators demand innovative extrapolation methodologies that extend development timelines and consulting expenditure.
- Supply Chain Reconfiguration:EU F-Gas Regulation and REACH chemical safety protocols are forcing excipient sourcing shifts. Manufacturers must qualify alternative suppliers while maintaining batch-to-batch bioequivalence documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antidiarrhoeal Market |
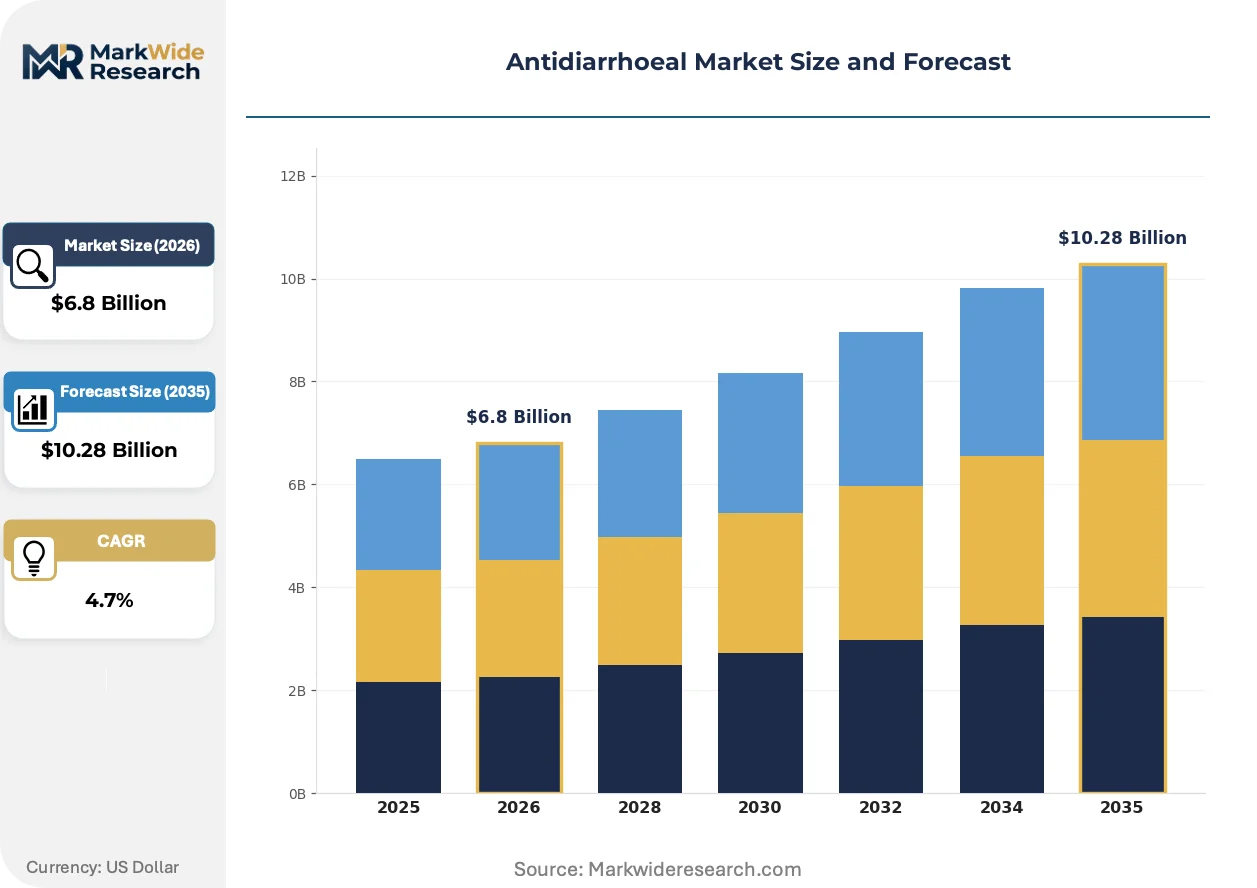
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loperamide, Bismuth Subsalicylate, Kaolin, Atropine Therapy Area: Acute Diarrhea, Chronic Diarrhea, Traveler's Diarrhea, Antibiotic-associated Diarrhea Delivery Mode: Oral Tablet, Liquid Suspension, Gel, Powder End User: Pharmacies, Hospitals, Clinics, Online Retailers |
| Companies Covered | GlaxoSmithKline, Pfizer, Johnson & Johnson, Lupin, Perrigo Company, Glenmark Pharmaceuticals, Sanofi, Novartis, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antidiarrhoeal Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how antidiarrhoeal therapies reach patients, with technology fragmentation and regulatory layering creating new competitive segmentation.
Orally disintegrating tablet platforms are fragmenting conventional swallowable dosage dominance. Geriatric populations in Japanese and European long-term care facilities are adopting these formats at accelerating rates. The technology is fragmenting procurement patterns as institutional buyers specify compliance-friendly alternatives that reduce aspiration risk and nursing administration burden.
EMA's F-Gas Regulation and REACH chemical safety protocols are mandating excipient substitution in European supply chains. Manufacturers are reformulating with alternative suspending agents and preservatives to maintain stability profiles. Pediatric liquid formulations face the most acute reformulation pressure as propellant and solvent restrictions tighten across German and French manufacturing sites.
Self-diagnostic integration into pharmacy retail is compressing the consultation-to-purchase cycle. Smartphone-enabled symptom checkers in Indian and Brazilian pharmacy apps are routing patients directly to algorithm-recommended antidiarrhoeal selections. This behavioral shift concentrates volume in private-label and pharmacist-recommended tiers rather than brand-loyal repeat purchases.
Antidiarrhoeal Market Segmentation
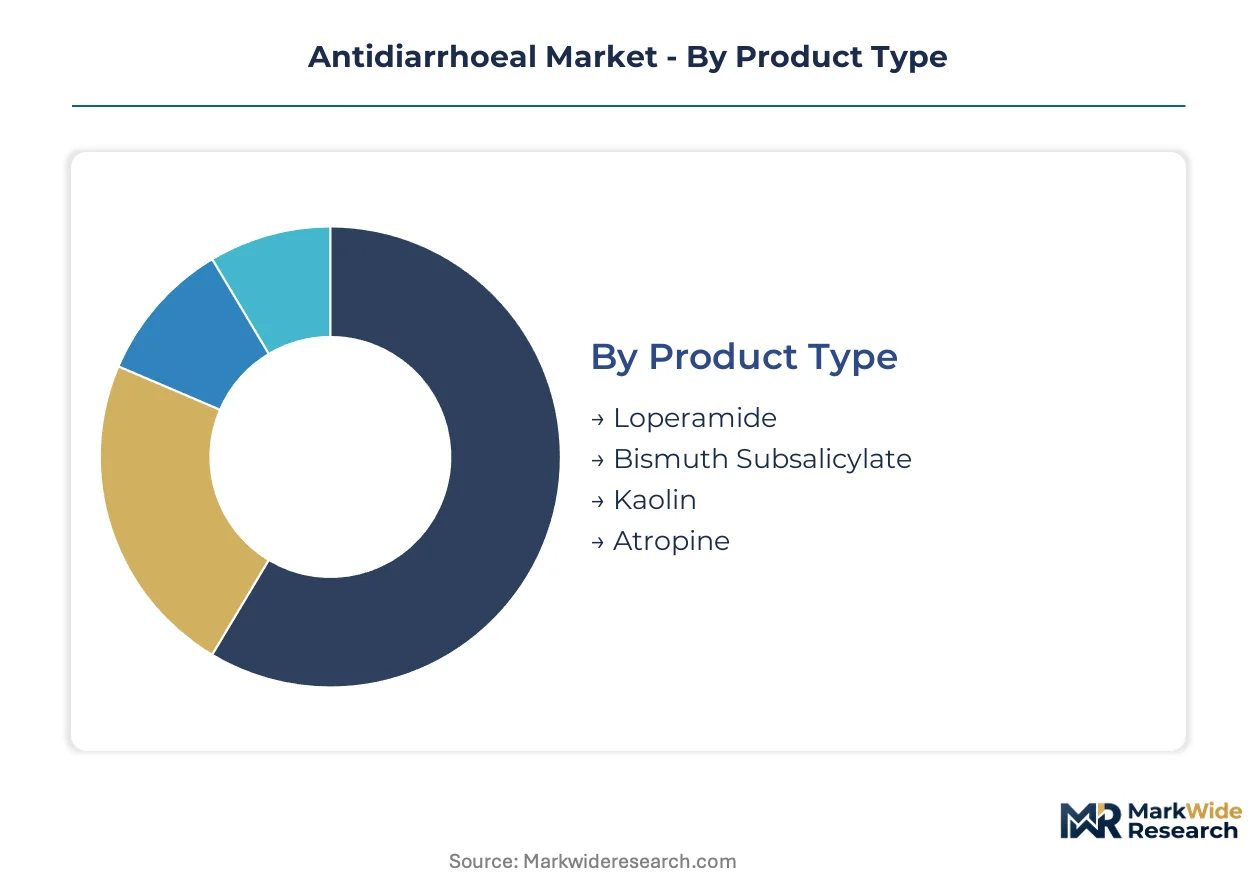
Antidiarrhoeal segmentation reflects divergent supply chain architectures, with some categories dominated by domestic formulation capacity and others dependent on cross-border API flows. Understanding these geographic fault lines shapes procurement strategy and regulatory compliance investment.
Product Type:
Loperamide and bismuth subsalicylate production clusters in Indian and Chinese chemical hubs, while kaolin and atropine sourcing spans domestic mining and botanical extraction networks across multiple continents.
- Loperamide:Mu-opioid receptor agonist synthesized at 2 mg standard dose, with hydrochloride salt form enabling stable tablet compression. Indian API manufacturers in Hyderabad and Ahmedabad supply formulation facilities across Southeast Asia and Latin America; FDA bioequivalence documentation requirements favor established producers with pre-existing safety databases.
- Bismuth Subsalicylate:Dual-action agent combining antibacterial and antisecretory mechanisms, typically dosed at 262 mg per unit. Mining concentration in Peru's Cerro de Pasco region and Bolivia's Potosí department creates export dependency for North American and European formulators; currency volatility in Andean markets transmits directly into cost structures.
- Kaolin:Natural hydrated aluminum silicate clay with adsorbent properties, sourced from domestic deposits in Georgia (US), Cornwall (UK), and Jiangxi province (China).
- Atropine:Belladonna alkaloid with antispasmodic action, extracted from Datura and Atropa cultivation in Eastern European and Indian agricultural zones.
Loperamide holds the largest share; momentum sits with bismuth subsalicylate as travelers' health positioning expands in pharmacy channels.
Therapy Area:
Acute infectious presentations drive volume through retail pharmacy, while chronic and iatrogenic indications concentrate prescribing in hospital and specialty clinic settings with higher reimbursement complexity.
- Acute Diarrhea:Self-limiting infectious episodes lasting under 14 days, comprising viral, bacterial, and parasitic etiologies. Pharmacy-first treatment seeking in India, Brazil, and Nigeria concentrates OTC volume; WHO prequalification requirements shape procurement for institutional programs in sub-Saharan Africa.
- Chronic Diarrhea:Persistent symptoms exceeding four weeks, often associated with functional disorders, malabsorption syndromes, or endocrine dysfunction. Gastroenterology clinic prescribing in Germany, Japan, and the United States favors prescription-grade formulations with documented efficacy in refractory cases.
- Traveler's Diarrhea:Enterotoxigenic E. coli and other pathogen exposure during international travel. Airport pharmacy and pre-travel clinic channels in London Heathrow, Dubai International, and Singapore Changi anchor premium positioning.
- Antibiotic-associated Diarrhea:Clostridioides difficile and microbiome disruption following antimicrobial therapy. Hospital formulary inclusion requires pharmacovigilance infrastructure that smaller manufacturers struggle to maintain.
Acute diarrhea commands volume leadership; antibiotic-associated diarrhea is climbing the fastest as antimicrobial stewardship programs expand surveillance.
Delivery Mode:
Tablet manufacturing localizes near population centers to minimize distribution cost, while liquid suspension production concentrates in specialized aseptic facilities serving pediatric and geriatric export markets.
- Oral Tablet:Compressed solid dosage with coating for moisture protection and taste masking. Contract manufacturers in Gujarat and Zhejiang province supply private-label programs for European and North American retailers; unit cost advantages sustain margin pressure on branded alternatives.
- Liquid Suspension:Aqueous or oil-based dispersed systems with suspending agents and preservatives for pediatric and dysphagia populations. Aseptic filling lines in Ireland, Switzerland, and Singapore command premium capacity allocations; EMA F-Gas Regulation is forcing propellant substitution in European production.
- Gel:Semisolid hydrocolloid systems for buccal or oral delivery, niche positioning in Japanese and South Korean markets.
- Powder:Reconstitutable dry blends for sachet packaging, expanding in Indian and Nigerian pharmacy channels with clean water access requirements.
Oral tablets dominate manufacturing scale; liquid suspension formats are gaining share fastest among aging populations and pediatric segments.
End User:
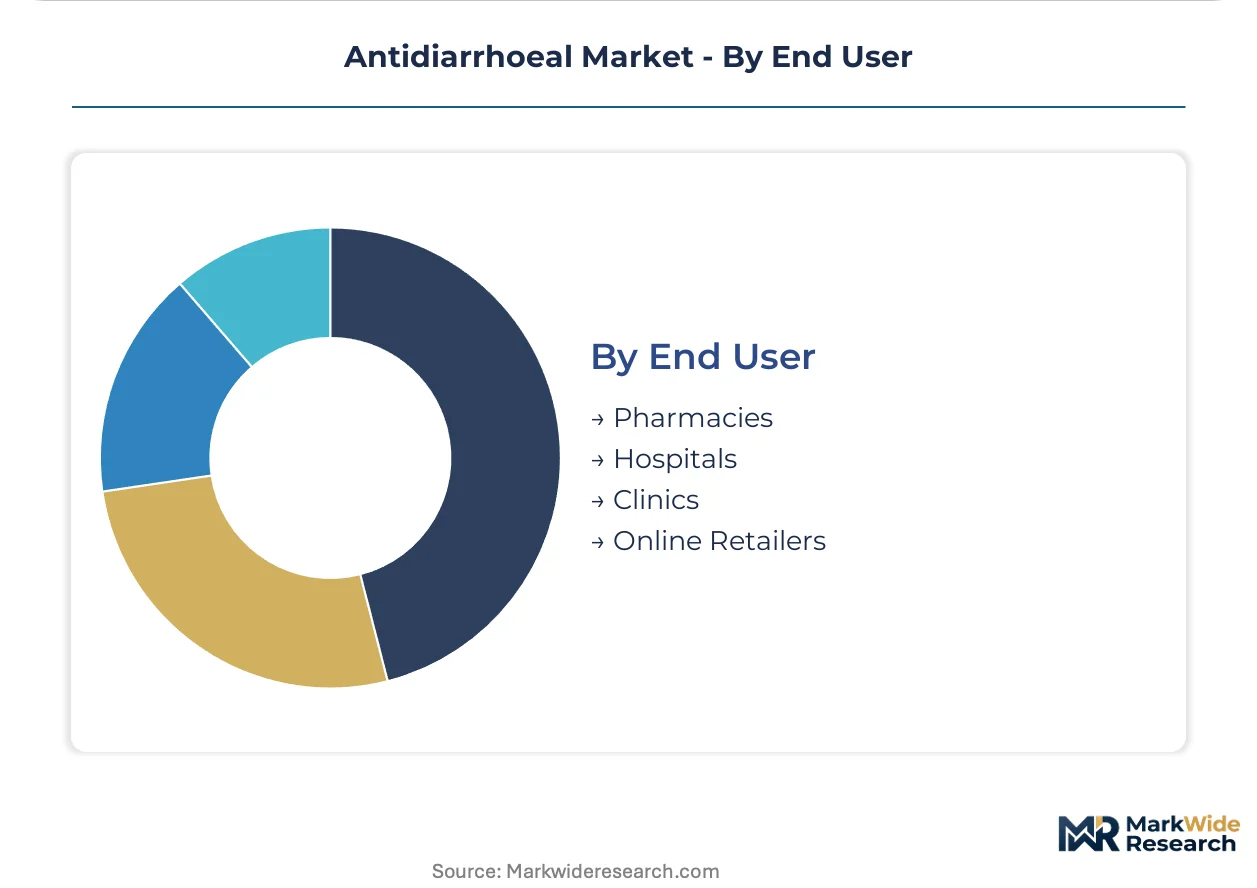
Pharmacy and hospital procurement operate on divergent tender timelines, with retail chains consolidating supplier relationships while institutional buyers fragment across regional health authorities.
- Pharmacies:Community and chain retail dispensing with pharmacist recommendation influence. CVS, Walgreens, and Boots networks in the United States and United Kingdom concentrate volume; Indian Apollo and MedPlus chains are expanding tier-2 and tier-3 city coverage.
- Hospitals:Inpatient and emergency department formulary procurement with clinical committee oversight. NHS Trusts in England and integrated delivery networks in Texas and California drive standardization toward preferred therapeutic classes.
- Clinics:Outpatient and urgent care settings with limited on-site pharmacy. Federally qualified health centers in the United States and polyclinics in Russia and Eastern Europe represent fragmented, price-sensitive demand.
- Online Retailers:Direct-to-consumer platforms with algorithmic recommendation engines. Amazon Pharmacy, 1mg in India, and Zur Rose in Germany are compressing traditional wholesale margins.
Pharmacies retain the largest channel share; online retailers are expanding most quickly as telehealth integration accelerates prescription-to-fulfillment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Brazil consume antidiarrhoeals primarily through self-medication channels, while Germany and Japan route most volume through prescription-controlled pharmacy networks, creating divergent regulatory compliance burdens for multinational formulators.
United States
CVS and Walgreens chains concentrate OTC volume in suburban markets, with pharmacist recommendation algorithms steering patients toward loperamide-based options. FDA bioequivalence documentation requirements favor established producers with pre-existing safety databases. New Jersey and Pennsylvania formulation clusters supply private-label programs for national retailers.
India
Apollo and MedPlus pharmacy chains are expanding tier-2 and tier-3 city coverage, capturing rising self-medication demand. CDSCO streamlined approval processes for fixed-dose combinations shorten time-to-market for reformulated products. Hyderabad and Ahmedabad API manufacturers supply formulation facilities across Southeast Asia and Latin America.
Germany
NHS Trusts and integrated delivery networks drive standardization toward preferred therapeutic classes with documented pharmacovigilance infrastructure. EMA F-Gas Regulation and REACH chemical safety protocols force excipient substitution in domestic manufacturing. Bavarian and North Rhine-Westphalian production sites reformulate with alternative suspending agents to maintain stability profiles.
Brazil
ANVISA regulatory harmonization with FDA standards reduces duplicative clinical requirements for market entry. São Paulo and Rio de Janeiro pharmacy chains concentrate whitespace for premium-positioned brands as self-medication culture expands. Domestic formulators leverage regional manufacturing cost advantages to supply Andean markets.
Japan
Geriatric populations in long-term care facilities drive adoption of orally disintegrating tablet formats that reduce aspiration risk. METI and PMDA guidance on pediatric trial design complicates indication expansion through ethical constraints on placebo-controlled studies. Kanto and Kansai manufacturing clusters specialize in aseptic filling lines for unit-dose sachets serving export markets.
Antidiarrhoeal Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated prescription-to-OTC switch capabilities distinguishing the upper stratum from contract-dependent competitors. The upper tier commands preferred supplier status with institutional procurement committees through captive pharmacovigilance infrastructure. Three archetypes populate the competitive map: multinational pharmaceutical conglomerates with regulatory science depth, private-label specialists competing on manufacturing scale, and regional formulators with domestic distribution lock-in. Capacity expansion in pediatric liquid suspension formats and strategic partnerships with telehealth platforms represent the dominant competitive vectors reshaping positioning.
Among the integrated multinational tier, GlaxoSmithKline and Johnson & Johnson occupy positions anchored by consumer health channel dominance and established OTC brand equity. Perrigo Company exemplifies the private-label manufacturing archetype, competing through cost structures and distribution scale rather than proprietary formulation differentiation. These three entities collectively represent the competitive tension between regulatory-science-driven premium positioning and manufacturing-efficiency-driven volume capture that defines current market dynamics.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Pfizer |
| Johnson & Johnson |
| Lupin |
| Perrigo Company |
| Glenmark Pharmaceuticals |
| Sanofi |
| Novartis |
| Bayer |
| Others |
Pricing and Supply Chain Analysis
FDA bioequivalence documentation requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to pre-invest in clinical safety databases before capturing premium positioning in OTC channels. This regulatory threshold stratifies the market into validated incumbents with established pharmacovigilance infrastructure and cost-pressured challengers competing on manufacturing scale alone.
Pricing Analysis
Contract-based long-term offtake agreements anchor procurement relationships between multinational marketers and Indian API manufacturers, while spot purchasing dominates excipient sourcing from Andean mining regions. Price differentiation hinges on FDA bioequivalence certification tier and pediatric formulation capabilities, with aseptic filling lines commanding substantial premiums over standard tablet compression. Cost compression in private-label tiers is intensifying because contract manufacturers in Gujarat and Zhejiang province compete aggressively on unit economics. Hospital procurement committees exhibit the lowest price sensitivity due to formulary standardization requirements, whereas retail pharmacy chains in tier-2 Indian cities drive the hardest volume-based negotiations.
Supply Chain Analysis
Inventory lead times for bismuth subsalicylate extend significantly during Peruvian and Bolivian export quota regimes, forcing European formulators to maintain buffer stocks or qualify alternative suppliers. Loperamide hydrochloride API production concentrates in India and China, while atropine extraction draws from Eastern European and Indian agricultural zones. Single-source vulnerability in Andean bismuth mining creates exposure to currency fluctuation and environmental compliance shutdowns. Distribution runs through regional formulation hubs that supply finished goods to pharmacy chains and hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacovigilance infrastructure represents a service-attach opportunity expanding faster than core formulation manufacturing, as post-market safety monitoring contracts generate recurring revenue streams insulated from commodity API pricing cycles.
For Market Incumbents: Shield formulary positions by deepening backward integration into pediatric liquid suspension manufacturing in Ireland and Singapore, where aseptic capacity scarcity limits competitor replication. Fortify against probiotic substitution threats by embedding antidiarrhoeal recommendations into telehealth algorithmic protocols, creating channel control that bypasses traditional pharmacy retail.
For New Entrants and Emerging Players: Differentiate on WHO prequalification compliance to capture institutional procurement in sub-Saharan Africa and South Asia, where UN agency tenders favor audited manufacturers over retail competitors. Target Brazilian pharmacy chains in São Paulo and Rio de Janeiro, where ANVISA regulatory harmonization reduces clinical requirements and self-medication culture creates whitespace for premium-positioned entrants. Pursue direct partnerships with digital health platforms enabling algorithmic treatment recommendations and direct-to-patient fulfillment.
For Investors and Strategic Acquirers: EMA F-Gas Regulation and REACH chemical safety protocol enforcement reshapes the acquisition landscape toward formulators with proven excipient substitution capabilities and alternative supplier qualification expertise. Long-term viability centers on manufacturers with captive pharmacovigilance infrastructure serving hospital formulary committees. The signal to monitor is pediatric indication expansion approvals, which extend addressable populations and command pricing premiums in institutional procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | Orally disintegrating tablets and liquid suspensions capture geriatric and pediatric demand in Japanese long-term care. |
| OTC Switch Pathway Investment | FDA bioequivalence documentation builds defensible positioning in self-medication segments ahead of competitor entries. |
| Telehealth Platform Partnership | Algorithmic treatment integration compresses consultation-to-purchase cycles and bypasses traditional wholesale channels. |
| WHO Prequalification Compliance | Manufacturing audit eligibility opens UN agency and government tenders in sub-Saharan Africa and South Asia. |
| Excipient Supplier Diversification | Alternative suspending agent qualification maintains European supply continuity under F-Gas Regulation constraints. |
Research Methodology
Cross-validation between regulatory filing analysis and channel procurement data anchors the qualitative findings, combining primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing triangulate volume estimates across the analysis window.
Sensitivity analysis on API cost volatility and regulatory approval timelines informs the analytical framework, with segmentation dimensions including product mechanism, dosage form, therapy area, and regional regulatory cluster modeled throughout the forecast period. CAGRs derive from epidemiological trend extrapolation, pricing trajectory assessment, and channel shift velocity, incorporating antimicrobial stewardship program expansion and self-medication rate growth as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable regulatory harmonization and continued pharmacy network densification in emerging markets; material deviation in API supply disruption frequency or probiotic therapeutic guideline adoption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Estonia Pharmaceutical Market