
 Oral Care Market | 2026-2036
Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Care Market Intelligence
Professional dental patients and orthodontic users are redrawing demand priorities across the Oral Care Market. Colgate-Palmolive leverages its therapeutic toothpaste formulations to sustain pharmacy channel dominance. Procter & Gamble anchors premium electric toothbrush growth through technology leadership in connected devices. Unilever competes in emerging markets with region-specific herbal formulations.
Oral care encompasses products engineered for dental hygiene maintenance, including formulations containing fluoride at 1000-1500 ppm for caries prevention and abrasives such as hydrated silica with controlled Relative Dentin Abrasivity values below 250. These products serve preventive dentistry by reducing plaque accumulation and managing gingival inflammation. Toothpaste occupies the largest margin pool due to repeat purchase frequency and formulation complexity. Mouthwash demonstrates the fastest structural growth as consumers integrate multi-step regimens. Dental clinics as a distribution channel concentrate premium professional-grade sales.
The FDA governs active ingredients in anticaries and antigingivitis products through its ongoing monograph revision process. The EPA regulates triclosan and other antimicrobial agents in oral rinses under environmental safety mandates. ISO 11609 standardizes toothpaste testing methods for abrasivity and fluoride release. Stakeholders must monitor regulatory shifts toward microbiome-friendly formulations and biocompatibility certifications.
Market Dynamics
The FDA's ongoing monograph revision for over-the-counter oral care products is forcing reformulation cycles across fluoride and antimicrobial categories, compressing R&D timelines while elevating biocompatibility testing costs for manufacturers.
Growth Catalysts
- India's tier-2 pharmacy expansion:Dental awareness campaigns in secondary cities accelerate channel penetration for therapeutic toothpaste formats.
- School-based pediatric programs:Government-funded dental screening initiatives create institutional demand volumes for fluoride varnish and sealant applications.
- ISO 11609 standardization:Harmonized abrasivity and fluoride release testing methods reduce regulatory friction for cross-border product registrations.
Market Restraints
- Triclosan phase-out mandates:EPA environmental safety rulings on antimicrobial rinses force inventory write-downs and supply chain requalification.
- Hydrated silica supply concentration:Abrasive sourcing clusters in China's industrial zones expose formulators to shipping volatility and input cost swings.
- Microbiome certification gaps:Absence of standardized biocompatibility protocols delays premium positioning for probiotic oral care launches.
Strategic Opportunities
- Connected device convergence:Pressure sensors and Bluetooth-enabled brushing analytics integrate with dental practice management software for remote patient monitoring.
- Herbal formulation white space:Region-specific botanical extracts target underserved preference clusters in Southeast Asian pharmacy channels.
- Professional-grade direct-to-consumer:Dental clinic exclusivity models loosen as prescription-strength remineralization kits migrate to verified online platforms.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in fluoride stabilization and abrasive particle engineering commands premium compensation, constraining mid-tier R&D expansion.
- Legacy ERP integration:Batch record systems for GMP-compliant oral care manufacturing resist real-time connectivity with modern quality management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Care Market |
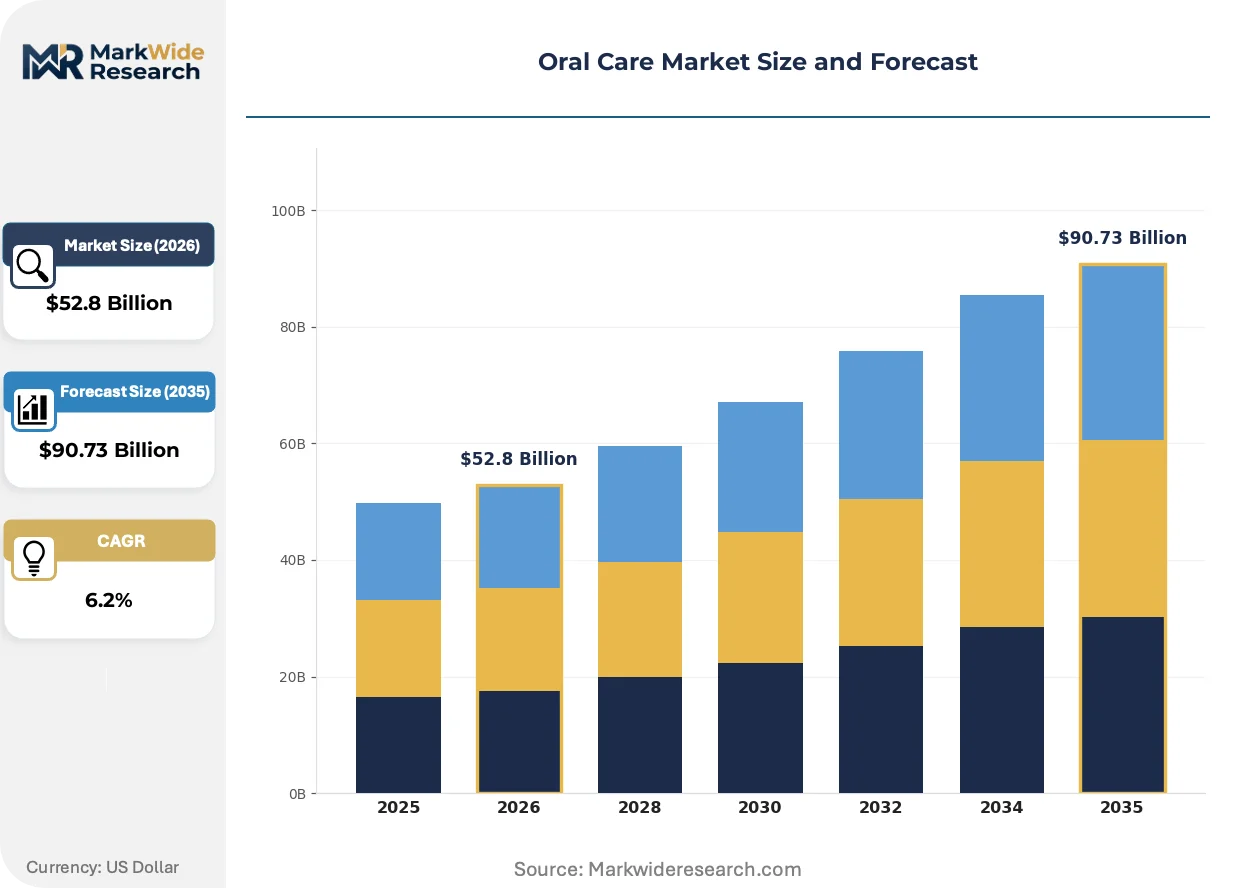
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $90.73 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Toothbrushes, Whitening Strips, Oral Rinses Application: Teeth Whitening, Cavity Protection, Gum Care, Fresh Breath, Sensitivity Relief, Plaque Control End User: Adults, Children, Seniors, Pregnant Women, Orthodontic Patients Distribution Channel: Supermarkets & Hypermarkets, Pharmacies, Online Retailers, Specialty Stores, Dental Clinics |
| Companies Covered | Johnson & Johnson, Church & Dwight, Colgate-Palmolive, Henkel, Dentsply Sirona, Procter & Gamble, GlaxoSmithKline, Lion Corporation, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Care Market Strategic Shifts & Innovations
Digital diagnostics and biocompatible materials are restructuring how oral care products demonstrate efficacy and secure professional endorsement. Formulation science now competes directly with hardware interfaces for consumer attention and dental practice loyalty.
Smart electric toothbrush platforms with real-time pressure mapping and brushing duration analytics are decomposing the traditional two-year replacement cycle into continuous software-subscription relationships. Orthodontic patients and periodontal maintenance cases adopt these connected devices fastest, generating data streams that dental practices use to justify professional-grade product recommendations and compress routine checkup intervals.
REACH restrictions on persistent antimicrobial substances are forcing oral rinse manufacturers toward enzymatic and prebiotic preservation systems. The EU's chemical safety framework now classifies several legacy antiseptic actives as substances of very high concern, compelling reformulation investments that favor biotech-derived alternatives. German and French pharmacy buyers increasingly demand full material disclosure certificates ahead of listing decisions.
Subscription-based replenishment models for replacement brush heads and therapeutic pastes are capturing high-lifetime-value households through direct channels. Dental insurance plans in the United States now partially reimburse connected preventive devices, shifting volume away from retail pharmacy endcaps toward verified digital platforms. This channel migration concentrates margin capture with manufacturers owning the full hardware-consumables ecosystem.
Oral Care Market Segmentation
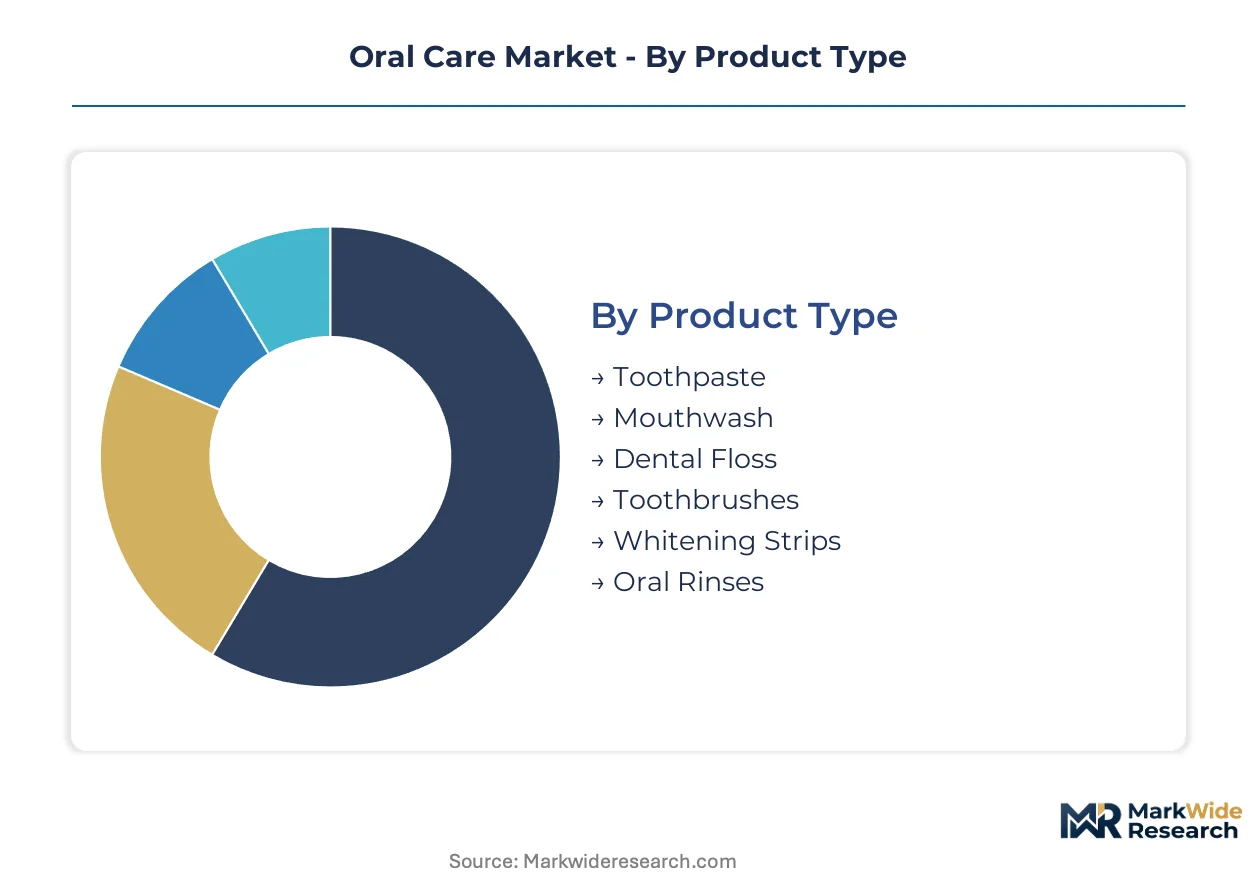
Segmentation in oral care separates mass-market commodity plays from defensible premium positions. Formulation complexity, channel access, and patient-specific clinical claims determine margin capture across each divide.
Product Type:
Geographic demand concentration varies sharply by product category, with therapeutic formats anchored in pharmacy channels and cosmetic innovations driven by export-led premium markets.
- Toothpaste:Formulations containing stabilized fluoride at therapeutic concentrations and engineered abrasive systems dominate household penetration. India's tier-2 pharmacy networks and North American mass retail channels concentrate volume, though FDA monograph compliance costs favor multinational formulators with dedicated regulatory affairs teams.
- Mouthwash:Antiseptic and cosmetic rinse formats with alcohol-free and essential oil bases are displacing legacy formulations. German and French pharmacy buyers drive premium positioning through material disclosure requirements, while EPA triclosan phase-outs force North American inventory restructuring.
- Dental Floss:Waxed and unwaxed nylon monofilament variants serve interdental cleaning compliance gaps.
- Toothbrushes:Manual designs with tapered filament technology compete against connected electric platforms with pressure mapping.
- Whitening Strips:Peroxide-based adhesive systems target cosmetic demand clusters in direct-to-consumer channels.
- Oral Rinses:Prebiotic and enzymatic preservation systems respond to REACH restrictions on persistent antimicrobials.
Toothpaste commands the established base. The steepest expansion runs through mouthwash as multi-step regimens penetrate developed markets.
Application:
Cost tier stratification separates reimbursed clinical indications from discretionary cosmetic positioning, with insurance coverage eligibility determining pricing architecture.
- Cavity Protection:Fluoride remineralization claims supported by clinical trial data anchor pediatric and senior segments. School-based screening programs in India and Medicaid reimbursement pathways in the United States institutionalize demand for professional-grade varnish applications.
- Gum Care:Antigingivitis actives with FDA monograph recognition command pharmacy shelf placement premiums. Japanese periodontal maintenance protocols and German statutory insurance coverage create concentrated demand for therapeutic rinse formats.
- Teeth Whitening:Peroxide and non-peroxide cosmetic systems target aesthetic-conscious consumer segments.
- Fresh Breath:Masking and neutralizing formulations serve immediate social utility needs.
- Sensitivity Relief:Potassium nitrate and arginine-based occlusive technologies address dentin hypersensitivity.
- Plaque Control:Mechanical and chemical disruption claims support preventive dentistry positioning.
Cavity protection holds the volume foundation. Gum care is climbing the fastest as aging populations expand periodontal maintenance needs.
End User:
Customer type determines formulation specifications, packaging safety requirements, and channel access strategies across the lifecycle.
- Adults:General population formulations with cosmetic and therapeutic variants represent the default mass-market configuration.
- Children:Lower fluoride concentrations, flavor masking systems, and child-resistant packaging respond to accidental ingestion risks. India's school dental programs and US pediatric dentistry guidelines institutionalize volume for sealant and varnish applications.
- Seniors:Dry mouth formulations and adapted grip packaging address polypharmacy and dexterity constraints.
- Pregnant Women:Alcohol-free and specific active restrictions respond to gestational safety protocols.
- Orthodontic Patients:Specialized cleaning tools and fluoride supplementation target appliance-related hygiene challenges.
Adults anchor the revenue base. Orthodontic patients are expanding most quickly through teenage alignment therapy growth.
Distribution Channel:
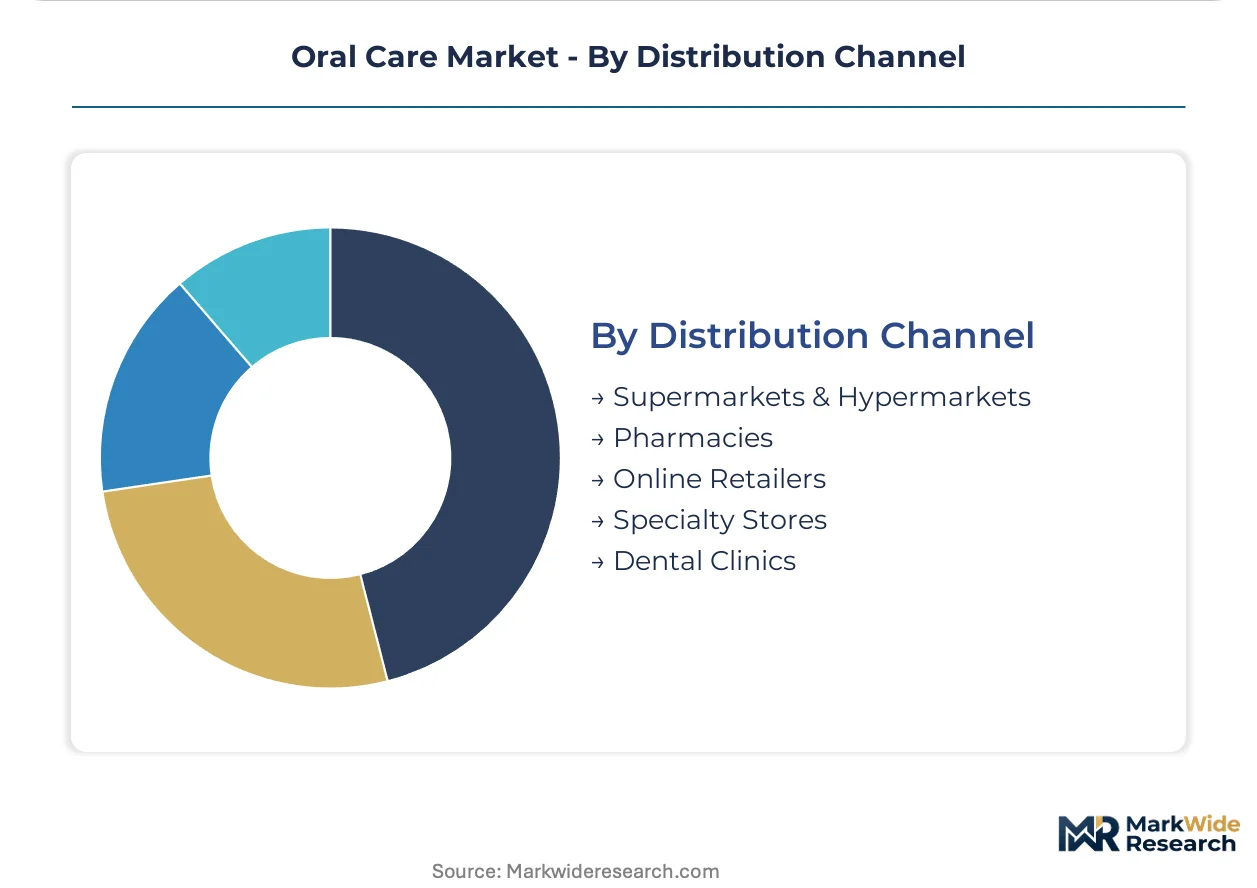
Channel selection dictates margin structure, with professional gatekeeping concentrated in clinical settings and volume scale concentrated in mass retail.
- Pharmacies:Therapeutic toothpaste and clinically validated mouthwash formats depend on pharmacist recommendation and OTC monograph compliance. India's tier-2 expansion and German pharmacy loyalty programs concentrate growth for evidence-based positioning.
- Dental Clinics:Professional-grade products with prescription-strength actives and procedure-linked bundling capture premium pricing. United States dental insurance reimbursement for connected devices is shifting volume toward verified digital platforms.
- Supermarkets & Hypermarkets:Mass-market SKUs with promotional frequency drive household penetration scale.
- Online Retailers:Subscription replenishment and direct-to-consumer professional kits bypass traditional gatekeepers.
- Specialty Stores:Premium cosmetic and natural positioning targets preference-driven segments.
Pharmacies defend the established margin pool. Dental clinics are gaining share fastest as professional endorsement commands pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss specialty chemical exports supply fluoride stabilization compounds to Indian formulators operating in Mumbai and Ahmedabad production corridors.
United States
Dental insurance reimbursement for connected preventive devices accelerates direct-to-consumer channel migration. FDA monograph revisions on anticaries actives compress R&D timelines for domestic manufacturers. Boston and Minneapolis medical device clusters concentrate smart toothbrush engineering talent and Bluetooth-enabled pressure sensor development.
Germany
REACH restrictions on persistent antimicrobials force enzymatic rinse reformulation investments across pharmacy suppliers. ECHA substance-of-very-high-concern classifications disrupt legacy antiseptic supply chains. Frankfurt and Düsseldorf pharmaceutical distribution hubs enforce material disclosure certificate requirements ahead of pharmacy listing decisions.
India
Government-funded school dental screening programs institutionalize demand for fluoride varnish and sealant applications. BIS standards for oral care products harmonize with ISO 11609 testing protocols. Tier-2 cities including Indore, Lucknow, and Coimbatore concentrate pharmacy channel expansion and dental awareness campaign deployment.
Japan
Aging demographics expand periodontal maintenance protocol adoption and therapeutic rinse consumption. PMDA regulatory pathways for quasi-drug oral care claims require clinical substantiation dossiers. Osaka and Nagoya industrial zones host precision abrasive manufacturing for controlled Relative Dentin Abrasivity formulations.
China
Dual carbon goals and environmental compliance mandates reshape hydrated silica abrasive sourcing from Shandong industrial zones. NMPA cosmetic and quasi-drug classification systems determine fluoride concentration labeling requirements. Guangzhou and Shanghai consumer goods clusters drive electric toothbrush assembly scale and connected device firmware development.
Oral Care Market Key Industry Players
Listed leaders compete with private specialists across formulation complexity and channel access dimensions. The market structure concentrates around multinational consumer goods conglomerates with dedicated regulatory affairs teams and pharmacy distribution scale, while regional herbal specialists capture preference-driven segments. Three archetypes dominate: therapeutic formulators with FDA monograph compliance capabilities, connected device hardware-software integrators, and botanical extract specialists targeting Southeast Asian pharmacy channels. Competitive moves center on subscription-based replenishment model deployment and professional-grade product direct-to-consumer migration.
Within the therapeutic formulator tier, Colgate-Palmolive and GlaxoSmithKline occupy positions anchored by pharmacy channel dominance and clinical validation infrastructure. Procter & Gamble exemplifies the connected device integrator archetype through hardware-consumables ecosystem ownership. Among Asia-Pacific specialists, Lion Corporation represents region-specific formulation adaptation capabilities.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Church & Dwight |
| Colgate-Palmolive |
| Henkel |
| Dentsply Sirona |
| Procter & Gamble |
| GlaxoSmithKline |
| Lion Corporation |
| Unilever |
| Others |
Cost & Logistics Intelligence
FDA monograph compliance gates both supply qualification and price differentiation simultaneously, as manufacturers must absorb biocompatibility testing costs and reformulation cycles that stratify market positions between multinational formulators with dedicated regulatory teams and regional players priced out of therapeutic tiers.
Pricing Analysis
Current-generation connected electric toothbrushes with pressure mapping and Bluetooth analytics command subscription-linked premiums against prior-generation manual designs and next-generation AI-integrated platforms still in clinical validation. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade clinic bundles from mass retail SKUs and private-label pharmacy entries, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in mid-tier therapeutic toothpaste is intensifying because of FDA monograph revision compliance burdens, while orthodontic patients and periodontal maintenance cases show least price sensitivity due to insurance reimbursement pathways.
Supply Chain Analysis
Strategic stockpiling of fluoride stabilization compounds and engineered abrasives dominates over just-in-time preferences given regulatory batch testing requirements and supply concentration risks. Hydrated silica sourcing clusters in China, Germany, and India, with fluoride active ingredients drawing from Swiss and German specialty chemical exports. Single-source vulnerability in China's Shandong industrial zones for abrasive feedstocks compounds tariff exposure on cross-border chemical shipments. Distribution runs through pharmacy channel gatekeepers in developed markets and tier-2 city networks in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected device convergence and microbiome-friendly formulation mandates are disrupting competitive positions across the oral care landscape, creating asymmetric opportunities for stakeholders with regulatory affairs depth and hardware-software integration capabilities.
For Market Incumbents: Consolidate pharmacy channel control through exclusive professional-grade bundling with dental practice management software, while accelerating backward integration into fluoride stabilization compound production to offset hydrated silica cost volatility from Chinese industrial zones. FDA monograph revision timelines compress R&D windows, favoring incumbents with existing clinical validation infrastructure over mid-tier challengers. For New Entrants and Emerging Players: Anchor in India's tier-2 pharmacy expansion corridors where dental awareness campaigns are accelerating therapeutic format adoption ahead of multinational distribution buildout. Region-specific herbal formulations for Southeast Asian preference clusters offer the most penetrable white space, with direct-to-consumer subscription models bypassing traditional retail gatekeepers as the optimal go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across connected device hardware-software ecosystems as pressure sensor miniaturization and Bluetooth firmware development demand specialized engineering talent pools. Long-term viability over the next decade hinges on owning the full hardware-consumables relationship rather than component supply, with acquisition targets clustering around mid-cap dental diagnostics platforms possessing FDA 510(k) pathways and dental practice software integration capabilities. Watch for dental insurance reimbursement policy shifts as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Replenishment Model | Captures lifetime value through brush head and therapeutic paste auto-delivery, locking in pharmacy bypass. |
| Professional-Grade Direct-to-Consumer Migration | Prescription-strength remineralization kits on verified platforms loosen dental clinic exclusivity constraints. |
| Microbiome-Friendly Formulation Pivot | REACH restrictions on antimicrobials favor enzymatic and prebiotic preservation systems with biocompatibility certifications. |
| Connected Device Platform Integration | Pressure sensor data streams integrate with dental practice software for remote patient monitoring and compressed checkup intervals. |
| Region-Specific Herbal Line Extension | Botanical extracts target underserved preference clusters in Southeast Asian pharmacy channels ahead of multinational entry. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including brand managers at multinational consumer goods conglomerates, pharmacy channel buyers in India and Germany, formulation chemists specializing in fluoride stabilization, dental clinic procurement officers, and connected device firmware engineers. Secondary validation drew from FDA monograph revision dockets, EPA environmental safety rulings, ISO 11609 testing protocol documentation, BIS oral care standards, and trade flow data for hydrated silica and fluoride compound imports. Bottom-up product-level volume builds were triangulated against top-down macroeconomic healthcare expenditure trends.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, application indication, end-user lifecycle stage, and distribution channel access tier, with particular attention to orthodontic patient expansion rates and dental insurance reimbursement eligibility shifts. CAGRs were derived from regression analysis against demographic drivers, regulatory compliance cost trajectories, and channel migration patterns, with fluoride concentration tier adoption and connected device penetration serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued FDA monograph revision timelines and stable hydrated silica supply from Chinese industrial zones; material deviation would warrant model refresh. Revision becomes warranted when EPA antimicrobial phase-out enforcement intensity or dental insurance reimbursement scope crosses thresholds that alter professional-grade product accessibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Antiseptics Market
Oral Care
Oral Mucositis Market
Oral Care
Global Oral Care Products Market
Oral Care
Mouthwash Market
Oral Care
Toothcare Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Us Oral Care Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Herbal Toothcare Market
Oral Care
North America Oral Care Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Adult Oral Care Products Market
Oral Care
Oral Thin Films Market
Oral Care
Oral Thrush Market
Oral Care
Mouth Sore Medicine Market