
 Global Interdental Cleaning Products Market | 2026-2036
Global Interdental Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interdental Cleaning Products Market Intelligence
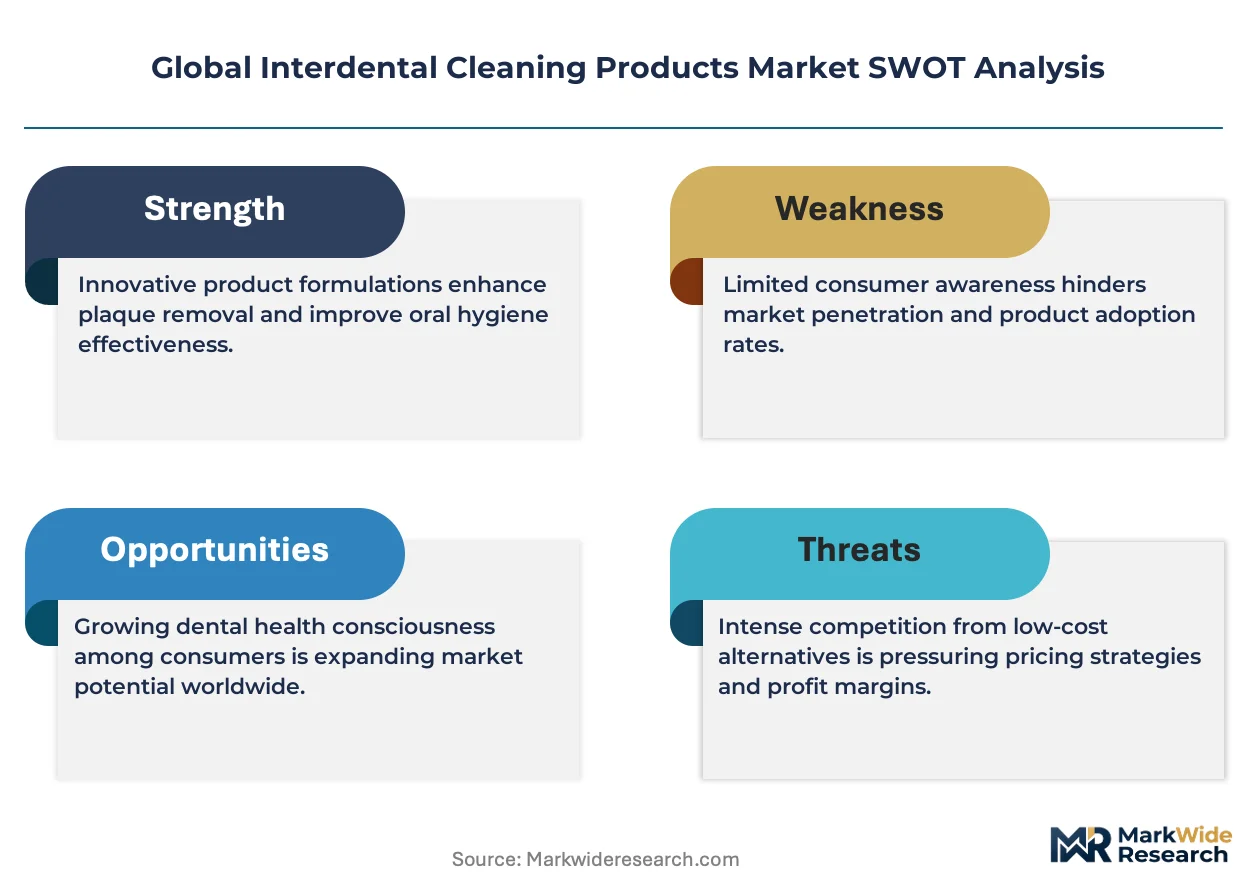
The substitution of traditional nylon filaments with biodegradable polylactic acid (PLA) alternatives is restructuring product cost structures and brand positioning. Colgate-Palmolive Company leverages its extensive distribution network to introduce these eco-friendly options into mass-market channels. Sunstar Suisse S.A. differentiates by focusing on specialized tools for periodontal care, while Procter & Gamble competes heavily on brand recognition and technological innovation within the water flosser category.
Interdental cleaning products are devices engineered to remove plaque and debris from between teeth, areas inaccessible to standard toothbrushes. These tools often feature fine-gauge, plastic-coated metal wires for brushes or high-tensile strength nylon for floss. Their primary function is the mechanical disruption of biofilm for plaque removal and gingivitis prevention. While interdental brushes command a significant market share, the water flossers segment is expanding rapidly, especially for complex needs like orthodontic cleaning.
Product safety and material claims are governed by multiple authorities. In the United States, the FDA classifies many of these items as Class I medical devices, while in Europe, they must adhere to CE marking standards under the Medical Device Regulation (MDR). China's NMPA imposes separate registration requirements. Navigating these disparate regulatory pathways for new biomaterials will determine market access and competitive advantage.
Market Dynamics
The convergence of consumer demand for sustainable products and stringent environmental regulations is the central force shaping the interdental cleaning products market. This pressure compels manufacturers to innovate away from traditional plastics toward biomaterials, altering cost structures and supply chain dependencies.
Growth Catalysts
- Professional Endorsement:Demand from dental hygienists and periodontists for more effective and specialized tools for managing conditions like gingivitis and peri-implantitis accelerates the development and adoption of advanced interdental brushes and water flossers.
- Sustainability Mandates:Regulations such as the EU Green Deal and related single-use plastics directives are creating a strong pull for products made from biodegradable materials like polylactic acid (PLA), particularly in the European market.
- Preventive Healthcare Focus:Heightened oral health awareness in developed economies, especially Germany and Japan, supports premium pricing and sustained demand for products that are part of a preventive daily hygiene routine, moving beyond basic tooth brushing.
Market Restraints
- Biomaterial Cost Premium:The higher input cost of biodegradable polymers like PLA compared to conventional nylon and petroleum-based plastics creates margin pressure and can limit adoption in price-sensitive segments or geographies.
- Regulatory Fragmentation:Navigating disparate and rigorous regulatory frameworks, including FDA classification in the US, CE marking under MDR in Europe, and NMPA registration in China, creates significant barriers to entry and slows new product introductions.
- Low Consumer Adherence:A persistent lack of consistent daily use of interdental cleaning products among the general population, often due to perceived difficulty or lack of time, remains a fundamental structural barrier to market expansion.
Strategic Opportunities
- Emerging Market Penetration:Untapped demand in large emerging economies with growing middle-class populations and increasing expenditure on personal healthcare presents a significant opportunity for volume growth and brand establishment.
- Specialized Clinical Applications:Developing products specifically for complex oral health needs, such as cleaning around orthodontic appliances, dental implants, and bridges, opens high-value niches underserved by standard floss.
- Smart Device Integration:Incorporating sensor technology and Bluetooth connectivity into electric devices like water flossers offers an opportunity to provide users with real-time feedback and personalized guidance, enhancing efficacy and user engagement.
Industry Challenges
- Supply Chain Realignment:Shifting production from established nylon filament and plastic handle supply chains to new, often less mature, suppliers of biomaterials like PLA introduces logistical complexities and potential quality control hurdles.
- Multi-Jurisdictional Compliance:The operational challenge of securing and maintaining separate regulatory approvals from the FDA, European Notified Bodies (for MDR), and China's NMPA for a single product line is resource-intensive and extends time-to-market.
- Consumer Education Gap:Overcoming consumer inertia and effectively communicating the clinical benefits of interdental brushes and water flossers over traditional string floss requires significant investment in marketing and educational initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interdental Cleaning Products Market |
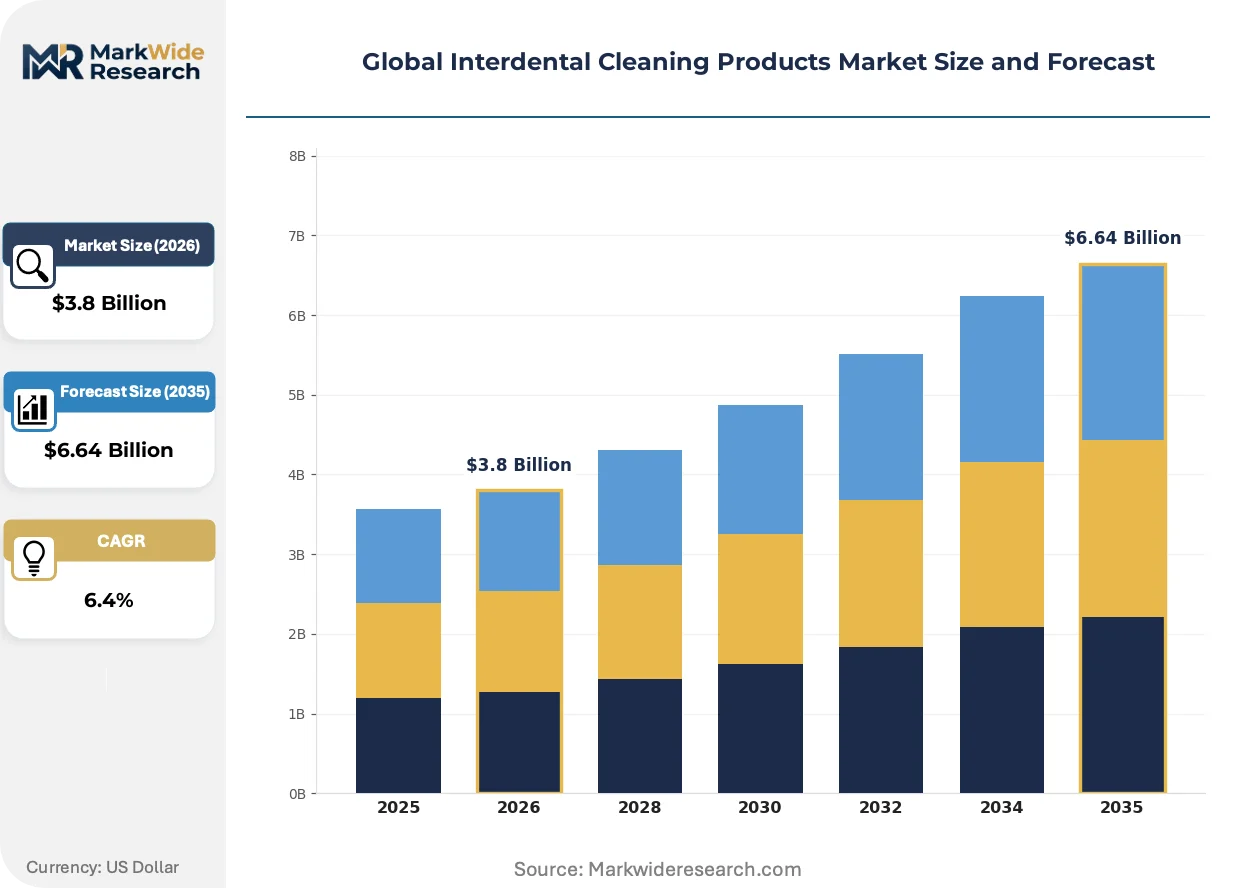
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interdental Brushes, Dental Floss, Floss Picks, Water Flossers, Soft Picks Material: Nylon Filaments, Silicone, Plastic Handles, Metal Wires, Rubber Bristles Application: Plaque Removal, Gingivitis Prevention, Periodontal Care, Orthodontic Cleaning End User: Dental Clinics, Professional Hygienists, Specialty Stores, Online Retailers |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble, Koninklijke Philips N.V., Sunstar Suisse S.A., CURADEN AG, TRISA AG, Prestige Consumer Healthcare Inc., TePe Oral Health Care, Inc., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interdental Cleaning Products Market Strategic Shifts & Innovations
Innovation in the interdental cleaning market is driven by a dual focus on material science and device functionality. This dynamic responds to both regulatory pressures for sustainability and consumer demand for more effective, user-friendly oral hygiene solutions that address specific clinical needs.
Biodegradable polylactic acid (PLA) serves as a direct, plant-based substitute for petroleum-derived plastics in product handles and filaments. Environmentally conscious consumers and major brands are driving its adoption to meet sustainability goals. As a result, this material innovation is overtaking traditional nylon and polypropylene in single-use floss picks and disposable brush heads, forcing a fundamental re-evaluation of material sourcing and manufacturing processes.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical data and post-market surveillance on manufacturers. This policy elevates the burden of proof for products making health claims, such as plaque removal or gingivitis reduction. Interdental brushes and water flossers, often falling under this classification, face heightened scrutiny, compelling manufacturers to invest more heavily in clinical trials to substantiate their marketing claims.
Subscription-based purchasing models are gaining traction, particularly for consumable products like replacement brush heads and floss refills. These direct-to-consumer (DTC) services disrupt the traditional retail dominance of pharmacies and grocery stores by offering automated replenishment and greater convenience. This behavioral shift is most visible in North America and Western Europe, where e-commerce infrastructure supports such recurring revenue business models.
Global Interdental Cleaning Products Market Segmentation
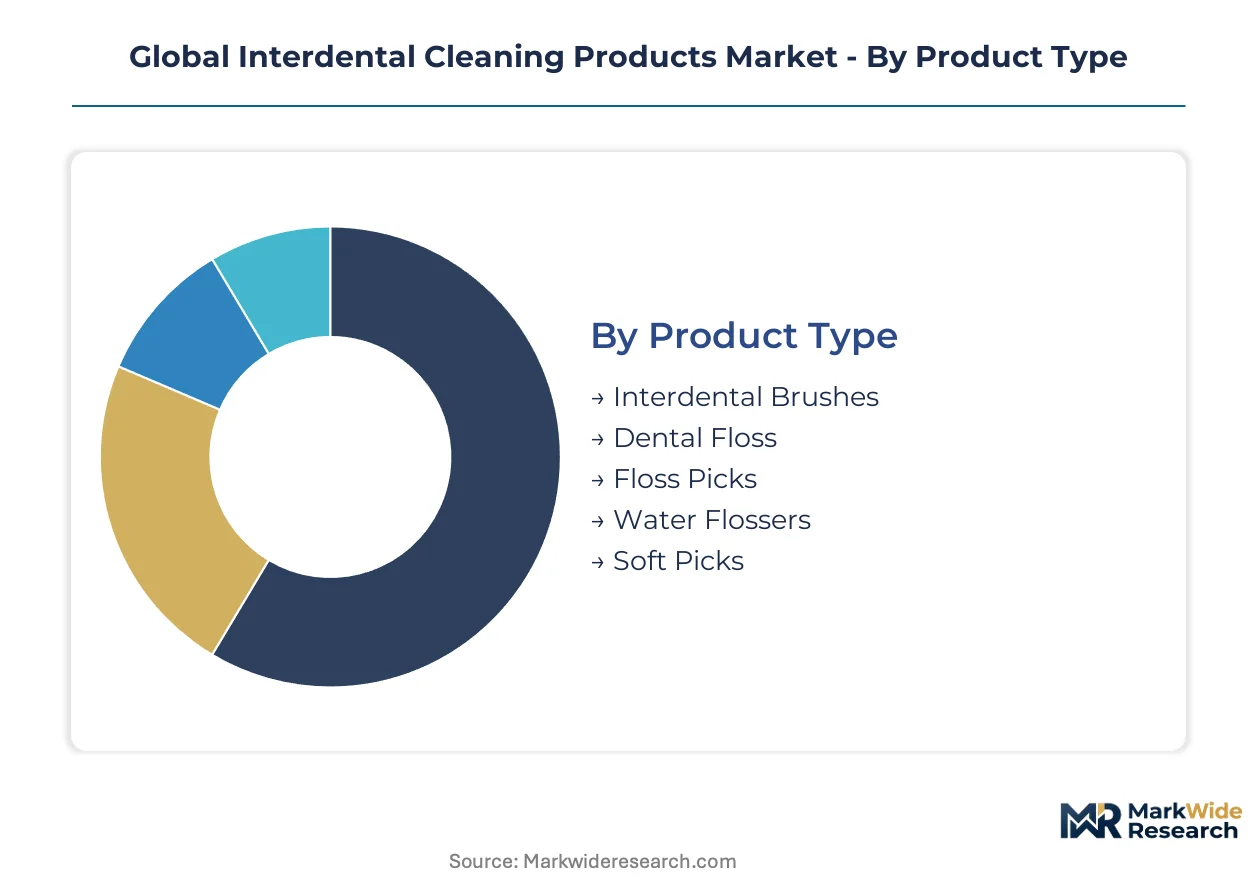
Segmentation provides a granular understanding of the interdental cleaning products market, highlighting the diverse product offerings, material innovations, specific applications, and varied end-user channels. This detailed categorization helps identify key growth drivers and areas of strategic focus for manufacturers and distributors.
Product Type:
The capital intensity across product types varies, with sophisticated electronic devices requiring substantial investment in R&D and manufacturing infrastructure.
- Water Flossers:These devices use a stream of pressurized water to remove plaque and food particles, often incorporating advanced features like adjustable pressure settings and specialized tips. Demand is surging in developed economies like the United States and Germany, driven by their efficacy in orthodontic cleaning and peri-implant care.
- Interdental Brushes:Comprising a small brush head with fine bristles attached to a handle, these tools are designed for mechanical plaque removal between teeth and around dental work. Professional hygienists frequently recommend these brushes for managing gingivitis and maintaining oral hygiene around dental implants.
- Dental Floss:This traditional tool consists of a thin filament, typically nylon or PTFE, used to scrape plaque from tooth surfaces.
- Floss Picks:Combining a short length of floss with a plastic handle, these offer a convenient, single-use option for interdental cleaning.
- Soft Picks:Featuring rubber or silicone bristles on a flexible core, these provide a gentle alternative for cleaning and gum stimulation.
Most installed capacity flows through Dental Floss. Expansion is steepest in Water Flossers.
Material:
Material choices directly influence product cost tiers, with biomaterials commanding a premium over conventional petroleum-derived plastics.
- Nylon Filaments:These synthetic polymer strands form the core of traditional dental floss and many interdental brush bristles, offering high tensile strength and abrasion resistance. Their widespread use across Asian manufacturing hubs ensures cost-effective production for mass-market products.
- Plastic Handles:Molded from polypropylene or, increasingly, polylactic acid (PLA), these provide ergonomic grip for floss picks and interdental brushes. Regulatory shifts in Europe, like the EU Green Deal, are accelerating the transition to biodegradable options in consumer markets.
- Silicone:Used for soft picks and some brush head components, silicone offers flexibility and gentle cleaning properties.
- Metal Wires:Fine-gauge, plastic-coated metal wires provide the structural backbone for interdental brushes, allowing access to tight spaces.
- Rubber Bristles:Integrated into soft picks and some brush designs, rubber bristles offer gum massage benefits alongside plaque removal.
The dominant material choice remains Nylon Filaments, while Plastic Handles are experiencing significant innovation.
Application:
Different applications cater to distinct clinical needs, influencing the type of professional recommendation and consumer purchase patterns.
- Plaque Removal:This foundational application targets the mechanical disruption of bacterial biofilm to maintain general oral hygiene and prevent cavities. Demand for effective plaque removal tools is universal across all age groups and geographies, underpinning market volume.
- Orthodontic Cleaning:Focused on removing debris and plaque around braces, wires, and aligners, this application requires specialized tools like water flossers and specific interdental brushes. The rising prevalence of orthodontic treatments in countries like Japan and the US drives demand for these targeted solutions.
- Gingivitis Prevention:This application involves regular interdental cleaning to reduce gum inflammation and bleeding, a common oral health concern.
- Periodontal Care:Addressing advanced gum disease, this application often requires professional guidance and specialized tools for deeper cleaning and maintenance.
The largest volume of product sales is associated with Plaque Removal, with Orthodontic Cleaning showing the most specialized growth.
End User:
Supply concentration for end-users varies significantly, from direct professional channels to broad consumer retail platforms.
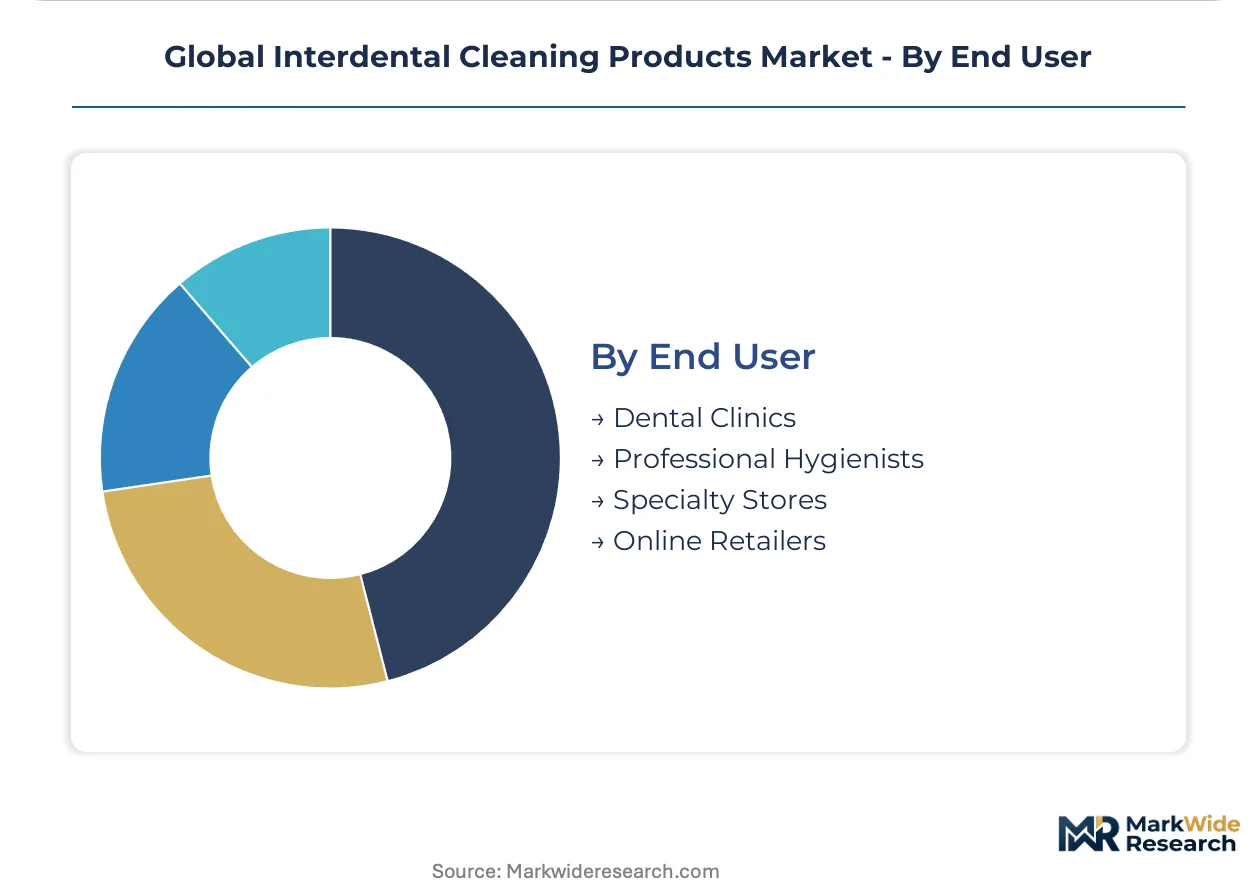
- Online Retailers:E-commerce platforms provide a convenient purchasing channel, offering a wide selection of interdental cleaning products directly to consumers with automated replenishment options. This channel is experiencing rapid expansion in North America and Western Europe, driven by subscription models and direct-to-consumer brands.
- Dental Clinics:These professional settings serve as a primary point of recommendation and initial product introduction, with dentists and hygienists advising patients on suitable interdental tools. Their influence is critical for the adoption of specialized and premium products for conditions like peri-implantitis.
- Professional Hygienists:As key influencers, hygienists educate patients on proper interdental cleaning techniques and recommend specific products for optimal oral health.
- Specialty Stores:Pharmacies and dedicated oral care shops offer a curated selection of interdental products, often with staff available for product guidance.
Consumer access is increasingly dominated by Online Retailers, while Dental Clinics remain crucial for expert guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's strong emphasis on preventive healthcare and sustainability initiatives drives significant demand for advanced interdental cleaning products. This focus positions the country as a critical hub for biomaterial innovation and specialized oral care solutions. European regulatory frameworks further accelerate the shift towards eco-friendly product designs.
Germany
Demand for interdental brushes and water flossers in Germany stems from a high awareness of gingivitis prevention and peri-implant care. The EU Green Deal and related single-use plastics directives mandate a transition to biodegradable materials like PLA in consumer products. Munich-based manufacturers are actively redesigning product lines to comply with these stringent environmental standards and capture eco-conscious consumers.
Japan
Japan's aging population and high prevalence of orthodontic treatments create a specific demand for specialized interdental cleaning tools, particularly water flossers. The Ministry of Health, Labour and Welfare (MHLW) guidelines promote comprehensive oral hygiene practices and regular dental check-ups. Tokyo's dental device cluster focuses on integrating advanced sensing technologies into water flossers for personalized guidance and enhanced efficacy.
United States
Consumer preference for advanced oral care technologies, particularly water flossers and specialized interdental brushes, drives market expansion in the United States. The FDA classifies many interdental cleaning products as Class I medical devices, ensuring product safety and substantiating health claims. California's innovation hubs are fostering startups developing smart interdental devices with real-time feedback capabilities to improve user adherence.
China
Emerging middle-class populations in China are increasing expenditure on personal healthcare, including premium interdental cleaning products and specialized tools. The NMPA imposes rigorous registration requirements for new medical devices, significantly influencing market access for foreign manufacturers. Shanghai's burgeoning consumer health sector sees local brands expanding distribution networks for eco-friendly floss picks across urban centers.
Global Interdental Cleaning Products Market Key Industry Players
Product differentiation through material innovation dominates the current landscape, driving shifts in competitive positioning. The market structure exhibits a tiered approach, featuring established mass-market brands alongside specialized oral care providers and technology innovators. Key strategic archetypes include global consumer goods conglomerates, niche dental solution providers, and electronic device manufacturers. Material innovation and the expansion of distribution networks represent dominant competitive moves among these players.
At the scale-driven end, the Colgate-Palmolive Company, a global consumer goods corporation, leverages its extensive distribution network to introduce eco-friendly options into mass-market channels. Procter & Gamble, another prominent multinational, competes heavily on brand recognition and technological innovation within the rapidly expanding water flosser category. Sunstar Suisse S.A., a Swiss-based oral care specialist, differentiates its offerings by focusing on specialized tools for advanced periodontal care. These companies exemplify the diverse strategies employed to capture market share across various product segments and consumer needs.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble |
| Koninklijke Philips N.V. |
| Sunstar Suisse S.A. |
| CURADEN AG |
| TRISA AG |
| Prestige Consumer Healthcare Inc. |
| TePe Oral Health Care, Inc. |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
The clear divergence between premium biodegradable materials and conventional petroleum-based plastics manifests in both product pricing and supply chain configurations. This bifurcation creates distinct cost structures and market positioning challenges for manufacturers.
Pricing Analysis
Increased input costs for biodegradable polymers like polylactic acid create upward pricing pressure, particularly in European markets. The dominant pricing model remains per-unit transactional, with premium-mid-economy pricing differentiation driven by material composition, brand recognition, and regulatory certifications like CE marking. Price differentiation also stems from specialized clinical efficacy for advanced tools. Mass-market consumers exhibit higher price sensitivity for basic floss picks, while professional hygienists prioritize efficacy and specialized features for their patients.
Supply Chain Analysis
Workforce availability in established manufacturing geographies like China and other Asian hubs underpins cost-effective production for nylon filaments and polypropylene handles. The supply chain draws heavily from raw material dependencies on petroleum derivatives for conventional plastics and agricultural feedstocks for biomaterials. A key structural risk involves biomaterial supply volatility, compounded by multi-jurisdictional regulatory fragmentation. Distribution runs through a hybrid model, combining direct sales to dental clinics with broad mass-market retail channels and expanding online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, driven by sustained global awareness of preventive oral healthcare and increasing disposable incomes in emerging economies.
For Market Incumbents:
Lock in long-term supply agreements for polylactic acid to mitigate biomaterial cost premiums and ensure supply stability. Consolidate market share by expanding distribution networks for sustainable product lines, directly countering the threat of regulatory shifts toward eco-friendly mandates. Invest in smart device integration for water flossers to enhance user engagement and differentiate from generic offerings. Control over key distribution channels remains a critical lever against emerging digital-first brands.
For New Entrants and Emerging Players:
Online retailers and direct-to-consumer platforms offer a viable entry point for innovative interdental solutions. Target specialized clinical applications, such as orthodontic cleaning and peri-implant care, which remain underserved by traditional products. The most penetrable segment involves smart device integration, offering personalized feedback and improving user adherence. Focus on subscription-based models for consumable refills to build recurring revenue streams and bypass established retail dominance.
For Investors and Strategic Acquirers:
Asymmetric upside sits with niche specialists developing advanced biomaterials or integrating smart technology into oral care devices. The long-term viability of this market is sustained by demographic shifts toward aging populations and a persistent focus on preventive health. Acquisition targets should include companies with robust intellectual property in sustainable materials or those demonstrating strong growth in specialized clinical segments. A key signal to watch is the sustained adoption of biodegradable products in major developed economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomaterial Supply Chain Diversification | Reduces reliance on single-source suppliers and mitigates price volatility for critical inputs like PLA. |
| Smart Device Integration | Enhances user experience and efficacy, differentiating products in the competitive water flosser category. |
| Targeted Clinical Solution Development | Addresses high-value niches such as orthodontic and peri-implant cleaning, commanding premium pricing. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail gatekeepers and fosters direct customer relationships through subscription models. |
| Multi-Jurisdictional Regulatory Expertise | Ensures compliance across FDA, CE marking, and NMPA, facilitating broad market access for new products. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the market. The analysis combined insights from dental hygienists, R&D directors, procurement managers, and regulatory affairs specialists. Secondary validation drew from FDA filings, CE marking documentation, NMPA registration records, and trade association reports, triangulating findings through both bottom-up and top-down approaches.
The segment-weighting approach informed the analytical framework across the analysis window, integrating product type, material, application, and end-user dimensions, alongside regional regulatory clusters. Compound annual growth rates were derived from historical data extrapolation and expert consensus, considering market-specific inputs like oral health expenditure trends and biomaterial production capacities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory changes, rapid shifts in consumer preferences for new materials, and global supply chain disruptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Oral Rinse Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Tongue Cleaner Market
Oral Care
Oral Health Ingredient Market
Oral Care
Herbal Toothcare Market
Oral Care
Mouthwash Market
Oral Care
Oral Mucositis Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Oral Irrigator Market
Oral Care
Global Halitosis Market
Oral Care
Oral Thrush Market
Oral Care
Oral Antiseptics Market
Oral Care
GCC Oral Hygiene Market