
 Oral Thrush Treatment Market | 2026-2036
Oral Thrush Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Thrush Treatment Market Analytics
Subscription-based patient monitoring and adherence programs is restructuring how antifungal therapy gets delivered beyond the initial prescription. Pfizer leverages its manufacturing scale to sustain broad distribution of azole-class tablets across institutional channels. Glenmark Pharmaceuticals specializes in complex generic formulations that compete on bioequivalence metrics in regulated markets.
Oral thrush treatment encompasses pharmaceutical and non-pharmaceutical interventions targeting Candida albicans and non-albicans species colonizing the oropharyngeal mucosa, with azole antifungals—particularly fluconazole and clotrimazole—inhibiting ergosterol synthesis at fungal cell membranes to restore mucosal integrity in immunocompromised, diabetic, and antibiotic-exposed patient populations. Antifungal tablets dominate prescription volumes due to systemic efficacy in moderate-to-severe infections, while oral rinses capture preference in pediatric and geriatric populations where swallowing function is compromised. Homecare settings represent the fastest-growing end-user channel as post-acute protocols shift administration away from hospitals.
FDA bioequivalence standards and EMA quality guidelines govern generic entry and formulation stability requirements for azole therapies, directly shaping product development timelines and market access pathways. The WHO Essential Medicines List inclusion of fluconazole influences procurement priorities in low-resource health systems and donor-funded programs. Stakeholders must monitor evolving antifungal stewardship guidelines that restrict empiric azole use and redirect investment toward resistance-aware diagnostic-treatment algorithms.
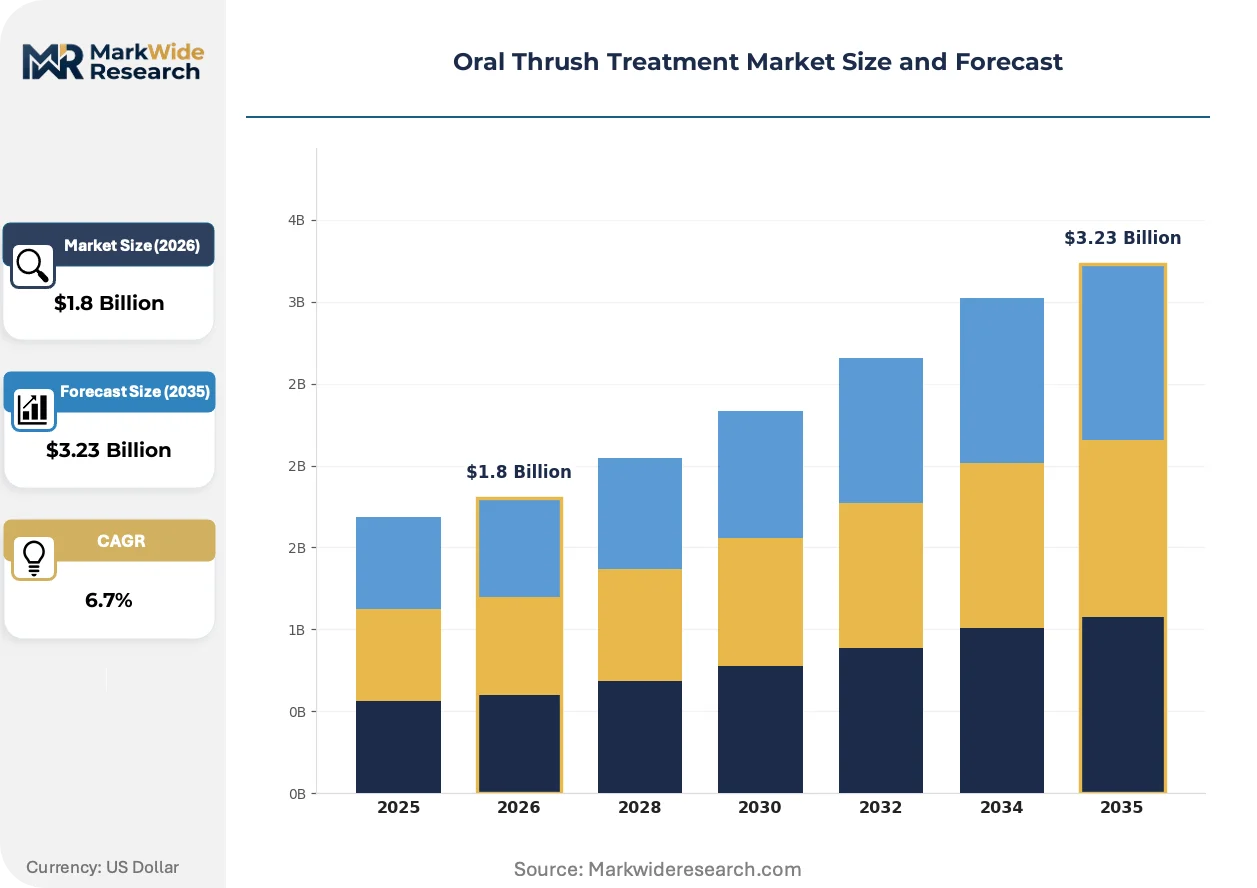
Market Dynamics
FDA and EMA bioequivalence standards for generic azole formulations are compressing development timelines while expanding competitive entry, fundamentally restructuring how antifungal therapies reach immunocompromised patient populations across institutional and homecare channels.
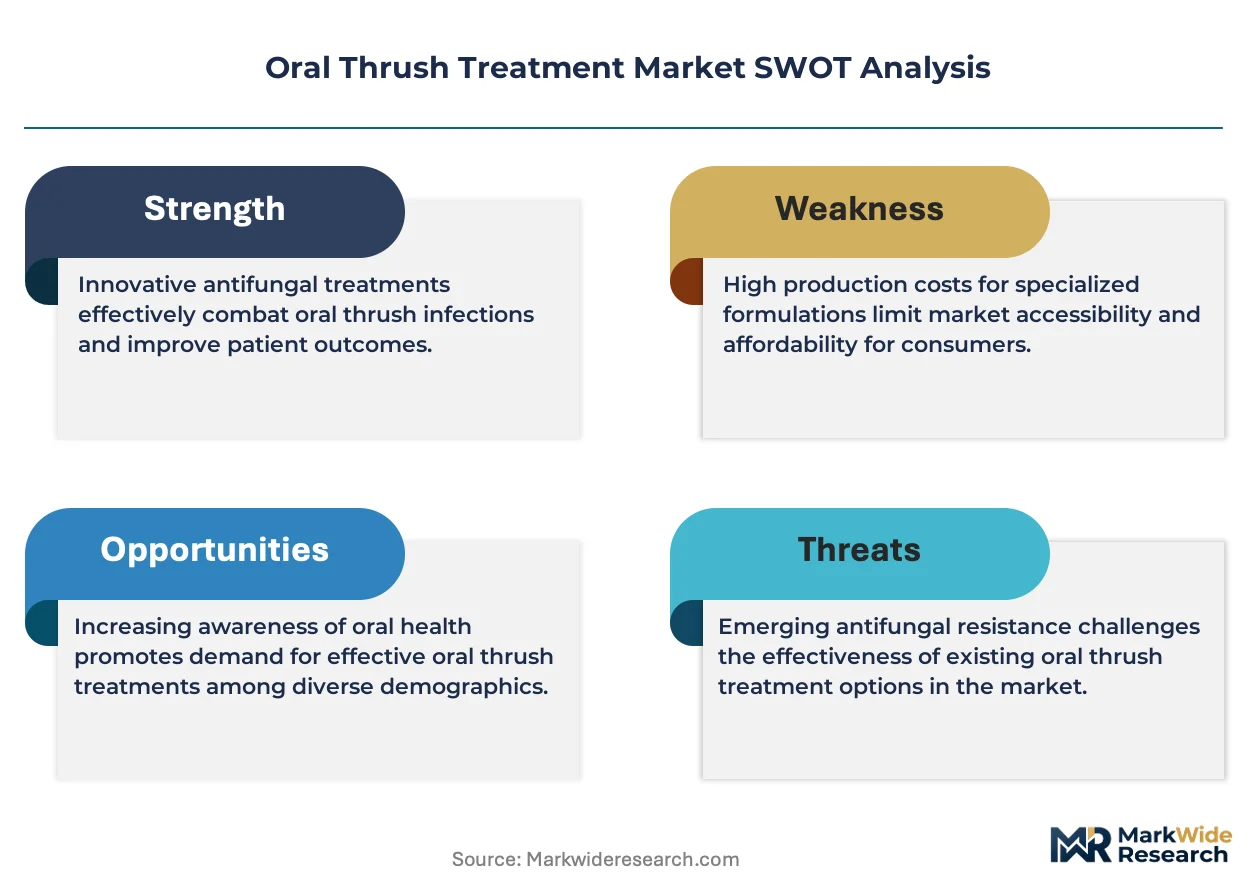
Growth Catalysts
- Hospital-acquired infection protocols:Rising Candida colonization rates among immunocompromised inpatients in the United States and Germany are expanding antifungal prescription volumes through standardized diagnostic-treatment algorithms.
- WHO Essential Medicines List inclusion:Fluconazole designation influences procurement priorities in low-resource health systems and donor-funded programs, channeling development resources toward affordable generic production.
- Post-acute care migration:Homecare settings are absorbing administration of moderate oral thrush cases previously managed in hospitals, creating new demand for patient-friendly formulations and remote monitoring infrastructure.
Market Restraints
- Azole resistance surveillance costs:Candida glabrata and Candida auris resistance patterns are forcing laboratories to implement species-specific susceptibility testing, elevating diagnostic overhead before therapy initiation.
- Active pharmaceutical ingredient concentration:Bulk fluconazole and clotrimazole production clusters in India and China, exposing formulation supply to geopolitical friction and export licensing variability.
- Echinocandin substitution threat:Intravenous caspofungin and micafungin are displacing oral azoles in bloodstream-invasive candidiasis protocols, narrowing the addressable population for oropharyngeal-specific therapies.
Strategic Opportunities
- Pediatric formulation gaps:Orally disintegrating tablets and flavored suspensions for swallowing-impaired pediatric and geriatric populations remain underdeveloped relative to adult tablet strengths.
- Subscription adherence platforms:Digital patient monitoring programs that track treatment completion and recurrence signals are creating recurring revenue attachment beyond initial prescription fulfillment.
- Antifungal stewardship alignment:Resistance-aware diagnostic-treatment algorithms mandated by hospital pharmacy committees are rewarding developers with rapid species identification companion tools.
Industry Challenges
- Pharmacokinetic modeling expertise:Demonstrating bioequivalence for complex generic azole formulations requires specialized biopharmaceutical modeling talent that concentrates in regulated-market CROs.
- Multi-jurisdiction dossier preparation:Simultaneous FDA 505(b)(2) and EMA hybrid application pathways demand divergent stability data packages, stretching regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Thrush Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifungal Tablets, Oral Rinses, Creams, Lozenges Delivery Mode: Topical, Oral, Intravenous, Sub-lingual End User: Hospitals, Clinics, Pharmacies, Homecare Settings Treatment Duration: Short-term, Long-term, Maintenance Therapy, Acute Care |
| Companies Covered | Pfizer, Bayer, Teva Pharmaceuticals, Stellar Pharma, Wockhardt, Glenmark Pharmaceuticals, Ranbaxy Laboratories, Bristol Laboratories, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Thrush Treatment Market Evolving Landscape
Digital adherence platforms and rapid point-of-care diagnostics are compressing the gap between symptom onset and appropriate therapy selection, while regulatory convergence around bioequivalence standards is accelerating generic substitution patterns.
Artificial intelligence-enabled patient risk stratification is automating identification of immunocompromised individuals most susceptible to recurrent oral thrush, enabling preemptive antifungal prophylaxis rather than reactive treatment. Oncology and transplant centers in the United States are piloting these algorithms during pre-chemotherapy workups. The technology is automating pharmacy resource allocation by flagging high-risk patients for adherence intervention before breakthrough infections occur.
EMA quality guidelines for azole-containing medicinal products are tightening impurity profiling requirements, forcing reformulation of legacy clotrimazole oral suspensions to meet updated nitrosamine and degradation product thresholds. Generic manufacturers serving European markets are responding with accelerated stability studies and revised excipient sourcing. The regulatory pressure is compressing shelf-life claims and elevating cold-chain requirements for liquid formulations.
Direct-to-patient pharmacy fulfillment is displacing traditional wholesale-to-hospital distribution for maintenance antifungal regimens, particularly in Medicare Advantage populations with integrated pharmacy benefits. Home infusion providers and specialty pharmacies are capturing prescription volume previously routed through inpatient discharge protocols. Germany's structured reimbursement pathways for post-acute medications are accelerating this channel migration among chronically immunosuppressed patient cohorts.
Oral Thrush Treatment Market Segmentation
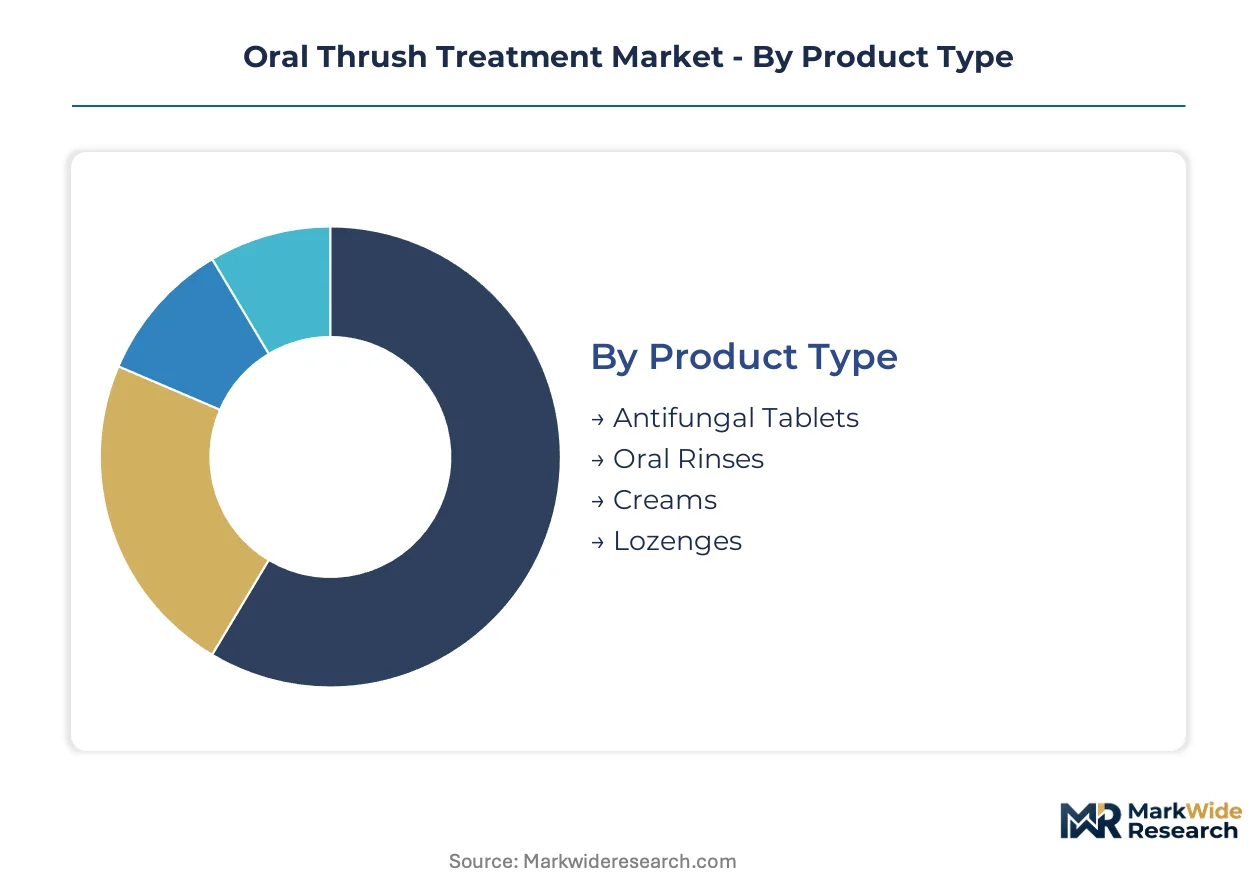
Oral thrush treatment segments diverge sharply by patient functional status and care setting. Prescribers weigh systemic efficacy against swallowing safety, while reimbursement pathways determine whether therapy initiates in hospitals or shifts to home administration.
Product Type:
Clinicians select formulations based on infection severity and mucosal penetration requirements, with bioavailability and palatability driving pediatric versus adult prescribing patterns.
- Antifungal Tablets:Systemic azole formulations deliver consistent plasma concentrations for moderate-to-severe oropharyngeal candidiasis. Demand concentrates in United States hospital discharge protocols where fluconazole remains first-line for immunocompromised oncology patients, though azole resistance surveillance is elevating pre-therapy diagnostic requirements.
- Oral Rinses:Topical suspensions containing nystatin or clotrimazole provide localized fungal membrane disruption without systemic absorption. Preference is climbing fastest in German geriatric homecare settings where aspiration risk limits solid dosage forms, creating formulation stability challenges under tightened EMA impurity guidelines.
- Creams:Topical azole preparations for perioral candidiasis extension.
- Lozenges:Mucoadhesive delivery systems for prolonged buccal contact in ambulatory patients.
Volume sits with Antifungal Tablets; growth tilts toward Oral Rinses.
Delivery Mode:
Route selection follows infection depth and patient hemodynamic stability, with institutional protocols increasingly restricting intravenous escalation to bloodstream-confirmed cases.
- Topical:Direct mucosal application limits systemic exposure in polypharmacy patients. United States Medicare Advantage plans favor this route for maintenance regimens, channeling fulfillment through specialty pharmacies rather than hospital discharge.
- Oral:Swallowed tablets and suspensions dominate prescription volumes across all care settings.
- Intravenous:Reserved for azole-refractory or hemodynamically unstable patients.
- Sub-lingual:Rapid absorption bypasses gastrointestinal compromise in advanced immunosuppression.
Oral administration captures the largest prescription base; sub-lingual formats are expanding most quickly in transplant center protocols.
End User:
Care setting determines reimbursement mechanics and adherence support intensity, with post-acute migration reshaping distribution infrastructure requirements.
- Hospitals:Inpatient initiation protocols for severe oropharyngeal candidiasis in neutropenic patients. German structured reimbursement pathways and United States antimicrobial stewardship mandates are compressing length-of-stay and accelerating discharge to lower-acuity settings.
- Homecare Settings:Post-acute administration of maintenance azole regimens with remote monitoring support. Germany's integrated pharmacy benefit structures and United States Medicare Advantage penetration are absorbing volume previously routed through outpatient clinics.
- Clinics:Initial diagnosis and therapy initiation for ambulatory immunocompromised patients.
- Pharmacies:Retail fulfillment of standard oral antifungal prescriptions with adherence counseling.
Hospitals retain the highest prescription value per patient; homecare settings are gaining share fastest as post-acute protocols mature.
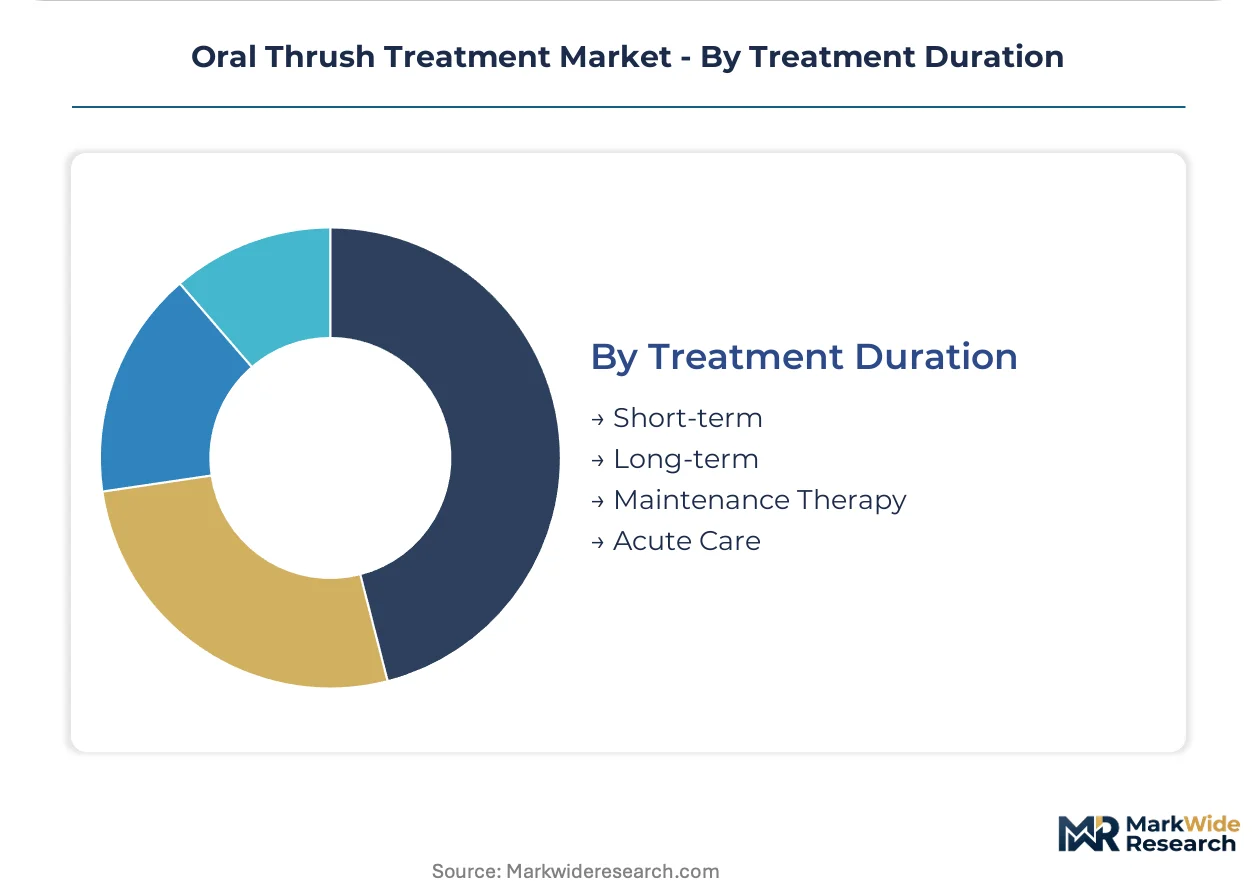
Treatment Duration:
Duration stratification separates acute infectious disease management from chronic immunosuppression maintenance, with subscription adherence platforms targeting the latter.
- Short-term:7-14 day azole courses for antibiotic-associated oropharyngeal candidiasis in otherwise healthy patients.
- Long-term:Extended suppressive therapy for recurrent disease in HIV and transplant populations.
- Maintenance Therapy:Intermittent prophylaxis for high-risk immunosuppressed cohorts. United States oncology centers pilot AI-enabled risk stratification to automate enrollment, while German sickness funds negotiate outcomes-based contracts for adherence-tracked regimens.
- Acute Care:Intensive initial dosing for breakthrough infections in failing prophylaxis.
Short-term courses generate the highest prescription frequency; maintenance therapy shows the steepest expansion trajectory as preemptive prophylaxis protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production clusters in India and China while consumption concentrates in the United States and Germany due to established diagnostic protocols and reimbursement clarity. This geographic divide exposes formulation supply to export licensing variability and geopolitical friction.
United States
FDA bioequivalence standards for generic azole formulations compress development timelines while expanding competitive entry through institutional channels. Hospital-acquired infection protocols and antimicrobial stewardship mandates drive prescription volumes for immunocompromised oncology patients. New York and Boston medical centers pilot AI-enabled risk stratification for preemptive antifungal prophylaxis.
Germany
EMA quality guidelines tighten impurity profiling requirements for clotrimazole oral suspensions, forcing reformulation of legacy products. Structured reimbursement pathways for post-acute medications accelerate channel migration toward homecare settings. Frankfurt and Munich pharmaceutical clusters specialize in complex generic formulations competing on bioequivalence metrics.
India
Bulk fluconazole and clotrimazole production concentrates in Mumbai and Hyderabad, supplying global formulation networks. CDSCO alignment with WHO Essential Medicines List priorities channels development resources toward affordable generic production. Indian manufacturers face export licensing variability that disrupts supply continuity to regulated markets.
China
NMPA oversight of azole-containing medicinal products governs domestic manufacturing standards while dual carbon goals reshape energy-intensive chemical synthesis. Shanghai and Jiangsu province house active pharmaceutical ingredient facilities serving multinational formulation partners. Geopolitical friction elevates supply risk for Western markets dependent on Chinese bulk production.
United Kingdom
UK antimicrobial resistance surveillance programs elevate species-specific susceptibility testing requirements before therapy initiation. NHS procurement frameworks influenced by WHO Essential Medicines List inclusion prioritize fluconazole availability in low-resource settings. London and Cambridge diagnostic clusters develop rapid point-of-care tools for resistance-aware treatment algorithms.
Oral Thrush Treatment Market Competitive Landscape
Top-tier vendors anchor hospital and institutional channels, while mid-scale generic specialists compete on bioequivalence metrics and formulation complexity. The market exhibits tiered concentration with multinational pharmaceutical corporations controlling prescription volumes through manufacturing scale and distribution breadth. Strategic archetypes include scale-driven institutional suppliers, complex generic formulators, and digital adherence platform operators. Competitive moves center on portfolio diversification into pediatric formulations and geographic expansion through multi-jurisdiction regulatory dossiers.
Among multinational pharmaceutical corporations, Pfizer and Bayer occupy positions exemplifying scale-driven institutional supply, while Glenmark Pharmaceuticals represents the complex generic formulator archetype competing on bioequivalence standards. Teva Pharmaceuticals sits within the mid-tier generic segment serving regulated markets through established distribution networks. These company structures illustrate how competitive positioning diverges between manufacturing scale advantages and specialized formulation expertise.
| Leading Market Players |
|---|
| Pfizer |
| Bayer |
| Teva Pharmaceuticals |
| Stellar Pharma |
| Wockhardt |
| Glenmark Pharmaceuticals |
| Ranbaxy Laboratories |
| Bristol Laboratories |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
EMA quality guidelines for azole-containing medicinal products gate qualified supply and premium-tier pricing access by mandating nitrosamine impurity profiling that legacy clotrimazole oral suspensions cannot meet without reformulation. German sickness funds and United States Medicare Advantage plans reserve favorable reimbursement for manufacturers demonstrating compliance, compressing margins for non-compliant suppliers while rewarding cold-chain-capable formulation specialists.
Pricing Analysis
Margin tightening in generic oral rinses reflects CDSCO-aligned manufacturers flooding economy-tier segments with WHO Essential Medicines List-prioritized fluconazole production. Three-tier pricing structure across premium cold-chain formulations, standard bioequivalence-certified tablets, and economy bulk generics separates Pfizer-scale institutional suppliers from Glenmark-style complex formulators. Price differentiation hinges on EMA impurity certification and pediatric palatability engineering. Oncology and transplant centers show lowest price sensitivity; geriatric homecare settings exhibit highest.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Mumbai operate hub-and-spoke patterns feeding formulation facilities in Germany and the United States. Bulk fluconazole and clotrimazole production clusters in India and China, drawing from petrochemical precursors and specialized fermentation substrates. Single-source vulnerability concentrates in Shanghai and Jiangsu province active pharmaceutical ingredient corridors exposed to export licensing variability. Distribution runs through hospital procurement consortia and direct-to-patient specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enabled patient risk stratification is displacing reactive prescribing protocols with preemptive antifungal prophylaxis algorithms, forcing stakeholders to recalibrate around digital adherence infrastructure.
For Market Incumbents: Deploy backward integration into cold-chain excipient sourcing to defend against EMA reformulation mandates. Pfizer-scale manufacturers should consolidate pediatric formulation capabilities before Glenmark-style competitors capture orphan-drug exclusivity windows. Channel control through integrated pharmacy benefit structures insulates against direct-to-patient disintermediation.
For New Entrants and Emerging Players: Direct-to-patient pharmacy fulfillment routes offer lowest competitive density for Medicare Advantage penetration. Orally disintegrating tablet formats for swallowing-impaired geriatric populations present the most penetrable white space. Partner with home infusion providers to bypass hospital discharge protocol gatekeepers.
For Investors and Strategic Acquirers: FDA 505(b)(2) approval acceleration for complex generic azole formulations is the leading indicator that bioequivalence modeling expertise commands scarcity premiums. Acquisition targets should combine biopharmaceutical CRO relationships with multi-jurisdiction dossier preparation capacity. Watch for EMA hybrid application backlog clearance as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | EMA orphan-drug pathways reward flavored suspensions and disintegrating tablets with exclusivity buffers. |
| Digital Adherence Platform Integration | Subscription monitoring programs attach recurring revenue to maintenance therapy prescriptions. |
| Multi-Jurisdiction Regulatory Dossier Filing | Simultaneous FDA and EMA submissions compress time-to-market for complex generic entrants. |
| Antifungal Stewardship Alignment | Rapid point-of-care diagnostic companions secure hospital pharmacy committee formulary preference. |
| Cold-Chain Distribution Infrastructure | EMA nitrosamine compliance requires reformulated liquid formulations with temperature-controlled logistics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists validated prescribing pattern assumptions. FDA 505(b)(2) submissions, EMA quality guidelines, WHO Essential Medicines List procurement databases, and CMS Medicare Part D claims furnished secondary triangulation. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure reconciliation ensured cross-verification.
Data-stream reconciliation across patient population epidemiology, treatment duration distributions, and channel migration patterns shaped the analytical framework. Segmentation dimensions encompassed product type, delivery mode, end-user setting, and treatment duration across the projection horizon. CAGRs derived from longitudinal prescription audit data and antimicrobial stewardship policy trajectories. Forecast inputs incorporated azole resistance surveillance trends and post-acute care protocol adoption curves.
The model holds under stable FDA bioequivalence standards and EMA impurity guideline continuity; deviation in antifungal stewardship mandate severity or API export licensing restrictions would shift trajectory. Antifungal resistance acceleration and geopolitical supply disruption constitute primary revision triggers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Halitosis Treatment Market
Oral Care
Mouth Spray Market
Oral Care
Oral Health Ingredient Market
Oral Care
Europe Oral Care Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Oral Irrigator Market
Oral Care
Oral Hygiene Products Market
Oral Care
Kids Oral Care Products Market
Oral Care
Oral Care Market
Oral Care
Japan Oral Hygiene Market
Oral Care
LED Oral Care Kits Market
Oral Care
China Oral Care Market
Oral Care
Baby Oral Care Market
Oral Care
Us Oral Care Market
Oral Care
Adult Oral Care Products Market
Oral Care
Children's Oral Care Market