
 Adult Oral Care Products Market | 2026-2036
Adult Oral Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Oral Care Products Market Outlook
Dental hygienist workforce shortages across developed markets is redrawing how oral care products reach consumers. Procter & Gamble Company leverages its pharmacy channel relationships to sustain professional endorsement pipelines. Colgate-Palmolive Company anchors its position through in-house fluoride sourcing and manufacturing scale. Koninklijke Philips N.V. differentiates via connected toothbrush ecosystems that blur retail and clinical boundaries.
Adult oral care products encompass dentifrices, rinses, interdental cleaners, and peroxide-based bleaching systems formulated with active ingredients such as stannous fluoride, cetylpyridinium chloride, and hydrogen peroxide at concentrations ranging from 0.07% to 14%, manufactured through emulsion processing, cold-fill blending, or strip-lamination techniques, serving preventive maintenance, aesthetic enhancement, and therapeutic gum management purposes. Toothpaste dominates value pools due to daily-use frequency and premium positioning around enamel repair and whitening claims, while whitening strips represent the fastest-growing product type as consumers shift toward at-home cosmetic procedures. E-commerce shoppers now command disproportionate attention from brand portfolios because subscription models and direct-to-consumer margins outperform traditional supermarket rotations.
FDA oversees over-the-counter oral care monographs and active ingredient safety thresholds in the United States, while REACH and the EU Cosmetics Regulation govern chemical substance registration and labeling across European markets, collectively pushing reformulation cycles and documentation costs upward. India's BIS and CDSCO are implementing tighter standards for imported oral care actives, affecting market access timelines for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation investments and channel compliance costs.
Market Dynamics
Dental hygienist workforce shortages across developed markets are redrawing how oral care products reach consumers, forcing manufacturers to recalibrate channel strategies and professional endorsement pipelines.
Growth Catalysts
- EU MDR framework:Tightening ingredient disclosure requirements are accelerating reformulation investments by manufacturers seeking premium positioning through clinical credibility.
- At-home cosmetic procedures:Consumer shift toward peroxide-based bleaching systems is expanding addressable market for whitening strips and tray systems.
- Germany:Concentrated demand from dental clinics for professional-grade formulations is pulling supply toward higher-margin institutional channels.
Market Restraints
- Fluoride supply concentration:Dependence on captive in-house sourcing or limited chemical suppliers creates input cost volatility and margin pressure.
- REACH compliance documentation:Chemical substance registration requirements across European markets inflate reformulation cycle timelines and regulatory overhead.
- Interdental cleaners:Water flosser substitution threatens traditional floss segment with superior efficacy claims and device integration.
Strategic Opportunities
- Subscription commerce:Direct-to-consumer recurring revenue models bypass supermarket slotting fees and capture lifetime value through automated replenishment.
- Connected toothbrush ecosystems:Convergence of sensor hardware and mobile applications creates data-rich relationships that blur retail-clinical boundaries.
- Japan:Aging demographic with high dental consciousness presents underpenetrated demand for therapeutic gum management formulations.
Industry Challenges
- Emulsion processing expertise:Specialized formulation chemistry talent scarcity constrains capacity expansion for stannous fluoride and cetylpyridinium chloride products.
- India BIS/CDSCO alignment:Tighter standards for imported oral care actives extend market access timelines and require dedicated regulatory affairs infrastructure.
- Cold-fill blending certification:Equipment validation protocols for hydrogen peroxide stability create capex intensity for manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Oral Care Products Market |
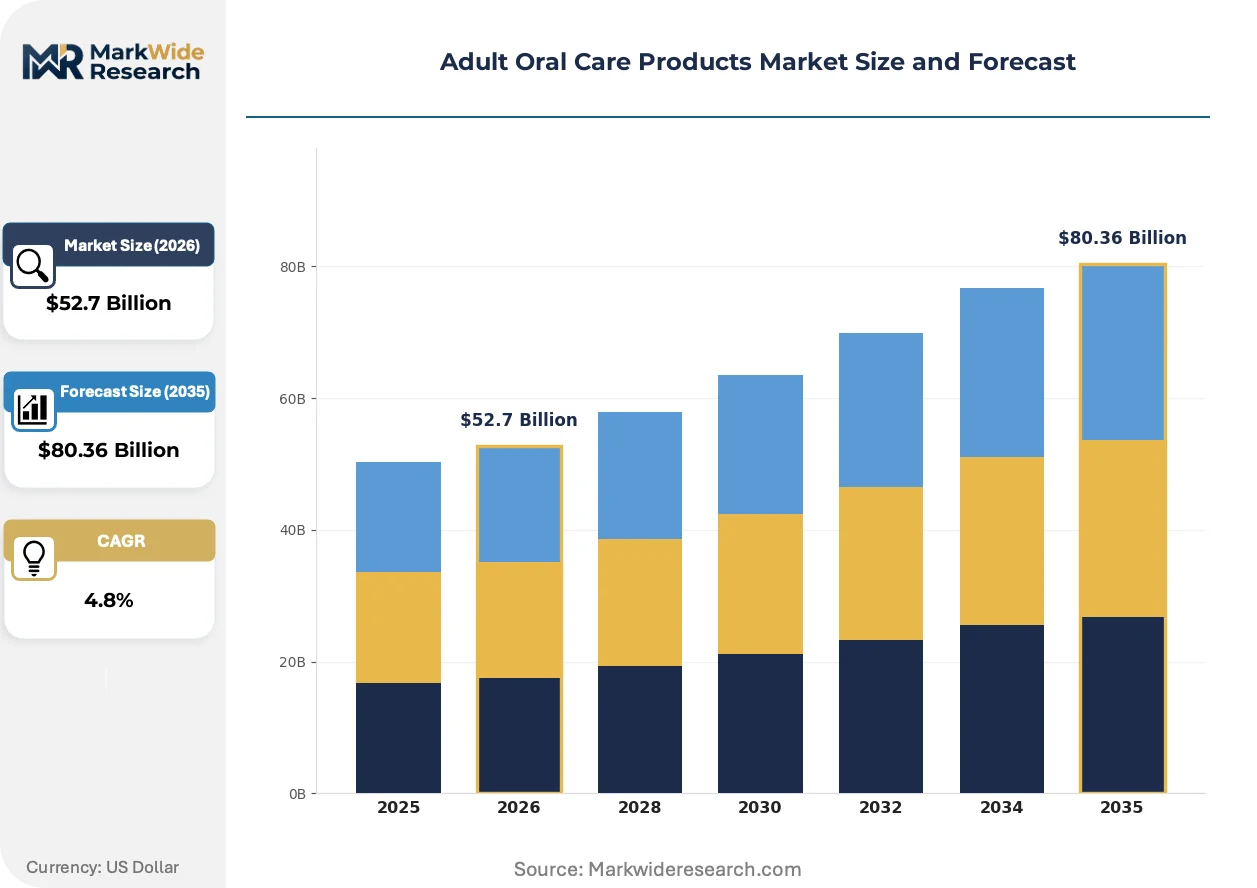
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Strips Application: Daily Maintenance, Cosmetic Improvement, Gum Health, Sensitivity Relief Customer Type: Retail Consumers, Healthcare Professionals, Dental Clinics, E-commerce Shoppers Distribution Channel: Supermarkets, Pharmacies, Online Stores, Personal Care Shops |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble Company, Unilever PLC, Church & Dwight Co., Inc., Johnson & Johnson Services, Inc., Haleon plc, GlaxoSmithKline plc, Koninklijke Philips N.V., Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Oral Care Products Market Strategic Shifts
Active ingredient transparency and connected device integration are converging to redefine competitive differentiation, while regulatory fragmentation forces parallel compliance investments across manufacturing footprints.
Smart oral care hardware is fragmenting traditional category boundaries by embedding diagnostic capabilities into daily-use devices. Dental clinics are piloting prescription-connected brush systems that transmit compliance data to hygienists. This convergence is compressing margins for standalone mechanical brushes while creating service revenue pools around data interpretation.
REACH and the EU Cosmetics Regulation are mandating granular chemical substance labeling that exceeds FDA monograph requirements. Manufacturers serving both jurisdictions face asymmetric documentation burdens. European-market formulations are leading reformulation cycles, with US portfolios trailing by 12-18 months on ingredient disclosure standards.
Subscription-based replenishment is displacing supermarket impulse purchases for core dentifrice categories. E-commerce platforms capture disproportionate attention from brand portfolios because automated reorder algorithms reduce price sensitivity. This channel shift is most visible in United States and German metropolitan markets where delivery infrastructure supports rapid fulfillment.
Adult Oral Care Products Market Segmentation
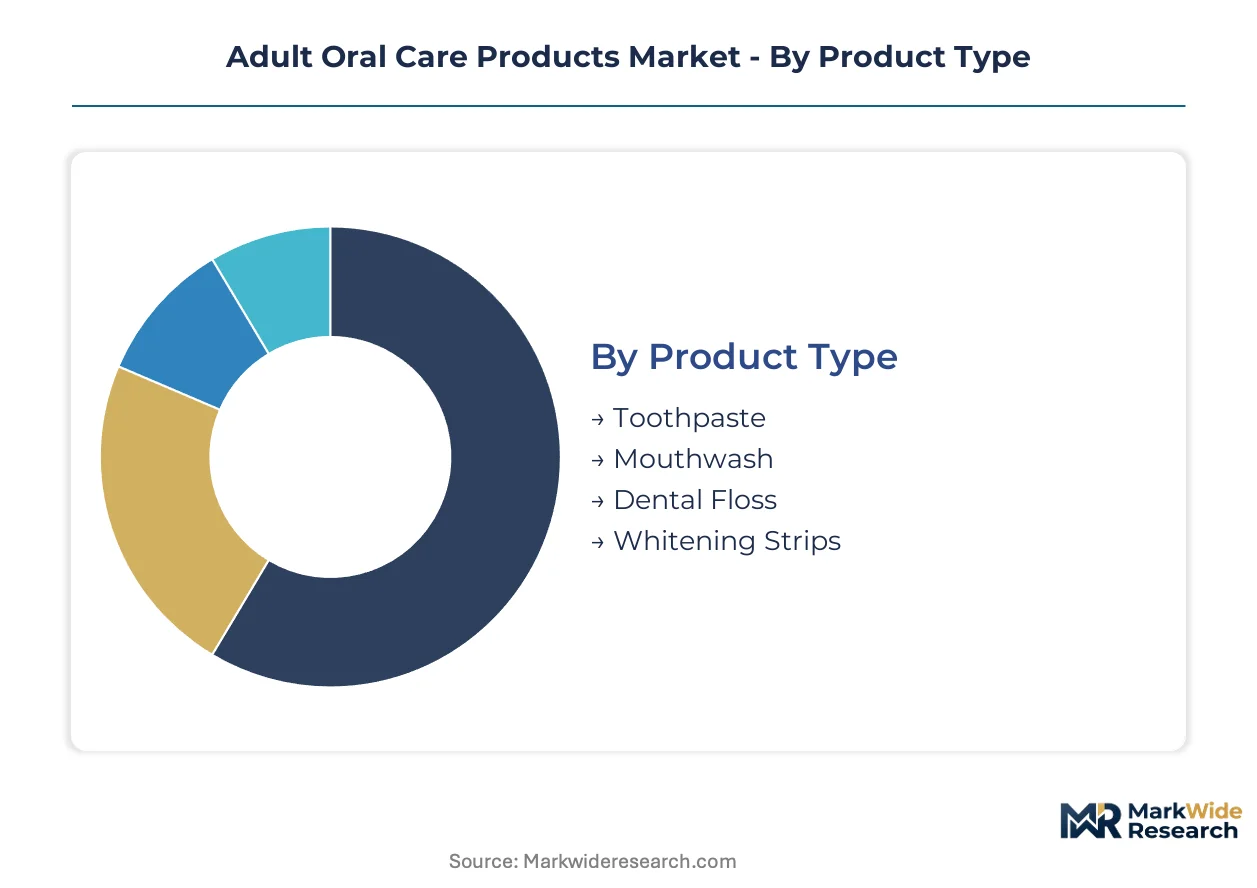
Segmentation in adult oral care products reveals how formulation chemistry, channel economics, and professional endorsement interact to create distinct value pools. Understanding these divides exposes where margin concentrates and where volume growth accelerates.
Product Type:
Domestic manufacturing dominates toothpaste and mouthwash production across Germany, the United States, and Japan, while whitening strips flow through export-led supply chains centered on specialized film-lamination facilities.
- Toothpaste:Formulations incorporate stannous fluoride at 0.454% concentration or sodium fluoride at 0.243% through emulsion processing, delivering enamel repair and anti-cavity claims. Demand concentrates in German dental clinics seeking professional-grade prophylaxis pastes with elevated abrasive indices. REACH documentation requirements for fluoride sourcing extend reformulation cycles.
- Whitening Strips:Hydrogen peroxide concentrations range from 6% to 14% in strip-laminated polymer matrices designed for 30-minute wear cycles. Japanese retail consumers and United States e-commerce shoppers drive disproportionate volume through at-home cosmetic positioning. Cold-fill blending certification creates manufacturing bottlenecks.
- Mouthwash:Cetylpyridinium chloride formulations at 0.07% provide antiseptic claims without prescription status.
- Dental Floss:Nylon and PTFE monofilament variants face substitution pressure from water flosser device integration.
Toothpaste commands the established base. The steepest expansion runs through whitening strips.
Application:
Cost tier stratification separates premium therapeutic formulations from mass-market daily-use products, with reimbursement eligibility in Germany and Japan pulling professional-grade applications toward higher price bands.
- Daily Maintenance:Standard fluoride dentifrices and alcohol-free rinses serve preventive protocols with twice-daily use frequency. United States supermarket channels and Japanese personal care shops concentrate volume for this functional baseline. Subscription commerce models capture recurring replenishment with reduced price sensitivity.
- Cosmetic Improvement:Peroxide-based systems and optical brightening agents address aesthetic demands through at-home bleaching regimens. E-commerce shoppers in metropolitan United States and German markets exhibit willingness-to-pay premiums for visible efficacy timelines. FDA monograph compliance for hydrogen peroxide thresholds constrains formulation latitude.
- Gum Health:Stannous fluoride and essential oil formulations target gingivitis reduction with therapeutic positioning.
- Sensitivity Relief:Potassium nitrate and arginine-based desensitizers block dentinal tubule transmission.
Daily maintenance commands the established base. Cosmetic improvement gains share fastest.
Customer Type:
Volume concentration tilts toward retail consumers, while margin accretion concentrates in healthcare professional and dental clinic procurement where formulary decisions bypass price comparison.
- Retail Consumers:Individual purchasers selecting products through supermarket aisles and online search algorithms, with brand loyalty eroding amid private-label expansion. German and United States metropolitan markets show highest subscription adoption for automated replenishment. E-commerce platforms reduce slotting fee burdens for challenger brands.
- Dental Clinics:Institutional procurement of professional-grade prophylaxis pastes and prescription-connected brush systems. Germany's clinic network concentrates demand for higher-abrasivity formulations with clinical credibility claims. Workforce shortages across developed markets force clinics to delegate product recommendation to automated compliance systems.
- Healthcare Professionals:Hygienist and dentist endorsement pipelines channel patients toward specific fluoride sources.
- E-commerce Shoppers:Digital-native consumers with elevated responsiveness to algorithmic replenishment and direct-to-consumer margins.
Retail consumers command the established base. Dental clinics show the steepest margin expansion.
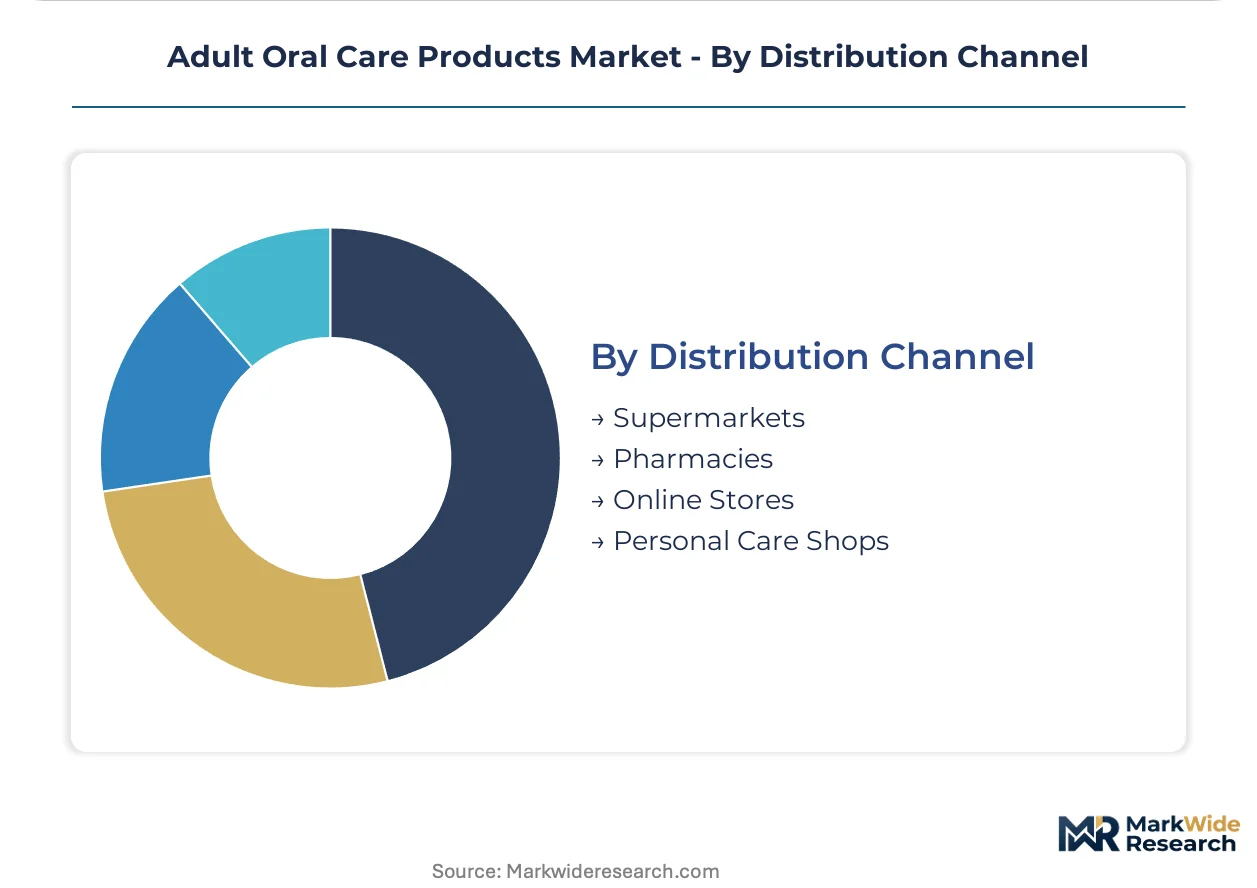
Distribution Channel:
Supply concentration in pharmacy networks creates professional endorsement leverage, while online store infrastructure enables subscription economics that bypass traditional retail intermediaries.
- Supermarkets:Mass-market shelf space commanding impulse purchase behavior and promotional discounting cycles. United States and German chains concentrate volume for standard fluoride dentifrices with rotating promotional calendars. Slotting fees create barriers for formulation innovators lacking scale.
- Online Stores:Direct-to-consumer platforms capturing subscription revenue with automated replenishment algorithms and first-party data relationships. E-commerce shoppers in United States and Japanese metropolitan markets exhibit highest lifetime value metrics. Fulfillment infrastructure investments compress delivery windows to same-day or next-day service.
- Pharmacies:Professional endorsement pipelines with pharmacist consultation and clinical credibility transfer.
- Personal Care Shops:Curated beauty-retail environments emphasizing aesthetic positioning and premium packaging.
Supermarkets command the established base. Online stores climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. Germany channels demand through dental clinics seeking professional-grade prophylaxis pastes, while Japanese consumers favor therapeutic gum formulations and United States shoppers accelerate toward subscription-based replenishment models.
United States
E-commerce shoppers drive disproportionate volume through automated replenishment algorithms that reduce price sensitivity. FDA monographs govern hydrogen peroxide thresholds in whitening strips, constraining formulation latitude for at-home bleaching systems. Metropolitan markets in California and New York concentrate subscription commerce infrastructure with same-day fulfillment capabilities.
Germany
Dental clinics anchor procurement of higher-abrasivity prophylaxis pastes with clinical credibility positioning. EU MDR and REACH frameworks mandate granular chemical substance labeling that exceeds documentation requirements elsewhere. Manufacturing clusters in North Rhine-Westphalia supply professional-grade formulations to clinic networks across the country.
Japan
Aging demographics with elevated dental consciousness pull demand toward therapeutic gum management formulations containing stannous fluoride and essential oils. METI standards and PMDA oversight govern active ingredient safety thresholds for over-the-counter oral care products. Kanto region households in Tokyo and surrounding prefectures exhibit highest per-capita expenditure on preventive oral care regimens.
India
Urban retail consumers in metropolitan centers shift from traditional powder-based cleaners to branded dentifrices with fluoride claims. BIS and CDSCO implementation of tighter standards for imported oral care actives extends market access timelines for multinational suppliers. Manufacturing activity concentrates in Maharashtra and Gujarat where domestic formulation capacity serves price-sensitive mass-market segments.
United Kingdom
Pharmacy channel relationships sustain professional endorsement pipelines for premium therapeutic rinses and sensitivity relief formulations. UK Cosmetics Regulation alignment with EU REACH maintains documentation burdens for chemical substance registration post-Brexit. Greater London and Southeast England concentrate demand for subscription-based oral care services with rapid delivery infrastructure.
Adult Oral Care Products Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the adult oral care products market. Consolidated multinational consumer goods conglomerates with captive fluoride sourcing and manufacturing scale dominate value pools through pharmacy channel relationships and professional endorsement pipelines. Specialist archetypes include connected device manufacturers blurring retail-clinical boundaries and regional formulation houses serving price-sensitive emerging markets. Competitive moves center on backward integration into active ingredient supply and strategic partnerships with dental clinic networks for prescription-connected compliance systems.
Among integrated consumer goods conglomerates, Colgate-Palmolive Company exemplifies archetype positioning through in-house fluoride sourcing capabilities and manufacturing scale that anchors professional-grade supply to clinic networks. Procter & Gamble Company occupies a position leveraging pharmacy channel relationships to sustain endorsement pipelines with dental professionals. Koninklijke Philips N.V. represents the connected device archetype, with sensor hardware and mobile application ecosystems that compress margins for standalone mechanical brushes while creating service revenue opportunities around compliance data interpretation.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble Company |
| Unilever PLC |
| Church & Dwight Co., Inc. |
| Johnson & Johnson Services, Inc. |
| Haleon plc |
| GlaxoSmithKline plc |
| Koninklijke Philips N.V. |
| Henkel AG & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Captive fluoride sourcing at Colgate-Palmolive and Procter & Gamble creates scale advantages that compress unit economics for challengers while establishing price floors across premium and mass-market tiers. Manufacturing scale in North Rhine-Westphalia and Ohio feedstock clusters shapes regional pricing power, with REACH compliance costs and cold-fill certification requirements acting as selective barriers that protect incumbent margin structures.
Pricing Analysis
Long-term offtake agreements between dental clinic networks and professional-grade suppliers dominate institutional procurement, insulating premium tiers from supermarket promotional cycles. Three-tier pricing structure across premium, standard, and economy levels separates prescription-connected brush ecosystems from mechanical brushes and private-label dentifrices. Cost compression in mass-market toothpaste stems from private-label expansion and slotting fee burdens. Retail consumers in United States metropolitan markets exhibit highest price sensitivity, while German dental clinics show lowest sensitivity due to reimbursement eligibility and formulary bypass.
Supply Chain Analysis
Germany, the United States, and Japan anchor domestic manufacturing for toothpaste and mouthwash through emulsion processing clusters, while China and South Korea concentrate specialized film-lamination capacity for whitening strip exports. Hydrogen peroxide, stannous fluoride, and cetylpyridinium chloride feedstock draws from limited chemical suppliers concentrated in North America and Western Europe. Single-source vulnerability in fluoride active sourcing creates input cost volatility during regulatory requalification cycles. Distribution runs through pharmacy networks for professional endorsement leverage and online direct-to-consumer platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected toothbrush ecosystems and prescription-compliance data streams are disrupting traditional category boundaries, creating service revenue pools that reward hardware-software integration and penalize standalone mechanical brush manufacturers.
For Market Incumbents: Secure captive supply agreements for stannous fluoride and cetylpyridinium chloride actives before REACH requalification windows tighten further. Deepen backward integration into cold-fill blending equipment to bypass certification bottlenecks for hydrogen peroxide stability. Lock in dental clinic network partnerships for prescription-connected brush system deployment, as workforce shortages force delegation to automated compliance platforms. For New Entrants and Emerging Players: Anchor in Japanese therapeutic gum management formulations, where aging demographics and elevated dental consciousness create underpenetrated demand for stannous fluoride and essential oil products. Target United States e-commerce subscription channels with algorithmic replenishment models that bypass supermarket slotting fees. Lead with direct-to-consumer margins and first-party data relationships rather than retail shelf presence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected device manufacturers with sensor hardware and mobile application ecosystems that generate compliance data interpretation fees. Five-to-ten year viability favors specialists with emulsion processing expertise and REACH documentation capabilities rather than commodity mechanical brush assemblers. Watch for inflection signals in dental hygienist workforce shortage severity, as automation adoption accelerates clinic procurement of prescription-connected systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoride Sourcing | Captive stannous fluoride supply insulates margin from REACH requalification volatility and input cost spikes. |
| Subscription Commerce Platform Launch | Automated replenishment algorithms in United States metropolitan markets capture lifetime value with reduced price sensitivity. |
| Connected Brush Ecosystem Development | Sensor hardware and mobile applications create data-rich relationships that blur retail-clinical boundaries for German clinics. |
| Professional-Grade Formulation Certification | Elevated abrasive index prophylaxis pastes secure formulary placement in Germany's dental clinic networks. |
| Regulatory Affairs Infrastructure Investment | Dedicated India BIS and CDSCO alignment teams compress market access timelines for multinational active suppliers. |
Study Parameters
A standing panel of dental hygienists, clinic procurement managers, formulation chemists, and pharmacy channel heads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA monograph filings, REACH substance registrations, EMA cosmetic ingredient assessments, and customs trade data for fluoride active imports. Bottom-up demand modeling across patient populations and clinic networks triangulated against top-down macroeconomic indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions spanned product type, application purpose, customer archetype, and distribution channel, with additional modeling for regulatory framework clusters. CAGRs derived from fitted growth curves applied to historical shipment data and clinic procurement survey responses, with hydrogen peroxide concentration trends and subscription adoption rates as industry-specific forecast inputs.
Material uncertainties — regulatory divergence between FDA and REACH disclosure standards, dental hygienist workforce shortage severity, and cold-fill certification bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about continued reimbursement eligibility for professional-grade formulations in Germany and Japan. Recalibration cycles align with material shifts in EU MDR enforcement timelines and connected device ecosystem penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Dry Mouth Relief Market
Oral Care
Baby Teeth Care Products Market
Oral Care
North America Oral Care Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Oral Thrush Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Global Oral Hygiene Market
Oral Care
China Oral Care Market
Oral Care
Baby Oral Care Market
Oral Care
Oral Health Ingredient Market
Oral Care
United States Oral Hygiene Market
Oral Care
Halitosis Treatment Market
Oral Care
BRICS Oral Care Market
Oral Care
Tongue Cleaner Market