
 Spine Surgery Devices Market | 2026-2036
Spine Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spine Surgery Devices Market Outlook
Asset-light leasing models for robotic surgical platforms is reshaping capital deployment across spine surgery, lowering barriers for mid-tier hospitals to adopt advanced navigation systems. Medtronic leverages its integrated spine and robotics portfolio to sustain high account retention in major hospital systems. Stryker Corporation anchors its competitive position through proprietary navigation hardware that extends surgeon workflow control from preoperative planning to intraoperative execution. Globus Medical differentiates via specialized expandable interbody devices that occupy premium positioning in minimally invasive lumbar fusion.
Spine surgery devices comprise implantable and instrumented systems designed to stabilize, decompress, or replace spinal structures, typically manufactured from titanium alloys, polyetheretherketone, or porous tantalum with modulus-matching properties to reduce stress shielding and promote osseointegration. These systems serve to restore sagittal balance, neural decompression, and segmental stability in degenerative, traumatic, or neoplastic pathologies. Spinal fusion devices lead current revenue contribution due to established reimbursement and broad surgeon familiarity, while robotic surgery technology represents the fastest-expanding segment as capital constraints ease through subscription and per-procedure leasing arrangements. Interbody fusion devices concentrate margin pools because of premium pricing tied to surface topography innovations and lordotic restoration capabilities.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose escalating clinical evidence burdens on implantable spine devices, filtering market access toward well-capitalized manufacturers capable of sustaining long-term follow-up studies. Japan's PMDA and South Korea's MFDS maintain distinct biocompatibility and mechanical testing standards that shape regional product registration timelines and localization investments. Stakeholders must monitor evolving site-of-care reimbursement differentials between hospitals and ambulatory surgery centers as procedural migration accelerates and capital allocation models adapt.
Market Dynamics
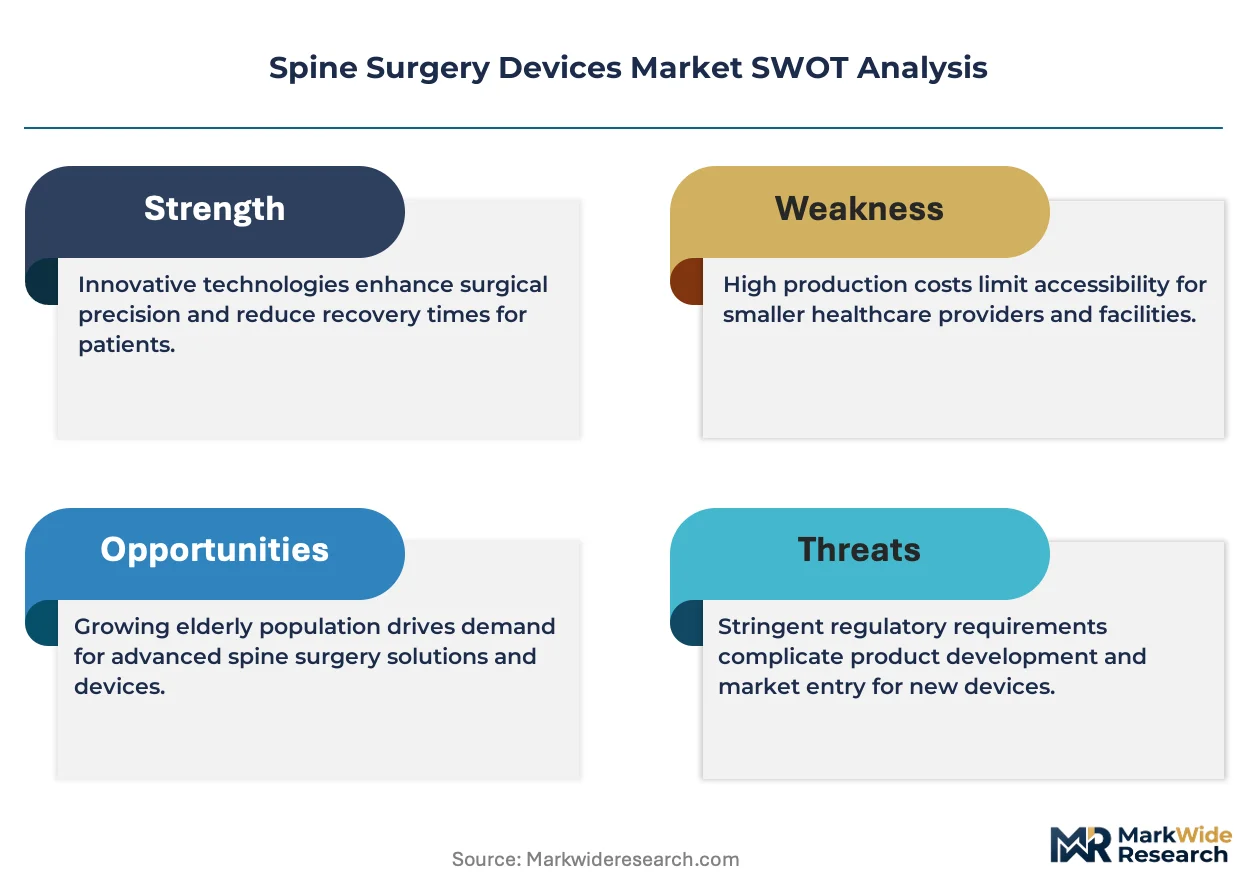
Site-of-care migration from inpatient hospitals to ambulatory surgery centers is compressing capital recovery timelines for spine device manufacturers and forcing pricing recalibration across procedural bundles.
Growth Catalysts
- EU MDR conformity pathways:Elevated clinical evidence standards for implantable devices are filtering market access toward manufacturers with sustained long-term follow-up capabilities, consolidating competitive positions for established players.
- Per-procedure leasing arrangements:Subscription models for robotic surgical platforms are lowering capital barriers for mid-tier hospitals, accelerating navigation system penetration beyond academic medical centers.
- Japan's aging demographic concentration:Elevated degenerative spine disease prevalence in the 65-plus population is driving procedural volume expansion where reimbursement clarity supports higher implant adoption rates.
Market Restraints
- Titanium alloy input volatility:Aerospace and energy sector demand for medical-grade titanium is creating intermittent supply tightness and cost pressure on implantable device margins.
- FDA 510(k) evidentiary escalation:Pre-market notification pathways now require comparative effectiveness data against predicate devices, extending regulatory timelines and development costs for novel implant designs.
- Non-fusion motion preservation substitutes:Artificial disc replacement and dynamic stabilization systems are capturing select patient segments previously channeled toward spinal fusion procedures.
Strategic Opportunities
- South Korea's MFDS pathway optimization:Streamlined biocompatibility testing protocols for predicate-equivalent devices are reducing registration timelines and enabling faster market entry for expandable interbody systems.
- Surface topography convergence:Integration of additive manufacturing with porous tantalum structures is opening premium positioning for osteoconductive interbody devices in minimally invasive lumbar approaches.
- Direct-to-ASC distribution channels:Bypassing traditional hospital supply chain intermediaries is capturing margin pools and enabling real-time inventory replenishment for high-volume surgery centers.
Industry Challenges
- Robotic navigation integration complexity:Surgeon workflow disruption during legacy system transitions is creating adoption friction and requiring extended proctoring investments.
- EU MDR technical documentation timelines:Legacy device recertification under strengthened clinical evidence requirements is consuming regulatory affairs bandwidth and delaying portfolio refresh cycles.
- Biomechanical engineer talent scarcity:Specialized expertise in modulus-matching implant design and finite element modeling is concentrating among a limited pool of orthopedic device specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spine Surgery Devices Market |
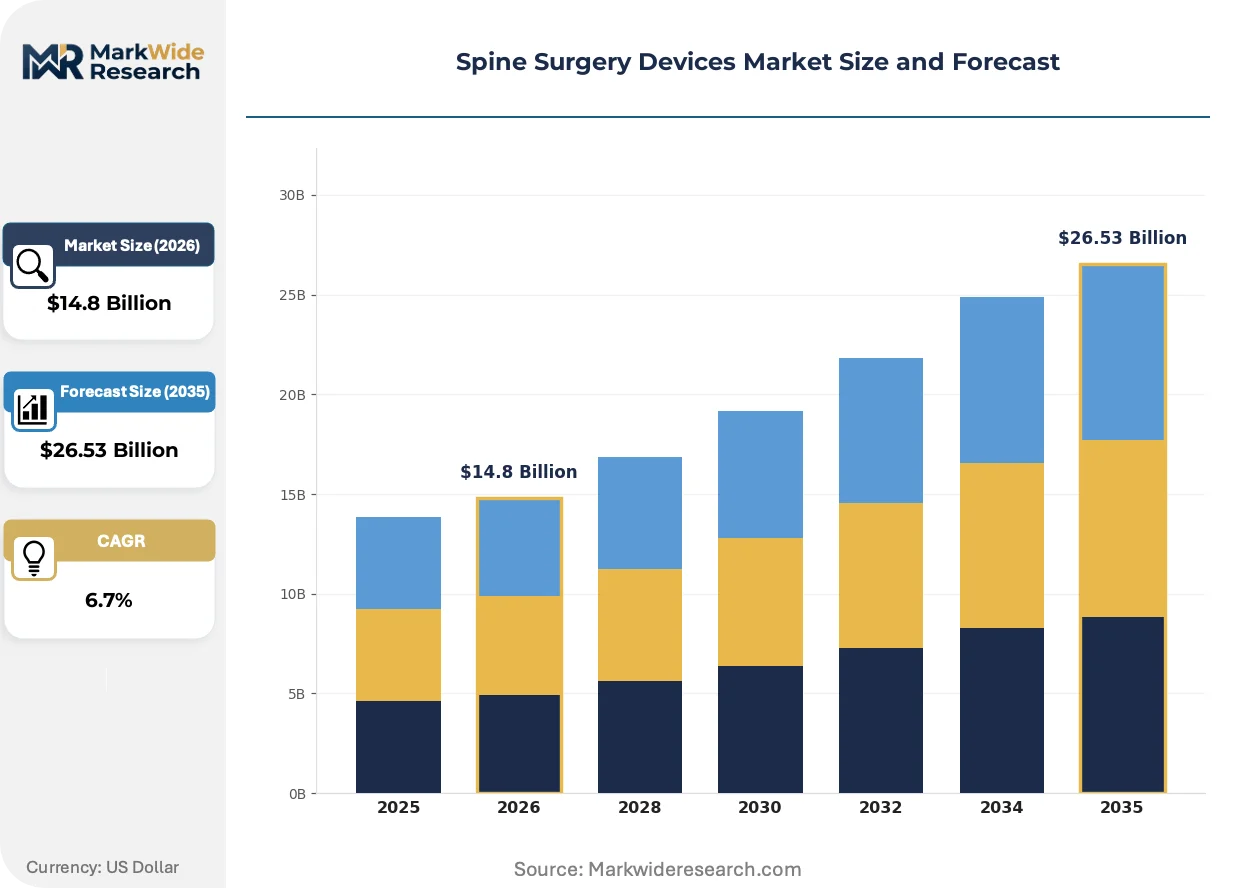
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intramedullary Nails, Spinal Fusion Devices, Vertebral Compression Fracture Devices, Interbody Fusion Devices End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Rehabilitation Centers Technology: Image-Guided Surgery, Robotic Surgery, Minimally Invasive Surgery, Traditional Open Surgery Application: Spinal Stabilization, Deformity Correction, Pain Management, Tumor Treatment |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker Corporation, Zimmer Biomet Holdings, Globus Medical, NuVasive, Alphatec Spine, RTI Surgical, Orthofix Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spine Surgery Devices Market Strategic Shifts
Convergence of additive manufacturing with patient-specific anatomical modeling is dissolving the boundary between standardized implant catalogs and bespoke surgical solutions.
Expandable interbody cage systems with integrated lordotic adjustment mechanisms are rendering obsolete fixed-height PEEK and titanium cages that require trialing multiple sizes intraoperatively. Ambulatory surgery centers are adopting these devices at twice the rate of traditional hospitals due to reduced operative time and inventory carrying costs. The structural consequence is compression of SKU proliferation strategies that previously sustained premium pricing through size granularity.
Japan's PMDA has implemented post-market surveillance mandates requiring ten-year follow-up data for cervical and lumbar fusion devices, elevating clinical evidence burdens beyond FDA 510(k) thresholds. Manufacturers must now maintain dedicated Japanese registry infrastructure or risk market withdrawal. Cervical disc replacement systems face the steepest compliance costs due to smaller patient cohorts and extended follow-up protocols.
Surgeon preference is rotating toward bundled procedural contracts that consolidate implant, biologic, and navigation fees into single episode payments. Hospital purchasing committees are displacing individual surgeon vendor selection authority with value-analysis team decisions. This behavioral shift is most pronounced in Germany, where sickness funds are piloting indication-based reimbursement for lumbar fusion procedures.
Spine Surgery Devices Market Segmentation
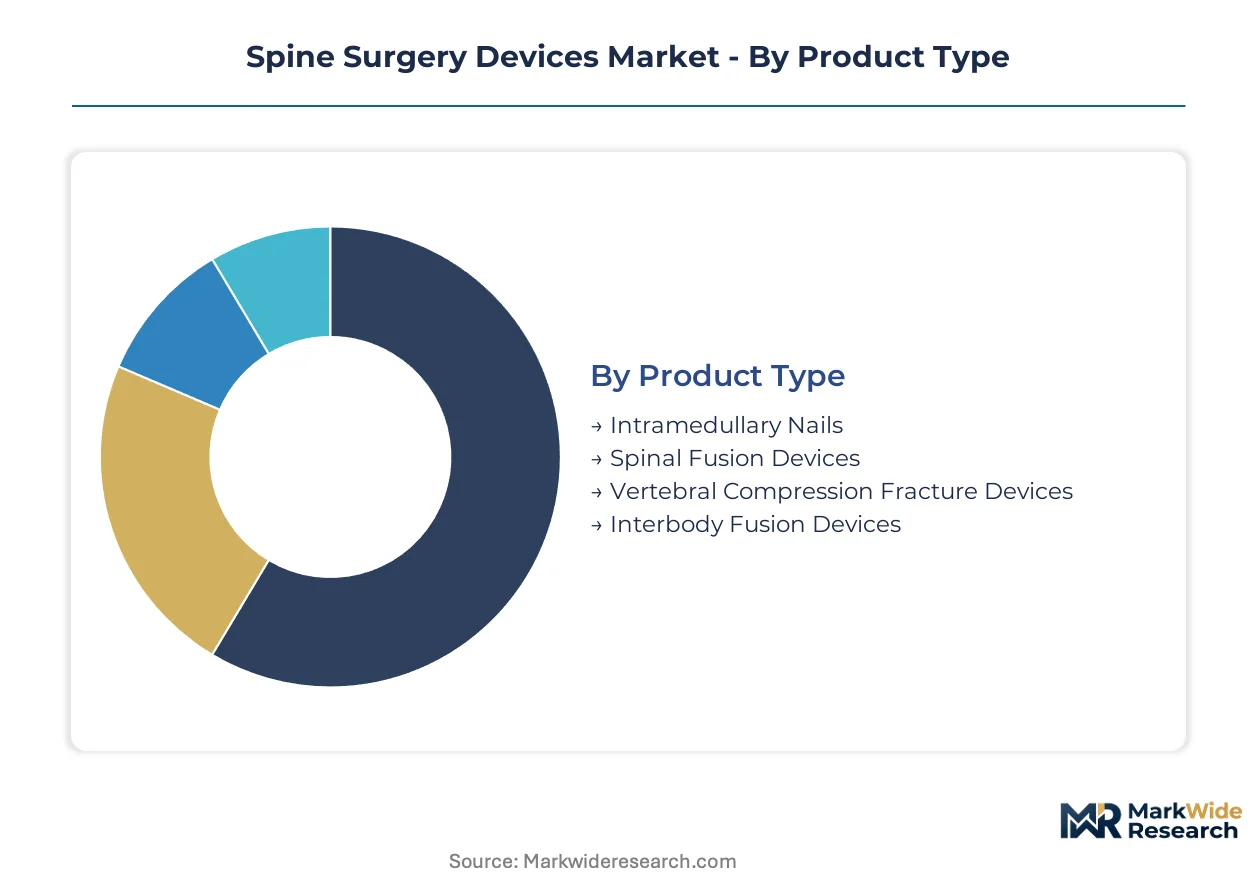
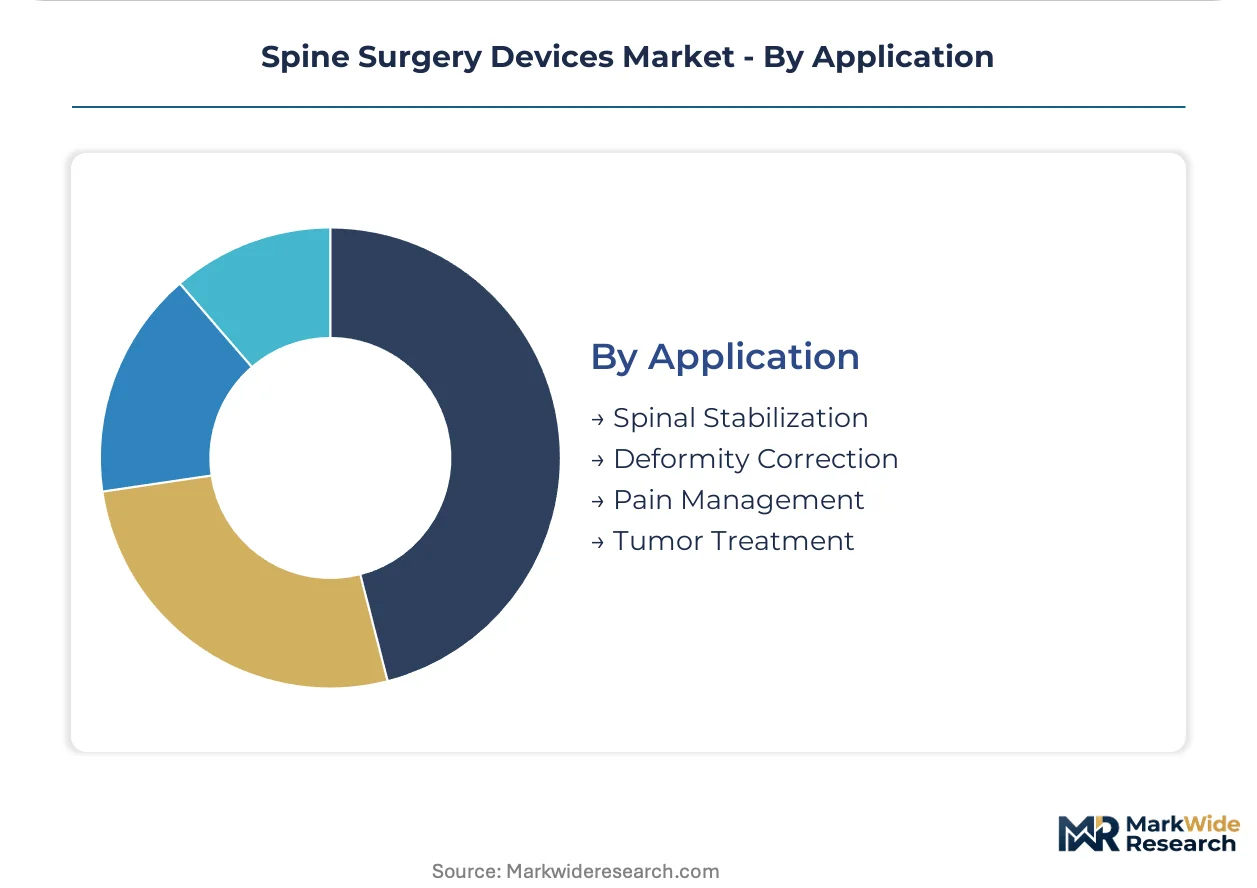
Segmentation in spine surgery devices reveals divergent margin structures across product architectures and care settings. Technology choices determine capital intensity and reimbursement pathways, while end-user shifts are compressing traditional hospital procurement hierarchies.
Product Type:
Mature fusion hardware dominates current revenue pools while emerging expandable and motion-preservation designs capture premium positioning.
- Spinal Fusion Devices:Pedicle screw-rod constructs and plate systems manufactured from titanium alloys or cobalt-chromium provide rigid segmental immobilization for degenerative disc disease and spondylolisthesis. Demand concentrates in United States hospital systems where bundled payment models favor established fusion codes. Reimbursement clarity and surgeon training depth sustain volume leadership despite longer recovery profiles.
- Interbody Fusion Devices:Cages manufactured from PEEK, titanium, or porous tantalum restore disc height and promote arthrodesis through osteoconductive surface engineering. Ambulatory surgery centers in Germany and Japan are adopting lordotic-adjustable expandable variants at accelerated rates, reducing operative time and inventory complexity. Surface topography innovations command premium pricing in minimally invasive lumbar approaches.
- Vertebral Compression Fracture Devices:Balloon kyphoplasty and vertebroplasty systems stabilize osteoporotic collapse through polymethylmethacrylate cement delivery.
- Intramedullary Nails:Load-sharing implants for thoracolumbar trauma provide rotational stability through proximal and distal interlocking screw fixation.
Spinal fusion devices handle the majority of throughput; interbody fusion devices are expanding most quickly on share.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean ambulatory operations.
- Hospitals:Academic medical centers and community hospitals maintain comprehensive spine programs with robotic navigation suites and 24-hour emergency coverage. These facilities capture complex deformity correction and tumor resections requiring intensive care support. Germany's sickness funds and United States Medicare reimbursement differentials favor inpatient coding for multilevel procedures.
- Ambulatory Surgery Centers:Freestanding facilities perform single and two-level lumbar fusions with same-day discharge protocols. Site-of-care migration is accelerating as payors push procedural volume toward lower-cost settings. Inventory carrying costs and case throughput efficiency determine vendor selection authority.
- Specialty Clinics:Orthopedic and neurosurgical group practices concentrate diagnostic workup and postoperative monitoring.
- Rehabilitation Centers:Post-acute facilities manage functional recovery protocols following implantation.
Hospitals retain the dominant share of complex procedure volume; ambulatory surgery centers are climbing the fastest on procedural migration.
Technology:
Application intensity varies by surgical invasiveness and navigation dependency.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce paraspinal muscle disruption and accelerate recovery. Japan's PMDA and United States FDA have cleared expandable interbody systems specifically for MIS corridors, driving adoption in aging patient populations. Surgeon learning curves and radiation exposure concerns constrain penetration.
- Robotic Surgery:Navigation platforms with preoperative planning software and intraoperative guidance execute screw trajectories with submillimeter accuracy. Subscription and per-procedure leasing models are lowering capital barriers for mid-tier hospitals beyond academic centers. Integration complexity and workflow disruption create adoption friction requiring extended proctoring.
- Image-Guided Surgery:Fluoroscopy and CT-based navigation provides real-time visualization without robotic arm constraints.
- Traditional Open Surgery:Midline approaches with direct visualization remain standard for severe deformity and trauma reconstruction.
Traditional open surgery handles the majority of global procedure volume; robotic surgery is gaining share fastest on capital deployment flexibility.
Application:
Volume distribution follows degenerative disease prevalence while margin concentration sits with complex reconstruction.
- Spinal Stabilization:Fusion and dynamic fixation procedures address instability from degenerative disc disease, spondylolisthesis, and post-laminectomy syndrome. United States Medicare and commercial payors have established distinct reimbursement codes driving predictable revenue capture. Implant selection prioritizes modulus-matching materials to reduce stress shielding.
- Deformity Correction:Scoliosis and kyphosis reconstruction requires multilevel osteotomy and three-column fixation with high implant density. Germany's indication-based reimbursement pilots and United States specialty hospital carve-outs concentrate these procedures in high-volume centers. Case complexity sustains premium pricing for patient-specific instrumentation.
- Pain Management:Neurostimulation and targeted drug delivery systems address chronic radiculopathy and failed back surgery syndrome.
- Tumor Treatment:Corpectomy and stabilization following metastatic vertebral body resection demands expandable cages and anterior column support.
Spinal stabilization commands the dominant procedure volume; deformity correction is expanding fastest on premium pricing and center consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals capture pricing premiums through bundled payment models, while German ASCs compress implant margins via indication-based reimbursement pilots. Japan's PMDA mandates ten-year follow-up data for fusion devices, elevating clinical evidence costs beyond FDA thresholds.
United States
Medicare reimbursement clarity and commercial payor bundled contracts drive procedural volume concentration in academic medical centers and specialty hospitals. FDA 510(k) pathways now require comparative effectiveness data against predicate devices, extending regulatory timelines. The Midwest corridor houses high-volume spine programs in Cleveland and Minneapolis where robotic navigation suites anchor comprehensive deformity centers.
Germany
Sickness funds pilot indication-based reimbursement for lumbar fusion, shifting procurement authority from individual surgeons to value-analysis committees. EU MDR technical documentation requirements consume regulatory bandwidth for legacy device recertification. The Rhine-Ruhr metropolitan region concentrates orthopedic manufacturing clusters in Düsseldorf and Cologne where mid-tier hospitals adopt per-procedure leasing for navigation platforms.
Japan
Aging demographics concentrate degenerative spine disease prevalence among the 65-plus population, supporting higher implant adoption rates where reimbursement clarity exists. PMDA post-market surveillance mandates require dedicated registry infrastructure for cervical and lumbar fusion devices. Tokyo and Osaka academic centers maintain the deepest surgeon training pipelines for minimally invasive expandable interbody approaches.
South Korea
MFDS streamlined biocompatibility testing protocols for predicate-equivalent devices reduce registration timelines for expandable interbody systems. National health insurance reimbursement rates for spinal fusion lag OECD averages, constraining premium implant penetration. The Seoul Capital Area concentrates high-volume spine centers in Gangnam and Songpa districts where ambulatory migration accelerates same-day discharge protocols.
Switzerland
Swissmedic maintains distinct mechanical testing standards for porous tantalum structures, shaping regional product registration timelines. Cantonal hospital procurement federations consolidate purchasing power across Zurich, Bern, and Geneva university hospitals. The Basel pharmaceutical-industrial corridor extends into orthopedic device manufacturing with specialized surface topography engineering capabilities.
Spine Surgery Devices Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in implant and instrument niches. The market structures around three tiers: diversified conglomerates with robotics-spine integration, mid-cap specialists in expandable interbody devices, and regional fabricators serving ASC direct channels. Consolidation pressures favor players with sustained long-term follow-up capabilities under EU MDR and PMDA mandates. Dominant competitive moves include M&A to capture navigation software assets and backward integration into titanium alloy processing to offset aerospace demand volatility.
Among diversified platform integrators, Medtronic and Stryker Corporation occupy positions exemplifying system-tier consolidation through integrated spine-robotics portfolios. Globus Medical represents the mid-cap specialist archetype, anchoring premium positioning in minimally invasive lumbar approaches. These three entities illustrate how regulatory evidence burdens and capital deployment flexibility separate scalable platform players from component-focused competitors.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Globus Medical |
| NuVasive |
| Alphatec Spine |
| RTI Surgical |
| Orthofix Holdings |
| Others |
Value Chain & Pricing Dynamics
Titanium alloy input volatility from aerospace sector competition determines both implant margin compression and supply chain regionalization strategies across spine device manufacturing. Manufacturers respond with backward integration into alloy processing and geographic diversification of forging partnerships to stabilize cost bases.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels for pedicle screw-rod constructs and interbody cages. Price differentiation stems from surface topography innovation grade and FDA 510(k) predicate equivalence tier. Cost compression in standard-tier implants is intensifying because ambulatory surgery centers demand bundled procedural contracts. High-volume ASC procurement teams exhibit greatest price sensitivity while academic medical centers prioritize navigation integration over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates strategic planning for titanium alloy rod and PEEK resin sourcing. Medical-grade titanium feedstock concentrates in United States, Germany, and Japan where aerospace demand creates intermittent allocation constraints. Raw material dependencies center on titanium sponge, medical-grade PEEK polymer, and porous tantalum substrate. Single-source vulnerability persists for additive manufacturing powder specifications. Distribution runs through GPO contracts and direct-to-ASC channels bypassing traditional hospital intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spine surgery devices sit at an early-cycle expansion story where per-procedure leasing for robotic platforms is accelerating navigation adoption beyond academic centers into mid-tier hospitals.
For Market Incumbents: Entrench platform integration advantages by deepening control over titanium alloy processing to offset aerospace demand volatility. Lock hospital system relationships through bundled navigation-implant contracts that raise switching costs for competitors facing EU MDR recertification burdens. For New Entrants and Emerging Players: Pursue direct-to-ASC distribution channels in Germany and Japan where site-of-care migration outpaces incumbent channel adaptation. Target expandable interbody device segments in South Korea where MFDS streamlined pathways reduce regulatory entry barriers. Lead with operative time reduction claims validated by ambulatory surgery center case volume data. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with sustained long-term follow-up capabilities under PMDA and EU MDR mandates. Five-to-ten year viability hinges on registry infrastructure ownership and navigation software assets. Watch for ambulatory surgery center procedural volume thresholds as inflection indicators for leasing model profitability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Comparative effectiveness data requirements extend timelines for novel implant designs. |
| EU MDR Technical Documentation | Legacy device recertification consumes regulatory bandwidth and delays portfolio refreshes. |
| Hospital System Partnership | Bundled navigation-implant contracts consolidate procurement authority and raise switching costs. |
| Software Companion Development | Preoperative planning integration deepens surgeon workflow control and platform stickiness. |
| Reimbursement Strategy | Site-of-care coding optimization captures ASC migration volume before competitors adapt. |
Study Parameters
A standing panel of spine surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interviews. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up implant volume modeling triangulated against top-down market sizing from capital equipment leasing disclosures.
Scenario-bracketing around regulatory timeline delays and site-of-care migration pace framed projection uncertainty across the analysis window. Segmentation dimensions spanned product architecture, end-user facility type, surgical technology, and regional regulatory cluster. CAGRs derived from procedural volume trajectories, implant ASP erosion curves, and navigation platform penetration rates. Forecast inputs incorporated PMDA registry mandate compliance costs and titanium alloy spot price volatility assumptions.
Sensitivities concentrate around EU MDR recertification timeline extensions and ambulatory surgery center reimbursement coding shifts. Forecasts reflect documented assumptions regarding surgeon training pipeline depth and payor site-of-care incentive structures. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Global Spinal Fusion Devices Market
Orthopedic Devices
Spinal Surgery Devices Market