
 Global Oral Care Products Market | 2026-2036
Global Oral Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oral Care Products Market Analysis
REACH is recalibrating the cost-of-entry calculus for oral care manufacturers seeking European market access, forcing reformulation of preservative systems and flavor compounds. Colgate-Palmolive leverages its captive fluoride sourcing network to sustain margin stability across regulated jurisdictions. Procter & Gamble anchors its competitive position through R&D intensity in enzymatic whitening technologies. Unilever differentiates via geographic dominance in emerging markets through locally adapted herbal formulations.
Oral care products encompass dentifrices, antiseptic rinses, interdental cleaning devices, and aesthetic whitening systems formulated with active agents such as stannous fluoride, hydrogen peroxide, or essential oils to prevent caries, reduce plaque accumulation, and manage gingival inflammation. These products serve both prophylactic home-use routines and adjunctive professional dental therapy protocols. Toothpaste occupies the largest revenue pool given its near-universal daily-use penetration, while whitening products represent the fastest-expanding margin segment as aesthetic dentistry demand escalates. Online retail channels are capturing disproportionate growth velocity among younger demographics, though pharmacies retain structural importance for clinical-grade formulations and professional-use mouthwash distribution.
The FDA governs over-the-counter oral care as cosmetic-drug hybrids through monograph compliance for anticaries and antigingivitis claims, while China's NMPA enforces GB standards for imported toothpaste safety and labeling. Japan's PMDA maintains distinct quasidrug classification for medicated oral rinses, creating segmented registration pathways that shape multinational portfolio architecture. Stakeholders must monitor evolving microbiome-friendly claim substantiation requirements as regulators scrutinize probiotic and prebiotic oral care positioning.
Market Dynamics
The oral care market pivots on regulatory recalibration of ingredient safety standards, with REACH and China's GB standards forcing simultaneous reformulation of preservative systems across multinational portfolios.
Growth Catalysts
- EU Green Deal disclosure mandates:Ingredient transparency requirements are accelerating clean-label product development and premium positioning across European retail channels.
- Enzymatic whitening technologies:Peroxide-free aesthetic solutions are capturing professional dental referral networks and high-margin direct-to-consumer subscriptions.
- Pediatric oral hygiene programs:School-based prevention initiatives in China and India are expanding daily-use penetration among children under twelve.
Market Restraints
- Fluoride supply concentration:Captive sourcing networks controlled by integrated multinationals create entry barriers for regional formulators lacking backward integration into active mineral supply.
- REACH compliance costs:Safety data dossier requirements for flavor compounds and preservatives are elevating fixed costs for small and mid-size manufacturers seeking European market access.
- Biodegradable packaging cost premiums:Sugarcane-derived tubes and aluminum alternatives carry 40-60% unit cost premiums versus conventional plastics, compressing mass-market margins.
Strategic Opportunities
- Microbiome-friendly positioning:Probiotic and prebiotic oral rinses are creating unoccupied claim territory ahead of finalized substantiation guidelines from FDA and EFSA.
- Rural India penetration:Sachet-format herbal toothpastes distributed through kirana stores address price sensitivity and single-use purchase patterns in underpenetrated districts.
- Tele-dental subscription integration:Remote diagnostic platforms are opening bundled product-prescription channels linking AI-powered plaque assessment to personalized dentifrice regimens.
Industry Challenges
- Cross-jurisdictional claim harmonization:Anticaries efficacy standards diverge between FDA monographs, Japan's PMDA quasidrug rules, and NMPA GB testing protocols, fragmenting global portfolio architecture.
- Clinical trial recruitment bottlenecks:Gingivitis reduction studies require extended observation periods and specialist supervision, stretching R&D timelines for novel therapeutic formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oral Care Products Market |
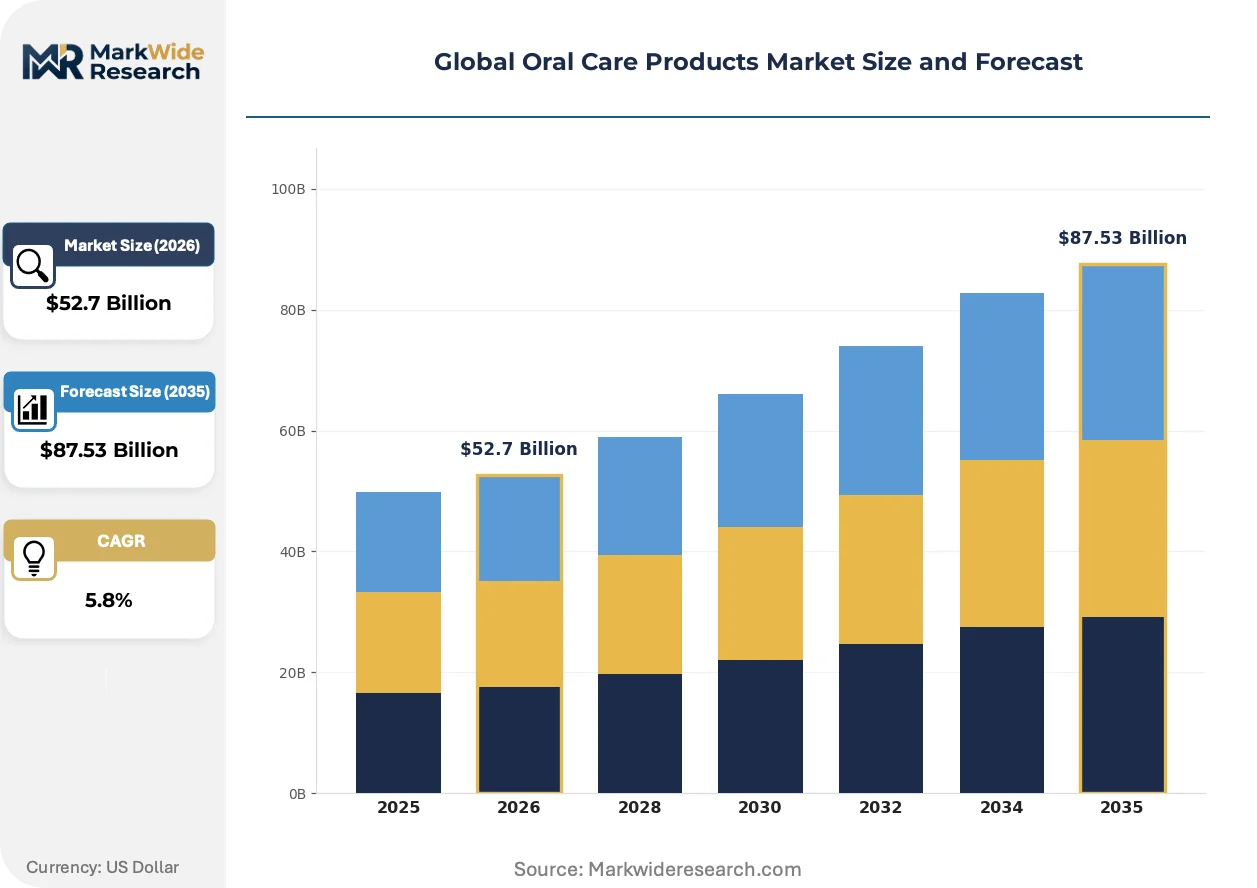
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $87.53 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Products Usage Frequency: Daily Use, Weekly Use, Occasional Use, Professional Use Target Consumer: Adults, Children, Seniors, Special Needs Sales Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Colgate-Palmolive, Procter & Gamble, Unilever, Johnson & Johnson, GlaxoSmithKline, Church & Dwight, Lion Corporation, Sunstar Suisse, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oral Care Products Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape competitive boundaries, with sustainability credentials and digital channel integration becoming primary differentiation vectors rather than secondary positioning.
Smart oral care devices integrating pressure sensors and Bluetooth connectivity are expanding into preventive home-care routines. Millennial and Gen-Z consumers in North America and Western Europe are adopting these systems at accelerating replacement cycles, compressing traditional manual brush upgrade intervals and capturing recurring consumables revenue through proprietary brush head ecosystems.
REACH authorization requirements for zinc pyrithione and triclosan alternatives are forcing preservative system redesigns across European antiseptic rinse portfolios. Manufacturers are substituting essential oil complexes and stabilized chlorine dioxide, with professional-use mouthwash categories experiencing the most intensive reformulation activity as clinical efficacy claims face heightened toxicological scrutiny.
Direct-to-consumer subscription models are displacing pharmacy-centric replenishment patterns among urban professionals in China and South Korea. These platforms bundle personalized toothpaste formulations with AI-driven brushing feedback, capturing customer lifetime value through data-locked ecosystem stickiness while eroding traditional retail margin pools for standard SKUs.
Global Oral Care Products Market Segmentation
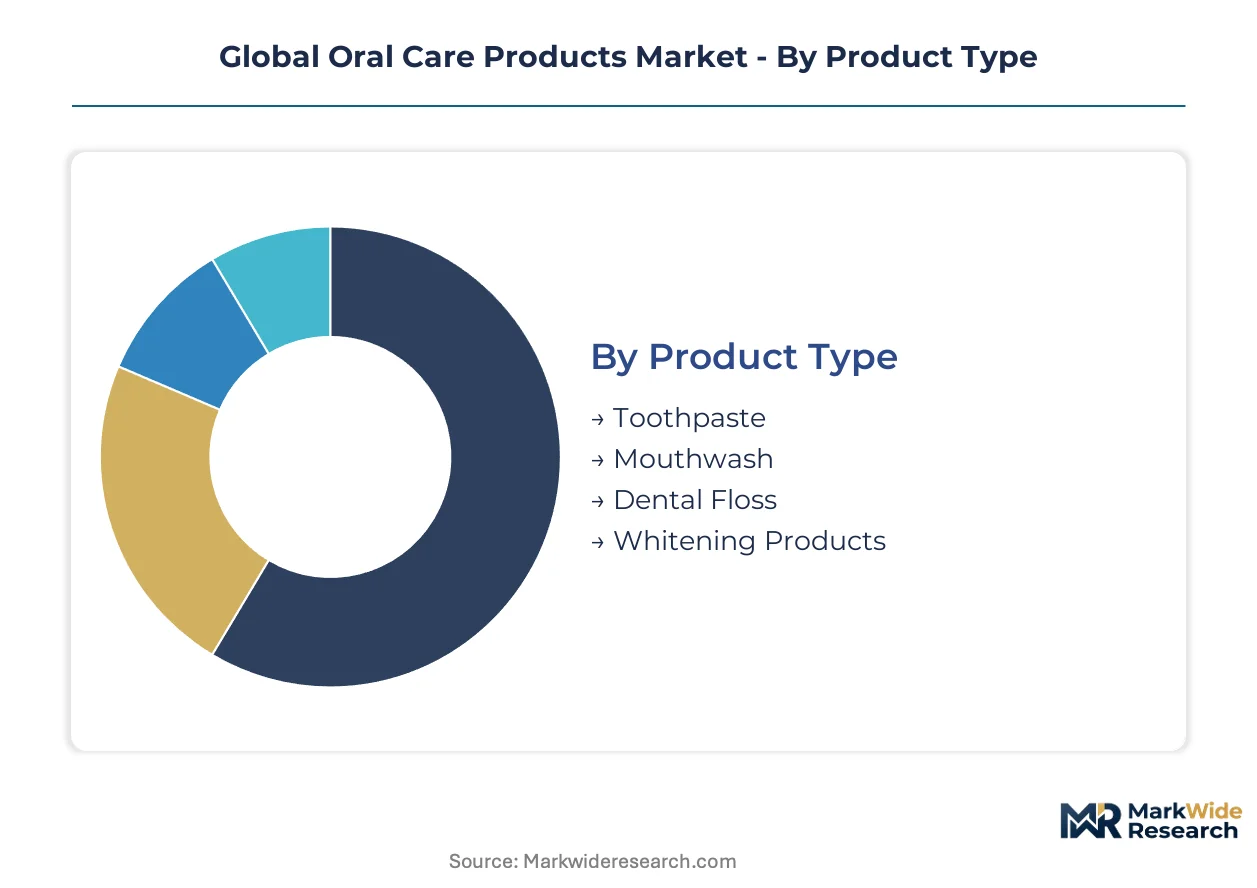
Segmentation in oral care reveals divergent profit pools across usage contexts and channel economics. Product form and purchase frequency together determine formulation complexity, packaging requirements, and regulatory classification pathways.
Product Type:
Buyers differentiate primarily by therapeutic claim intensity versus aesthetic positioning, which dictates active ingredient selection and margin structure.
- Toothpaste:Formulated with stannous fluoride, potassium nitrate, or hydroxyapatite for caries prevention and sensitivity management. Volume concentrates in mass-market daily-use segments across India and Brazil, where unit economics favor high-frequency replenishment over premium positioning.
- Whitening Products:Hydrogen peroxide gels, carbamide peroxide strips, and LED-accelerated systems target aesthetic dentistry demand. Demand clusters among urban professionals in South Korea and the United States, driven by social media visibility and workplace appearance standards.
- Mouthwash:Antiseptic rinses with essential oil or chlorine dioxide formulations for plaque reduction.
- Dental Floss:Nylon monofilament and PTFE tape variants for interdental cleaning compliance.
Volume sits with toothpaste; growth tilts toward whitening products.
Usage Frequency:
Regulatory classification splits across cosmetic, drug, and medical device boundaries depending on claim intensity and supervised application context.
- Daily Use:Low-concentration fluoride dentifrices and alcohol-free rinses designed for unsupervised home regimens. Penetration peaks in Japan and Germany, where dental professional endorsement drives protocol adherence and premium SKU selection.
- Professional Use:High-concentration fluoride varnishes, prophylaxis pastes, and prescription-strength peroxide systems administered in clinical settings. Demand concentrates in dental service clusters across Spain and Australia, where reimbursement frameworks subsidize preventive interventions.
- Weekly Use:Intensive whitening trays and therapeutic rinses for periodic deep cleaning.
- Occasional Use:Travel-sized formats and event-focused whitening strips for situational needs.
Revenue concentrates in daily use; margin expansion tracks professional use.
Target Consumer:
Age-linked oral health conditions and motor skill development stage formulation requirements and packaging accessibility standards.
- Children:Low-fluoride, flavored formulations with safety-sealed packaging to prevent ingestion risk. School-based distribution programs in China and Mexico are expanding penetration among ages 3-12, supported by parental dental anxiety reduction campaigns.
- Seniors:Dry mouth formulations, denture adhesives, and sensitivity-focused actives addressing age-related salivary decline and gingival recession. Demand clusters in aging populations across Italy and Japan, where pharmacy channels provide consultation-intensive purchasing environments.
- Adults:Multi-benefit whitening and sensitivity combinations for maintenance-oriented routines.
- Special Needs:Adaptive packaging and simplified application systems for motor or cognitive accessibility requirements.
Volume dominance rests with adults; pediatric and senior segments are climbing the fastest.
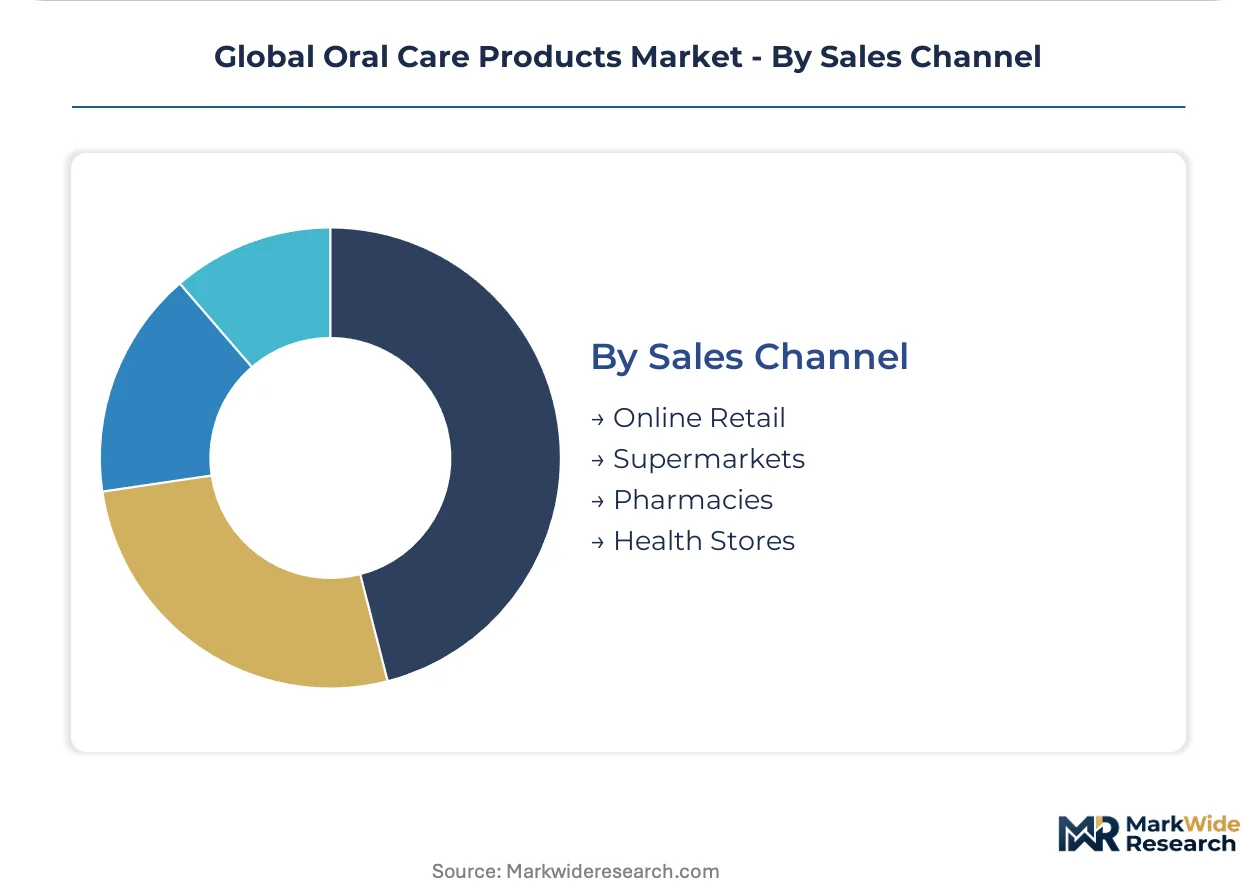
Sales Channel:
Channel selection determines price transparency, subscription attach rates, and clinical credibility transfer.
- Online Retail:Direct-to-consumer platforms enabling personalized formulation and replenishment automation. Subscription models capture professionals in China and the United Kingdom through AI-driven brushing feedback integration and loyalty-locked consumables ecosystems.
- Pharmacies:Clinical-grade formulations requiring pharmacist consultation or prescription verification. Structural importance persists in France and Canada, where therapeutic claims demand professional endorsement and insurance documentation.
- Supermarkets:Mass-market SKUs with high-visibility merchandising and promotional intensity.
- Health Stores:Natural-positioned and certified-organic assortments targeting ingredient-conscious segments.
Transaction volume flows through supermarkets; customer lifetime value accumulates in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cross-border e-commerce pilot zones concentrate oral care manufacturing for duty-advantaged export. Tax incentives in these zones attract multinational packaging operations and formulation labs serving Asia-Pacific demand.
China
Domestic herbal-positioned toothpaste brands capture share through NMPA GB standards compliance and traditional medicine credibility. School-based pediatric prevention programs in Shanghai and Guangzhou expand daily-use penetration among children under twelve. Manufacturing clusters in Guangdong Province supply sachet formats for rural distribution through kirana-adapted channels.
United States
Aesthetic dentistry demand drives hydrogen peroxide whitening system adoption among urban professionals. FDA monograph compliance for anticaries claims shapes OTC dentifrice formulation requirements. Dental service clusters in California and Texas concentrate professional-use fluoride varnish consumption.
Germany
REACH authorization dossiers for preservative alternatives elevate compliance costs for antiseptic rinse portfolios. Pharmacy channels retain structural importance for clinical-grade formulations requiring pharmacist consultation. Manufacturing operations in North Rhine-Westphalia supply enzymatic whitening technologies to European retail networks.
India
Rural price sensitivity sustains demand for single-use sachet formats distributed through kirana stores. Bureau of Indian Standards certification requirements shape import safety protocols for multinational entrants. Production facilities in Maharashtra and Gujarat serve mass-market daily-use segments with high-frequency replenishment economics.
Japan
PMDA quasidrug classification for medicated oral rinses creates segmented registration pathways for therapeutic claims. Aging population demand concentrates in dry mouth formulations and denture adhesive categories. Osaka-based manufacturers export probiotic-positioned products ahead of finalized EFSA substantiation guidelines.
Global Oral Care Products Market Vendor Landscape
North American producers anchor one tier; European specialists hold formulation-science positioning. The market exhibits consolidated structure among integrated multinationals with captive fluoride sourcing, while regional formulators compete on herbal adaptation and price-accessible formats. Three archetypes dominate: backward-integrated giants with mineral supply control, emerging-market herbal specialists, and subscription-platform direct-to-consumer operators. Competitive moves concentrate on enzymatic technology licensing and sustainable packaging partnerships.
Within the integrated multinational tier, Colgate-Palmolive, Procter & Gamble, and Unilever occupy positions defined by geographic coverage and active-agent sourcing advantages. Colgate-Palmolive exemplifies backward integration into fluoride mineral supply. Procter & Gamble represents R&D intensity in peroxide-free whitening systems. Unilever anchors emerging-market penetration through locally adapted herbal formulations. These three entities collectively illustrate how supply control, technology investment, and geographic adaptation separate market tiers.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| Procter & Gamble |
| Unilever |
| Johnson & Johnson |
| GlaxoSmithKline |
| Church & Dwight |
| Lion Corporation |
| Sunstar Suisse |
| Henkel |
| Others |
Supply Flow & Price Mechanics
Mass-market retail buyers in India and Brazil anchor volume-weighted pricing, locking suppliers into high-frequency replenishment contracts that sacrifice margin for shelf access. This buyer concentration forces manufacturers to absorb packaging cost premiums or cede position to regional sachet-format competitors.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to enzymatic whitening systems and clinical-grade fluoride varnishes demanded by dental service clusters in California and Texas. Three-tier pricing structure across premium, standard, and economy levels separates subscription-platform personalized formulations from mass-market SKUs and rural sachet formats. Cost compression in biodegradable packaging tiers is intensifying because sugarcane-derived tubes carry forty to sixty percent unit cost premiums versus conventional plastics. Price sensitivity peaks among rural Indian consumers purchasing single-use sachets through kirana-adapted channels; it bottoms out among urban Chinese professionals subscribing to AI-integrated oral care ecosystems.
Supply Chain Analysis
Domestic-content mandates in China's NMPA GB standards and India's Bureau of Indian Standards certification requirements are reshaping sourcing toward localized formulation labs and packaging operations. Active mineral supply concentrates in captive networks controlled by integrated multinationals with fluoride sourcing operations spanning Morocco, China, and the United States. Stabilized chlorine dioxide and essential oil complexes for preservative system redesigns draw from specialty chemical producers in Germany and Japan. Single-source vulnerability in fluoride mineral supply creates entry barriers for regional formulators lacking upstream control. Distribution runs through pharmacy channels for clinical-grade formulations in France and Canada, direct-to-consumer platforms for subscription models in China and South Korea, and supermarket merchandising for mass-market daily-use segments in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoride supply concentration among three integrated multinationals props pricing power across regulated jurisdictions, constraining volume expansion for non-integrated competitors.
For Market Incumbents: Acquire captive fluoride mineral sourcing assets in Morocco or western China to defend margin stability against REACH-driven reformulation cost inflation. Lock in five-year supply agreements with sugarcane-derived packaging converters before EU Green Deal disclosure mandates accelerate sustainable material demand. Channel control through pharmacy partnerships in Germany and France remains essential for clinical-grade formulation credibility transfer. For New Entrants and Emerging Players: Tele-dental subscription platforms represent the most penetrable channel for bypassing incumbent retail shelf dominance. Target rural Indian districts with sachet-format herbal toothpastes distributed through kirana-adapted networks where daily-use penetration remains underdeveloped. Microbiome-friendly probiotic rinses offer unoccupied claim territory ahead of finalized FDA and EFSA substantiation guidelines. For Investors and Strategic Acquirers: The window for entry favors regional herbal specialists with NMPA GB compliance and traditional medicine credibility in China's domestic market. Long-term viability hinges on acquisition targets possessing backward integration into active mineral supply or exclusive licensing for peroxide-free whitening technologies. Watch for EFSA microbiome claim substantiation rulings as the inflection indicator for probiotic oral rinse category legitimacy.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoride Supply | Captive mineral sourcing anchors margin stability across REACH and FDA regulated jurisdictions. |
| Enzymatic Whitening Technology Licensing | Peroxide-free systems capture professional dental referral networks in South Korea and the United States. |
| Direct-to-Consumer Subscription Launch | AI-integrated platforms lock customer lifetime value through data-locked ecosystem stickiness in China. |
| Sustainable Packaging Transition | Sugarcane-derived tubes and aluminum alternatives satisfy EU Green Deal disclosure mandates ahead of competitors. |
| Rural Distribution Channel Expansion | Kirana-adapted sachet formats address price sensitivity in underpenetrated Indian districts. |
Methodological Framework
Multi-period observation of NMPA GB standard evolution, REACH authorization timelines, and FDA monograph amendments anchored the trend analysis, supplemented by interviews with brand managers at multinational consumer goods companies, category buyers at pharmacy retail chains, supply planners at packaging converters, and regulatory affairs leads at oral care formulators. Secondary validation drew from FDA OTC monograph databases, ECHA REACH registration dossiers, NMPA cosmetic ingredient safety filings, and Nielsen retail audit data across seven countries. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Input-output matrices mapped fluoride mineral sourcing flows, formulation cost structures, and channel margin economics across the projection horizon. Segmentation dimensions modeled included product type, usage frequency classification, target consumer age bracket, and sales channel archetype. CAGRs were derived from regression analysis against dental service expenditure trends, pediatric prevention program enrollment data, and subscription platform adoption curves. Whitening product demand elasticity and preservative system reformulation cost trajectories informed scenario-weighted outputs.
Caveats apply where EFSA microbiome claim substantiation rulings, NMPA herbal ingredient safety reassessments, or biodegradable packaging cost curves could materially shift the outlook. Forecasts reflect documented assumptions about regulatory timelines and raw material supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Thrush Market
Oral Care
Kids Toothpaste Market
Oral Care
South America Oral Care Market
Oral Care
Oral Rinse Market
Oral Care
Mouth Sore Medicine Market
Oral Care
United States Oral Hygiene Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Mouthwash Market
Oral Care
Dry Mouth Relief Market
Oral Care
Oral Care Market
Oral Care
Herbal Toothpaste Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Us Oral Care Market
Oral Care
Herbal Toothcare Market
Oral Care
Japan Oral Hygiene Market