
 Us Oral Care Market | 2026-2036
Us Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Us Oral Care Market Outlook
Pharmacy and grocery shelf space allocation is reconfiguring as oral care brands compete for premium positioning alongside private-label expansion. Colgate-Palmolive Company leverages its manufacturing scale to dominate traditional retail channels, while Procter & Gamble sustains R&D intensity across whitening and sensitivity formulations. Haleon anchors the therapeutic segment with clinically positioned products, and Church & Dwight Co., Inc. differentiates through natural and baking soda-based alternatives.
US oral care encompasses consumer products designed for dental hygiene maintenance, including formulations containing abrasives, humectants, surfactants, and active ingredients such as fluoride or potassium nitrate manufactured through emulsion-based processes or gel suspension systems. Toothpaste occupies the largest value share within the product type dimension, while whitening formulations command premium pricing relative to standard fluoride variants. Adults generate the dominant revenue stream among end users, though orthodontic patients represent a specialized growth corridor driven by aligner and braces maintenance protocols.
FDA oversight of anticaries drug claims and cosmetic safety substantiation shapes product labeling and active ingredient thresholds across the category. The FTC monitors advertising claims for whitening efficacy and enamel protection, creating compliance costs that favor established manufacturers with regulatory infrastructure. Stakeholders must monitor evolving state-level chemical disclosure requirements and ingredient transparency mandates that could reshape formulation strategies and packaging specifications.
Market Dynamics
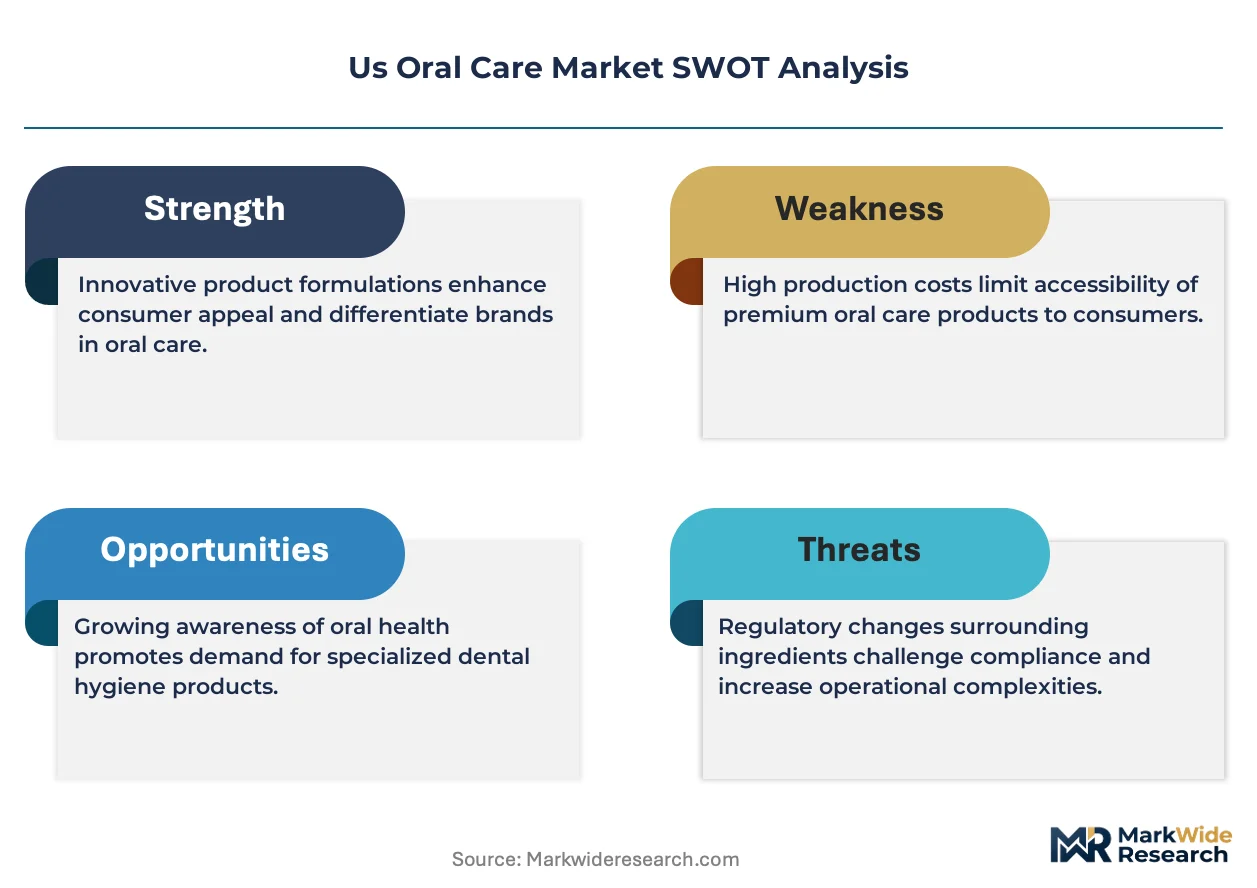
Pharmacy shelf space reconfiguration is compressing margins for mid-tier oral care brands as private-label penetration accelerates and premium positioning demands heavier trade spend. FDA monograph revisions for anticaries drug claims are forcing reformulation cycles that favor manufacturers with dedicated regulatory infrastructure.
Growth Catalysts
- Orthodontic patient protocols:Aligner and braces maintenance regimens are expanding specialized product demand among dental practices. This end-use channel requires distinct formulations for appliance cleaning and enamel protection.
- California chemical disclosure mandates:State-level ingredient transparency requirements are accelerating clean-label innovation cycles. Formulators are preemptively redesigning packaging specifications to satisfy disclosure thresholds.
- Potassium nitrate suspension technology:Advanced gel systems for sensitivity relief are improving therapeutic efficacy claims. Dental clinics are adopting these formulations for post-procedure patient protocols.
Market Restraints
- Sorbitol supply concentration:Humectant sourcing depends heavily on corn-derived supply chains concentrated in Midwest agricultural processing. Price volatility in feedstock commodities transmits directly to formulation costs.
- FDA cosmetic-drug boundary friction:Whitening efficacy claims trigger OTC drug classification, extending approval timelines. This regulatory uncertainty constrains marketing language for enamel-safe positioning.
- Fluoride concentration ceilings:Monograph limits on active ingredient thresholds cap therapeutic differentiation. Manufacturers cannot exceed established ppm levels regardless of clinical evidence.
Strategic Opportunities
- Texas and Arizona expansion corridors:Sun Belt population migration is creating underpenetrated demand pockets outside coastal consumption clusters. Distribution infrastructure investments in these states are yielding first-mover shelf positioning.
- Subscription direct-to-consumer channels:Replenishment automation for brush heads and specialty pastes is bypassing traditional retail markup structures. This channel innovation captures recurring revenue with reduced trade spend.
- Biomimetic enamel repair formulations:Convergence of hydroxyapatite research and nanotechnology delivery systems is opening premium positioning above standard fluoride variants. Dental practices are piloting these for high-value patient segments.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise combining emulsion stability with active ingredient bioavailability is concentrated among retiring specialists. Recruitment pipelines from materials science programs remain underdeveloped.
- ISO 11609 compliance timelines:Abrasivity testing and enamel safety certification requirements are extending product development cycles. Smaller manufacturers lack in-house testing infrastructure to parallelize validation.
- Legacy ERP integration friction:Batch record systems for pharmaceutical-grade oral care production are incompatible with modern demand-planning software. Facility upgrades require simultaneous process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Us Oral Care Market |
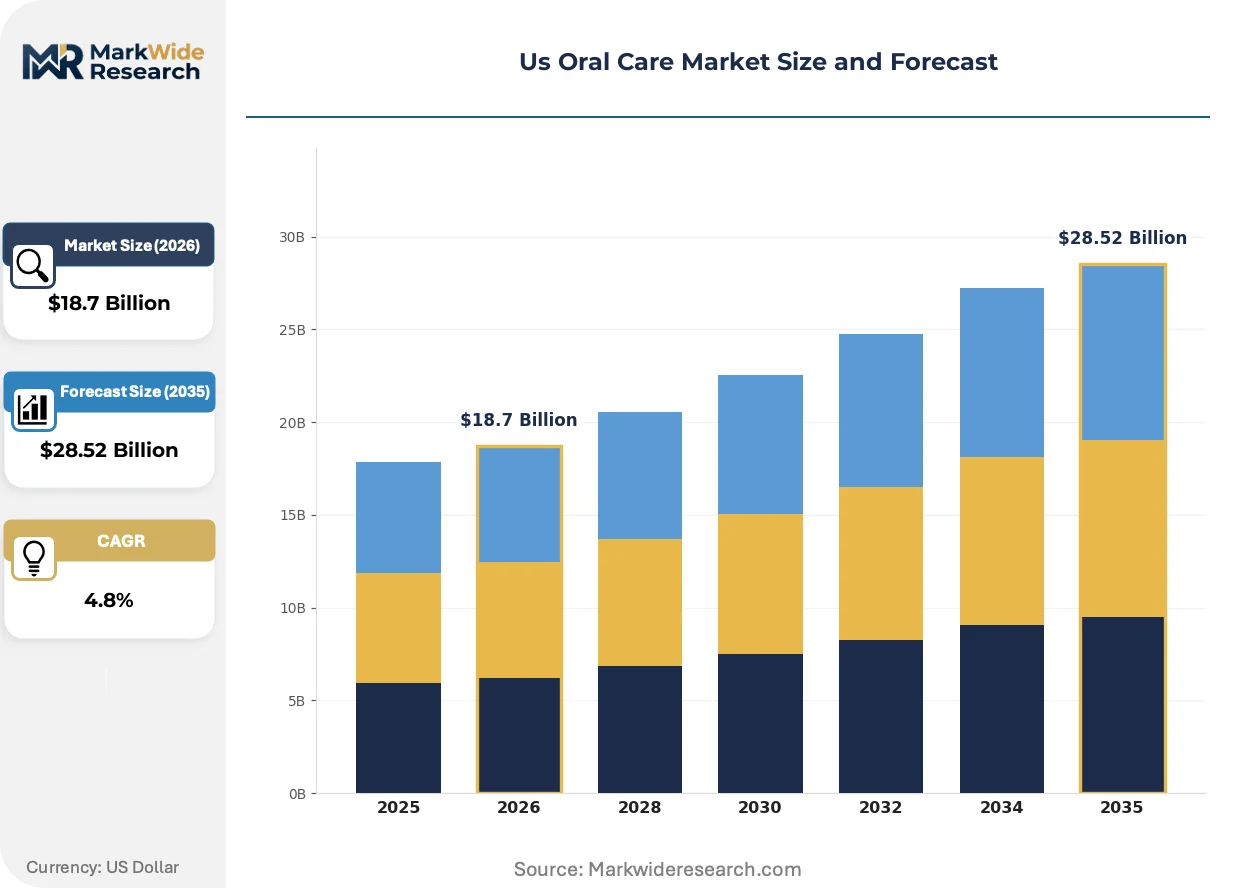
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Floss, Whiteners End User: Adults, Children, Seniors, Orthodontic Patients Distribution Channel: Supermarkets, Online Retailers, Pharmacies, Specialty Stores Formulation: Fluoride, Herbal, Natural, Whitening |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble, Church & Dwight Co., Inc., Unilever plc, Johnson & Johnson, Haleon, Koninklijke Philips N.V., Perrigo Company plc, Sunstar Suisse S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Us Oral Care Market Strategic Shifts
Smart dispensing systems and AI-powered personalization are collapsing traditional segmentation assumptions, while regulatory pressure on sustainability claims is rewriting packaging specifications across the category.
Hydroxyapatite-based remineralization technology is collapsing the boundary between cosmetic and therapeutic oral care classifications. Dental clinics in California and New York are adopting these formulations for patient protocols previously reserved for prescription fluoride. The structural consequence is compression of premium pricing tiers as clinical efficacy claims become achievable without drug classification.
FTC substantiation requirements for whitening advertising are tightening enforcement against before-and-after imagery without clinical trial backing. This policy shift is elevating compliance costs disproportionately for challenger brands lacking dedicated legal infrastructure. The direct-to-consumer segment is responding by shifting marketing spend toward ingredient transparency narratives rather than efficacy promises.
Buyer concentration among retail pharmacy chains is consolidating shelf access negotiations into quarterly category reviews with centralized procurement teams. Independent oral care brands are losing facings as CVS Health and Walgreens Boots Alliance prioritize private-label and exclusive national brand arrangements. This pattern is most visible in Florida and Illinois, where chain penetration exceeds independent pharmacy density by the widest margins.
Us Oral Care Market Segmentation
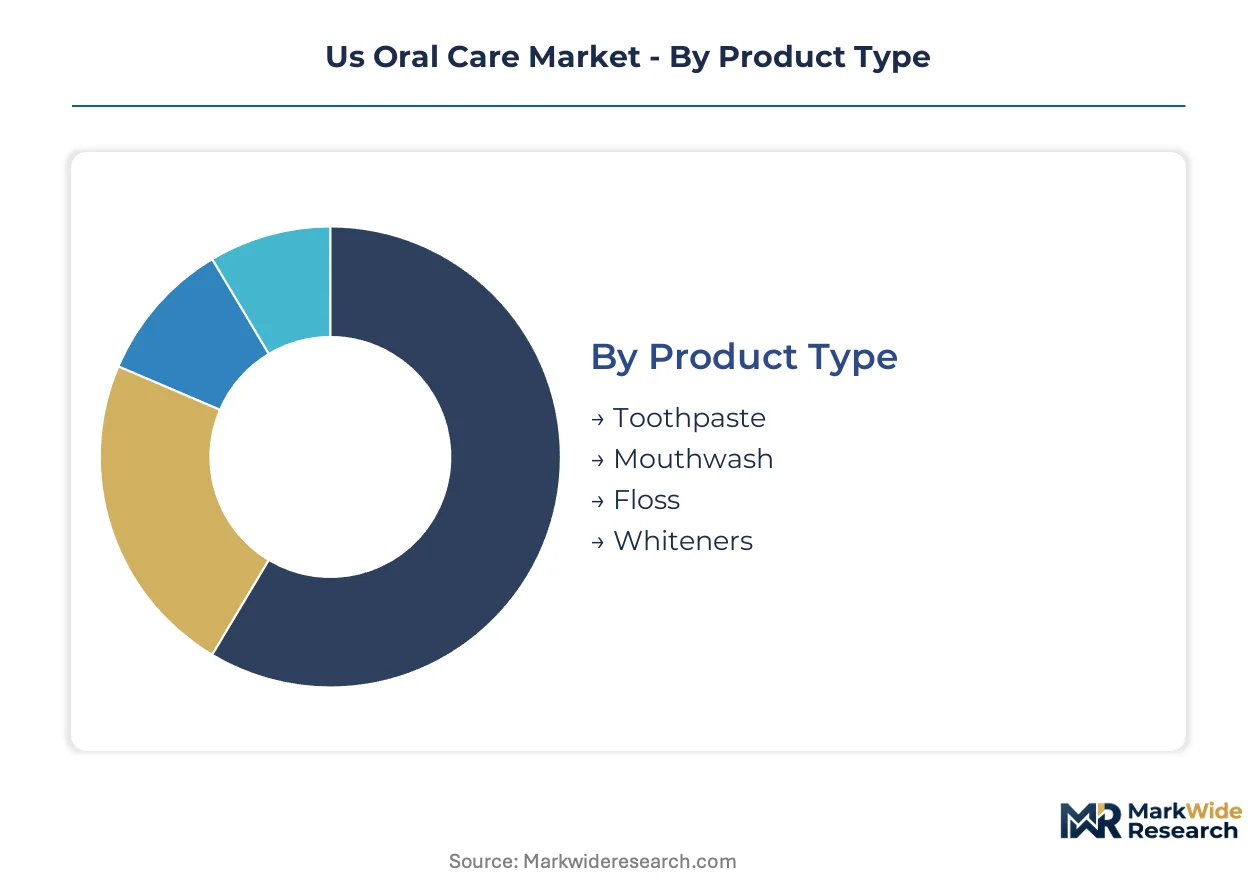
Oral care segmentation reveals divergent service intensity requirements across patient protocols and retail environments. Product positioning must align with distinct regulatory thresholds, formulation stability demands, and channel-specific replenishment cycles.
Product Type:
After-sales engagement varies sharply across product formats, with appliance-dependent categories requiring instructional support and consumable formats demanding subscription infrastructure.
- Toothpaste:Emulsion-based formulations containing abrasives, humectants, and surfactants dominate pharmacy and grocery shelf allocation. Demand concentrates among adults seeking daily anticaries maintenance, with California and New York retail clusters absorbing premium fluoride and whitening variants. FDA monograph compliance for active ingredient thresholds shapes manufacturer R&D allocation.
- Whiteners:Gel suspension systems with peroxide or non-peroxide active agents command specialized dispensing protocols. Dental clinics in Florida are adopting these for patient take-home regimens, though FTC substantiation requirements for efficacy claims elevate compliance costs relative to standard cosmetic classifications.
- Mouthwash:Antiseptic and cosmetic rinses serve pre-procedure protocols and daily hygiene adjunct roles.
- Floss:String and tape formats address interdental cleaning compliance gaps identified in clinical assessments.
Toothpaste holds the largest share; momentum sits with Whiteners as professional-channel adoption accelerates.
End User:
Patient lifecycle stage determines formulation sensitivity requirements and purchase decision authority structures.
- Adults:The primary revenue base encompasses standard maintenance, sensitivity management, and aesthetic enhancement needs. Urban coastal states generate disproportionate volume for premium-positioned variants, with workplace appearance consciousness driving whitening product trial rates.
- Orthodontic Patients:Aligner and braces maintenance protocols require specialized appliance cleaning formulations and enamel protection systems. Dental practices in Texas are expanding dedicated product dispensing for this segment as aligner therapy adoption climbs.
- Children:Flavor-optimized, lower-abrasivity formulations address compliance challenges in early hygiene habit formation.
- Seniors:Dry mouth and recession-related sensitivity drive demand for therapeutic-positioned variants with modified surfactant profiles.
Adults represent the dominant value pool; Orthodontic Patients are gaining share fastest as appliance therapy expands.
Distribution Channel:
Channel selection determines margin structure, with direct-to-consumer formats capturing recurring revenue through subscription automation.
- Pharmacies:CVS Health and Walgreens Boots Alliance centralized procurement teams conduct quarterly category reviews, compressing independent brand facings. Florida and Illinois exhibit the steepest chain penetration advantages, where private-label expansion accelerates.
- Online Retailers:Subscription automation for brush head and specialty paste replenishment bypasses traditional retail markup structures. Arizona and Texas sun belt migration corridors show strongest direct-to-consumer adoption as distribution infrastructure investments mature.
- Supermarkets:Mass-market volume depends on trade spend intensity for endcap positioning and promotional calendar access.
- Specialty Stores:Curated natural and premium assortments serve ingredient-transparency-motivated purchasers.
Pharmacies retain the greatest volume concentration; Online Retailers are climbing the fastest as replenishment automation scales.
Formulation:
Active ingredient classification governs regulatory pathway and marketing claim permissibility, with drug-cosmetic boundary determinations shaping commercial strategy.
- Fluoride:Anticaries drug monograph compliance enables therapeutic claims, though concentration ceilings cap differentiation potential. Midwest manufacturing clusters supply the bulk of active ingredient volume, with corn-derived sorbitol humectant integration creating feedstock cost exposure.
- Natural:Baking soda and plant-derived alternatives appeal to chemical disclosure-motivated purchasers. California state-level transparency mandates are accelerating clean-label packaging redesign cycles among formulators seeking preemptive compliance.
- Whitening:Peroxide and alternative active systems trigger OTC drug classification when efficacy claims exceed cosmetic thresholds.
- Herbal:Botanical extract formulations occupy niche positioning between conventional and natural categorizations.
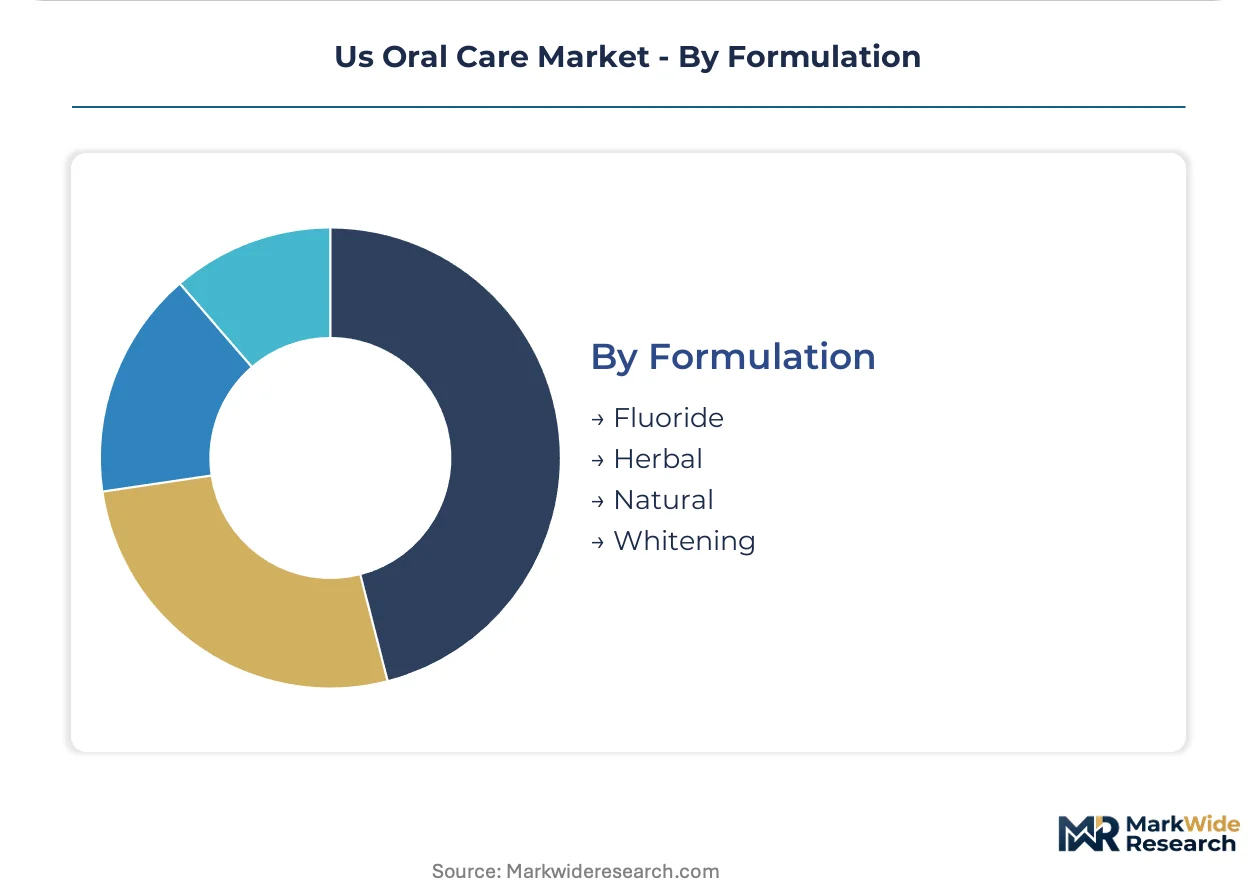
Fluoride formulations anchor volume; Natural variants show the steepest expansion trajectory as disclosure mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in California and New York retail corridors, while Texas and Arizona absorb volume growth at compressed margin structures. FDA monograph enforcement and state-level chemical disclosure mandates create divergent compliance cost burdens across metropolitan markets. Sun Belt population migration is redistributing demand toward underpenetrated distribution infrastructure.
California
Workplace appearance consciousness and aligner therapy adoption drive premium whitening and sensitivity product demand in Los Angeles and San Francisco clusters. The state's Proposition 65 chemical disclosure requirements are accelerating clean-label packaging redesign cycles among formulators. San Diego dental practices are piloting hydroxyapatite-based remineralization protocols for high-value patient segments.
New York
Urban professional density sustains demand for aesthetic-focused oral care regimens and subscription replenishment services. FDA OTC drug monograph compliance costs elevate barriers for challenger brands seeking shelf placement in Manhattan pharmacy chains. Buffalo and Rochester manufacturing facilities supply fluoride active ingredients to northeastern retail networks.
Texas
Orthodontic patient volumes are climbing fastest in Dallas-Fort Worth and Houston as aligner therapy penetration expands. The state lacks California-grade chemical disclosure mandates, reducing packaging compliance costs for natural-formulation entrants. Austin direct-to-consumer brands are capturing subscription revenue with reduced trade spend versus coastal retail channels.
Florida
Retiree concentration generates disproportionate demand for dry mouth and recession-related sensitivity formulations. CVS Health and Walgreens Boots Alliance centralized procurement teams conduct quarterly category reviews that compress independent brand facings. Miami dental clinics are expanding professional-channel dispensing for whitening take-home regimens.
Arizona
Sun Belt inbound migration is creating first-mover shelf positioning opportunities as distribution infrastructure investments mature. Online retailer subscription automation for brush head and specialty paste replenishment shows strongest adoption rates in Phoenix and Tucson corridors. The state represents a testbed for bypassing traditional retail markup structures through direct-to-consumer channel innovation.
Us Oral Care Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in active ingredient and packaging supply. The vendor base organizes around three tiers: multinational consumer goods conglomerates with regulatory infrastructure, mid-cap therapeutic specialists with dental channel relationships, and challenger brands exploiting direct-to-consumer subscription mechanics. Competitive moves concentrate on portfolio diversification into natural-positioned variants and geographic expansion through sun belt distribution infrastructure investments.
Among the multinational tier, Colgate-Palmolive Company and Procter & Gamble exemplify scale-driven platform integrators with manufacturing footprint advantages. Haleon occupies a position within the therapeutic specialist archetype, leveraging clinically positioned formulations for dental practice channels. Church & Dwight Co., Inc. represents the natural-formulation vector, differentiating through baking soda-based alternatives and preemptive compliance with chemical disclosure mandates.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble |
| Church & Dwight Co., Inc. |
| Unilever plc |
| Johnson & Johnson |
| Haleon |
| Koninklijke Philips N.V. |
| Perrigo Company plc |
| Sunstar Suisse S.A. |
| Others |
Value Chain & Pricing Dynamics
Midwest agricultural processing clusters around Decatur, Illinois and Cedar Rapids, Iowa concentrate sorbitol humectant production, transmitting corn feedstock volatility directly into oral care formulation costs and compressing margin flexibility for manufacturers lacking long-term supply contracts.
Pricing Analysis
The customization-premium spread between standard fluoride toothpaste and specialized orthodontic or sensitivity formulations spans three distinct pricing tiers. Certification-grade differentiation through FDA monograph compliance and ISO 11609 abrasivity testing anchors premium positioning, while private-label expansion in CVS Health and Walgreens Boots Alliance networks intensifies cost compression at the economy tier. Orthodontic patients and aligner therapy users show lowest price sensitivity due to protocol-driven purchase authority, whereas mass-market adults in Sun Belt migration corridors exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with Colgate-Palmolive and Procter & Gamble captive production facilities in New Jersey and Ohio, supplemented by third-party processors serving mid-tier natural-formulation brands. Active ingredient sourcing draws from domestic fluoride chemical processors and imported potassium nitrate suppliers, with packaging materials feeding from Midwest paperboard and plastics converters. Single-source vulnerability in corn-derived sorbitol supply chains creates exposure to agricultural commodity cycles. Distribution runs through centralized pharmacy chain distribution centers before final-mile deployment to retail shelves.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment automation and dental practice dispensing protocols are collapsing traditional retail platform economics, creating interoperability demands between direct-to-consumer software stacks and professional-channel inventory systems.
For Market Incumbents: Build regulatory infrastructure moats by accelerating FDA monograph pre-submission investments ahead of anticipated whitening efficacy claim tightening. Deepen backward integration into sorbitol supply through captive agricultural processing partnerships or long-term offtake agreements with Midwest cooperatives. Channel control investments in Texas and Arizona distribution infrastructure defend against Sun Belt challenger brands. For New Entrants and Emerging Players: Arizona and Texas direct-to-consumer subscription corridors represent the most penetrable entry points, bypassing CVS Health and Walgreens Boots Alliance shelf access barriers. Natural-formulation positioning with preemptive California Proposition 65 compliance enables coastal market access without legacy reformulation cycles. Go-to-market execution through dental practice dispensing partnerships captures orthodontic patient protocol adherence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors therapeutic specialists with hydroxyapatite remineralization pipelines and established dental clinic relationships. Five-to-ten year viability hinges on clinical efficacy claim substantiation infrastructure rather than brand equity alone. Acquisition target archetypes include mid-cap formulators with ISO 11609 in-house testing capabilities and existing professional-channel sales organizations. Watch FDA cosmetic-drug boundary enforcement intensity as inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses CVS Health and Walgreens Boots Alliance shelf access negotiations in Arizona and Texas corridors. |
| Professional Channel Expansion | Dental practice dispensing protocols capture orthodontic patient volume with protocol-driven repurchase cycles. |
| Clean-Label Packaging Redesign | Preemptive California Proposition 65 compliance accelerates market access ahead of disclosure mandate enforcement. |
| Hydroxyapatite Formulation Development | Collapses cosmetic-therapeutic boundary without FDA drug classification timelines or concentration ceilings. |
| Sun Belt Distribution Infrastructure | First-mover shelf positioning in Texas and Arizona captures inbound migration demand outside coastal clusters. |
Study Parameters
A spread of perspectives from brand managers at multinational consumer goods conglomerates, category buyers at CVS Health and Walgreens Boots Alliance procurement teams, dental practice dispensing coordinators, and formulation chemists at contract manufacturers converged on the working assumptions underlying demand projections. Secondary validation drew from FDA OTC drug monograph filings, FTC advertising substantiation enforcement records, Nielsen retail audit data, and state-level chemical disclosure regulatory texts. Bottom-up product-format volume builds triangulated against top-down category spending estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling patient population growth, aligner therapy adoption curves, and subscription replenishment automation penetration against Midwest sorbitol production capacity and packaging material converter throughput. Segmentation dimensions included product type, end user lifecycle stage, distribution channel format, and formulation active ingredient classification. CAGRs were derived from regression analysis of historical volume trends projected through demographic and regulatory scenario weighting. Industry-specific inputs encompassed orthodontic patient protocol compliance rates and direct-to-consumer customer acquisition cost trajectories.
Practitioners should monitor FDA monograph revision timelines, California chemical disclosure mandate expansion patterns, and corn futures price volatility for early signals of forecast deviation. Forecasts reflect assumptions regarding stable regulatory enforcement intensity and uninterrupted agricultural feedstock supply. Quarterly review of pharmacy chain procurement centralization indicators and Sun Belt population migration statistics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Oral Thrush Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Mouth Spray Market
Oral Care
Children's Oral Care Market
Oral Care
Oral Antiseptics Market
Oral Care
Mouthwash Market
Oral Care
Oral Mucositis Market
Oral Care
BRICS Oral Care Market
Oral Care
Global Oral Care Products Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Kids Oral Care Products Market
Oral Care
Antiseptic Mouthwash Market