
 Bluetooth Hearing Aids Market | 2026-2036
Bluetooth Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Hearing Aids Market Analysis
Aftermarket service revenue is narrowing as manufacturers bundle remote fitting and firmware updates into initial device purchases. Sonova leverages its integrated audiology care network to capture lifetime value across software-enabled adjustments. WS Audiology sustains competitive pressure through manufacturing scale across European and Asian production facilities. Starkey Laboratories anchors its position in the United States through in-house semiconductor development for proprietary wireless protocols.
Bluetooth hearing aids combine low-energy radio transceivers with digital signal processors to stream audio directly from smartphones and televisions while applying real-time frequency compression algorithms for sensorineural loss compensation. Behind-the-Ear configurations dominate unit volume due to battery capacity advantages that support sustained Bluetooth streaming, while Completely-in-Canal designs command premium positioning among cosmetic-conscious adult users. Direct Streaming technology leads feature differentiation as interoperability with iOS and Android ecosystems becomes a baseline purchase criterion, whereas Rechargeable systems represent the fastest-growing technology sub-segment as lithium-ion cell miniaturization eliminates disposable battery dependency.
The FDA's OTC hearing aid classification and the EU Medical Device Regulation impose divergent safety and electromagnetic compatibility requirements that fragment product certification pathways across Atlantic markets. CE marking under MDR mandates clinical performance documentation for Bluetooth-enabled devices sold in European Economic Area countries, while the FCC governs radio frequency emissions for United States commercialization. Stakeholders must monitor evolving interoperability standards between hearing aid firmware and consumer electronics operating systems to anticipate platform-dependent demand shifts.
Market Dynamics
The FDA's over-the-counter hearing aid rule is compressing traditional audiology channel control while simultaneously expanding addressable demand among mild-to-moderate hearing loss consumers who previously bypassed clinical fitting pathways.
Growth Catalysts
- Elderly Demographics:Aging populations in Germany, Japan, and the United States are generating sustained replacement demand for connected hearing solutions with smartphone interoperability.
- CE Marking under MDR:The EU Medical Device Regulation's clinical performance documentation requirements are accelerating firmware sophistication among manufacturers seeking European Economic Area access.
- Lithium-Ion Miniaturization:Rechargeable cell technology is eliminating disposable battery dependency and reducing total cost of ownership for daily Bluetooth streaming users.
Market Restraints
- Semiconductor Supply Concentration:Proprietary wireless protocol chips face fabrication bottlenecks concentrated among Asian foundry networks, creating lead time vulnerability.
- Electromagnetic Compatibility Testing:Divergent FCC and CE marking radio frequency emission standards impose redundant certification costs that fragment product development resources.
- Direct-to-Consumer Substitution:Personal Sound Amplification Products (PSAPs) are capturing price-sensitive demand at entry-level price points below regulated hearing aid thresholds.
Strategic Opportunities
- German Reimbursement Frameworks:Statutory health insurance coverage for Bluetooth-enabled devices creates premium pricing headroom unmatched in out-of-pocket markets.
- Telehealth Integration:Remote fitting platforms are enabling manufacturers to capture recurring software adjustment revenue previously retained by independent audiologists.
- Android and iOS Convergence:Direct Streaming interoperability standards are creating platform-agnostic device categories that expand beyond legacy proprietary ecosystem lock-in.
Industry Challenges
- Firmware-Audiologist Skill Gap:Clinical professionals require retraining on software-enabled fitting interfaces that displace traditional hardware programming tools.
- MDR Clinical Documentation Timelines:European Economic Area market entry now requires 12-18 month performance validation cycles that compress product launch windows.
- Legacy Analog System Integration:Healthcare facilities with installed base telecoil infrastructure face capital expenditure burdens to support simultaneous Bluetooth and inductive loop compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Hearing Aids Market |
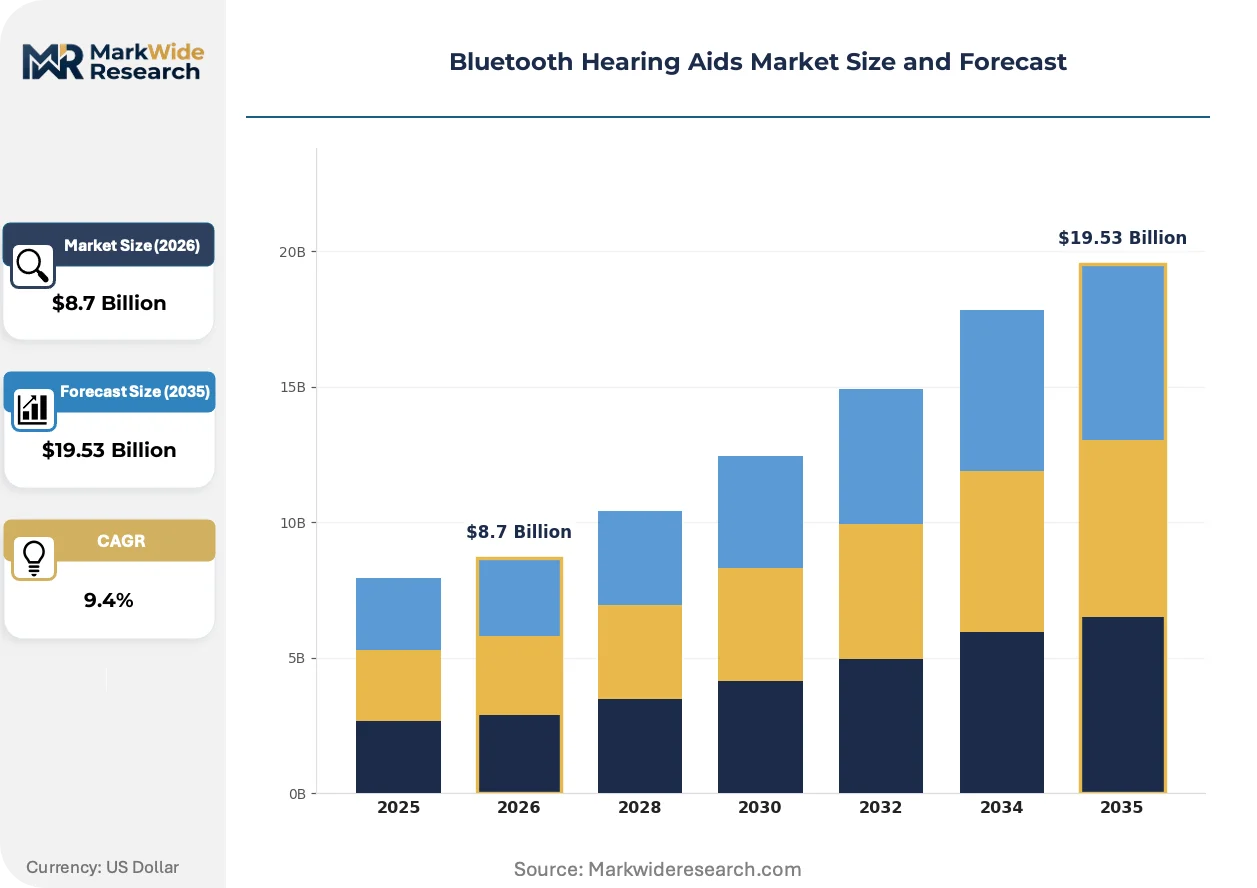
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Receiver-in-Canal, Behind-the-Ear, Completely-in-Canal, Open-Fit Technology: Direct Streaming, Noise Reduction, Rechargeable, Voice Assistance End User: Adults, Elderly, Pediatric, Professional Users Distribution Channel: Online Retail, Audiology Clinics, Pharmacies, Hospitals |
| Companies Covered | Sonova, WS Audiology, Demant A/S, GN Store Nord A/S, Starkey Laboratories, Phonak, Jabra, Eargo, Oticon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Hearing Aids Market Emerging Trajectories
Audio processing architectures are converging with consumer electronics platform standards, collapsing the historical separation between medical device firmware and smartphone operating system ecosystems.
Artificial intelligence-driven noise suppression algorithms are migrating from cloud-dependent processing to on-device neural inference engines. Adult users with active professional lifestyles are adopting these capabilities at accelerated replacement cycles. This shift is compressing competitive differentiation timelines as firmware updates rather than hardware generations deliver perceptible performance gains.
The FDA's over-the-counter classification framework is dismantling state-level dispensing licensure barriers that previously restricted device access to audiologist channels. Manufacturers are redirecting commercial investment toward direct-to-consumer marketing infrastructure. Mild-to-moderate hearing loss segments in the United States are responding with purchase trial rates previously suppressed by clinical appointment friction.
Subscription-based firmware feature unlocking is displacing single-transaction device economics among premium-tier buyers. Channel partners with audiology care networks are bundling remote adjustment services into recurring membership structures. Germany and the Netherlands exhibit the strongest consumer uptake of this model where statutory reimbursement partially covers ongoing service costs.
Bluetooth Hearing Aids Market Segmentation
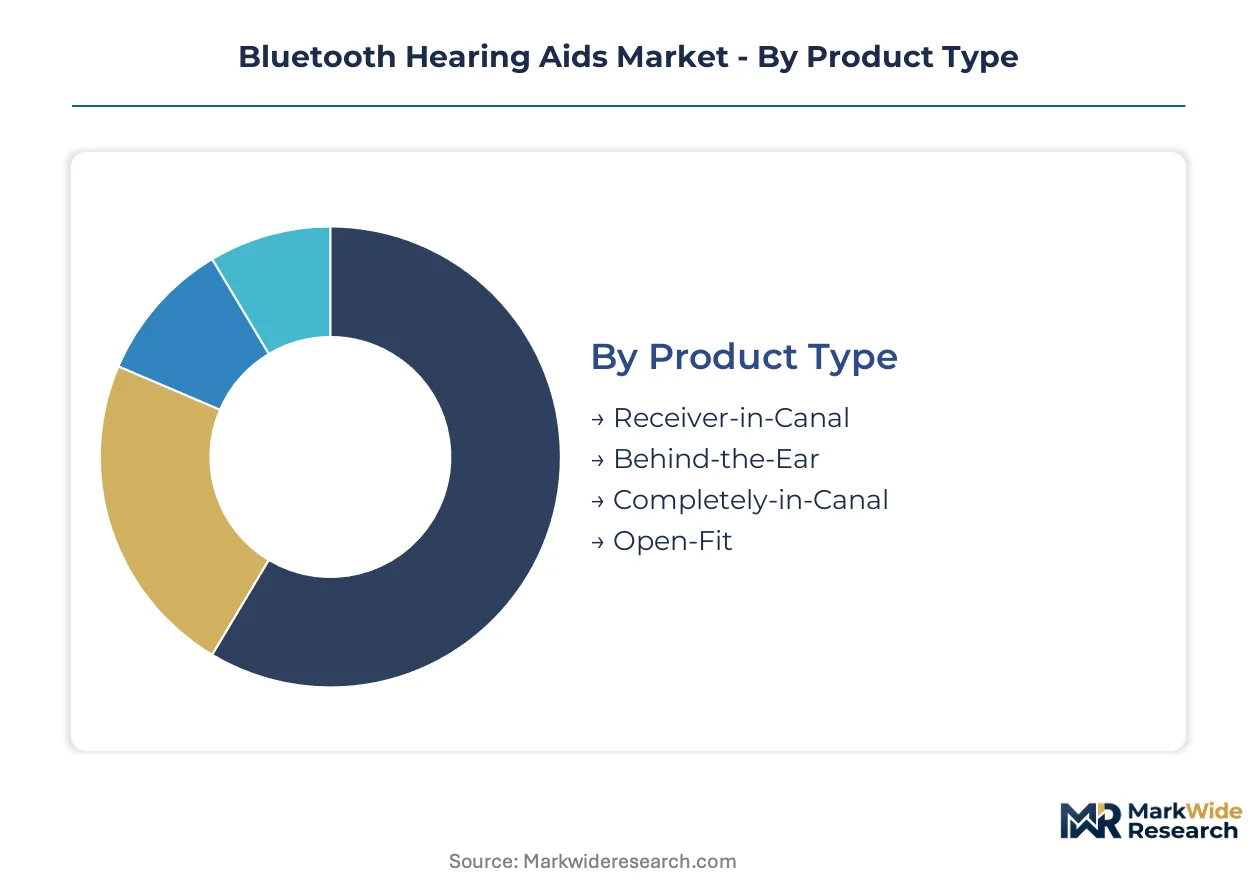
Bluetooth hearing aids fragment across device architecture, processing capabilities, user demographics, and procurement pathways. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Cost tier differentiation separates battery-intensive configurations from cosmetic-optimized miniaturized designs.
- Behind-the-Ear:Larger housing accommodates dual-microphone arrays and extended-capacity lithium-ion cells for all-day Bluetooth streaming. Germany's statutory reimbursement frameworks favor this configuration for elderly beneficiaries requiring sustained connectivity.
- Completely-in-Canal:Deep insertion placement demands custom shell fabrication and reduced antenna efficiency, limiting streaming range. Adult professionals in the United States select this segment for workplace discretion despite shorter battery cycles.
- Receiver-in-Canal:Hybrid architecture splits processor and receiver components for moderate occlusion with amplified output.
- Open-Fit:Thin tubing preserves natural low-frequency resonance for mild high-frequency loss profiles.
Behind-the-Ear commands the established base. The steepest expansion runs through Completely-in-Canal.
Technology:
Application utility determines firmware investment priority across audio processing and power management domains.
- Direct Streaming:Low-energy radio transceivers enable bidirectional audio transmission from iOS and Android hosts without intermediate relay devices. FDA OTC classification in the United States accelerates consumer expectation for seamless smartphone interoperability.
- Rechargeable:Lithium-ion cell miniaturization eliminates zinc-air battery dependency while supporting 16-24 hour streaming endurance. Dutch and German users exhibit strongest uptake where electricity costs remain below disposable battery replacement economics.
- Noise Reduction:Multi-band compression algorithms attenuate competing signals in reverberant environments.
- Voice Assistance:Embedded wake-word detection enables hands-free digital assistant invocation.
Direct Streaming anchors current procurement specifications. Rechargeable systems are climbing the fastest as cell chemistry advances.
End User:
Customer type segmentation aligns clinical indication severity with lifestyle connectivity demands.
- Elderly:Age-related sensorineural degeneration drives replacement cycles for connected solutions with simplified smartphone interfaces. Japan's super-aged demographic sustains premium pricing tolerance for telehealth-integrated fitting services.
- Adults:Occupational noise exposure and early-onset genetic factors generate demand for discreet multi-environment processing. United States workplace accommodation mandates under ADA provisions expand employer-subsidized procurement.
- Pediatric:Congenital or early childhood onset requires tamper-resistant battery enclosures and school-compatible FM system integration.
- Professional Users:Musicians and broadcast technicians demand extended frequency response beyond standard speech bandwidth.
Elderly users anchor volume concentration. Adult segments are gaining share fastest as OTC channels reduce clinical friction.
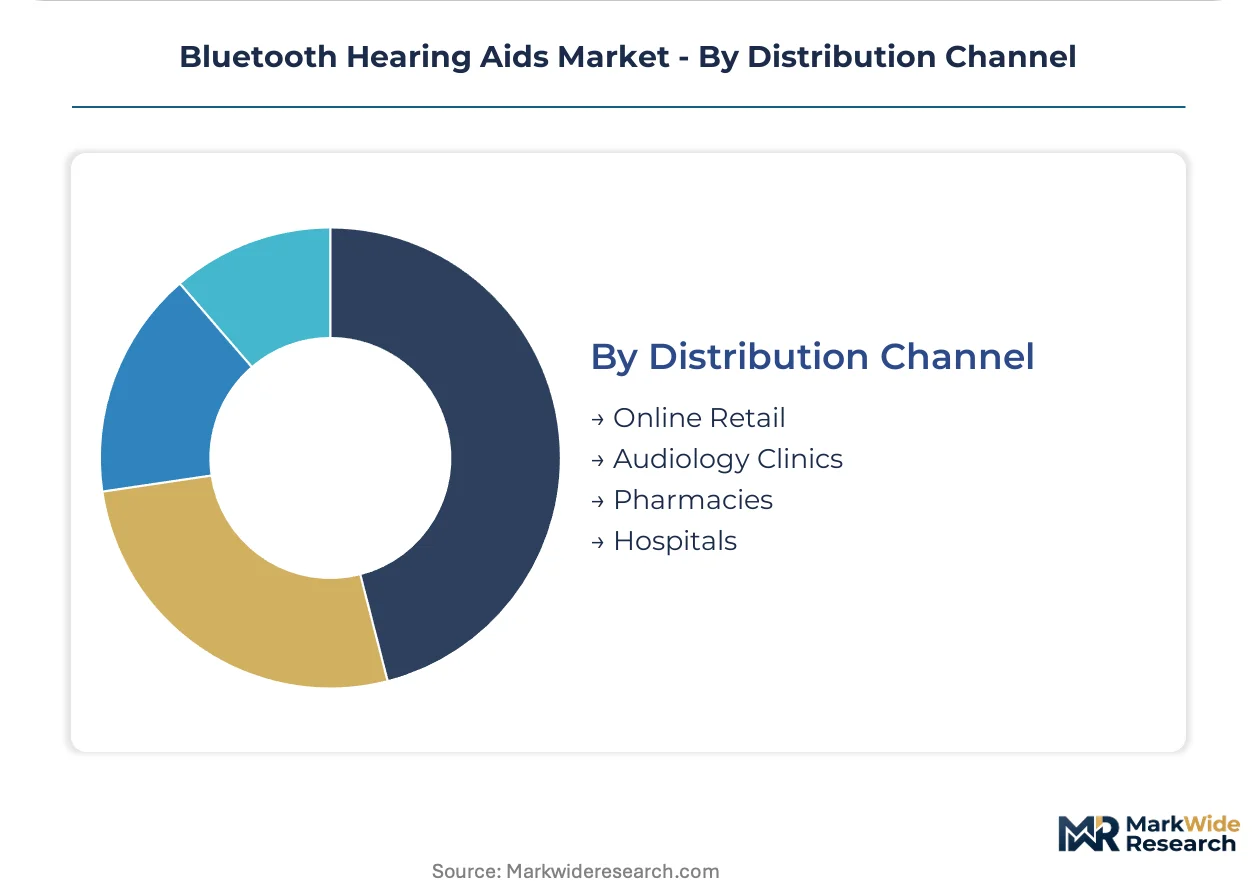
Distribution Channel:
Volume concentration shifts as regulatory frameworks restructure access pathways between clinical and direct-to-consumer procurement.
- Audiology Clinics:Professional fitting services bundle real-ear measurement verification with software-enabled adjustment protocols. CE marking under MDR preserves clinical channel relevance in European Economic Area markets requiring performance documentation.
- Online Retail:Direct-to-consumer platforms capture mild-to-moderate loss segments previously excluded by appointment availability constraints. United States FDA OTC implementation enables manufacturer-controlled digital marketing investment.
- Pharmacies:Retail health infrastructure provides physical touchpoints for device demonstration and basic troubleshooting.
- Hospitals:Otolaryngology departments coordinate acute intervention with post-surgical amplification fitting.
Audiology Clinics retain the established base. Online Retail is expanding most quickly as regulatory barriers dismantle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German buyers exhibit the lowest elasticity due to statutory reimbursement, while United States consumers face the highest out-of-pocket exposure under fragmented insurance coverage.
United States
Elderly Medicare beneficiaries drive replacement demand for smartphone-integrated devices. The FDA's over-the-counter hearing aid rule dismantled state-level dispensing barriers, redirecting manufacturer investment toward direct-to-consumer channels. Minneapolis-St. Paul anchors domestic audiology infrastructure with dense clinic networks supporting telehealth-integrated fitting services.
Germany
Statutory health insurance coverage eliminates cost barriers for connected hearing solutions among aging beneficiaries. CE marking under MDR mandates clinical performance documentation, preserving audiology clinic relevance against direct-to-consumer substitution. Berlin and Munich concentrate reimbursement administration and manufacturer regional headquarters.
Japan
Super-aged demographic structure sustains premium pricing tolerance for telehealth-enabled devices. METI guidelines on medical device software updates shape firmware development timelines for domestic market entry. Tokyo-Osaka corridor hosts the densest audiology specialist concentration in Asia-Pacific.
Netherlands
Electricity cost economics below disposable battery replacement rates accelerate rechargeable system uptake. The national health insurance system covers Bluetooth-enabled devices with remote adjustment capabilities. Eindhoven's semiconductor ecosystem supplies miniaturized power management components to hearing aid fabricators.
United Kingdom
NHS audiology waiting list pressures push mild-to-moderate loss consumers toward private procurement channels. MHRA post-Brexit regulatory divergence from EU MDR creates parallel certification requirements for manufacturers. London's private healthcare cluster concentrates premium-tier dispensing and fitting services.
Bluetooth Hearing Aids Market Vendor Landscape
Integrated audiology networks and manufacturing-scale specialists split the market into distinct competitive spheres. Consolidation pressures favor players with captive distribution or foundry-scale production cost structures. Three archetypes dominate: vertically integrated care-network operators, semiconductor-capable device specialists, and direct-to-consumer platform builders. M&A activity targets audiology clinic chains and firmware development capabilities, while geographic expansion concentrates on German and Dutch reimbursement markets.
Among integrated care-network operators, Sonova exemplifies the vertical-control archetype through its audiology service infrastructure. WS Audiology occupies the manufacturing-scale position with distributed production across European and Asian facilities. Starkey Laboratories anchors the semiconductor-specialist tier through in-house wireless protocol development. These three represent the strategic poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Sonova |
| WS Audiology |
| Demant A/S |
| GN Store Nord A/S |
| Starkey Laboratories |
| Phonak |
| Jabra |
| Eargo |
| Oticon |
| Others |
Supply Flow & Price Mechanics
Asian foundry undercapacity for Bluetooth Low Energy transceivers is compressing component availability timelines and forcing manufacturers to pre-pay for wafer capacity, which in turn hardens pricing discipline across premium-tier device configurations while squeezing margin flexibility in entry-level segments.
Pricing Analysis
After-sales firmware subscription tiers now anchor lifetime value capture as manufacturers bundle remote adjustment services into recurring membership structures. Three-tier pricing structure across premium, standard, and economy levels separates telehealth-integrated offerings from basic streaming-capable devices and unconnected analog alternatives. Cost compression in the economy tier is intensifying because PSAP substitution threatens entry-level hearing aid demand. Employer-subsidized procurement through ADA workplace mandates exhibits the lowest price sensitivity, while direct-to-consumer OTC purchasers show highest elasticity.
Supply Chain Analysis
Export controls on advanced radio frequency semiconductor fabrication equipment limit capacity expansion at leading-edge nodes in China, constraining Bluetooth transceiver supply growth. Taiwan, South Korea, and Germany concentrate wafer fabrication and precision assembly operations. Lithium-ion cells, MEMS microphones, and custom DSP silicon feed from concentrated Asian supplier networks. Single-source vulnerability in BLE protocol chip fabrication creates lead time exposure. Distribution runs through audiology clinic networks in reimbursement markets and direct-to-consumer platforms in deregulated jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personal Sound Amplification Products represent the most acute substitution threat to regulated hearing aid incumbents, as FDA OTC classification erodes the clinical channel moat that historically protected premium pricing.
For Market Incumbents: Pre-empt PSAP encroachment by acquiring direct-to-consumer platform capabilities and embedding AI-driven noise suppression as baseline firmware rather than premium upsell. Backward integration into lithium-ion cell supply secures power management component availability against Asian foundry allocation constraints. Channel control through captive audiology networks preserves reimbursement market access where statutory coverage sustains pricing power.
For New Entrants and Emerging Players: Mild-to-moderate hearing loss segments in United States OTC channels represent the most penetrable entry point given dismantled state-level dispensing barriers and suppressed clinical appointment friction. Rechargeable Completely-in-Canal configurations targeting workplace discretion demands among adult professionals offer differentiated positioning against legacy Behind-the-Ear dominance. Go-to-market execution should prioritize smartphone-native fitting applications that eliminate audiologist dependency.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across firmware-centric device architectures as software-enabled feature delivery displaces hardware refresh cycles. Five-to-ten year viability favors manufacturers with integrated telehealth platforms and statutory reimbursement relationships rather than pure hardware fabricators. Acquisition targets should demonstrate CE marking completion under MDR and German statutory health insurance inclusion. The signal to watch is OTC channel share capture rates in United States markets as early indicator of platform economics transition.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Captures recurring software adjustment revenue previously retained by independent audiologists. |
| CE Marking Pathway Completion | Preserves European Economic Area market access under MDR clinical documentation mandates. |
| Reimbursement Strategy Development | Unlocks German statutory health insurance coverage for premium Bluetooth-enabled configurations. |
| Firmware Companion Development | Enables AI-driven noise suppression migration from cloud to on-device neural inference engines. |
| Semiconductor Supply Agreement | Secures proprietary wireless protocol chip allocation against Asian foundry capacity constraints. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and statutory health insurance reimbursement schedules preceded structured interviews with audiology clinic operators, biomedical engineers at hearing aid manufacturers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FCC equipment authorization records, customs trade data for lithium-ion cell imports, and CMS Medicare hearing aid utilization statistics. Bottom-up unit shipment estimates triangulated against top-down reimbursement expenditure analysis.
Assumptions held fixed include prevailing FDA OTC classification framework and German statutory coverage levels, while variables tested included iOS-Android interoperability standard evolution and lithium-ion cell chemistry advancement rates. Segmentation modeling spanned device architecture, technology capability tier, end-user demographic, and distribution channel structure across the projection horizon. CAGRs derived from replacement cycle analysis among aging populations and Bluetooth streaming adoption elasticity. Forecast inputs incorporated telehealth integration penetration rates and rechargeable system cost curves.
Practitioners should monitor FDA enforcement discretion on OTC marketing claims and METI software update guideline revisions for early signals of regulatory trajectory shift. Forecasts reflect these documented assumptions regarding reimbursement stability and semiconductor supply normalization. Material shifts in FCC radio frequency allocation or EU MDR clinical evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Contact Lenses Market
Medical Devices
Bone Cement Mixers Market
Medical Devices
Japan Hemostats Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Image-Based Cytometer Market