
 Oral Thin Films Market | 2026-2036
Oral Thin Films Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Thin Films Market Intelligence
Multi-source API procurement is repositioning supply chain economics for film-based drug delivery. Aquestive Therapeutics, Inc. leverages its PharmFilm platform to dominate prescription sublingual segments. ZIM Laboratories Limited anchors Indian manufacturing scale for export markets. IntelGenx Corp. specializes in vertically integrated film casting and printing operations in North America.
Oral thin films are polymeric matrices, typically 50-500 microns thick, that disintegrate on mucosal surfaces to release active pharmaceutical ingredients without water or swallowing. The composition blends hydrophilic polymers like pullulan or hydroxypropyl methylcellulose with plasticizers and APIs through solvent-casting or hot-melt extrusion. Pharmaceutical applications lead the product type landscape due to bioavailability enhancement and dose-precision advantages over conventional tablets. Sublingual delivery mode captures premium positioning through rapid systemic absorption and first-pass metabolism avoidance, while buccal films compete on duration and mucosal adhesion for chronic therapies.
FDA's 505(b)(2) pathway and EMA's centralized marketing authorization shape product development timelines and geographic launch sequencing for film-based reformulations. The EU MDR and REACH compliance requirements elevate barrier-to-entry for polymer suppliers and finished film manufacturers serving European markets. Stakeholders must monitor evolving pharmacopeial monographs for dissolution testing standards and polymer qualification protocols.
Market Dynamics
Reformulation economics under FDA's 505(b)(2) pathway is compressing development timelines and redirecting R&D investment toward film-based delivery platforms that bypass first-pass metabolism.
Growth Catalysts
- Pediatric medication compliance:Sublingual films eliminate choking risks and dosing errors that plague liquid formulations in home care settings. Caregivers in the United States and Germany increasingly request non-invasive alternatives.
- EMA centralized authorization:Streamlined marketing approval across EU member states accelerates cross-border commercialization for buccal film manufacturers. REACH compliance costs are offset by reduced duplicative filings.
- Geriatric polypharmacy management:Thin film formats simplify complex regimens for patients with dysphagia or reduced manual dexterity. Japan's aging demographic concentrates demand for rapid-disintegration products.
Market Restraints
- API stability constraints:Moisture-sensitive active ingredients degrade during solvent-casting processes, limiting candidate selection for film formulations. Hydrolytic instability excludes approximately 40% of small-molecule drugs.
- Polymer supply concentration:Pharmaceutical-grade pullulan production clusters in Japan and China, creating geographic vulnerability for Western manufacturers. Quality audits and import documentation extend lead times.
- Film-to-film substitution:Orally disintegrating tablets and fast-melt granules compete on equivalent convenience with established reimbursement codes. Payers in Germany require incremental clinical evidence for premium coverage.
Strategic Opportunities
- Veterinary oral films:Companion animal medication represents an unserved application where buccal absorption bypasses gastric degradation of sensitive compounds. Regulatory pathways through FDA's Center for Veterinary Medicine remain underutilized.
- Continuous manufacturing integration:Hot-melt extrusion lines coupled with real-time release testing compress batch cycle times from days to hours. This convergence enables on-demand production for personalized dosing.
- Direct-to-pharmacy distribution:Bypassing wholesale intermediaries allows film specialists to capture margin and capture patient adherence data. Independent pharmacy chains in the United States pilot this channel for chronic disease management.
Industry Challenges
- Dissolution method standardization:USP and EP monographs lack harmonized apparatus specifications for mucosal film testing, forcing duplicate validation studies for multi-territory filings.
- Specialized formulation talent:Polymer rheology and mucoadhesion science expertise resides at a handful of contract development organizations, constraining internal R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Thin Films Market |
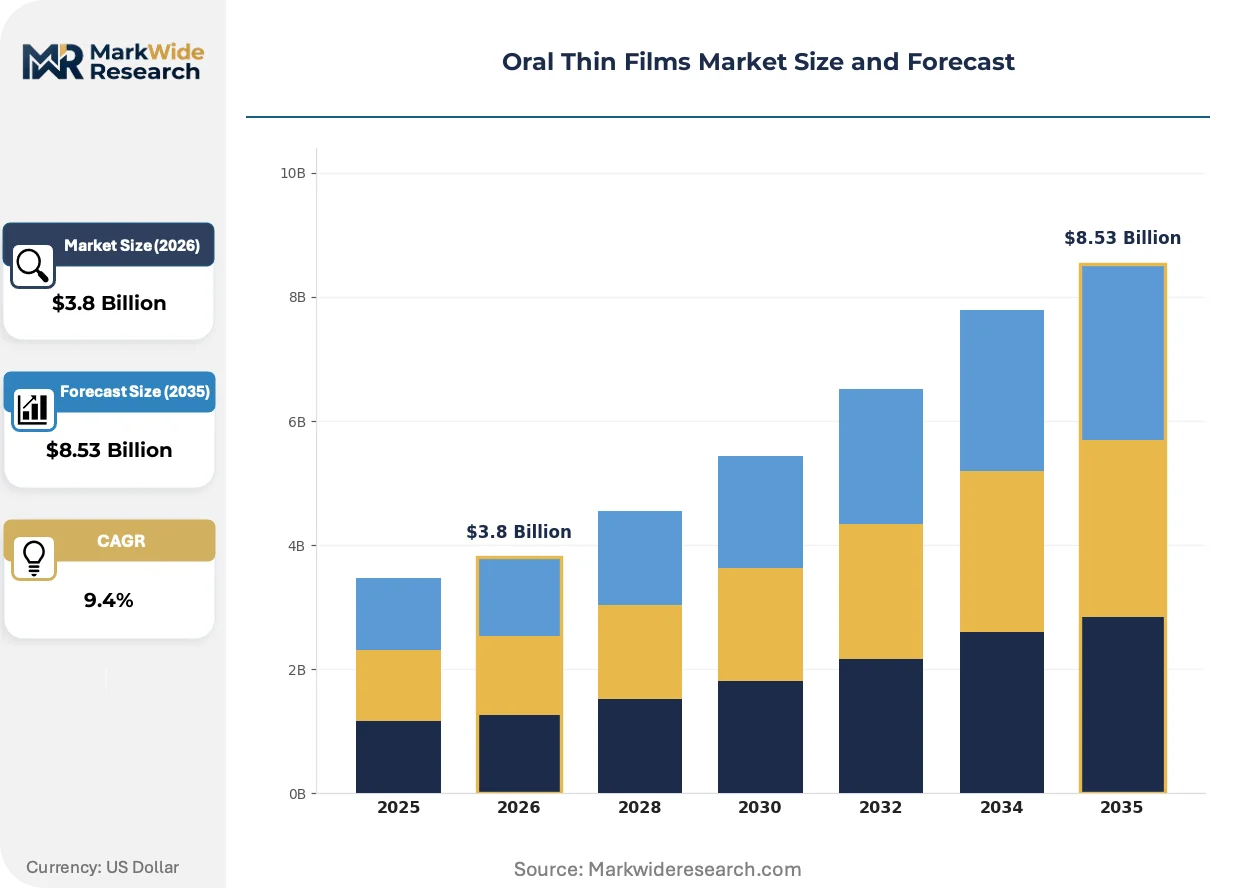
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Nutraceuticals, Disinfectants, Others Therapy Area: Pain Management, Antiemetic, Cognitive Disorders, Hormonal Therapy Delivery Mode: Sublingual, Buccal, Oral, Transmucosal End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Aquestive Therapeutics, Inc., ZIM Laboratories Limited, IntelGenx Corp., C.L. Pharm, Cure Pharmaceutical, LTS Lohmann Therapie-Systeme AG, Indivior plc, Viatris Inc., NAL Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Thin Films Market Strategic Shifts & Innovations
Manufacturing technology and regulatory science are converging to reshape competitive positioning in film-based drug delivery. Three developments warrant particular attention.
Hot-melt extrusion equipment with integrated process analytical technology is modularizing production scale-up for pharmaceutical film manufacturers. Mid-cap CDMOs in North America and Europe adopt these platforms to serve multiple clients without dedicated line changeovers. This modularization collapses minimum viable batch sizes and enables niche therapeutic segments previously excluded by capital intensity.
REACH polymer registration requirements in Europe are elevating documentation burdens for hydroxypropyl methylcellulose suppliers serving pharmaceutical film applications. ECHA's expanded substance evaluation criteria now demand migration studies for residual solvents and plasticizers. Buccal film developers targeting chronic therapy indications face extended qualification timelines as they reformulate to meet evolving safety thresholds.
Hospital formulary committees are consolidating vendor lists for oral thin films around suppliers with demonstrated bioequivalence data packages. Purchasing groups in the United States negotiate multi-year supply agreements that bundle sublingual and buccal variants, displacing spot procurement. This concentration is most pronounced in oncology supportive care, where film-based antiemetics compete for limited therapeutic substitution slots.
Oral Thin Films Market Segmentation
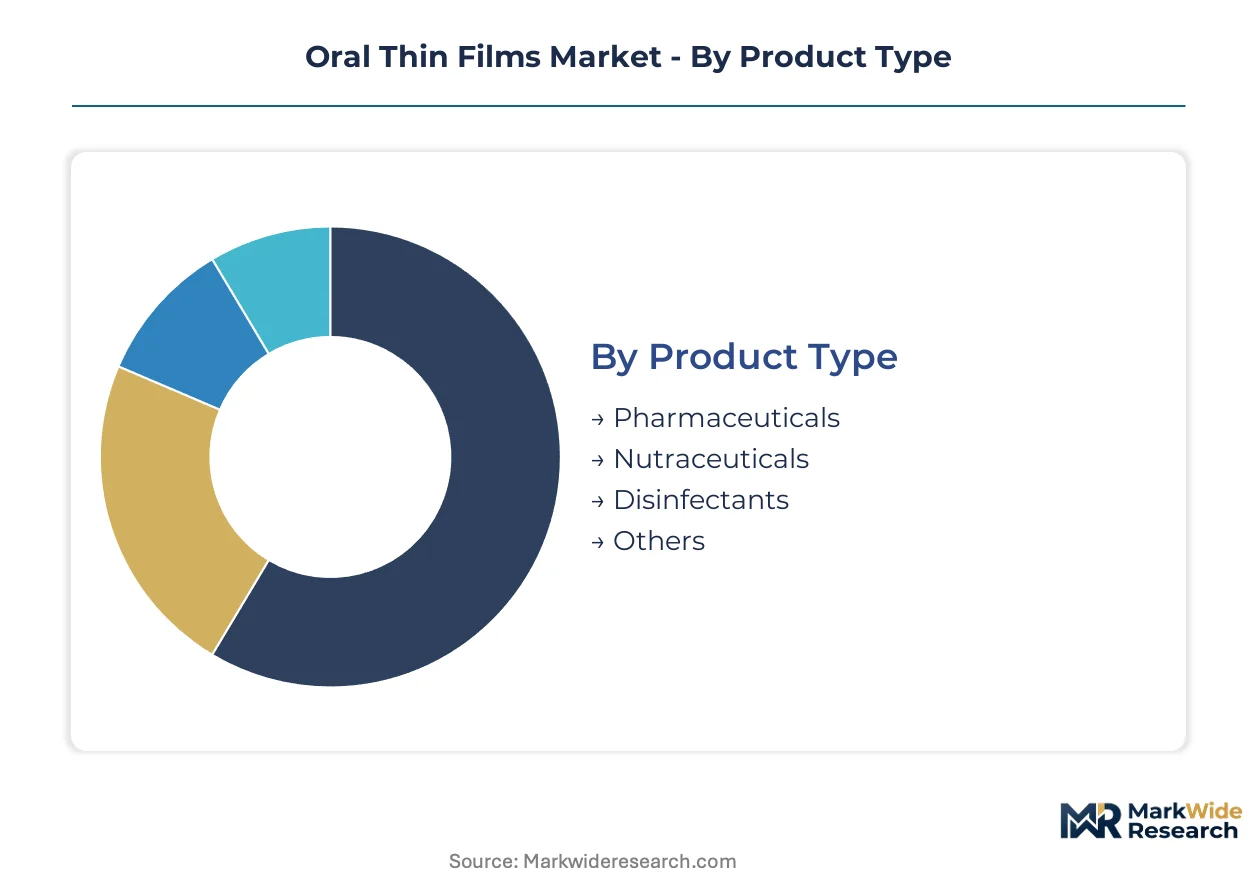
Segmentation in oral thin films reveals how capital allocation, regulatory pathways, and patient demographics create divergent margin profiles across product categories. Each dimension exposes distinct competitive barriers and growth vectors that reshape vendor positioning.
Product Type:
Capital intensity varies sharply across product types, with pharmaceutical-grade manufacturing demanding dedicated cleanroom infrastructure and validated dissolution testing suites that nutraceutical operations can bypass.
- Pharmaceuticals:These films incorporate active pharmaceutical ingredients into hydroxypropyl methylcellulose or pullulan matrices with precise dose uniformity specifications. Demand concentrates in the United States and Germany where FDA's 505(b)(2) pathway and EMA centralized authorization accelerate reformulation approvals for bioavailability enhancement.
- Nutraceuticals:Vitamin and botanical extracts delivered via rapid-dissolving strips target wellness consumers seeking alternatives to capsules and tablets. Japanese and South Korean manufacturers lead export supply for this segment, capitalizing on established pullulan supply chains and cosmetic-grade film aesthetics.
- Disinfectants:Antiseptic films for oral cavity applications serve institutional hygiene protocols in hospital settings.
- Others:Cosmetic films and diagnostic sampling strips occupy niche positions with lower regulatory barriers.
Pharmaceuticals absorb the bulk of installed capacity; nutraceuticals are expanding most quickly.
Therapy Area:
Application-specific formulation requirements dictate which therapy areas attract sustained R&D investment versus opportunistic entry.
- Pain Management:Opioid and non-opioid analgesics exploit sublingual delivery to accelerate onset and bypass gastric degradation. United States hospice and palliative care programs drive volume for fentanyl and buprenorphine film formulations where dysphagia complicates conventional dosing.
- Antiemetic:Nausea control for chemotherapy and post-surgical recovery leverages rapid buccal absorption when oral intake is compromised. Oncology supportive care purchasing groups in Germany and Japan negotiate multi-year supply agreements that favor suppliers with complete bioequivalence documentation.
- Cognitive Disorders:Donepezil and similar compounds target geriatric compliance through simplified administration.
- Hormonal Therapy:Testosterone and estrogen films compete with transdermal patches and injectables on convenience metrics.
Pain management commands the deepest formulation expertise investment; antiemetic applications show the steepest expansion trajectory.
Delivery Mode:
Physiological absorption kinetics separate delivery modes into distinct competitive arenas with incompatible manufacturing specifications.
- Sublingual:Films placed under the tongue achieve rapid systemic absorption through the ventral tongue's dense vascularization. Premium positioning in the United States reflects first-pass metabolism avoidance for cardiovascular and emergency medications where speed determines therapeutic outcome.
- Buccal:Cheek-adhering matrices extend residence time for chronic therapies requiring sustained plasma levels. Japanese geriatric polypharmacy management programs favor buccal formats for antihypertensive and antidiabetic regimens where patient dexterity limits tablet handling.
- Oral:Rapid-disintegration films on the tongue serve pediatric populations and patients with swallowing difficulties.
- Transmucosal:Broader mucosal targeting expands absorption surface area for select APIs.
Sublingual delivery claims the highest unit economics; buccal formats are gaining share fastest in chronic disease management.
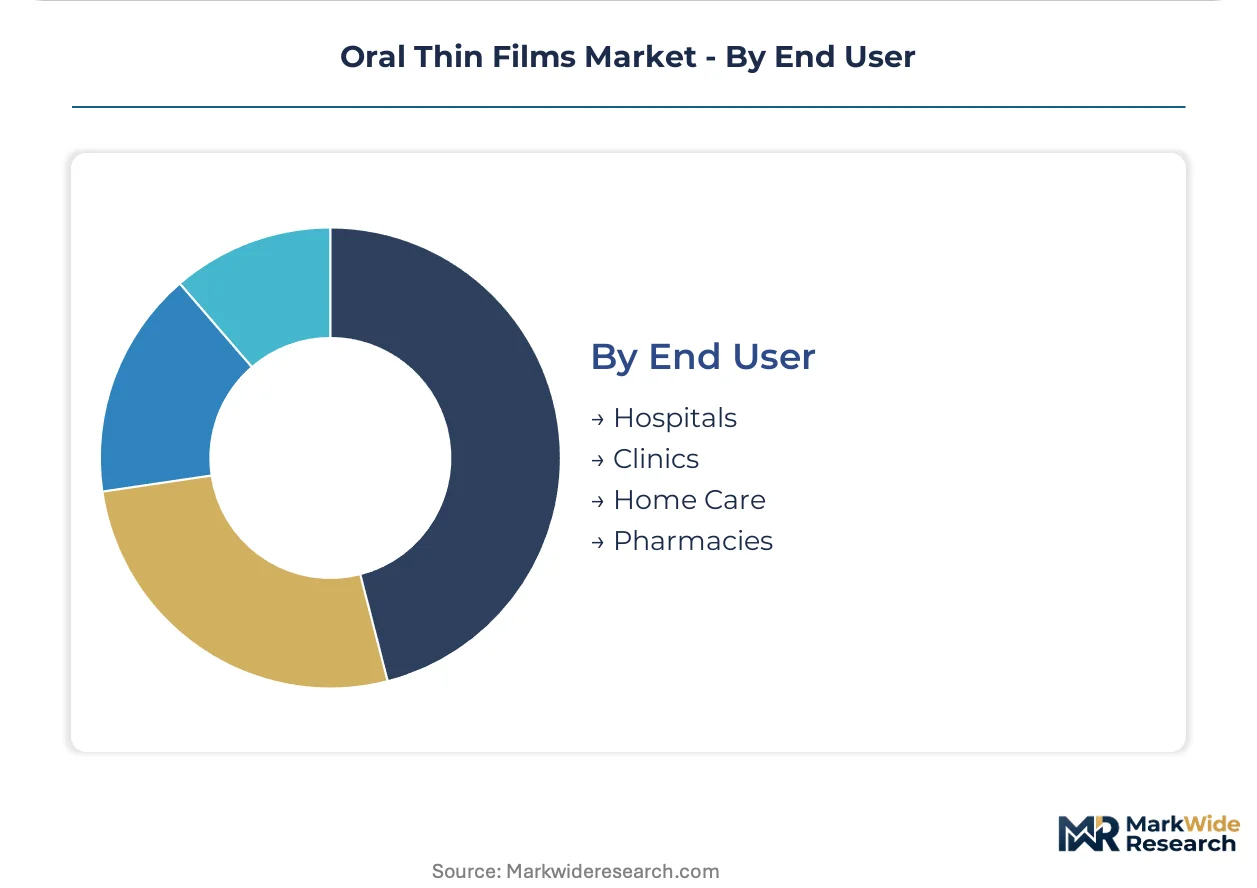
End User:
Procurement authority and reimbursement pathways fragment end-user segments into incompatible commercial models.
- Hospitals:Formulary committees consolidate vendor lists around suppliers with demonstrated bioequivalence packages and multi-product bundling capacity. United States group purchasing organizations negotiate exclusive agreements that displace spot procurement for film-based antiemetics and analgesics.
- Home Care:Pediatric and geriatric caregivers in Germany and Japan increasingly request non-invasive alternatives that eliminate choking risks and dosing errors associated with liquid formulations. Direct-to-pharmacy distribution pilots in the United States target this channel for chronic disease adherence monitoring.
- Clinics:Outpatient settings favor rapid-dispensing formats for same-day procedures.
- Pharmacies:Retail channels compete on convenience positioning against orally disintegrating tablets with established reimbursement codes.
Hospitals concentrate procurement volume through consolidated vendor lists; home care is climbing the fastest as reimbursement frameworks shift toward non-invasive alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade pullulan production clusters in Japan and China, anchoring raw material supply chains that feed film manufacturers across North America and Europe. This geographic concentration shapes regional competitive dynamics and procurement strategies.
United States
Hospice and palliative care programs drive demand for sublingual opioid films where dysphagia complicates conventional dosing. FDA's 505(b)(2) pathway accelerates reformulation approvals for bioavailability-enhanced products. Greater Boston hosts contract development organizations specializing in polymer rheology and mucoadhesion science.
Germany
Geriatric polypharmacy management programs favor buccal formats for patients with reduced manual dexterity. EMA centralized authorization streamlines marketing approval across EU member states, offsetting REACH compliance costs through reduced duplicative filings. The Rhine-Ruhr corridor concentrates pharmaceutical film manufacturing infrastructure.
Japan
Rapid-aging demographics concentrate demand for rapid-disintegration products in home care settings. PMDA marketing authorization pathways favor locally conducted clinical trials for buccal film formulations. The Kanto region around Tokyo anchors pharmaceutical-grade pullulan production for export markets.
India
Export-oriented manufacturing scales serve price-sensitive nutraceutical film segments across Southeast Asia and Africa. CDSCO manufacturing facility inspections align with WHO GMP standards for international market access. Maharashtra's pharmaceutical clusters in Mumbai and Pune specialize in solvent-casting operations for generic film formulations.
Oral Thin Films Market Key Industry Players
Strategic partnerships dominate the current landscape as mid-cap specialists seek technology access without capital-intensive internal development. The vendor base exhibits moderate concentration, with platform technology holders commanding premium positioning against commoditized nutraceutical suppliers. Two archetypes define competitive positioning: vertically integrated film casting specialists and modular contract development organizations serving multiple therapeutic areas. Capacity expansion and technology licensing represent the dominant competitive moves, with polymer qualification capabilities serving as the primary differentiation mechanism.
Within the platform technology tier, Aquestive Therapeutics, Inc. and IntelGenx Corp. represent North American specialists with integrated film casting and regulatory submission capabilities. ZIM Laboratories Limited occupies a position among Indian manufacturing-scale exporters serving European and North American markets. LTS Lohmann Therapie-Systeme AG exemplifies European contract manufacturing depth with established EMA compliance infrastructure.
| Leading Market Players |
|---|
| Aquestive Therapeutics, Inc. |
| ZIM Laboratories Limited |
| IntelGenx Corp. |
| C.L. Pharm |
| Cure Pharmaceutical |
| LTS Lohmann Therapie-Systeme AG |
| Indivior plc |
| Viatris Inc. |
| NAL Pharma |
| Others |
Cost & Logistics Intelligence
United States hospital group purchasing organizations and German geriatric care procurement programs concentrate buying power around suppliers with bundled bioequivalence documentation and multi-year contract structures. This buyer consolidation forces film manufacturers to absorb REACH compliance and polymer qualification costs into upfront pricing while competing on total cost-of-ownership metrics.
Pricing Analysis
Warranty and technical service bundling separates premium film suppliers from commodity competitors in contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in standard-tier pharmaceutical films is intensifying because Indian and Chinese manufacturers expand solvent-casting capacity for export markets. Home care distributors in Japan exhibit highest price sensitivity due to direct-to-patient reimbursement constraints, while United States oncology purchasing groups prioritize bioequivalence data over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and New Jersey anchor hub-and-spoke patterns for temperature-sensitive film shipments. Pharmaceutical-grade pullulan production concentrates in Japan and China, with hydroxypropyl methylcellulose sourcing anchored in the United States and Europe. Western manufacturers face single-source vulnerability for Japanese pullulan supply, where quality audits and import documentation extend lead times. Distribution runs through specialized pharmaceutical logistics providers with validated cold-chain capabilities for moisture-sensitive finished films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot-melt extrusion technology is displacing legacy solvent-casting processes, compressing batch cycle times and enabling real-time release testing for personalized dosing applications.
For Market Incumbents: Extend platform technology licensing into veterinary oral films and companion animal applications where FDA Center for Veterinary Medicine pathways remain underutilized. Acquire polymer rheology expertise through targeted hiring from Greater Boston contract development organizations to defend against modular CDMO competition. Prioritize backward integration into pharmaceutical-grade pullulan qualification capabilities to reduce Japanese supply concentration risk. For New Entrants and Emerging Players: Begin with nutraceutical rapid-dissolving strips for Southeast Asian wellness markets, where Japanese and South Korean aesthetic standards create premium positioning opportunities. Target direct-to-pharmacy distribution pilots in United States independent pharmacy chains for chronic disease adherence monitoring. Leverage continuous manufacturing integration with process analytical technology to compete on batch flexibility against established solvent-casting operations. For Investors and Strategic Acquirers: The window for entry favors vertically integrated film casting specialists with demonstrated EMA compliance infrastructure and multi-territory bioequivalence packages. Long-term viability hinges on polymer qualification capabilities and regulatory submission track records across FDA 505(b)(2) and EMA centralized pathways. Monitor FDA dissolution method standardization harmonization with EP monographs as inflection indicator for multi-territory filing cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Qualification Investment | REACH compliance and ECHA substance evaluation criteria elevate barrier-to-entry for European market access. |
| Continuous Manufacturing Scale-Up | Hot-melt extrusion with process analytical technology collapses batch cycle times from days to hours. |
| Veterinary Regulatory Pathway Development | FDA Center for Veterinary Medicine approvals for buccal films bypass gastric degradation in companion animals. |
| Direct-to-Pharmacy Distribution Pilot | United States independent pharmacy chains enable patient adherence data capture and margin retention. |
| Modular CDMO Platform Expansion | Mid-cap contract development organizations serve multiple clients without dedicated line changeovers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this oral thin films market assessment. Primary interviews with formulation scientists, regulatory affairs leads at film manufacturers, hospital formulary directors, and polymer procurement managers combined with FDA 505(b)(2) submission databases, EMA centralized authorization records, and REACH registration documentation. Bottom-up capacity modeling and top-down demand triangulation validated segment-level outputs.
Granularity-level modeling operated at product type, delivery mode, therapy area, and end-user dimensions across the projection horizon. Treatment line positioning, regional regulatory cluster alignment, and polymer qualification status informed pharmaceutical segment forecasts. CAGRs derived from installed capacity expansion timelines, reformulation pipeline visibility, and reimbursement framework evolution across United States, Germany, and Japan markets.
Underlying measurement precision varies by segment; pharmaceutical-grade films with FDA submission histories carry tighter precision than emerging nutraceutical categories. Forecasts reflect documented assumptions on regulatory approval timelines, polymer supply stability, and dissolution method harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Us Oral Care Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Dry Mouth Relief Market
Oral Care
Tongue Cleaner Market
Oral Care
Canker Sores Treatment Market
Oral Care
Oral Thrush Market
Oral Care
Herbal Toothpaste Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Kids Oral Care Products Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
South America Oral Care Market
Oral Care
Manual Toothbrush Market