
 Baby Teeth Care Products Market | 2026-2036
Baby Teeth Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Teeth Care Products Market Outlook
Pharmacy-to-digital shelf migration is rewriting how parents stock baby bathrooms across developed economies. Procter & Gamble leverages its pediatric dentist endorsement network to sustain premium placement in retail pharmacies. Colgate-Palmolive anchors fluoride education campaigns that drive repeat purchase behavior in emerging markets. Pigeon Corporation specializes in silicone-based infant toothbrushes that dominate Asian specialty store shelves.
Baby teeth care products encompass oral hygiene formulations and implements engineered for deciduous dentition, typically featuring reduced abrasivity indices below 250 RDA value and pH buffers between 5.5 and 7.0 to protect immature enamel. These products serve commercial purposes by preventing early childhood caries and establishing lifelong hygiene habits through age-appropriate delivery systems. Toothpastes formulated with natural ingredients command widening margin pools as parental ingredient scrutiny intensifies, while bamboo material toothbrushes attract sustainability-motivated buyers despite higher unit economics. Toddlers represent the fastest-expanding age group segment as first-molar emergence triggers category entry.
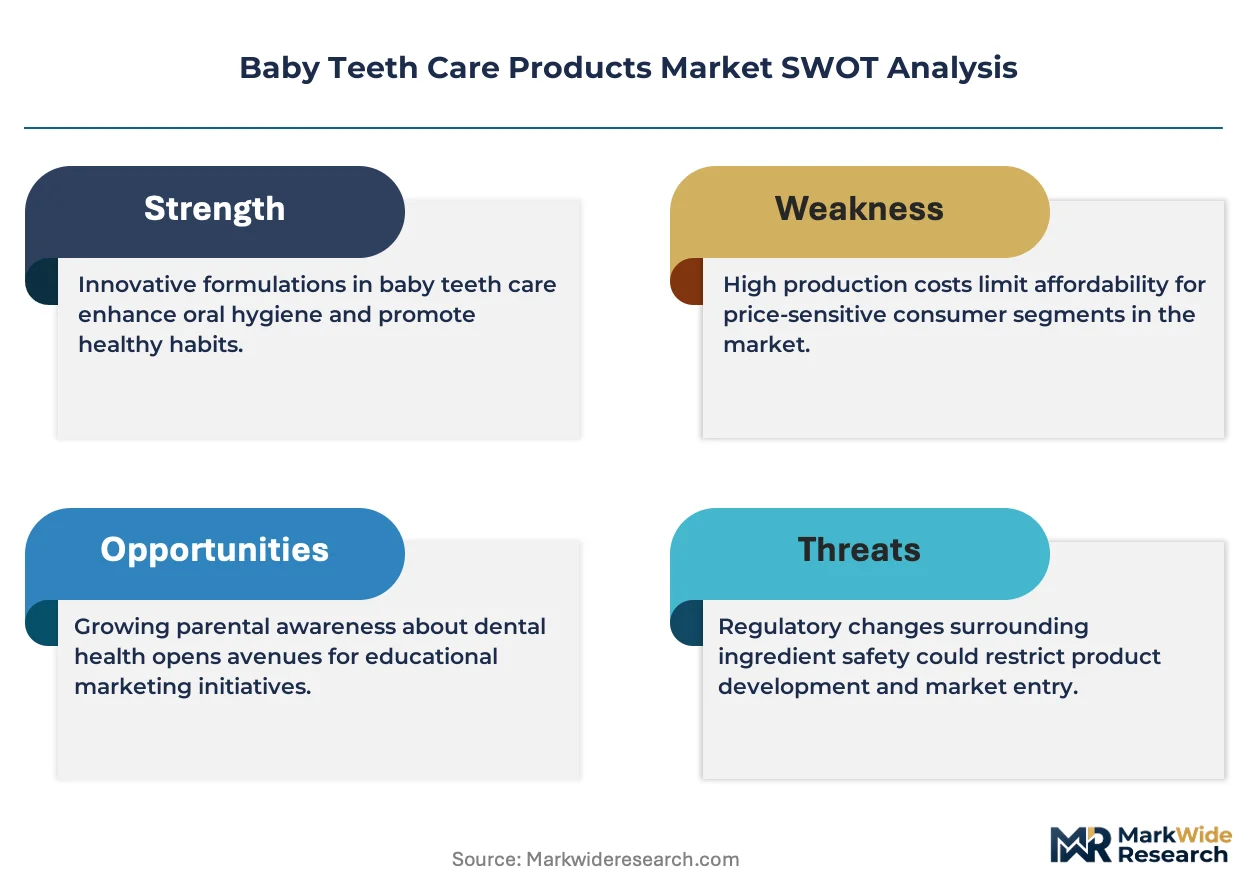
The US FDA governs fluoride concentration limits in children's toothpaste through monograph standards, while the EU REACH framework restricts preservative chemistries permissible in oral care products destined for pediatric use. China's NMPA enforces GB standards for silicone material safety in infant oral implements, creating multi-jurisdictional compliance burdens for multinational suppliers. Stakeholders must monitor evolving state-level fluoride varnish regulations and biodegradable packaging mandates that will reshape product specifications and regional manufacturing footprints.
Market Dynamics
Parental ingredient literacy is forcing formulation transparency across baby teeth care supply chains. Manufacturers now disclose full material sourcing to satisfy retailer procurement audits and direct-to-consumer disclosure mandates.
Growth Catalysts
- EU REACH microplastic restrictions:Formulators pivot to plant-derived abrasives and natural gum bases, opening premium positioning for certified-clean products.
- Silicone toothbrush adoption:Soft, non-toxic implements gain traction in pediatric dental protocols, expanding the addressable hardware segment.
- China birth-rate policy adjustments:Expanded infant population pools create volume foundations for category entrants targeting first-time parents.
Market Restraints
- Natural ingredient cost volatility:Xylitol and stevia extract prices fluctuate with agricultural yields, compressing margin stability for mid-tier brands.
- Single-source silicone supply:Medical-grade silicone concentrate in East Asian foundries exposes toothbrush manufacturers to logistics disruption.
- Fluoride concentration ceiling:FDA monograph limits cap therapeutic claims, constraining clinical differentiation in the toothpaste segment.
Strategic Opportunities
- Subscription replenishment models:Direct-to-parent delivery services capture recurring revenue through age-staged product progression.
- Biodegradable packaging mandates:EU Green Deal packaging regulations reward early adopters of compostable tube and blister materials.
- Pediatric telehealth integration:Remote dental consultation platforms create bundled product-prescription channels for fluoride varnish applications.
Industry Challenges
- Multi-jurisdictional compliance staffing:Simultaneous FDA, REACH, and NMPA filing requirements strain regulatory affairs teams at mid-scale suppliers.
- Clinical evidence generation timelines:Pediatric caries prevention claims require multi-year longitudinal studies, delaying new ingredient market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Teeth Care Products Market |
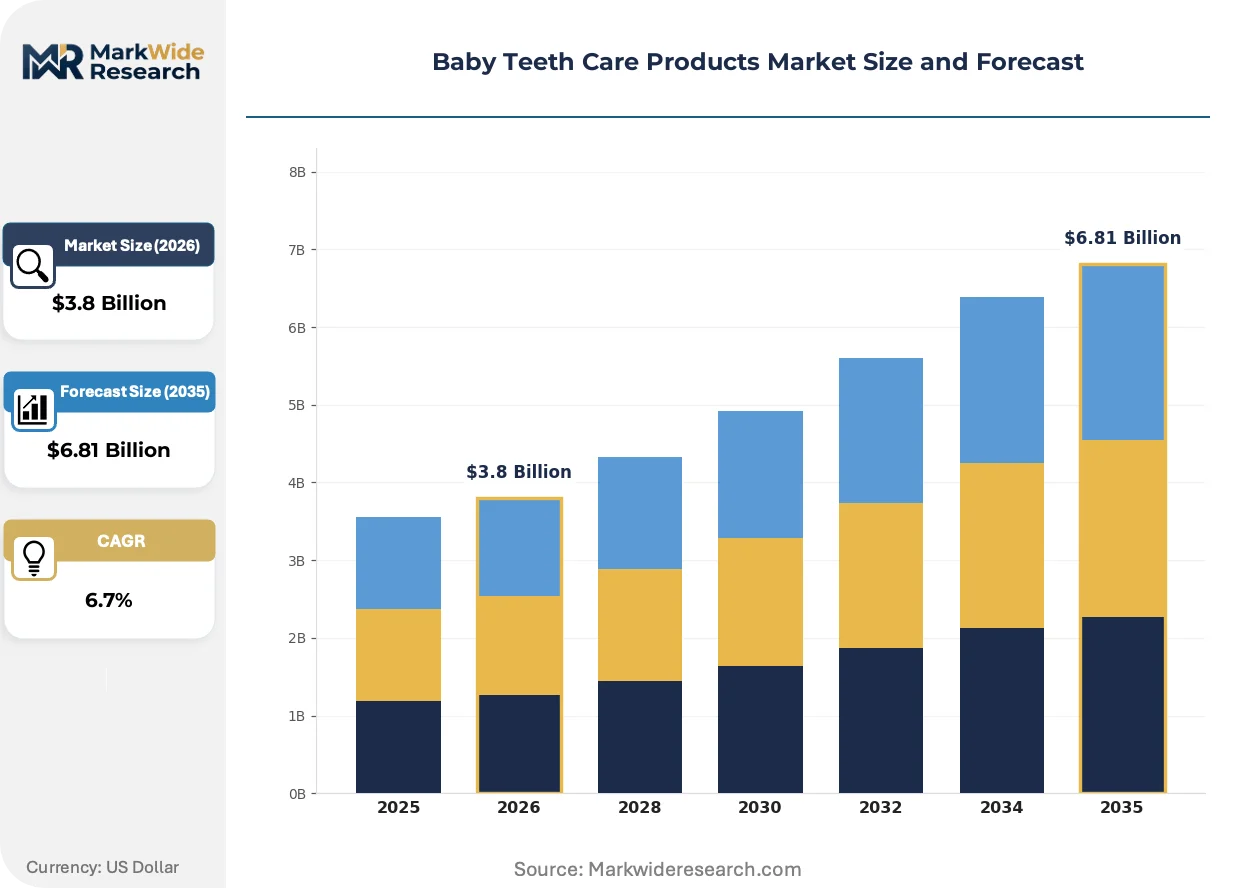
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothbrushes, Toothpastes, Floss, Mouthwash Material: Plastic, Bamboo, Silicone, Natural Ingredients Age Group: Infants, Toddlers, Pre-schoolers, Older Children Distribution Channel: Online Stores, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Procter & Gamble, Colgate-Palmolive, Johnson & Johnson, Unilever, Church & Dwight, Pigeon Corporation, Kenvue, GlaxoSmithKline, Lion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Teeth Care Products Market Strategic Shifts
Digital engagement tools are rewriting how oral hygiene habits form in early childhood. Connected devices and app-based reward systems now supplement physical product efficacy with behavioral reinforcement.
Smart toothbrush hardware is virtualizing the preventive care encounter. Bluetooth-enabled infant brushes transmit brushing duration and pressure data to parental smartphones. Dental practitioners in South Korea and Japan prescribe these devices to track compliance between appointments. The technology is virtualizing the traditional six-month checkup into continuous remote monitoring.
REACH authorization requirements are tightening preservative chemistry portfolios. ECHA scrutiny of isothiazolinone biocides forces reformulation toward organic acid preservation systems. European private-label manufacturers accelerate natural certification timelines to preempt retail delisting. The policy shift most affects fluoride-free training toothpaste lines targeting the zero-to-two age bracket.
Pharmacy shelf space is fragmenting into specialty verticals. Mass-market retailers now segment baby oral care from adult aisles, creating dedicated planogram blocks. Parents in Germany and the Netherlands increasingly complete routine purchases through pharmacy apps with same-day fulfillment. This channel bifurcation rewards brands with distinct pediatric sub-brand identity over house-label alternatives.
Baby Teeth Care Products Market Segmentation
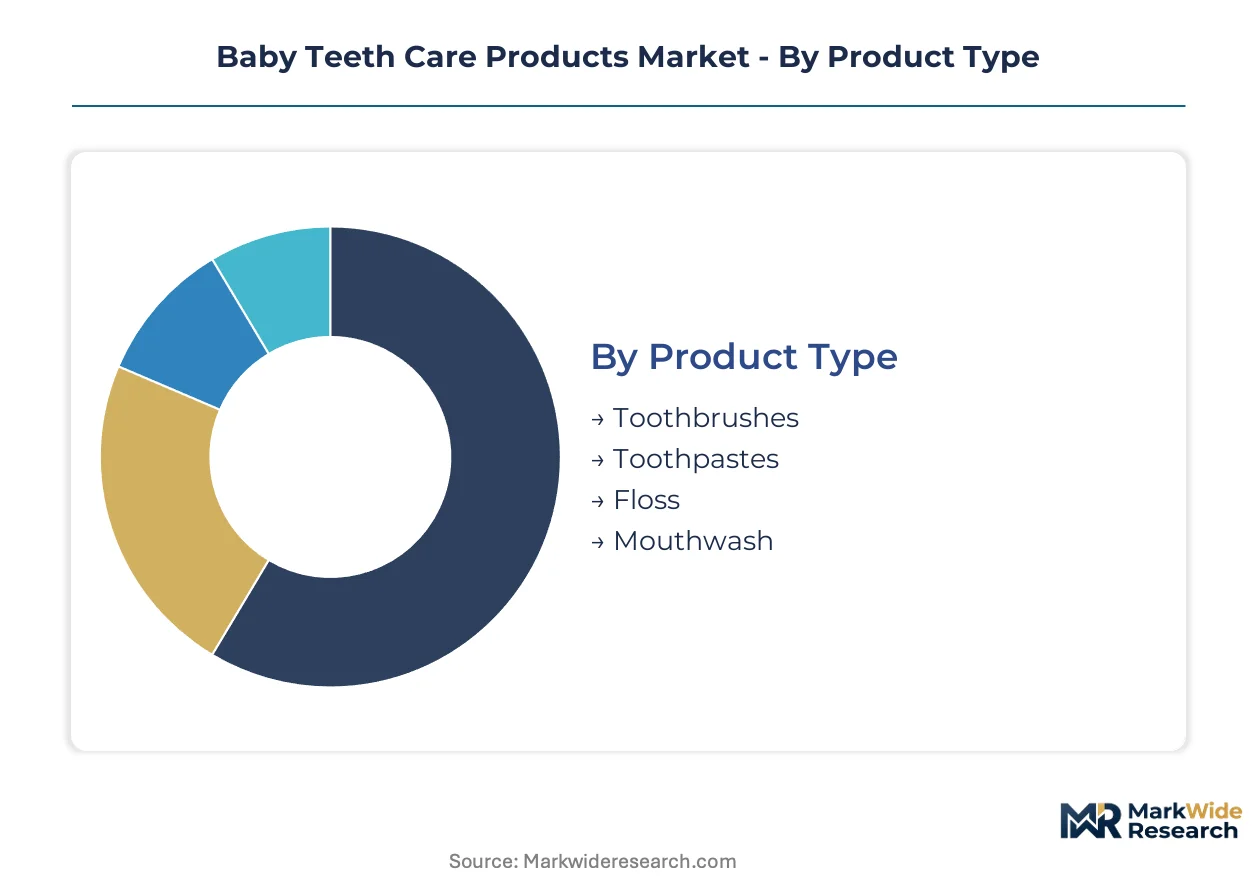
Baby teeth care products demand granular segmentation because parental purchase decisions pivot on developmental milestones, safety certifications, and channel accessibility. Each dimension reveals distinct margin structures and regulatory exposure profiles that shape supplier strategy.
Product Type:
After-sales service intensity varies sharply across product types, with hardware segments requiring warranty support and consumables depending on replenishment logistics.
- Toothpastes:Formulations engineered with reduced abrasivity below 250 RDA and pH buffers between 5.5 and 7.0 protect immature enamel. Demand clusters in China as birth-rate policies expand the addressable infant population, though FDA fluoride concentration ceilings constrain therapeutic differentiation.
- Toothbrushes:Implements feature age-scaled head dimensions and filament softness grades matched to gingival sensitivity. Silicone variants dominate specialty store shelves across Japan and South Korea where pediatric dental protocols emphasize compliance tracking through connected devices.
- Floss:Pre-threaded flossers with ergonomic handles address manual dexterity limitations in pre-school-aged users.
- Mouthwash:Alcohol-free rinses with xylitol bases target older children transitioning to independent hygiene routines.
By volume, Toothpastes leads. By growth pace, Toothbrushes is ahead.
Material:
Cost tier stratification separates premium-positioned sustainable inputs from commodity petrochemical derivatives.
- Silicone:Medical-grade elastomers meet China's NMPA GB standards for infant oral implements, creating compliance moats for qualified suppliers. Single-source concentration in East Asian foundries exposes manufacturers to logistics disruption.
- Natural Ingredients:Plant-derived abrasives and organic acid preservation systems command widening margin pools as EU REACH microplastic restrictions redirect formulation priorities. Xylitol and stevia extract price volatility compresses stability for mid-tier brands.
- Plastic:Polypropylene and TPE compounds dominate mass-market price points through established injection molding supply chains.
- Bamboo:Sustainably harvested fibers attract premium positioning despite higher unit economics and moisture sensitivity challenges.
By installed base, Plastic dominates. By margin expansion trajectory, Natural Ingredients climbs fastest.
Age Group:
Application specificity intensifies as developmental stages demand graduated formulation potency and implement ergonomics.
- Toddlers:First-molar emergence triggers category entry, expanding hardware and paste consumption simultaneously. Silicone toothbrush adoption accelerates in this bracket as parents seek non-toxic implements for emerging dentition.
- Infants:Fluoride-free training toothpaste lines target the zero-to-two bracket under tightened ECHA preservative scrutiny. Pharmacy-to-digital shelf migration concentrates demand among first-time parents seeking dentist-endorsed starter kits.
- Pre-schoolers:Independent brushing initiation drives flavored paste preferences and character-licensed implement designs.
- Older Children:Permanent tooth emergence shifts demand toward transitional formulations bridging pediatric and adult oral care.
By absolute users, Pre-schoolers represents the largest cohort. By category entry velocity, Toddlers is expanding most quickly.
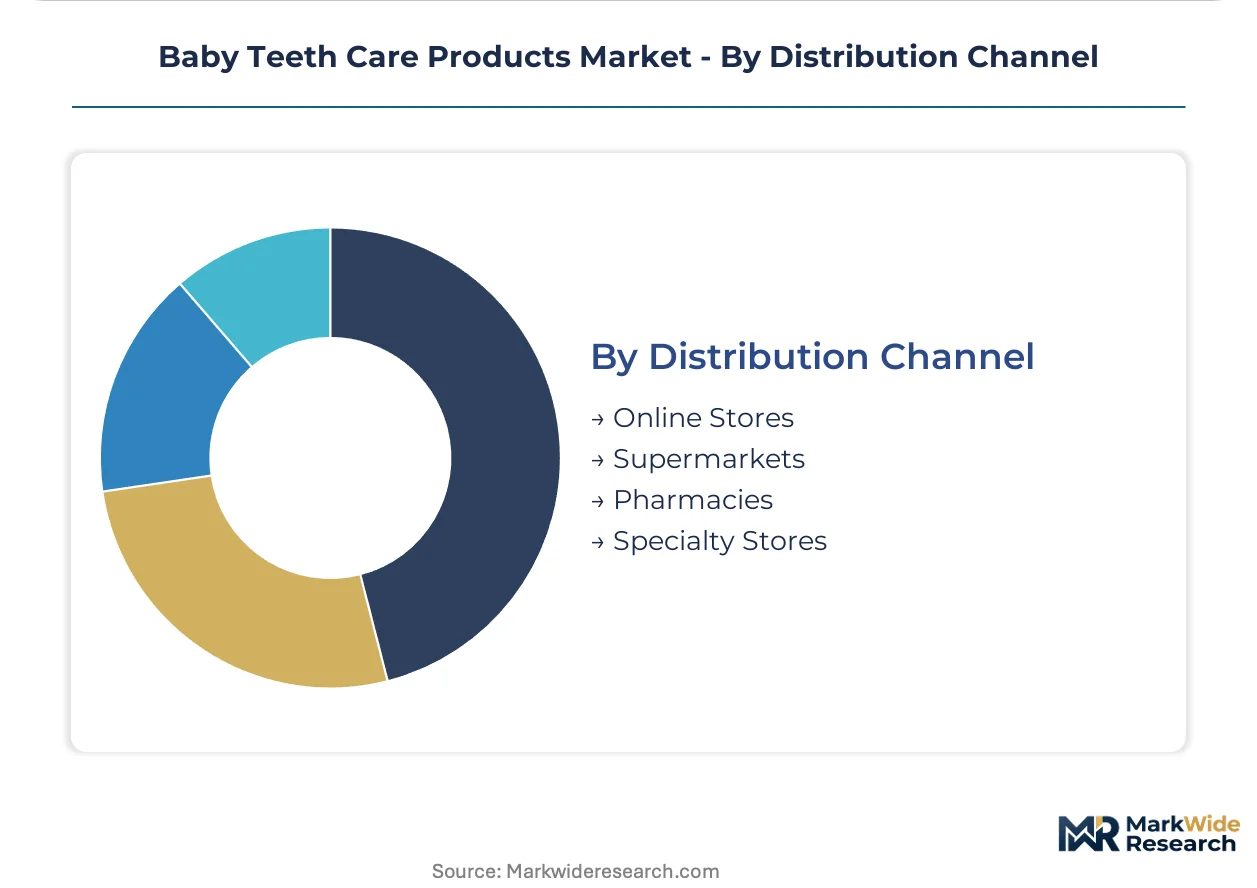
Distribution Channel:
Customer type fragmentation separates convenience-driven replenishment from deliberative first-purchase research behaviors.
- Pharmacies:Pediatric dentist endorsement networks sustain premium placement and trust transfer to first-time parents. Same-day fulfillment apps in Germany and the Netherlands accelerate routine purchase migration from physical aisles.
- Online Stores:Direct-to-parent subscription models capture recurring revenue through age-staged product progression, though regulatory filing burdens strain mid-scale supplier compliance staffing.
- Supermarkets:Mass-market retailers segment baby oral care into dedicated planogram blocks, rewarding distinct pediatric sub-brand identity.
- Specialty Stores:Curated assortments in Asian markets feature silicone toothbrush dominance and natural certification preemption strategies.
By transaction frequency, Supermarkets leads. By customer lifetime value capture, Online Stores is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites Asia-Pacific distribution networks for silicone toothbrush imports reaching European and North American retail channels. This maritime infrastructure positions China as the central node in global baby teeth care product circulation.
United States
Pediatric dentist endorsement networks drive pharmacy channel penetration for fluoride education campaigns. FDA monograph standards govern children's toothpaste concentration limits, constraining therapeutic claim differentiation. Greater Boston clusters telehealth dental platforms bundling product prescriptions with remote consultation services.
Germany
Pharmacy app adoption concentrates routine purchase behavior among first-time parents in Berlin-Brandenburg and North Rhine-Westphalia. EU REACH microplastic restrictions redirect formulation priorities toward plant-derived abrasives. ECHA scrutiny of isothiazolinone biocides accelerates natural certification timelines for private-label manufacturers.
China
Birth-rate policy adjustments expand addressable infant population pools for category entrants. NMPA enforces GB standards for silicone material safety in infant oral implements. Yangtze River Delta foundries concentrate medical-grade silicone supply for toothbrush manufacturers serving domestic and export markets.
Japan
Pediatric dental protocols in Kanto and Kansai regions emphasize compliance tracking through connected toothbrush devices. METI standards guide smart hardware integration into preventive care encounters. Osaka-based specialty retailers curate silicone toothbrush assortments dominating premium shelf positioning.
South Korea
Bluetooth-enabled infant brushes gain prescription traction among Seoul Capital Area dental practitioners. MFDS regulations align with regional standards for connected medical device data transmission. Busan-Ulsan logistics hubs facilitate component sourcing for hardware manufacturers targeting Asian export markets.
Baby Teeth Care Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying formulation and material inputs. The vendor base organizes around three structural tiers: multinational consumer goods conglomerates with pediatric sub-brand portfolios, regional specialists in silicone hardware and natural ingredients, and private-label manufacturers serving pharmacy and supermarket channels. Two dominant competitive moves reshape positioning: geographic expansion into China's expanding infant population pools, and portfolio diversification toward connected device ecosystems bundling hardware with subscription consumables.
Within the multinational tier, Procter & Gamble, Colgate-Palmolive, and Pigeon Corporation occupy distinct positioning archetypes. Procter & Gamble exemplifies the pharmacy-anchored endorsement model leveraging professional trust transfer. Colgate-Palmolive represents the fluoride education campaign approach driving emerging market penetration. Pigeon Corporation anchors the Asian specialty hardware segment with silicone-focused infant toothbrush expertise.
| Leading Market Players |
|---|
| Procter & Gamble |
| Colgate-Palmolive |
| Johnson & Johnson |
| Unilever |
| Church & Dwight |
| Pigeon Corporation |
| Kenvue |
| GlaxoSmithKline |
| Lion Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Yangtze River Delta silicone foundries is compressing toothbrush hardware margins while simultaneously creating procurement leverage for buyers negotiating multi-year supply agreements. This utilization dynamic forces mid-tier brands toward natural ingredient formulations where agricultural input volatility transfers pricing risk upstream to growers.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships between retailers and manufacturers, with pharmacy chains extracting steeper rebates than supermarket buyers. Pricing stratifies across premium silicone-connected devices, standard fluoride-free pastes, and economy plastic-handle toothbrushes. Price differentiation hinges on FDA pediatric monograph compliance tier and organic acid preservation certification under REACH. Cost compression in the standard tier intensifies as private-label manufacturers replicate natural ingredient claims. First-time parents through pharmacy apps exhibit lowest price sensitivity, while supermarket replenishment shoppers drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates risk calculations for silicone toothbrush manufacturers dependent on Yangtze River Delta foundries. Medical-grade silicone concentrate, xylitol sweetener, and bamboo fiber raw materials draw from Chinese, Finnish, and Vietnamese suppliers respectively. Single-source vulnerability in East Asian medical-grade silicone exposes hardware producers to logistics disruption. Distribution runs through Shanghai Port container networks reaching European pharmacy distributors and North American retail consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified regulatory affairs staffing capable of simultaneous FDA, REACH, and NMPA filings represents the scarcest capability in this market, constraining mid-scale supplier expansion and creating acquisition premiums for compliant entities.
For Market Incumbents: Build certification moats by accelerating natural ingredient pre-qualification under tightening ECHA preservative scrutiny before retail delisting deadlines. Anchor pharmacy shelf position through pediatric dentist endorsement network expansion. Defensive consolidation should target silicone hardware specialists with established NMPA GB compliance to neutralize single-source supply risk. For New Entrants and Emerging Players: China's expanding infant population pools under birth-rate policy adjustments represent the most penetrable entry point for fluoride-free training toothpaste lines. Subscription replenishment models capturing age-staged product progression offer defensible recurring revenue architecture. Go-to-market execution should leverage direct-to-parent digital channels bypassing incumbent pharmacy gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale suppliers possessing qualified multi-jurisdictional regulatory filing capabilities but lacking brand equity. Long-term viability over the coming decade rests on connected device ecosystem bundling hardware with consumable subscriptions. Watch pediatric telehealth platform partnership announcements as inflection signal for bundled prescription channel emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Certification Pre-qualification | ECHA isothiazolinone scrutiny accelerates retail delisting timelines for non-compliant private-label manufacturers. |
| Silicone Hardware Compliance Investment | NMPA GB standards create qualification moats for toothbrush suppliers serving Chinese domestic and export markets. |
| Subscription Replenishment Model Launch | Age-staged product progression captures recurring revenue and displaces transactional supermarket purchasing. |
| Pediatric Telehealth Platform Partnership | Remote dental consultation channels bundle fluoride varnish prescriptions with hardware-consumable integration. |
| Biodegradable Packaging Transition | EU Green Deal packaging regulations reward early compostable tube adopters with retail preferential placement. |
Study Parameters
A standing panel of pediatric dental clinic procurement managers, regulatory affairs directors at oral care manufacturers, pharmacy category buyers, and silicone materials sourcing specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against FDA monograph filings, ECHA REACH authorization databases, NMPA GB standard registrations, and Nielsen retail audit data. Bottom-up volume triangulation across product type, material, age group, and channel segments was cross-checked against top-down macroeconomic anchoring.
Scenario-bracketing framed demand projections across the analysis window, modeling low, base, and high cases for birth-rate policy effectiveness and silicone supply disruption probability. Segmentation dimensions included product formulation type, implement material grade, child developmental stage, and distribution channel format. CAGRs were derived from installed base growth rates modified by replacement cycle compression and category penetration expansion. Forecast inputs incorporated pediatric dental protocol adoption curves for connected devices and natural ingredient certification velocity.
Macroeconomic conditions sit as an overlay; deviation in birth-rate trajectories, agricultural commodity price spikes, or maritime logistics rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory filing timelines and retail channel migration velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Children's Oral Care Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Oral Care Market
Oral Care
Global Oral Hygiene Market
Oral Care
United States Oral Hygiene Market
Oral Care
Adult Oral Care Products Market
Oral Care
Oral Antiseptics Market
Oral Care
Manual Toothbrush Market
Oral Care
Oral Mucositis Market
Oral Care
Kids Oral Care Products Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Oral Thin Films Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Europe Oral Care Market