
 Middle East and Africa Oral Care Market | 2026-2036
Middle East and Africa Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Oral Care Market Foresight
The EU Green Deal's extraterritorial supply chain requirements for imported consumer goods is consolidating sustainability expectations across Middle East and Africa oral care exporters. Procter & Gamble leverages its manufacturing scale to meet these compliance thresholds across Gulf Cooperation Council markets. Colgate-Palmolive anchors its regional position through deep pharmacy channel control in Egypt and Morocco. Unilever competes via economy-tier distribution reach into East African convenience networks.
Middle East and Africa oral care encompasses toothpaste, mouthwash, toothbrushes, and dental floss formulated with fluoride concentrations typically ranging from 1000 to 1500 ppm for caries prevention, manufactured through hydration, milling, and aeration processes for paste stability in high-temperature climates. Toothpaste dominates value generation due to daily-use frequency and premium whitening variant uptake, while dental clinics represent the fastest-growing end user as professional prophylaxis services expand in urban Nigeria and Kenya. Online retail channels capture disproportionate growth momentum among younger demographics seeking subscription replenishment models.
South Africa's National Regulator for Compulsory Specifications enforces mandatory safety standards on oral care imports, while Saudi Arabia's Saudi Food and Drug Authority governs product registration and ingredient disclosure for regional distribution. Egypt's Ministry of Health and Population maintains localized manufacturing licensing that shapes competitive access for multinational entrants. Stakeholders must monitor evolving halal certification requirements and water-scarcity formulation adaptations as decisive market access variables.
Market Dynamics
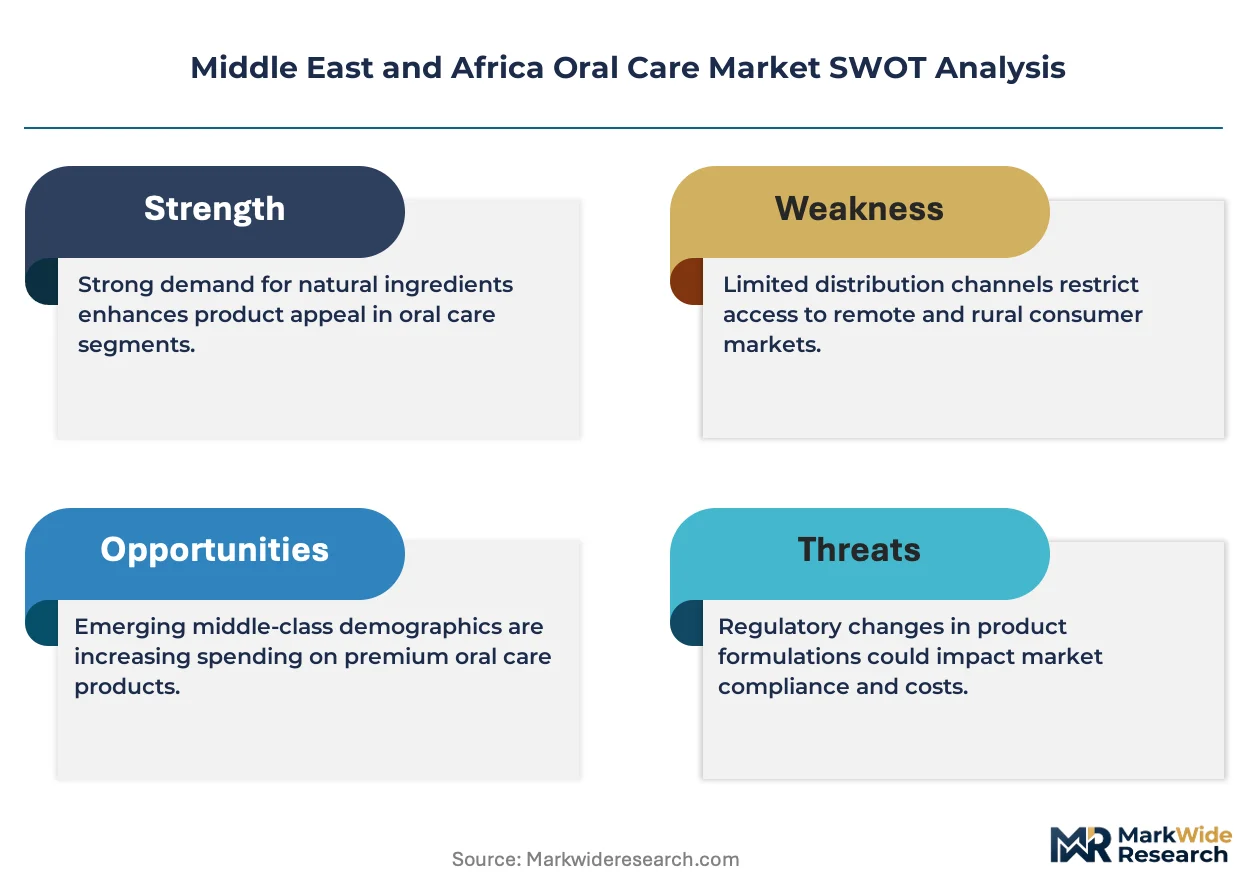
The Middle East and Africa oral care sector faces a structural tension between Gulf Cooperation Council premiumization and Sub-Saharan Africa's price-sensitive mass-market expansion, with halal certification and water-scarce formulation requirements now determining manufacturing location decisions.
Growth Catalysts
- Egyptian urban pharmacy networks:Cairo and Alexandria's retail pharmacy consolidation creates concentrated distribution nodes for professional-grade oral care products.
- Saudi Food and Drug Authority registration pathways:Streamlined product approval processes for halal-certified formulations accelerate market entry timelines for compliant manufacturers.
- Professional prophylaxis services:Dental clinic chains in Lagos and Nairobi drive demand for fluoride varnish and prescription-strength toothpaste.
Market Restraints
- Sorbitol price volatility:Humectant input costs fluctuate with global corn and tapioca supply disruptions, compressing margin structures for paste manufacturers.
- South African import dependency:The National Regulator for Compulsory Specifications concentrates compliance costs on foreign suppliers without local manufacturing assets.
- Water-scarce formulation constraints:High-temperature stability requirements limit conventional hydration processes, raising technical barriers for new entrants.
Strategic Opportunities
- Kenyan convenience retail modernization:Nairobi's supermarket expansion creates shelf space for mid-tier whitening and sensitivity product lines.
- Subscription replenishment models:Younger demographics in Dubai and Johannesburg adopt automated toothbrush head and paste delivery services.
- EU Green Deal supply chain alignment:Exporters meeting extraterritorial sustainability requirements gain preferential access to European retail partnerships.
Industry Challenges
- Halal certification timeline fragmentation:Divergent standards between Saudi Arabia, UAE, and Malaysia create redundant audit cycles for multi-market products.
- Clinical salesforce scaling:Dental clinic channel development requires specialized professional education capabilities scarce in East African labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Oral Care Market |
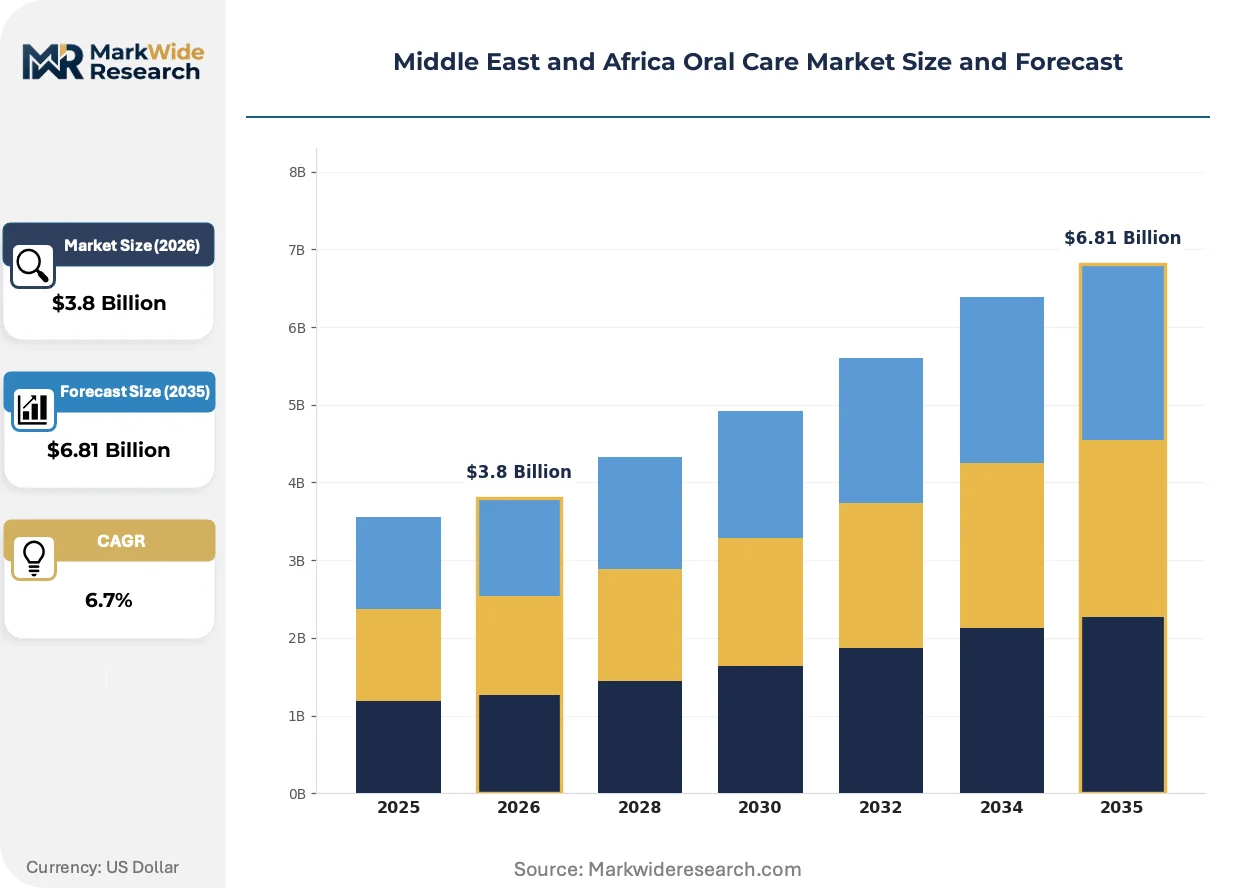
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Toothbrushes, Dental Floss End User: Adults, Children, Seniors, Dental Clinics Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Price Tier: Premium, Mid-Range, Economy, Discount |
| Companies Covered | GlaxoSmithKline PLC, Henkel AG & Co. KGaA, Procter & Gamble, Philips, Sunstar Suisse S.A., Colgate-Palmolive Company, Johnson & Johnson, LG Corporation, Unilever PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Oral Care Market Shifts & Advancements
Formulation science and channel architecture are converging to reshape competitive access across the Middle East and Africa oral care landscape, with climate adaptation and digital distribution emerging as decisive capability differentiators.
Desensitizing potassium nitrate and nano-hydroxyapatite remineralization systems are expanding into premium daily-use segments. Younger consumers in Gulf Cooperation Council markets adopt these technologies at accelerated rates. This expansion is compressing conventional fluoride-only positioning and forcing ingredient transparency upgrades.
South Africa's National Regulator for Compulsory Specifications now mandates expanded safety documentation for imported oral care. This industrial consequence raises compliance thresholds for Asian manufacturing sources. Professional-grade imports face the most acute documentation burdens, shifting sourcing toward locally licensed production.
Younger buyers now favor subscription-based replenishment over traditional retail stocking. Pharmacy and supermarket channels in Cairo and Lagos experience the most visible disruption, with direct-to-consumer platforms capturing recurring purchase relationships. This behavioral pivot concentrates customer lifetime value with logistics-capable suppliers.
Middle East and Africa Oral Care Market Segmentation
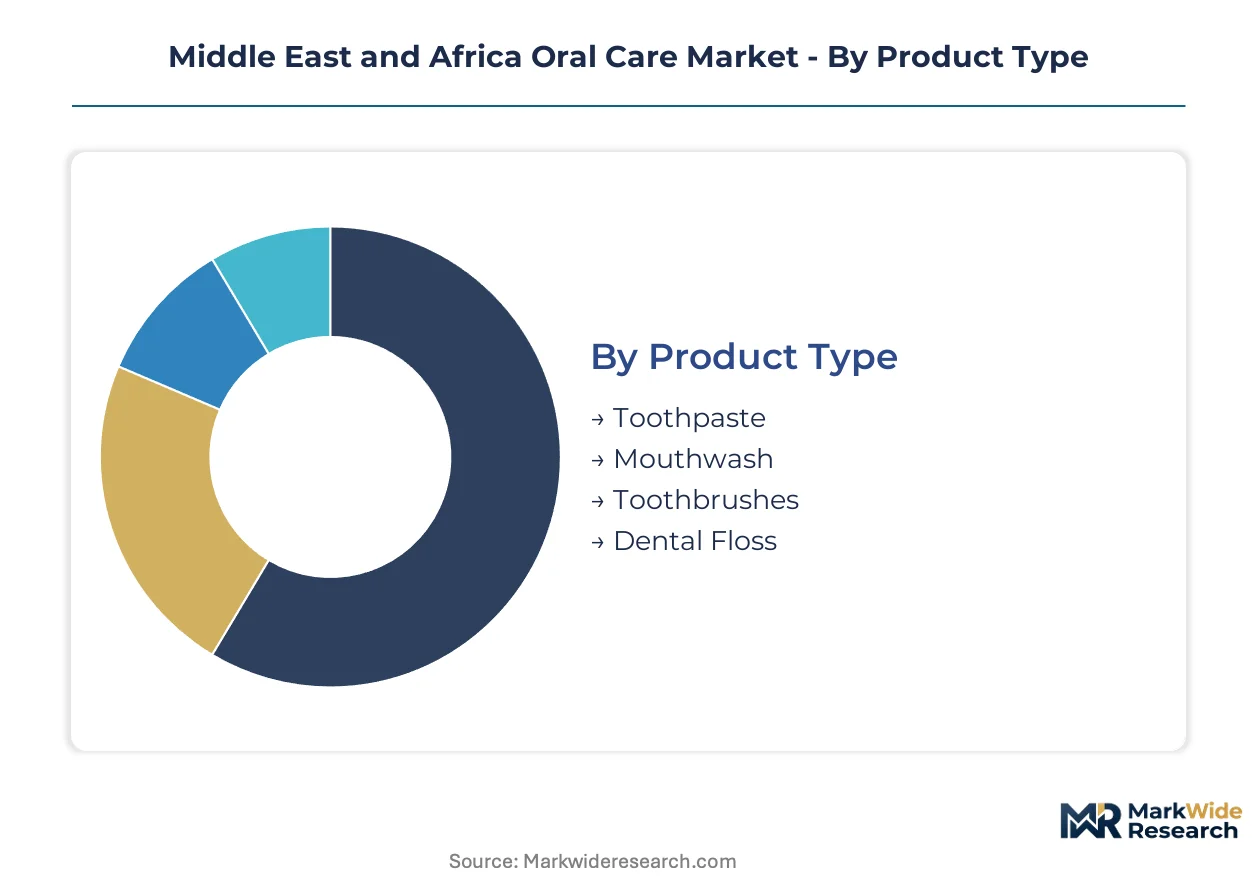
Halal certification requirements and water-scarce formulation standards fragment product approvals across Middle East and Africa oral care segments. Manufacturers must align technical specifications with Saudi Food and Drug Authority, South Africa's National Regulator for Compulsory Specifications, and Egypt's Ministry of Health and Population to secure market access.
Product Type:
Saudi Food and Drug Authority registration timelines vary sharply by product complexity, with fluoride concentration declarations and stability testing protocols creating divergent compliance burdens.
- Toothpaste:Hydrated silica abrasives and fluoride systems at 1000-1500 ppm dominate daily consumption. Egyptian urban pharmacy networks and Lagos supermarket chains concentrate volume for whitening and sensitivity variants.
- Toothbrushes:Nylon bristle configurations and ergonomic handle designs span manual and powered formats. Nairobi's dental clinic procurement and Dubai's subscription replenishment services drive replacement cycle acceleration.
- Mouthwash:Cetylpyridinium chloride and essential oil formulations require alcohol-content disclosure under Gulf Cooperation Council standards. Johannesburg pharmacy channels capture professional recommendation traffic.
- Dental Floss:Nylon and PTFE monofilament constructions target interdental cleaning frequency gaps. Moroccan urban retail shows emerging uptake among younger demographics.
Leading the category by volume: Toothpaste. Growing fastest: Toothbrushes.
End User:
Prescription-strength fluoride access separates professional channels from over-the-counter segments, with dental clinic procurement governed by clinical licensing requirements.
- Adults:Sensitivity and whitening formulations capture recurring purchase frequency. Cairo and Alexandria pharmacy networks consolidate demand for premium daily-use products.
- Dental Clinics:Professional prophylaxis services in Lagos and Nairobi drive fluoride varnish and prescription toothpaste procurement. Kenya's clinical salesforce scarcity constrains channel expansion velocity.
- Children:Lower fluoride concentrations and flavor-optimized formulations target parental safety preferences. South African retail pharmacy compliance documentation shapes import sourcing.
- Seniors:Dry mouth and gingival recession formulations address age-specific oral health deterioration. Dubai's healthcare infrastructure supports specialized product availability.
Highest procurement concentration: Adults. Steepest expansion trajectory: Dental Clinics.
Distribution Channel:
Logistics infrastructure maturity determines replenishment model viability, with last-mile capabilities fragmenting between Gulf Cooperation Council urban centers and Sub-Saharan African secondary cities.
- Pharmacies:Professional recommendation influence and prescription fulfillment anchor oral care purchasing. Egypt's retail pharmacy consolidation creates concentrated distribution nodes for therapeutic variants.
- Online Retail:Subscription replenishment models capture automated toothbrush head and paste delivery among younger demographics. Johannesburg and Dubai show highest platform penetration rates.
- Supermarkets:Shelf space competition favors economy-tier volume brands with packaging localization. Nairobi's supermarket modernization expands mid-tier product access.
- Convenience Stores:Impulse purchase occasions and travel-size formats target immediate consumption needs. Morocco's urban convenience network shows emerging oral care SKU expansion.
Dominant volume channel: Pharmacies. Gaining share fastest: Online Retail.
Price Tier:
Raw material input costs and certification overhead stratify margin structures, with halal audit expenses disproportionately burdening economy-tier producers lacking scale efficiencies.
- Premium:Nano-hydroxyapatite and potassium nitrate formulations command formulation transparency premiums. Gulf Cooperation Council younger consumers adopt desensitizing technologies at accelerated rates.
- Economy:Basic fluoride protection and simplified packaging target price-sensitive mass markets. Unilever's East African convenience network distribution reach anchors this tier.
- Mid-Range:Whitening variant extensions and sensitivity positioning bridge daily-use and therapeutic benefits. South African retail pharmacy channels concentrate this tier's volume.
- Discount:Minimal ingredient disclosure and regional manufacturing sourcing reduce landed costs. Informal retail in Nigerian secondary cities captures this segment's distribution.
Largest revenue concentration: Premium. Expanding most quickly: Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cairo anchors oral care distribution density across the Middle East and Africa, with its consolidated pharmacy networks serving as the primary conduit for therapeutic and premium daily-use products into North African markets.
Egypt
Cairo and Alexandria's retail pharmacy consolidation creates concentrated nodes for professional-grade toothpaste and fluoride varnish distribution. The Ministry of Health and Population maintains localized manufacturing licensing requirements that shape competitive access for multinational entrants. Egypt's urban pharmacy networks capture disproportionate volume for whitening and sensitivity formulations.
Saudi Arabia
The Saudi Food and Drug Authority governs product registration and ingredient disclosure requirements that determine regional distribution eligibility for halal-certified formulations. Streamlined approval pathways for compliant manufacturers accelerate market entry timelines into Gulf Cooperation Council markets. Riyadh and Jeddah's retail infrastructure supports premium product uptake among younger demographics seeking desensitizing technologies.
South Africa
Johannesburg's retail pharmacy channels concentrate mid-tier oral care volume while the National Regulator for Compulsory Specifications enforces mandatory safety standards on imports. Tightened cosmetics and toiletries documentation requirements reshape product formulation specifications for foreign suppliers. Cape Town's healthcare infrastructure supports specialized availability for dry mouth and gingival recession formulations targeting senior populations.
Nigeria
Lagos anchors dental clinic chain expansion driving demand for prescription-strength toothpaste and professional prophylaxis services. The country's national pharmaceutical regulator maintains import compliance frameworks that concentrate costs on suppliers lacking local manufacturing assets. Lagos and Abuja's urban pharmacy networks experience visible disruption from direct-to-consumer platform penetration among younger buyers.
Kenya
Nairobi's supermarket modernization creates shelf space for mid-tier whitening and sensitivity product lines while dental clinic procurement accelerates replacement cycles for powered toothbrushes. Kenya's clinical salesforce scarcity constrains professional channel expansion velocity despite rising urban demand. Nairobi's convenience retail network anchors economy-tier distribution reach into East African secondary cities.
Middle East and Africa Oral Care Market Competitive Landscape
The competitive structure tilts toward multinational conglomerates with manufacturing scale sufficient to meet fragmented regulatory requirements across multiple jurisdictions. Three archetypes dominate: Gulf Cooperation Council premium specialists leveraging halal certification advantages, Sub-Saharan African mass-market distributors optimizing economy-tier convenience reach, and professional-grade suppliers building dental clinic channel relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves as players address water-scarce formulation constraints and halal audit timeline fragmentation.
Among multinational conglomerates, Procter & Gamble, Colgate-Palmolive Company, and Unilever PLC occupy positions exemplifying divergent strategic archetypes. Procter & Gamble represents scale-driven compliance capability across Gulf Cooperation Council markets. Colgate-Palmolive Company anchors pharmacy channel control in Egypt and Morocco. Unilever PLC exemplifies economy-tier distribution optimization into East African convenience networks.
| Leading Market Players |
|---|
| GlaxoSmithKline PLC |
| Henkel AG & Co. KGaA |
| Procter & Gamble |
| Philips |
| Sunstar Suisse S.A. |
| Colgate-Palmolive Company |
| Johnson & Johnson |
| LG Corporation |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Skilled formulation chemists concentrated in Egypt's manufacturing corridor drive labor-cost differentials that widen spreads between premium therapeutic tiers and economy fluoride protection. Egypt's localized licensing requirements and South Africa's import compliance burdens concentrate pricing power with manufacturers possessing regional production assets.
Pricing Analysis
Outcome-linked pricing for prescription-strength fluoride varnish and desensitizing systems anchors premium tier valuations to clinical efficacy metrics. Three-tier pricing structure across premium, standard, and economy levels stratifies by halal certification grade and fluoride concentration disclosure depth. Cost compression in economy tiers intensifies because sorbitol humectant costs fluctuate with global corn supply disruptions. Dental clinics exhibit lowest price sensitivity due to professional reimbursement structures, while informal retail channels in Nigerian secondary cities show highest elasticity.
Supply Chain Analysis
Pharmacy-direct distribution handles professional-grade demand in Cairo and Alexandria, while supermarket and convenience networks manage mass-market replenishment across Lagos and Nairobi. Manufacturing concentrates in Egypt, South Africa, and Saudi Arabia to satisfy divergent halal certification and water-scarce formulation standards. Raw material sourcing draws from Malaysian palm-derived surfactants, Chinese hydrated silica abrasives, and Indian flavor compounds. Single-source vulnerability in halal audit certification bodies creates redundant compliance cycles. Distribution runs through consolidated urban pharmacy nodes in North Africa and expanding supermarket infrastructure in East Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over halal-certified ingredient sourcing determines margin sustainability. Players pursue backward integration into surfactant and abrasive supply to reduce certification timeline fragmentation.
For Market Incumbents: Deepen pharmacy channel control in Egypt and Morocco to defend against direct-to-consumer platform disruption. Lock in long-term halal certification partnerships with Saudi Food and Drug Authority-accredited bodies to preempt audit redundancy. Capacity addition in Cairo manufacturing corridors secures localized licensing advantages against Asian import competitors. For New Entrants and Emerging Players: Nano-hydroxyapatite remineralization technology offers a technology-first wedge into Gulf Cooperation Council premium daily-use segments underserved by fluoride-only incumbents. Target Nairobi's supermarket modernization for mid-tier whitening and sensitivity positioning. Pursue subscription replenishment partnerships with Johannesburg and Dubai logistics platforms to bypass established retail gatekeepers. For Investors and Strategic Acquirers: The window for entry favors professional-grade suppliers with dental clinic channel relationships and scalable clinical salesforce capabilities. Long-term viability hinges on water-scarce formulation R&D assets transferable across high-temperature climate markets. Watch halal certification standard harmonization between Saudi Arabia, UAE, and Malaysia as the inflection signal for multi-market product consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Streamlining | Redundant audit cycle elimination accelerates Saudi Food and Drug Authority market entry timelines. |
| Water-Scarce Formulation R&D | High-temperature stability capabilities unlock Gulf Cooperation Council premium tier access. |
| Pharmacy Channel Consolidation | Cairo and Alexandria retail node control concentrates therapeutic variant distribution. |
| Subscription Platform Partnership | Direct-to-consumer replenishment captures recurring purchase relationships from younger demographics. |
| Clinical Salesforce Buildout | Professional education capabilities in Lagos and Nairobi drive fluoride varnish procurement velocity. |
Research Methodology
Document review covered Saudi Food and Drug Authority registration filings, South Africa's National Regulator for Compulsory Specifications safety documentation, and Egypt's Ministry of Health and Population manufacturing licensing records, complemented by interviews with brand managers at multinational oral care manufacturers, category buyers at Cairo pharmacy chains, Nairobi supermarket procurement leads, and dental clinic purchasing coordinators in Lagos. Secondary validation drew from customs import records, Nielsen retail audit data for Middle East and Africa consumer goods, and trade association statistics. Bottom-up volume modeling and top-down value triangulation anchored forecast construction.
Cross-referencing historical consumption patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end user archetype, distribution channel, price tier, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for policy intervention timing and infrastructure buildout schedules. Forecast inputs incorporated halal certification timeline evolution and water-scarce formulation patent filings.
Several conditions sit outside the modeled scope, including currency devaluation episodes, abrupt regulatory standard changes, and pandemic-related supply chain disruptions. Forecasts reflect base-case assumptions about pharmacy network consolidation velocity and subscription platform penetration rates. Periodic stress-testing of base assumptions is recommended against sorbitol price volatility and clinical salesforce availability in East African labor markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Adult Oral Care Products Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Global Halitosis Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Xerostomia Treatment Market
Oral Care
Us Oral Care Market
Oral Care
Herbal Toothpaste Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Children's Oral Care Market
Oral Care
Oral Rinse Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Europe Oral Care Market
Oral Care
Tongue Cleaner Market
Oral Care
Kids Toothpaste Market
Oral Care
Mouthwash Market
Oral Care
Global Oral Care/Oral Hygiene Market