
 Herbal Toothcare Market | 2026-2036
Herbal Toothcare Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Toothcare Market Intelligence
India's Ayurvedic manufacturing corridors are rewriting supply dynamics for herbal toothcare. Patanjali Ayurved Limited leverages its vertically integrated herb cultivation networks to sustain cost leadership across rural and urban distribution. Himalaya Wellness Company anchors premium positioning through pharmacy-centric channels in Southeast Asia and the Middle East. Dabur India Limited competes on formulation heritage, extending its portfolio from clove oil toothpowders to complete oral care systems.
Herbal toothcare comprises oral hygiene preparations formulated with botanical extracts, essential oils, and plant-derived abrasives rather than synthetic chemicals, typically containing specified concentrations of active compounds like eugenol from clove or azadirachtin from neem to deliver antimicrobial and anti-inflammatory efficacy. These products serve consumers seeking alternatives to fluoride-heavy or triclosan-containing conventional products, particularly in markets with strong traditional medicine heritage. Toothpaste dominates current value generation due to established usage habits and shelf visibility, though chewing tablets represent the fastest-expanding format among travel and zero-waste consumer segments. Aloe vera and neem ingredient categories command the deepest margin pools because of recognizable consumer efficacy narratives and supply chain control by major Indian producers.
India's BIS and CDSCO frameworks govern Ayurvedic oral care labeling and safety thresholds, while the EU's REACH regulation and Cosmetic Product Regulation impose stringent botanical extract documentation requirements that filter market entrants. The US FDA exercises oversight through cosmetic and drug distinction rules that determine whether herbal claims trigger pre-market approval pathways. Stakeholders must monitor evolving definitions of cosmetic versus therapeutic claims across jurisdictions, as regulatory reclassification would force reformulation investments or channel restrictions.
Market Dynamics
Herbal toothcare supply chains concentrate around vertically integrated herb cultivation networks in India, where BIS certification requirements for Ayurvedic products create compliance moats that filter smaller competitors from premium positioning.
Growth Catalysts
- CDSCO safety thresholds:India's tightened Ayurvedic oral care labeling standards elevate consumer trust in domestically certified products, accelerating pharmacy channel penetration.
- Zero-waste consumption patterns:Chewing tablet formats gain traction among urban Millennial and Gen Z travelers seeking plastic-free alternatives to conventional tubes.
- Neem cultivation corridors:Maharashtra and Gujarat herb belts provide captive supply of azadirachtin-rich raw material for antimicrobial formulations.
Market Restraints
- EU REACH documentation burdens:Stringent botanical extract traceability requirements impose compliance costs that exclude small-batch Ayurvedic exporters from German natural cosmetics retail.
- Clove oil price volatility:Indonesian and Madagascan supply disruptions transmit directly to eugenol-dependent formulation margins.
- Fluoride substitution ceiling:Clinical efficacy gaps in caries prevention limit herbal penetration among pediatric and high-risk dental patient segments.
Strategic Opportunities
- Middle East pharmacy expansion:UAE and Saudi Arabia's MOHAP registration pathways for Ayurvedic products open premium positioning in halal-certified oral care aisles.
- Solid tablet subscription models:Direct-to-consumer channels bypass conventional retail slotting fees while capturing recurring revenue from zero-waste adherents.
- PLI scheme herbal processing:India's production-linked incentive allocations for Ayurvedic manufacturing reduce capital intensity for extraction facility upgrades.
Industry Challenges
- Cosmetic-therapeutic claim boundary enforcement:US FDA distinction rules require legal review of antimicrobial positioning, delaying campaign launches.
- Phytochemical standardization gaps:Batch-to-batch azadirachtin and eugenol potency variation complicates consistent efficacy messaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Toothcare Market |
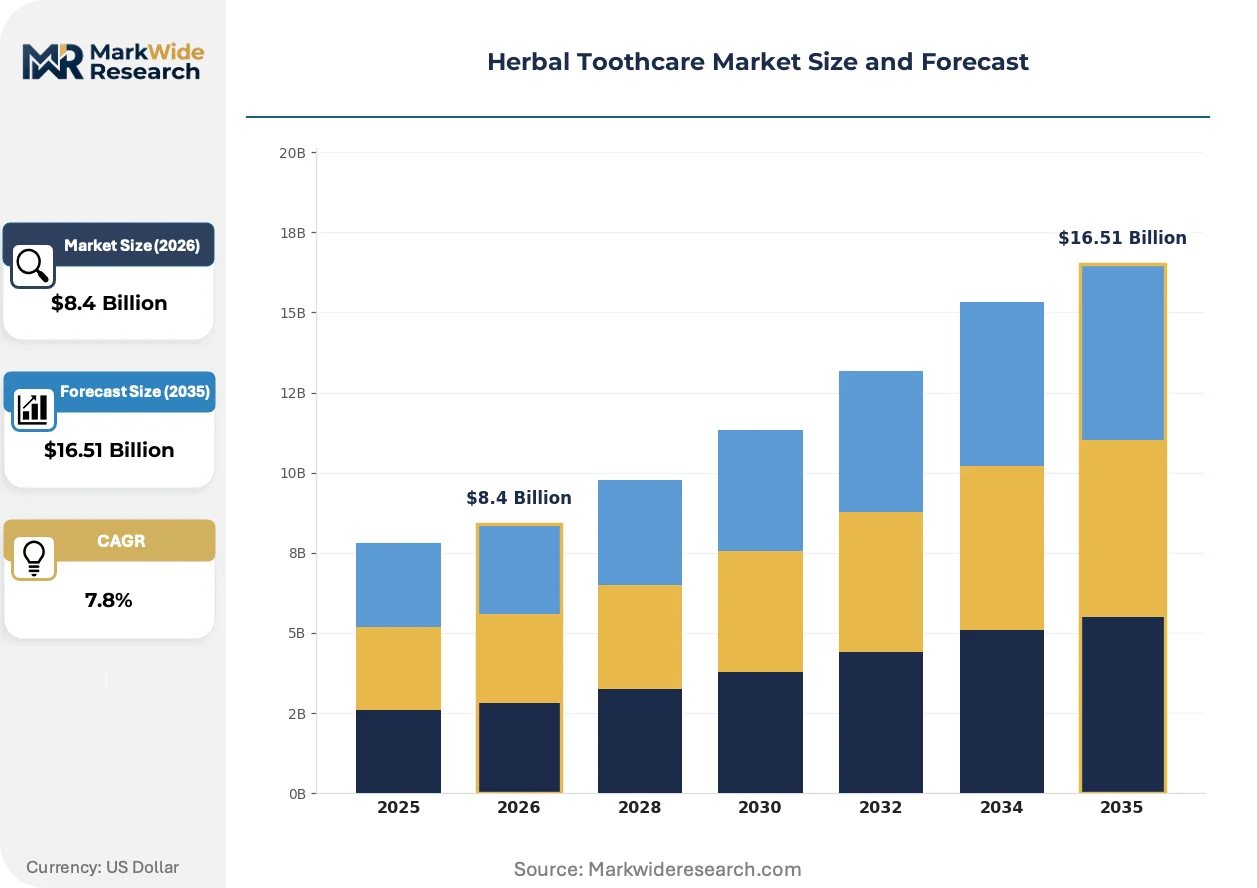
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Chewing Tablets, Powder Ingredient Type: Aloe Vera, Neem, Clove Oil, Tea Tree Oil Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies Consumer Type: Adults, Children, Seniors, Dental Patients |
| Companies Covered | Colgate-Palmolive Company, Patanjali Ayurved Limited, Himalaya Wellness Company, Dabur India Limited, Procter & Gamble, Unilever, GSK plc, Amway Corporation, Vicco Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Toothcare Market Strategic Shifts & Innovations
Waterless formulation technologies and solid delivery systems are compressing packaging requirements while botanical fingerprinting methods reshape quality assurance protocols across herbal oral care manufacturing.
Solid toothpaste tablets utilizing plant-derived binders and effervescent agents is collapsing the conventional tube-and-cap packaging paradigm. Urban Indian professionals and European zero-waste adopters are switching formats at accelerating velocity. This compression eliminates aluminum-plastic laminate waste streams while reducing shipping cube and shelf-space economics.
REACH regulation botanical extract documentation requirements are forcing reformulation investments among Ayurvedic exporters targeting EU natural cosmetics channels. ECHA substance registration thresholds now demand chromatographic fingerprinting for neem and clove oil batches. German and Dutch importers are consolidating supplier bases toward CDSCO-certified Indian manufacturers with in-house analytical capabilities.
Subscription-based replenishment models are displacing conventional supermarket stock-up behavior among metropolitan herbal toothcare consumers. Direct channels capture recurring revenue while bypassing retail slotting fee structures. This shift concentrates most visibly in Bangalore, Mumbai, and Berlin where zero-waste community density supports membership economics.
Herbal Toothcare Market Segmentation
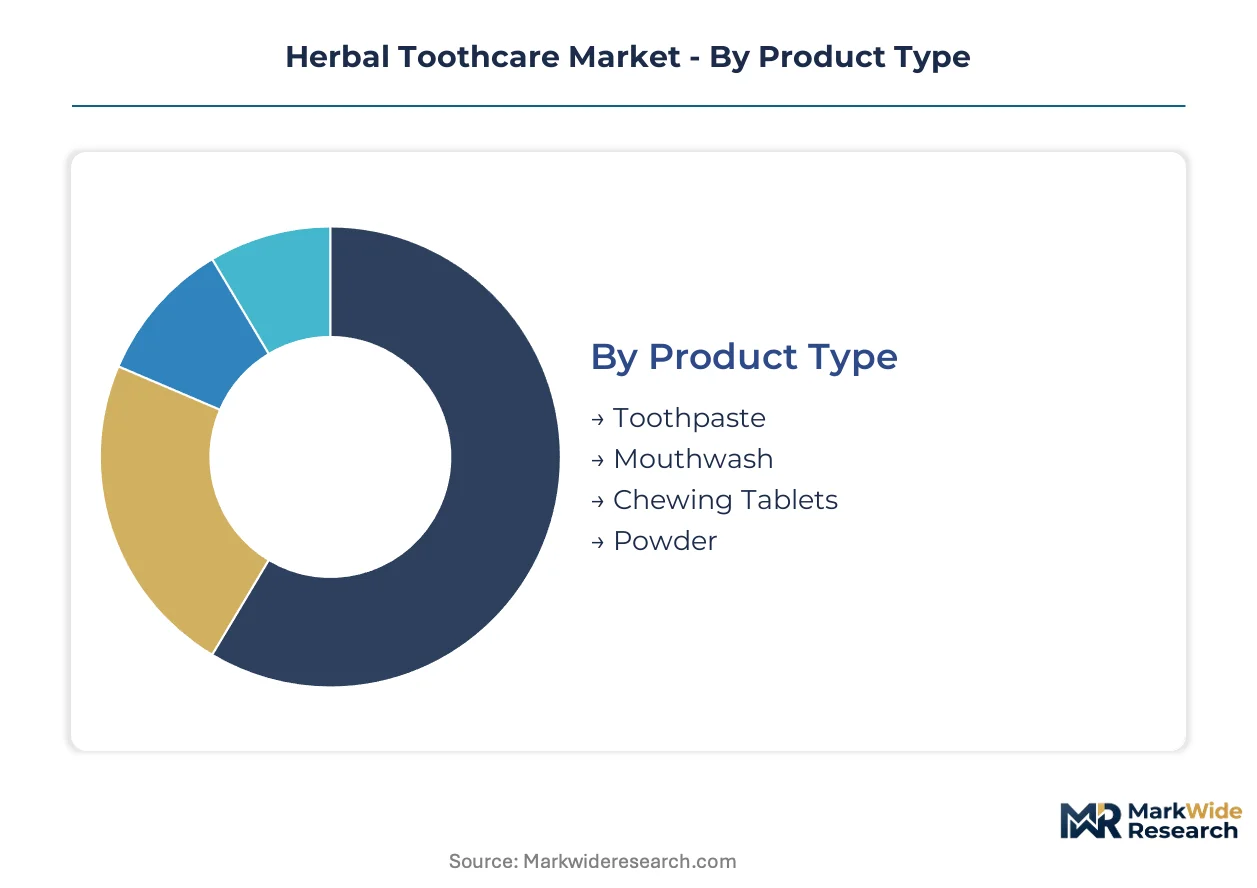
Herbal toothcare segmentation reveals distinct velocity patterns across consumption cycles. Product formats and ingredient sourcing drive replenishment frequency, while channel and consumer type dictate margin capture and regulatory exposure.
Product Type:
Chewing tablets turn inventory fastest among travel-oriented urban consumers, while powders cycle slowest through traditional household pantries.
- Toothpaste:Cream or gel formulations containing botanical extracts and plant-derived abrasives in squeezable tubes or pumps. Pharmacy channels in India and Germany concentrate demand as BIS and REACH certifications validate antimicrobial claims for neem and clove oil variants.
- Chewing Tablets:Solid effervescent tablets utilizing plant-derived binders that activate with saliva. Zero-waste adherents in Berlin and Bangalore drive the steepest expansion trajectory as direct-to-consumer subscriptions displace conventional retail stock-up behavior.
- Mouthwash:Liquid rinses incorporating herbal extracts for antimicrobial action without synthetic preservatives. Hotel amenity programs and dental clinic dispensing represent concentrated demand nodes.
- Powder:Dry abrasive blends of clove, neem, and salt requiring water activation during use. Rural Indian households and Ayurvedic purists sustain this slowest-turning format.
Toothpaste dominates installed base. Chewing tablets is where expansion concentrates.
Ingredient Type:
Margin pools concentrate where supply chain control intersects with recognizable efficacy narratives among Indian producers.
- Neem:Azadirachtin-rich extracts from Azadirachta indica delivering antimicrobial and anti-inflammatory properties. Maharashtra and Gujarat cultivation belts provide captive supply for domestic manufacturers targeting CDSCO-certified pharmacy distribution.
- Aloe Vera:Mucopolysaccharide gels from Aloe barbadensis for soothing gum tissue and reducing inflammation. Southeast Asian pharmacy channels and Middle East halal-certified aisles concentrate demand.
- Clove Oil:Eugenol-dominant essential oil from Syzygium aromaticum with proven analgesic properties. Indonesian and Madagascan supply disruptions transmit directly to formulation cost structures.
- Tea Tree Oil:Terpinen-4-ol rich extracts from Melaleuca alternifolia with broad-spectrum antimicrobial activity. Australian regulatory recognition drives natural cosmetics channel placement.
Neem and aloe vera command the deepest margin pools. Clove oil faces the steepest input volatility.
Distribution Channel:
Channel selection determines regulatory burden intensity and customer acquisition economics simultaneously.
- Pharmacies:Brick-and-mortar and online dispensaries requiring product registration and pharmacist recommendation. India's CDSCO framework and UAE MOHAP pathways filter entrants while validating premium positioning.
- Online:Direct-to-consumer platforms and marketplace listings bypassing conventional retail slotting structures. Subscription models capture recurring revenue from zero-waste metropolitan clusters.
- Supermarkets:Mass-market retail with high shelf visibility and promotional intensity. Price competition limits herbal penetration where conventional fluoride brands dominate.
- Health Stores:Natural and organic specialty retailers with educated consumer bases. German natural cosmetics retail channels impose REACH documentation requirements that consolidate supplier bases.
Pharmacies dominate certified premium volume. Online is where subscription economics concentrate.
Consumer Type:
Risk tolerance and efficacy expectations segment herbal adoption patterns sharply across demographic boundaries.
- Adults:Primary decision-makers with established oral hygiene habits seeking alternatives to synthetic chemicals. Urban Indian millennials and European zero-waste adopters drive format experimentation.
- Dental Patients:Individuals with specific periodontal conditions or post-procedure sensitivity requirements. Prescription-adjacent positioning requires careful cosmetic-therapeutic claim navigation under FDA distinction rules.
- Seniors:Aging consumers with dry mouth conditions and medication-induced oral health challenges. Pharmacy channel trust and familiar ingredient recognition sustain loyalty.
- Children:Pediatric users where parental safety concerns dominate purchase decisions. Fluoride substitution ceilings limit herbal penetration due to clinical efficacy gaps in caries prevention.
Adults dominate current consumption volume. Dental patients represent the most regulated expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes herbal toothcare through pharmacy-certified channels with BIS validation, while Germany sources through REACH-compliant natural cosmetics retail and the United States navigates FDA cosmetic-drug distinction rules.
India
Maharashtra and Gujarat cultivation belts supply azadirachtin-rich neem to domestic formulators. CDSCO tightened Ayurvedic oral care labeling standards in 2023, elevating pharmacy channel trust. Mumbai and Bangalore metropolitan clusters drive chewing tablet subscription adoption among zero-waste professionals.
Germany
Natural cosmetics retail channels in Berlin and Hamburg concentrate demand for botanical fingerprinted extracts. ECHA REACH documentation requirements filter small-batch Ayurvedic exporters, consolidating supplier bases toward CDSCO-certified Indian manufacturers. German importers now require chromatographic batch verification for neem and clove oil formulations.
United States
FDA cosmetic-drug distinction rules determine whether antimicrobial herbal claims trigger pre-market approval pathways. Direct-to-consumer channels bypass conventional retail slotting fees in metropolitan coastal markets. Brooklyn and Austin zero-waste communities represent concentrated tablet format adoption.
United Arab Emirates
MOHAP registration pathways for Ayurvedic products opened premium positioning in halal-certified pharmacy aisles during 2022-2024. Dubai and Abu Dhabi retail corridors validate products through dual certification requirements. Expatriate Indian professionals sustain demand for familiar neem-based formulations.
United Kingdom
Health food retail chains in London and Manchester impose strict botanical sourcing documentation aligned with EU-origin standards post-Brexit. The Medicines and Healthcare products Regulatory Agency monitors cosmetic-therapeutic claim boundaries for clove oil analgesic positioning. Subscription models capture recurring revenue from zero-waste adopters in the Southeast corridor.
Herbal Toothcare Market Key Industry Players
Capability concentration sits with vertically integrated herb cultivators; scale advantage sits with multinational consumer goods conglomerates. The market structures around three tiers: Ayurvedic heritage houses with captive supply chains, global oral care majors with pharmacy channel dominance, and natural cosmetics specialists with zero-waste format innovation. Dominant competitive moves include backward integration into Maharashtra and Gujarat herb belts, plus direct-to-consumer subscription infrastructure buildout.
Among Ayurvedic heritage houses, Patanjali Ayurved Limited and Himalaya Wellness Company exemplify the vertically integrated archetype with in-house neem cultivation networks. Dabur India Limited occupies a position bridging traditional formulation heritage with complete oral care system expansion. These three anchors represent distinct strategic postures: cost leadership through captive supply, premium pharmacy positioning, and portfolio breadth across powder-to-paste format evolution.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Patanjali Ayurved Limited |
| Himalaya Wellness Company |
| Dabur India Limited |
| Procter & Gamble |
| Unilever |
| GSK plc |
| Amway Corporation |
| Vicco Laboratories |
| Others |
Cost & Logistics Intelligence
Maharashtra and Gujarat herb cultivation belts anchor downstream pricing power through captive azadirachtin supply for domestic formulators. CDSCO certification tiers stratify cost structures across pharmacy and mass-market channels.
Pricing Analysis
Long-term offtake contracts with neem cultivators in Maharashtra insulate major formulators from spot market volatility in eugenol-dependent clove oil. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification grade and pharmacy channel validation. Cost compression in economy tiers intensifies because Indonesian supply disruptions transmit directly to clove oil formulations. Price-sensitive rural households favor unbranded powders while pharmacy-certified segments absorb premium positioning.
Supply Chain Analysis
Tariff exposure between Indonesia and India dominates input cost volatility for eugenol-dependent formulations. India, Madagascar, and Indonesia supply 90% of clove oil and neem extract feedstocks. Raw material dependencies rest on azadirachtin-rich neem bark, eugenol-dominant clove bud oil, and aloe vera mucopolysaccharide gels. Single-source vulnerability in Madagascan clove harvests compounds margin pressure. Distribution runs through CDSCO-certified pharmacy networks and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoride-free synthetic alternatives pose substitution pressure that heritage Ayurvedic formulators must neutralize through efficacy validation and certification investment.
For Market Incumbents: Harden pharmacy channel control through CDSCO registration depth and backward integration into Gujarat neem cultivation corridors. Neutralize fluoride substitution threats by commissioning clinical efficacy studies for caries prevention claims. Certification moat investment is the defensive priority. For New Entrants and Emerging Players: UAE pharmacy aisles underpenetrated by CDSCO-certified Ayurvedic brands offer halal-certified positioning white space. Target Berlin zero-waste subscription clusters with solid tablet formats bypassing REACH documentation barriers. Direct-to-consumer replenishment models minimize slotting fee exposure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated herb cultivators with in-house chromatographic fingerprinting capabilities. Five-to-ten year viability hinges on regulatory consolidation toward CDSCO-certified manufacturers. Watch ECHA REACH threshold tightening as inflection signal for supplier base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Herb Cultivation | Maharashtra and Gujarat captive supply secures azadirachtin cost advantage against volatile Indonesian clove oil. |
| CDSCO Certification Investment | Pharmacy channel registration elevates consumer trust and filters economy-tier competitors from premium positioning. |
| Direct-to-Consumer Subscription Launch | Bangalore and Berlin metropolitan clusters support recurring revenue capture outside supermarket slotting structures. |
| REACH-Compliant Botanical Fingerprinting | Chromatographic batch verification opens German natural cosmetics retail to Ayurvedic exporters. |
| Halal Certification Pathway | MOHAP registration unlocks UAE and Saudi Arabia pharmacy premium positioning for heritage formulations. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with Ayurvedic formulators, pharmacy procurement managers, and CDSCO regulatory affairs specialists; and secondary validation through BIS certification databases, CDSCO product registries, and customs import records for clove oil and neem extract trade flows. Bottom-up triangulation against top-down market sizing cross-validated segment-level estimates.
Forecast inputs considered product format evolution, ingredient substitution patterns, and channel migration dynamics across the analysis window. Segmentation dimensions modeled include product type, ingredient category, distribution channel, and consumer risk tolerance. CAGRs derived from regression analysis of historical pharmacy sales velocity and subscription adoption curves in metropolitan clusters.
Practitioners should monitor regulatory reclassification of cosmetic-therapeutic claim boundaries and ECHA REACH threshold adjustments for early signals. Forecasts reflect assumptions on certification pathway stability and herb cultivation yield consistency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
GCC Oral Hygiene Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
BRICS Oral Care Market
Oral Care
Global Oral Hygiene Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Kids Oral Care Products Market
Oral Care
Global Oral Care Products Market
Oral Care
Global Halitosis Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Oral Hygiene Products Market
Oral Care
Baby Teeth Care Products Market
Oral Care
China Oral Care Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Oral Irrigator Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
South America Oral Care Market