
 Mouth Sore Medicine Market | 2026-2036
Mouth Sore Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Mouth Sore Medicine Market Insights
North American pharmaceutical manufacturing capacity is shifting toward higher-margin prescription formulations as generic commoditization squeezes over-the-counter margins. GlaxoSmithKline plc leverages its respiratory and oral health heritage to sustain brand loyalty in pharmacy channels. Johnson & Johnson anchors the consumer shelf with broad retail distribution and pediatric trust. Pfizer Inc. competes through hospital and dental clinic detailing for its prescription portfolio.
Mouth sore medicine encompasses topical, oral, and systemic therapeutic agents designed to alleviate pain, reduce inflammation, and accelerate healing of aphthous ulcers, cold sores, and traumatic oral lesions, typically formulated with active concentrations of corticosteroids, local anesthetics, or antiseptics in bioadhesive bases that prolong mucosal contact. These products serve both acute symptomatic relief and chronic management protocols in dental, oncology, and immunocompromised patient populations. Topical gels command the largest revenue share due to superior patient compliance and targeted delivery, while oral rinses represent the fastest-expanding category as clinicians emphasize whole-mouth coverage for chemotherapy-induced mucositis. The lidocaine active ingredient segment captures premium pricing in hospital settings where rapid onset anesthesia proves critical.
The FDA oversees OTC benzocaine labeling and pediatric risk mitigation, while the EMA's MDR framework imposes stricter clinical evidence requirements for CE-marked oral care devices and drug-device combinations in Europe. These dual regulatory tracks elevate R&D costs for multinational entrants but simultaneously protect validated formulations from low-cost substitution. Stakeholders must monitor evolving pharmacovigilance signals and reimbursement pathways for prescription-grade therapies as the boundary between cosmetic oral care and medical treatment continues to blur.
Market Dynamics
The FDA's benzocaine pediatric safety review is forcing immediate reformulation toward lidocaine-based alternatives, compressing development timelines and elevating clinical evidence requirements across prescription and over-the-counter portfolios.
Growth Catalysts
- Oncology mucositis protocols:Chemotherapy-induced oral lesions now mandate prophylactic topical therapy in hospital formularies, expanding prescription volumes for bioadhesive anesthetic gels.
- EMA MDR framework:Stricter clinical evidence requirements for CE-marked oral care devices protect validated formulations from low-cost substitution, sustaining premium pricing for compliant entrants.
- Dental clinic consolidation:Specialist networks in the United States are standardizing prescription-grade topical therapies across multi-site practices, concentrating procurement volume.
Market Restraints
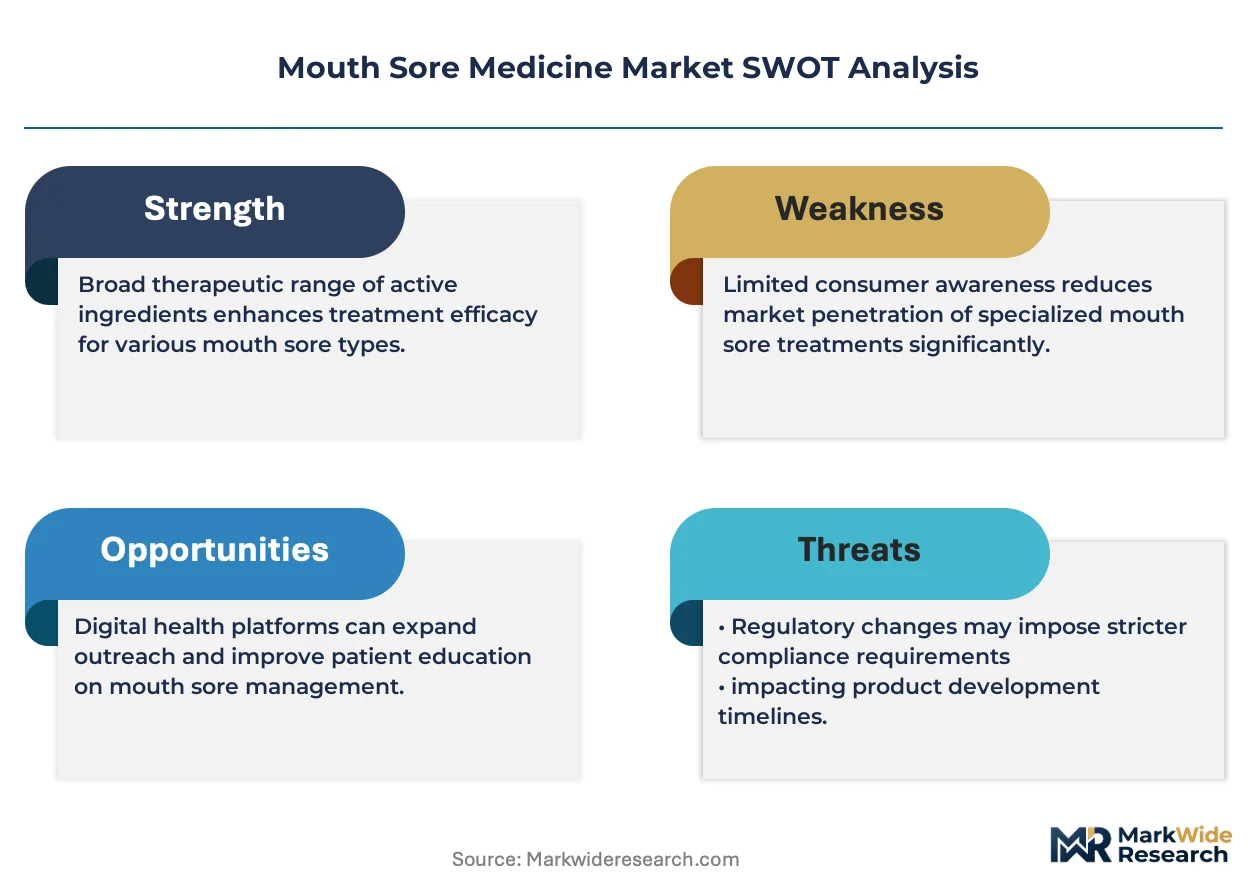
- Active ingredient supply concentration:Pharmaceutical-grade lidocaine API production clusters in India and China, exposing formulators to geopolitical friction and import inspection delays.
- Generic commoditization:Over-the-counter benzocaine gels face margin compression as private-label entrants replicate bioadhesive bases without therapeutic differentiation.
- Reimbursement pathway fragmentation:Medicare Part D and commercial pharmacy benefit managers apply inconsistent prior authorization criteria for prescription mouth sore therapies, delaying patient access.
Strategic Opportunities
- Immunocompromised outpatient management:HIV and transplant patient populations remain underserved by current retail-focused distribution, creating white space for specialty pharmacy partnerships.
- Digital health integration:Tele-dental platforms are integrating symptom-triage algorithms that direct patients toward prescription-grade therapies, opening direct-to-patient channels.
- Biologics convergence:Combination therapies pairing corticosteroids with growth factor peptides are entering Phase II trials, targeting accelerated lesion healing beyond symptomatic relief.
Industry Challenges
- Formulation stability expertise:Bioadhesive polymer science and mucosal permeation enhancement require specialized talent scarce outside established oral health R&D clusters.
- Dual-track regulatory navigation:Companies must simultaneously satisfy FDA OTC monograph requirements and prescription NDA pathways, duplicating clinical development costs.
- Legacy distribution contracts:Long-term pharmacy benefit manager agreements lock incumbent brands into unfavorable rebate structures that resist renegotiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mouth Sore Medicine Market |
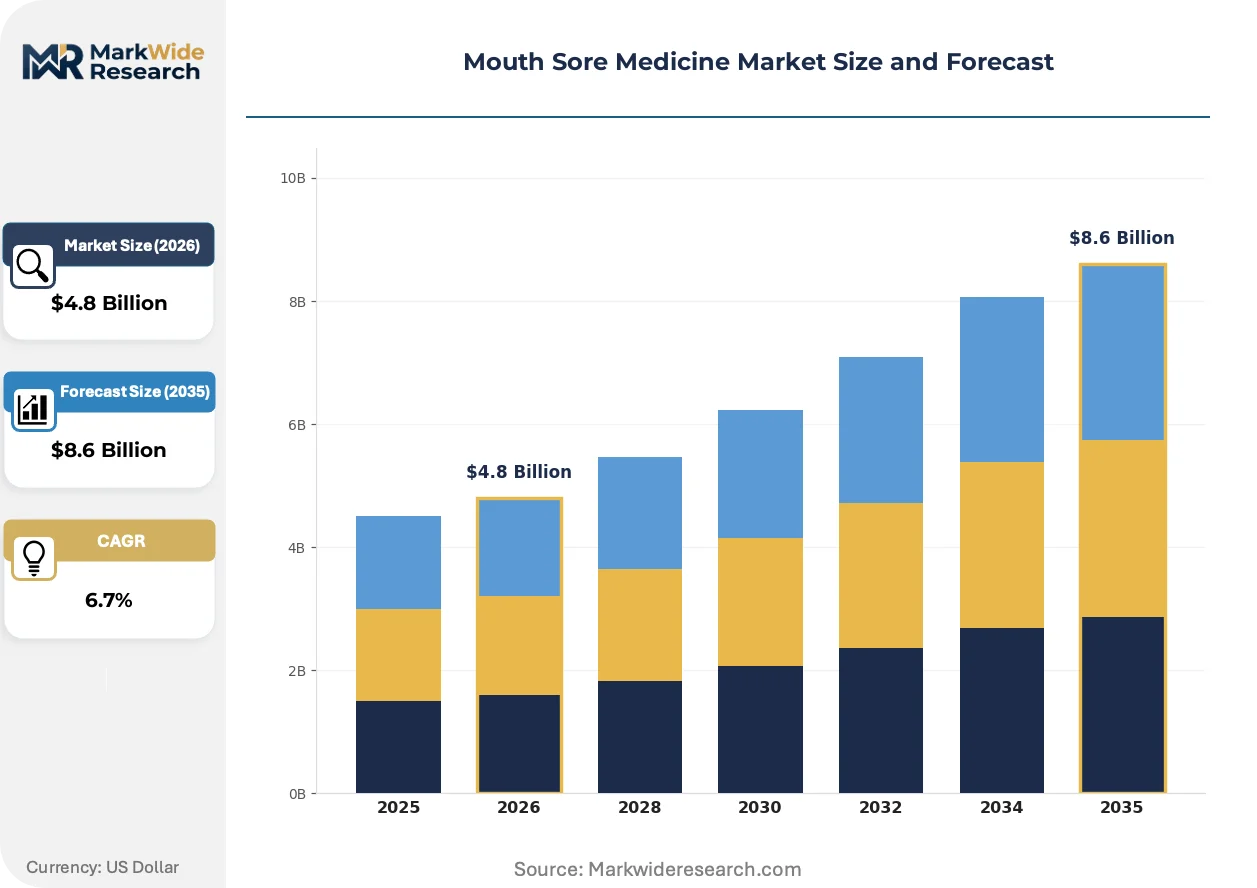
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Gels, Oral Rinses, Tablets, Sprays Active Ingredient: Fluocinonide, Benzocaine, Lidocaine, Chlorhexidine End User: Hospitals, Dental Clinics, Pharmacies, Home Care Formulation: Liquid, Ointment, Cream, Powder |
| Companies Covered | 3M Company, Blistex Inc., Church & Dwight Co., Inc., Colgate-Palmolive Company, GlaxoSmithKline plc, Pfizer Inc., Bristol-Myers Squibb Company, Johnson & Johnson, Reckitt Benckiser Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mouth Sore Medicine Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how mouth sore therapies reach patients, with mucosal adhesion technology and channel disintermediation operating as parallel transformation vectors.
Hydrogel matrix systems containing chitosan-derivatized polymers are integrating sustained-release lidocaine into single-application doses that maintain therapeutic concentrations for six to eight hours. Hospital oncology units are adopting these platforms for chemotherapy-induced mucositis, displacing multi-dose rinse protocols that compromise patient compliance. The technology is integrating pain management and healing acceleration into unified treatment protocols that reduce nursing intervention frequency.
REACH authorization requirements for polymer-based drug-device combinations are extending toxicological evaluation timelines for European market entrants, elevating documentation costs but simultaneously filtering substandard competitors. Manufacturers are responding by front-loading clinical pharmacokinetic studies to secure CE marking ahead of MDR transition deadlines. Oral rinse categories face the steepest compliance burden due to systemic absorption concerns.
Direct-to-consumer pharmacy channels are capturing prescription mouth sore volumes previously routed through physician offices, with patients initiating therapy via asynchronous telehealth consultations. This pattern concentrates in the United States where regulatory frameworks accommodate remote prescribing for topical anesthetics. Dental clinic networks are countering by embedding e-prescribing into practice management software to retain formulary control.
Mouth Sore Medicine Market Segmentation
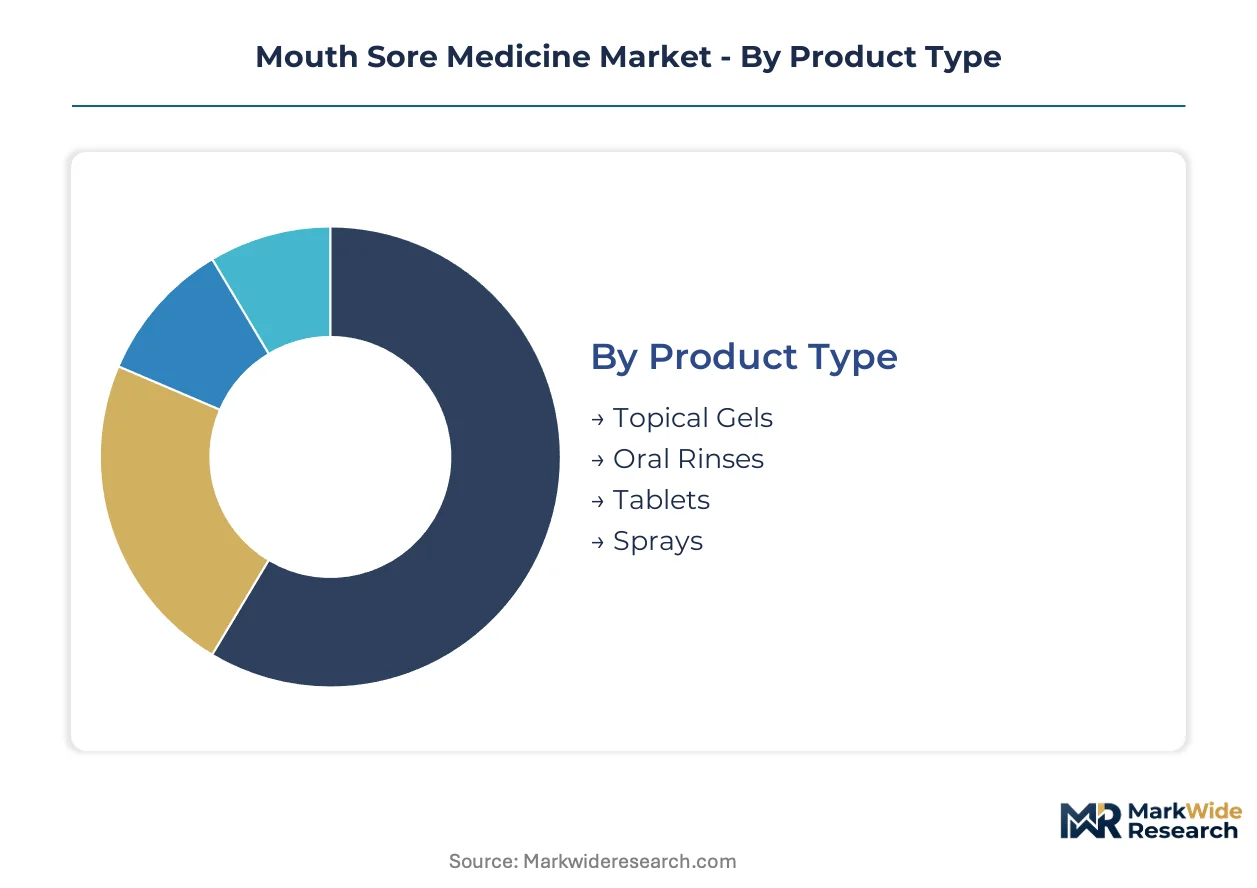
Mouth sore medicine segmentation reveals how formulation technology, clinical setting, and patient self-management preferences create distinct commercial battlegrounds. Product type and active ingredient selections directly determine reimbursement pathways and margin structures across hospital, dental, and retail channels.
Product Type:
Bioadhesive delivery mechanisms and mucosal contact duration differentiate competitive positioning across physical formats.
- Topical Gels:Hydrogel matrix systems with chitosan-derivatized polymers sustain therapeutic concentrations for six to eight hours through prolonged mucosal adhesion. Hospital oncology units in the United States favor these platforms for chemotherapy-induced mucositis, displacing multi-dose protocols that burden nursing staff.
- Oral Rinses:Whole-mouth coverage formulations address diffuse lesions and prophylactic protocols. Clinician emphasis on comprehensive mucosal protection in cancer care centers drives the steepest expansion trajectory for this category.
- Tablets:Systemic corticosteroid and analgesic combinations serve recurrent aphthous ulcer patients requiring chronic management.
- Sprays:Metered-dose topical anesthetics target posterior oral lesions where gel application proves difficult.
Mature deployment sits with Topical Gels. Newer deployment is concentrated in Oral Rinses.
Active Ingredient:
Regulatory pressure on pediatric safety and hospital formulary requirements reshape ingredient selection priorities.
- Lidocaine:Rapid-onset amide anesthetic dominates hospital procurement where procedure-related pain management demands predictable pharmacokinetics. FDA benzocaine safety reviews accelerate lidocaine adoption across prescription and OTC portfolios.
- Benzocaine:Ester-based anesthetic faces reformulation mandates due to methemoglobinemia risk in pediatric populations. Supply chains concentrate in Indian and Chinese API manufacturers exposed to import inspection volatility.
- Fluocinonide:High-potency corticosteroid addresses inflammatory ulcerative conditions through immunosuppressive action.
- Chlorhexidine:Antiseptic agent reduces secondary infection risk in traumatic and immunocompromised oral lesions.
Established clinical acceptance centers on Lidocaine. Accelerated transition is underway toward this segment from Benzocaine.
End User:
Channel control and prescription authority determine pricing power and patient access friction.
- Hospitals:Oncology and immunocompromised patient volumes drive bioadhesive anesthetic gel procurement through centralized formularies. Prior authorization requirements from Medicare Part D and commercial pharmacy benefit managers create access delays.
- Dental Clinics:Specialist network consolidation in the United States standardizes prescription-grade topical therapies across multi-site practices, concentrating procurement volume.
- Pharmacies:Direct-to-consumer channels capture prescription volumes previously routed through physician offices via asynchronous telehealth consultations.
- Home Care:Self-directed management of recurrent minor aphthous ulcers sustains OTC benzocaine and lidocaine gel demand.
Volume concentration rests with Dental Clinics. Channel expansion is gaining share fastest in Pharmacies.
Formulation:
Physical state dictates manufacturing complexity, stability requirements, and patient compliance profiles.
- Liquid:Rinse and spray vehicles enable whole-mouth distribution with minimal patient technique. EMA MDR framework imposes extended toxicological evaluation timelines for European market entrants due to systemic absorption concerns.
- Ointment:Occlusive petrolatum-based bases protect lesions from mechanical irritation and salivary washout.
- Cream:Aqueous-phase emulsions offer cosmetic acceptability for facial cold sore applications.
- Powder:Lyophilized or micronized formats serve specialized compounding pharmacies and exotic delivery research.
Commercial maturity aligns with Liquid formulations. Emerging interest concentrates in Powder for novel delivery platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade lidocaine API production clusters in Indian and Chinese manufacturing hubs, exposing formulators to geopolitical friction and import inspection delays that reshape procurement geography.
United States
Dental clinic consolidation concentrates prescription-grade topical therapy procurement through multi-site specialist networks. The FDA's ongoing benzocaine pediatric safety review accelerates lidocaine-based reformulation across OTC and prescription portfolios. Greater Boston and Research Triangle Park host bioadhesive polymer R&D clusters developing sustained-release mucosal delivery systems.
Germany
EMA MDR framework implementation elevates clinical evidence requirements for CE-marked oral care devices, filtering substandard competitors from European market entry. REACH authorization mandates extend toxicological evaluation timelines for polymer-based drug-device combinations. Baden-Württemberg's pharmaceutical manufacturing corridor specializes in high-potency corticosteroid formulations for inflammatory ulcerative conditions.
India
API manufacturing dominance in pharmaceutical-grade lidocaine exposes global formulators to CDSCO export certification delays and geopolitical supply friction. The PLI scheme incentivizes domestic formulation finishing capacity expansion for oncology mucositis therapies. Hyderabad and Mumbai anchor contract development and manufacturing organization clusters serving European and North American markets.
China
NMPA regulatory harmonization pressures domestic manufacturers toward international GMP standards for lidocaine API export certification. Dual carbon goals accelerate energy-intensive pharmaceutical intermediate production consolidation in coastal provinces. Yangtze River Delta chemical parks specialize in amide anesthetic precursor synthesis for global supply chains.
Japan
PMDA post-market surveillance requirements for topical oral anesthetics sustain premium pricing for validated bioadhesive formulations. METI industrial policy supports mucosal permeation enhancement technology development through university-industry consortia. Kansai region pharmaceutical clusters focus on pediatric-safe lidocaine delivery systems for aging population oral care needs.
Mouth Sore Medicine Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution channel control. The market structure consolidates around three tiers: diversified consumer health conglomerates with pharmacy shelf dominance, prescription-focused pharmaceutical specialists with hospital detailing capabilities, and private-label commoditizers squeezing OTC margins. Strategic archetypes include brand-loyalty sustainers leveraging heritage oral health positioning, formulary integrators embedding e-prescribing into dental practice management software, and API-backward-integrated manufacturers securing active ingredient supply. Competitive moves concentrate on M&A-driven portfolio diversification and strategic partnerships with tele-dental platforms for direct-to-patient channel access.
Within the diversified consumer health tier, Johnson & Johnson and Church & Dwight Co., Inc. exemplify archetypes anchored by broad retail distribution networks and pediatric trust positioning. GlaxoSmithKline plc occupies a position representing heritage brand loyalty sustainers in pharmacy channels. Pfizer Inc. exemplifies the prescription pharmaceutical specialist archetype with hospital and dental clinic detailing capabilities. Reckitt Benckiser Group plc represents the European-based consumer health consolidator model.
| Leading Market Players |
|---|
| 3M Company |
| Blistex Inc. |
| Church & Dwight Co., Inc. |
| Colgate-Palmolive Company |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Reckitt Benckiser Group plc |
| Others |
Pricing and Supply Chain Analysis
Prescription-grade bioadhesive gel certification against commodity benzocaine OTC alternatives creates a bifurcated margin architecture that simultaneously rewards FDA-validated formulations with premium hospital procurement contracts while exposing undifferentiated private-label entrants to relentless cost compression in retail pharmacy channels. This tier divergence manifests in supply chain configurations where lidocaine API sourcing concentrates in Indian and Chinese pharmaceutical hubs for premium segments, whereas commodity ester-anesthetic production feeds distributed compounding networks serving price-sensitive home care segments.
Pricing Analysis
Service bundling separates hospital formulary contracts that embed clinical training and adverse event monitoring from unbundled retail transactions where patients bear full substitution risk. Three-tier pricing structure across premium bioadhesive hospital gels, standard dental clinic prescriptions, and economy OTC benzocaine tubes reflects FDA pediatric safety tier differentiation and active ingredient pharmacokinetic performance. Pricing pressure stems from generic commoditization in OTC channels as private-label entrants replicate bioadhesive bases without therapeutic differentiation. Home care segments exhibit highest price sensitivity, while oncology hospital procurement demonstrates lowest sensitivity due to bundled outcome guarantees and nursing labor cost offsets.
Supply Chain Analysis
Single-source vulnerability sits with pharmaceutical-grade lidocaine API production concentrated in Indian CDSCO-certified facilities and Chinese NMPA-regulated chemical parks. Active ingredient dependencies include amide anesthetic precursors, chitosan-derivatized polymer bioadhesives, and corticosteroid raw materials. Tariff exposure and import inspection delays at US ports create supply friction that elevates working capital requirements for North American formulators. Distribution runs through specialist dental network group purchasing organizations for prescription volumes, direct-to-consumer pharmacy channels for asynchronous telehealth prescriptions, and mass retail merchandisers for OTC home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mouth sore medicine sector is navigating a technology-transition phase as sustained-release hydrogel matrix systems displace multi-dose rinse protocols in hospital oncology units, fundamentally altering formulation R&D priorities and procurement specifications across the care continuum.
For Market Incumbents: Anticipate accelerated lidocaine API cost volatility by securing backward integration into Indian pharmaceutical manufacturing or long-term offtake agreements with Hyderabad and Mumbai contract development organizations. Defensive consolidation should prioritize e-prescribing integration with dental practice management software to retain formulary control against tele-dental platform disintermediation. FDA benzocaine pediatric safety mandates threaten legacy OTC portfolio margins, necessitating rapid reformulation investment or portfolio divestiture.
For New Entrants and Emerging Players: Tele-dental platform symptom-triage algorithm partnerships offer a technology-first wedge into prescription-grade topical therapy distribution without legacy pharmacy benefit manager rebate obligations. Immunocompromised outpatient management through specialty pharmacy partnerships represents the most penetrable white space, as HIV and transplant patient populations remain underserved by retail-focused distribution architectures. Go-to-market execution should emphasize asynchronous telehealth consultation integration with direct-to-patient fulfillment.
For Investors and Strategic Acquirers: Re-rating potential sits with bioadhesive polymer specialists possessing mucosal permeation enhancement IP given EMA MDR framework compliance premiums and REACH authorization barriers filtering substandard competitors. Long-term viability across the projection horizon favors acquisition targets with validated CE marking pathways and hospital formulary anchoring in oncology mucositis protocols. The signal to watch is biologics convergence trial readouts pairing corticosteroids with growth factor peptides, which would reshape competitive moats beyond symptomatic relief toward healing acceleration claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Convergence Partnership | Phase II trials pairing corticosteroids with growth factor peptides target healing acceleration beyond symptomatic relief. |
| Tele-Dental Platform Integration | Symptom-triage algorithm embedding directs patients toward prescription-grade therapies through asynchronous consultations. |
| EMA MDR Compliance Front-Loading | Clinical pharmacokinetic studies secure CE marking ahead of transition deadlines, filtering substandard competitors. |
| Lidocaine API Supply Anchoring | Long-term offtake agreements with Indian CDSCO-certified manufacturers mitigate geopolitical friction and inspection delays. |
| Specialty Pharmacy Channel Development | Partnerships for immunocompromised outpatient management address underserved HIV and transplant patient populations. |
Research Methodology
Multi-period observation of FDA benzocaine safety review timelines, EMA MDR transition compliance rates, and hospital formulary adoption curves anchored the trend analysis, supplemented by interviews with drug development executives at diversified consumer health conglomerates, regulatory affairs leads navigating dual-track OTC monograph and prescription NDA pathways, formulary directors at consolidated dental specialist networks, and hospital procurement managers in oncology units. Secondary validation drew from FDA Orange Book filings, EMA centralized procedure assessment reports, ClinicalTrials.gov biologics convergence trial registrations, and CMS Medicare Part D prior authorization criteria databases. Bottom-up demand modeling across patient population segments triangulated against top-down pharmaceutical manufacturer revenue attribution.
Segment-weighting approaches distributed value estimates across product type dimensions including bioadhesive gel, oral rinse, tablet, and spray formulations; active ingredient categories spanning lidocaine, benzocaine, fluocinonide, and chlorhexidine; and end user channels encompassing hospitals, dental clinics, pharmacies, and home care. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory inflection points and technology substitution rates. Industry-specific forecast inputs incorporated bioadhesive polymer R&D pipeline maturation timelines and tele-dental platform patient acquisition cost trajectories across the analysis window.
Several conditions sit outside the modeled scope, including unforeseen FDA pediatric safety rulemaking outcomes, geopolitical disruption of Indian and Chinese API export certification flows, and breakthrough biologics convergence trial failures. Forecasts reflect assumptions regarding regulatory timeline adherence, supply chain continuity, and technology adoption elasticity that may require revision. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Kids Oral Care Products Market
Oral Care
Global Oral Care Products Market
Oral Care
Oral Thrush Market
Oral Care
Mouthwash Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Adult Oral Care Products Market
Oral Care
Baby Oral Care Market
Oral Care
Oral Rinse Market
Oral Care
Oral Care Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Global Oral Hygiene Market
Oral Care
Canker Sores Treatment Market
Oral Care
Oral Antiseptics Market
Oral Care
Herbal Toothpaste Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Halitosis Treatment Market