
 Optical Time-Domain Reflectometer Market | 2026-2036
Optical Time-Domain Reflectometer Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Time-Domain Reflectometer Market Analytics
IEC 61746 calibration compliance is redrawing competitive boundaries in the OTDR sector. EXFO Inc. leverages its vertically integrated manufacturing in Quebec to sustain precision calibration capabilities. Viavi Solutions Inc. anchors its position through dense channel partnerships with tier-one telecom providers across North America.
An optical time-domain reflectometer injects laser pulses into optical fiber and analyzes backscattered and reflected light to characterize loss, splice points, and fault locations with spatial resolution typically ranging from sub-meter to tens of meters depending on pulse width and averaging time. Portable OTDR units command the largest revenue share due to field technician mobility requirements in outside-plant environments. Handheld OTDR configurations represent the fastest-expanding product category as 5G fronthaul and FTTH deployments multiply access-network testing volumes.
FCC Part 15 emissions rules in the United States, CE marking requirements under the EU Radio Equipment Directive, and China's GB/T 15972 fiber measurement standards collectively shape product certification timelines and market entry costs. NIST-traceable calibration mandates in federal procurement further segment vendor eligibility for government agency contracts. Stakeholders must weigh modular platform architectures against dedicated single-function instruments as network complexity escalates.
Market Dynamics
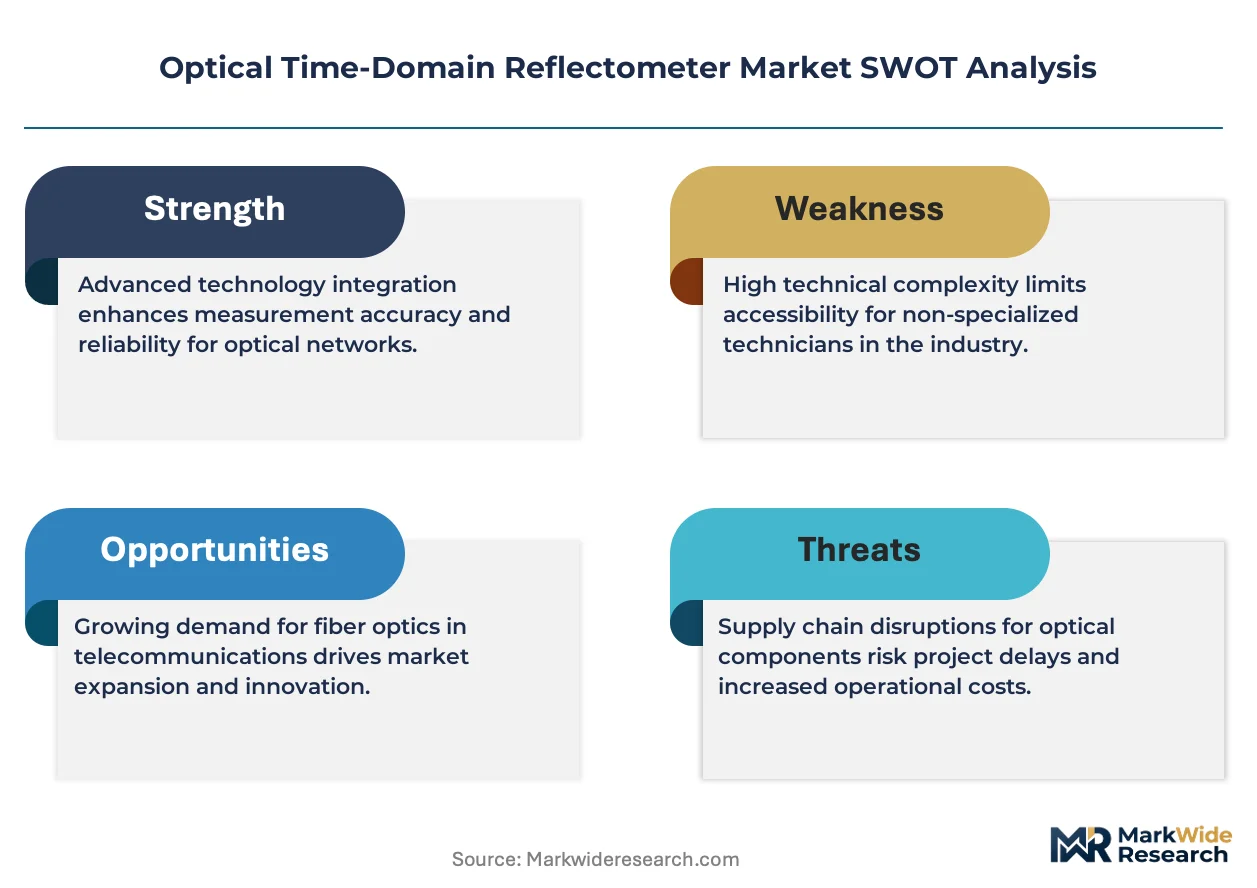
IEC 61746 calibration mandates are compressing vendor margins while simultaneously erecting barriers against low-cost entrants lacking NIST-traceable laboratory infrastructure. Telecom providers now specify certified instruments in procurement tenders, forcing calibration capability investments across the supply base.
Growth Catalysts
- 5G Fronthaul Deployment:China's MIIT spectrum allocations drive massive fiber-to-the-antenna installations requiring portable OTDR verification at every cell site.
- FTTH Mandates:The European Commission's Gigabit Infrastructure Act compels member states to accelerate passive optical network rollouts.
- Dual Carbon Goals:China's MEE efficiency standards favor fiber optic infrastructure over copper, amplifying measurement instrument demand across state-owned carriers.
Market Restraints
- Indium Phosphide Cost Volatility:Laser source material prices fluctuate with compound semiconductor foundry capacity constraints in Taiwan and South Korea.
- Calibration Infrastructure Concentration:NIST-traceable laboratories cluster in Germany, Japan, and the United States, creating geographic bottlenecks for Asian manufacturers seeking certification.
- Optical Time-of-Flight Limitations:Dead zones following reflective events restrict fault location accuracy in high-density ribbon fiber applications.
Strategic Opportunities
- Rural India Broadband:The BharatNet Phase III expansion targets 361,000 gram panchayats with optical fiber, creating unserved demand for ruggedized handheld units.
- AI-Assisted Fault Classification:Machine learning algorithms trained on OTDR trace databases are automating technician interpretation, enabling skill-scarce markets.
- Cloud-Connected Instruments:WiFi-enabled OTDRs streaming to centralized analytics platforms are opening subscription-based service revenue streams.
Industry Challenges
- Photonics Technician Scarcity:Fiber optic splicing and measurement expertise concentrates among aging workforces in North America and Western Europe.
- Multi-Standard Certification Burden:Simultaneous FCC Part 15, CE marking, and GB/T 15972 compliance extends product launch timelines by 8-14 months.
- Legacy Network Integration:Hybrid copper-fiber environments demand dual-mode instruments, complicating firmware architecture and field training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Time-Domain Reflectometer Market |
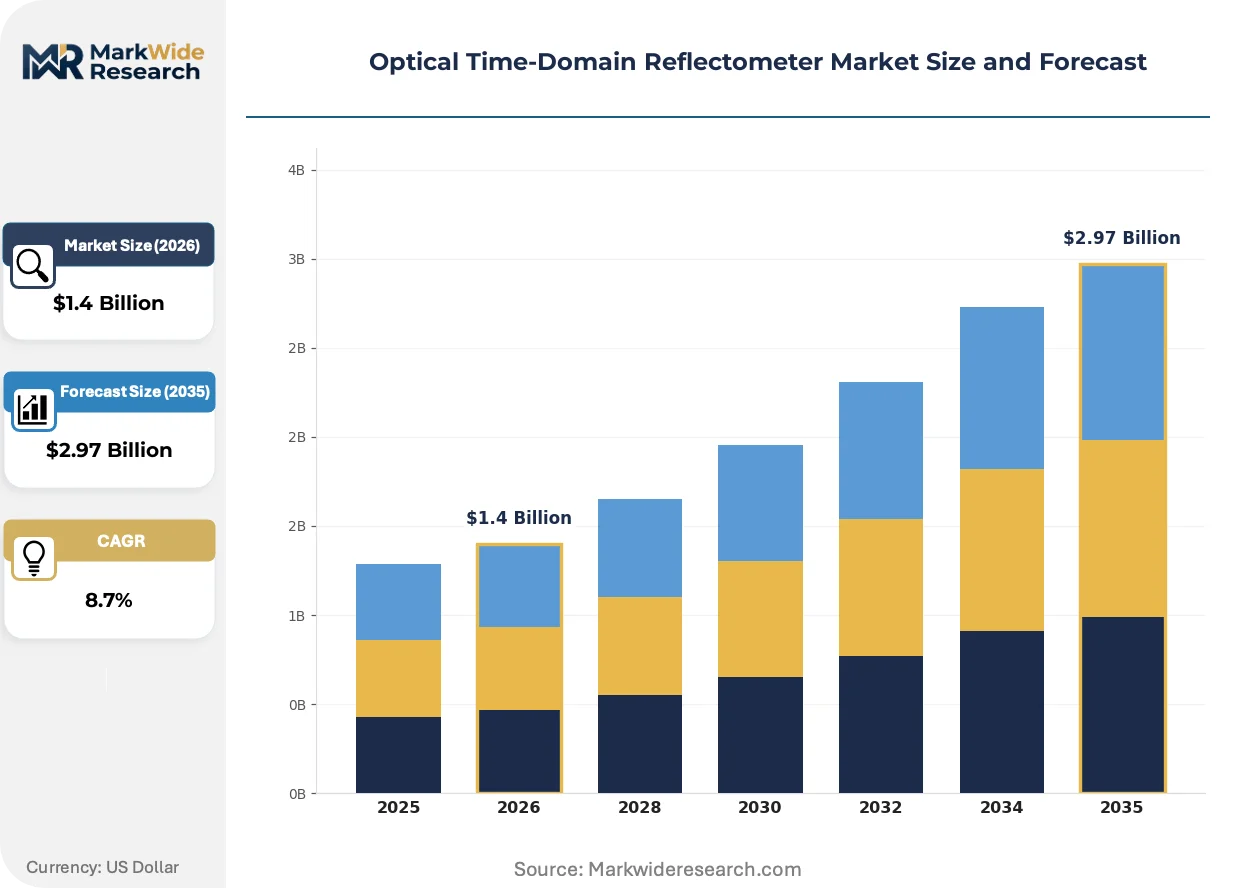
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable OTDR, Handheld OTDR, Fixed OTDR, Fiber Channel OTDR Technology: Active Technology, Passive Technology, Hybrid Technology, Digital Signal Processing End User: Telecom Providers, Government Agencies, Utility Companies, Research Institutions Application: Network Installation, Maintenance Services, Fault Location, System Monitoring |
| Companies Covered | EXFO Inc., Viavi Solutions Inc., Anritsu, Yokogawa Test & Measurement Corporation, Fluke Networks, TEKTRONIX, INC., AFL, Keysight Technologies, VeEX Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Time-Domain Reflectometer Market Evolving Landscape
Real-time fiber monitoring architectures are migrating from reactive break-fix models toward predictive maintenance systems embedded in network management platforms. This shift demands OTDR hardware capable of continuous unattended operation.
Coherent detection OTDR technology is supplanting conventional direct-detection architectures in submarine cable and long-haul terrestrial applications. Submarine system operators including Transco and regional carriers across the Mediterranean basin are specifying coherent instruments for 10,000+ kilometer link characterization. The technology is compressing measurement time from hours to minutes while revealing polarization-mode dispersion signatures invisible to legacy platforms.
The EU Radio Equipment Directive's 2024 cybersecurity annex imposes hardware security module requirements on connected test equipment. OTDR manufacturers serving European telecom providers must now integrate secure boot architectures and encrypted firmware update channels. Handheld product lines face the steepest compliance burden as field-replaceable batteries and USB ports create attack surfaces.
Telecom procurement departments are consolidating test equipment vendors through framework agreements spanning multiple instrument categories. Tier-one carriers in Germany and France now award single-source contracts covering OTDRs, optical power meters, and fiber inspection scopes. This concentration pressures mid-tier manufacturers to specialize or exit, while rewarding suppliers with broad optical test portfolios and established calibration service networks.
Optical Time-Domain Reflectometer Market Segmentation
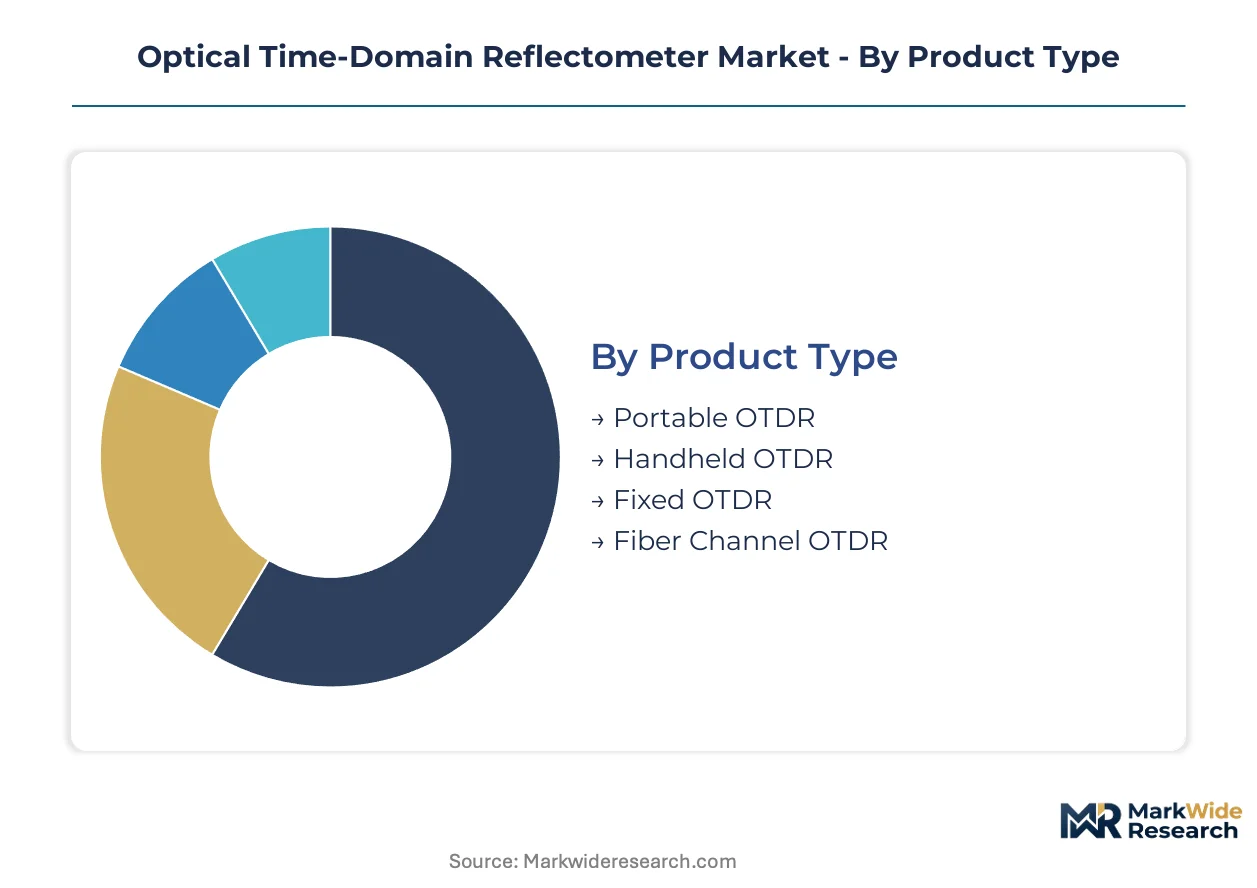
OTDR purchasing decisions hinge on deployment environment constraints, with regulatory calibration mandates and field mobility requirements creating distinct procurement profiles across product configurations. Segmentation reveals how vendor specialization aligns with divergent technical specifications and end-user operational models.
Product Type:
FCC Part 15 emissions compliance and IEC 61746 calibration portability requirements fragment product development roadmaps, forcing manufacturers to optimize for either laboratory precision or field ruggedization.
- Portable OTDR:These units balance bench-grade measurement accuracy with transit-ready enclosures, typically weighing under 5 kilograms with battery operation exceeding 8 hours. Demand concentrates among outside-plant contractors in Germany and Japan where utility tunnel inspections require NIST-traceable loss measurements without fixed-site infrastructure.
- Handheld OTDR:Pocket-sized configurations with simplified one-button operation and smartphone-grade displays dominate China's 5G fronthaul buildout, where crews verify fiber-to-the-antenna drops across thousands of cell sites monthly. The steepest expansion trajectory belongs to this segment as FTTH access networks multiply testing volumes.
- Fixed OTDR:Rack-mounted systems with continuous monitoring capabilities serve submarine cable landing stations and data center interconnect facilities.
- Fiber Channel OTDR:Specialized units optimized for storage area network verification target enterprise data center operators in the United States.
Established volume favors Portable OTDR; emerging adoption favors Handheld OTDR.
Technology:
Cost tier differentiation separates high-performance coherent detection architectures from commodity direct-detection platforms, with hybrid approaches capturing mid-market applications.
- Active Technology:Conventional laser-pulse architectures with real-time trace analysis dominate maintenance service contracts. Utility companies across France and Spain specify these platforms for scheduled fiber health audits where technician interpretation remains standard practice.
- Digital Signal Processing:Algorithm-enhanced noise reduction and automated event detection compress measurement time from minutes to seconds. Research institutions in Switzerland and the United Kingdom drive procurement as coherent detection experiments demand sub-meter spatial resolution.
- Passive Technology:Receiver-only configurations relying on external light sources suit budget-constrained educational laboratories.
- Hybrid Technology:Combined active-passive architectures balance cost and capability for mid-tier telecom providers.
Mature deployment patterns favor Active Technology; capability upgrades favor Digital Signal Processing.
End User:
Customer type determines calibration service expectations, with government agencies imposing NIST-traceable audit trails that private operators often waive.
- Telecom Providers:Tier-one carriers in China and Germany consolidate procurement through multi-year framework agreements spanning OTDRs, power meters, and inspection scopes. Their specifications increasingly demand WiFi connectivity for cloud-based trace storage.
- Government Agencies:Federal procurement mandates in the United States restrict vendor eligibility to manufacturers with domestic NIST-traceable laboratories, compressing the qualified supplier base.
- Utility Companies:Electric grid operators in Italy and Japan deploy ruggedized units for smart grid fiber backbone verification.
- Research Institutions:Academic and government laboratories in the United Kingdom and Switzerland purchase high-specification coherent detection platforms for next-generation fiber characterization.
Procurement scale favors Telecom Providers; specification stringency favors Government Agencies.
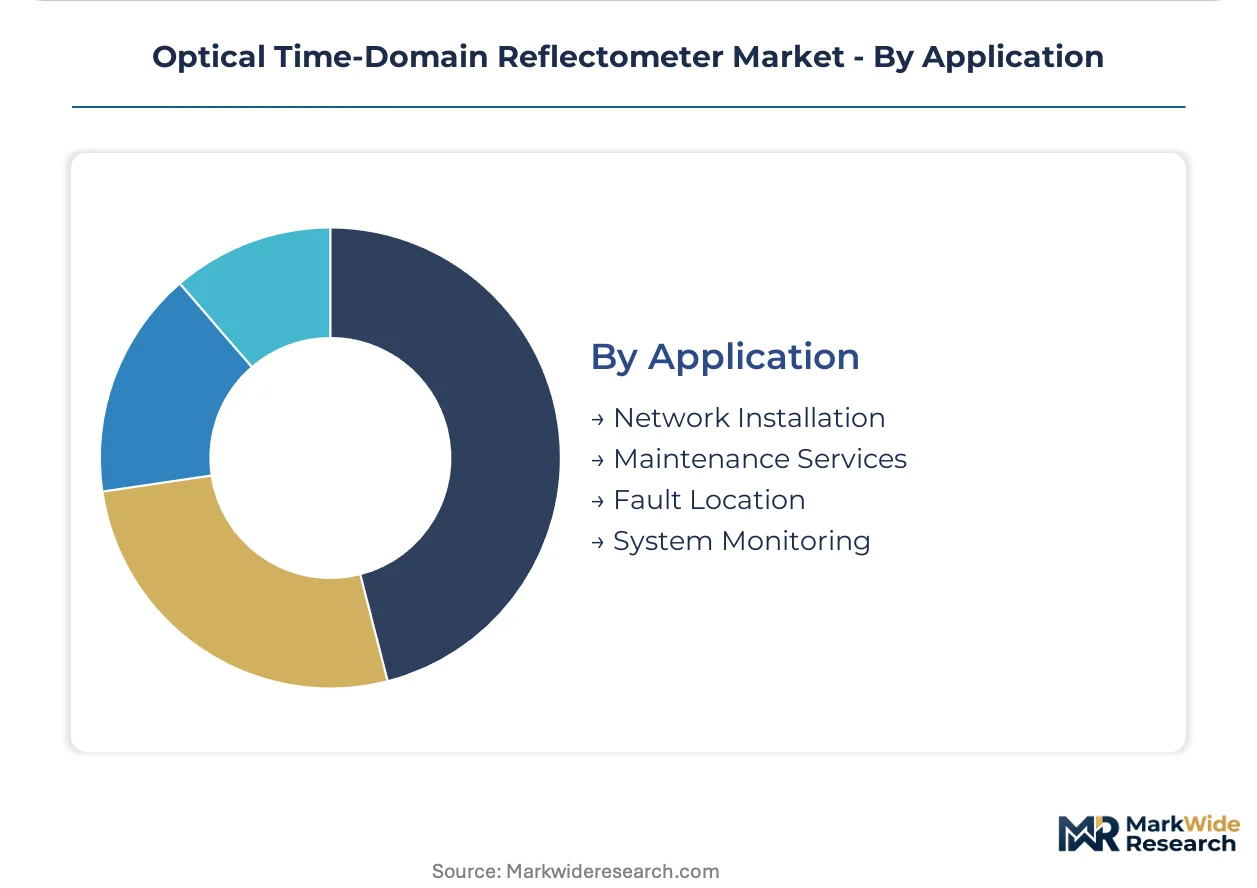
Application:
Application context dictates pulse width selection and averaging algorithms, with fault location demanding shortest pulses and system monitoring requiring unattended stability.
- Network Installation:Splice loss verification and acceptance testing consume the largest instrument volumes. Contractors across India's BharatNet Phase III expansion target 361,000 rural locations, each requiring handheld OTDR confirmation of drop fiber integrity.
- System Monitoring:Continuous unattended operation architectures embed OTDR hardware in network management platforms for predictive maintenance. Submarine cable operators across the Mediterranean basin specify these systems for 10,000+ kilometer link surveillance.
- Maintenance Services:Reactive break-fix deployments favor portable units with rapid boot times.
- Fault Location:High-resolution dead zone minimization suits dense urban fiber cuts in Japanese metropolitan networks.
Volume concentration favors Network Installation; technology migration favors System Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government broadband mandates across multiple jurisdictions are redirecting procurement volumes toward jurisdictions with active fiber infrastructure programs. Carrier consolidation and national fiber targets are concentrating instrument demand in specific metropolitan clusters.
China
MIIT spectrum allocations for 5G fronthaul are driving fiber-to-the-antenna installations at thousands of cell sites monthly. GB/T 15972 fiber measurement standards govern domestic procurement specifications for state-owned carriers. Shenzhen and Shanghai host dense concentrations of field service contractors deploying handheld units for access network verification.
United States
Federal procurement mandates restrict vendor eligibility to manufacturers with domestic NIST-traceable calibration laboratories. FCC Part 15 emissions rules shape product certification timelines for connected test equipment. The Dallas-Fort Worth metroplex anchors outside-plant contractor activity for regional fiber buildouts.
Germany
The European Commission's Gigabit Infrastructure Act compels accelerated passive optical network rollouts across member states. CE marking requirements under the EU Radio Equipment Directive impose hardware security module standards on connected instruments. Munich and Stuttgart concentrate utility tunnel inspection teams requiring portable NIST-traceable loss measurements.
India
BharatNet Phase III expansion targets 361,000 gram panchayats with optical fiber backbone deployment. TRAI broadband penetration targets create unserved demand for ruggedized handheld OTDR configurations. Hyderabad and Bengaluru field operations are scaling technician workforces for rural fiber verification.
Japan
METI efficiency standards favor fiber optic infrastructure replacement of legacy copper networks. JIS measurement protocols align with IEC 61746 calibration requirements for precision instrument acceptance. Tokyo metropolitan networks drive high-resolution dead zone minimization specifications for dense urban fiber cuts.
Optical Time-Domain Reflectometer Market Competitive Landscape
Listed leaders compete with private specialists across calibration service networks and channel density. The vendor base organizes around three tiers: integrated test equipment conglomerates with broad optical portfolios, regional specialists with captive calibration infrastructure, and component suppliers pivoting into finished instruments. Consolidation pressures are intensifying as telecom procurement departments award single-source framework agreements spanning multiple instrument categories. Two dominant competitive moves are emerging: backward integration into laser source manufacturing to secure compound semiconductor supply, and geographic expansion of NIST-traceable calibration laboratories to reduce certification bottlenecks.
Among North American-listed test equipment providers, EXFO Inc. and Viavi Solutions Inc. occupy positions within the integrated conglomerate tier, while Yokogawa Test & Measurement Corporation anchors the Japanese specialist archetype with established channel partnerships across Asia-Pacific telecom markets. These three exemplify how calibration capability investments and dense service networks are compressing margins for entrants lacking comparable infrastructure.
| Leading Market Players |
|---|
| EXFO Inc. |
| Viavi Solutions Inc. |
| Anritsu |
| Yokogawa Test & Measurement Corporation |
| Fluke Networks |
| TEKTRONIX, INC. |
| AFL |
| Keysight Technologies |
| VeEX Inc. |
| Others |
Value Network & Pricing Analysis
Long-term framework agreements between tier-one carriers and established test equipment suppliers lock in multi-year calibration service commitments while freezing unit pricing visibility across procurement cycles. These contractual structures concentrate purchasing power among German and Chinese state-owned carriers, compressing margin flexibility for vendors lacking captive NIST-traceable laboratory networks.
Pricing Analysis
Certification level (IEC 61746/NIST-traceable vs. non-certified) creates the primary spread between portable OTDR tiers, with government procurement mandates in the United States restricting eligible vendors to premium-grade instruments. Three-tier pricing structure across premium, standard, and economy levels segments the market, where premium tiers bundle cloud connectivity and predictive analytics subscriptions. Pricing pressure stems from Chinese state-owned carriers consolidating procurement through single-source framework agreements. Field service contractors in India's BharatNet expansion exhibit the highest price sensitivity, while federal agencies in the United States demonstrate minimal elasticity due to compliance mandates.
Supply Chain Analysis
Taiwan and South Korea anchor indium phosphide laser source fabrication, with compound semiconductor foundry capacity constraints directly feeding into OTDR production bottlenecks. Japan and Germany concentrate precision optical component manufacturing, while China dominates handheld enclosure and battery assembly. Raw material dependencies span indium phosphide substrates, single-mode fiber pigtails, and lithium-ion power cells. Single-source vulnerability runs through Taiwan's foundry concentration for high-performance laser diodes. Distribution runs through authorized channel partners serving carrier procurement departments, with direct sales reserved for government and research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment. IEC 61746 calibration mandates and NIST-traceable laboratory requirements create switching costs that protect incumbent positions while raising barriers for unqualified entrants.
For Market Incumbents: Compound calibration service network density by expanding NIST-traceable laboratory footprints into India and Southeast Asia, reducing certification bottlenecks that delay Asian manufacturer market entry. Deepen backward integration into indium phosphide laser source manufacturing to insulate margins from Taiwan foundry volatility. Prioritize cloud-connected instrument architectures that embed subscription revenue streams, defending against commoditization in handheld segments. For New Entrants and Emerging Players: Lead with AI-assisted fault classification software as a standalone entry point, bypassing capital-intensive hardware manufacturing while capturing value from technician skill scarcity in North American and Western European markets. Target rural India broadband contractors with ruggedized handheld units priced below premium-tier incumbents, leveraging BharatNet Phase III deployment timelines. Pursue white-label manufacturing partnerships with established calibration laboratories to satisfy government procurement eligibility requirements. For Investors and Strategic Acquirers: Regional specialists with captive calibration infrastructure and established channel partnerships in Asia-Pacific telecom markets represent the most defensible acquisition targets. Long-term viability hinges on regulatory compliance capabilities rather than hardware innovation cycles, favoring asset-light software-overlay strategies over capital-intensive manufacturing consolidation. Watch for MIIT spectrum allocation announcements in China as volume inflection indicators, as 5G fronthaul buildouts directly drive handheld OTDR procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | NIST-traceable facilities in India reduce certification delays for Asian manufacturers seeking government contracts. |
| Backward Integration into Laser Sources | In-house indium phosphide production insulates margins from Taiwan foundry capacity constraints. |
| Cloud-Connected Platform Launch | WiFi-enabled instruments streaming to centralized analytics open recurring subscription revenue streams. |
| AI-Assisted Fault Classification | Machine learning algorithms trained on OTDR trace databases automate technician interpretation for skill-scarce markets. |
| Framework Agreement Consolidation | Single-source contracts spanning OTDRs, power meters, and inspection scopes concentrate procurement power among tier-one carriers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, carrier procurement databases, and compound semiconductor trade data. Interviews with optical test equipment product managers, field service contractor operations leads, telecom procurement officers, and calibration laboratory technical directors informed demand-side assumptions. Secondary validation drew from IEC standards documentation, FCC equipment authorization records, MIIT spectrum allocation announcements, and SEC filings of listed test equipment providers. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts.
Segmentation dimensions modeled include product configuration (portable, handheld, fixed, fiber channel), detection technology (active, digital signal processing, passive, hybrid), end-user category (telecom providers, government agencies, utility companies, research institutions), and application context (network installation, system monitoring, maintenance services, fault location). CAGRs were derived from infrastructure deployment timelines and replacement cycle analysis. Forecast inputs incorporated 5G fronthaul buildout schedules, FTTH mandate compliance deadlines, and submarine cable installation pipelines across the analysis window.
The analysis sits within stated boundaries; outcomes outside sustained fiber infrastructure investment levels or stable compound semiconductor supply conditions would require recalibration. Forecasts reflect assumptions regarding calibration standard continuity and carrier procurement consolidation trajectories. Recalibration cycles align with material shifts in spectrum allocation policies, trade restrictions on laser source materials, and cybersecurity annex updates to the EU Radio Equipment Directive.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Transmitter Market
Optical Components
North America Optical Film Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Waveguide Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Prism Coupler Market
Optical Components
Optical Component Tester Market
Optical Components
100G Optical Transceivers Market
Optical Components
Europe Scintillator Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
VCSEL for Data Communication Market